
 Vacuum Shrink Bags Market | 2026-2036
Vacuum Shrink Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Shrink Bags Market Analytics
Foodservice redistributors is unwinding legacy reliance on butcher-counter operators as protein centralization accelerates. Cryovac leverages captive resin compounding to dominate high-barrier shrink applications for case-ready meats. Sealed Air Corporation anchors North American throughput with automated bagging systems tied to retail private-label programs. Amcor competes through vertical control of nylon supply chains for oxygen-scavenging multi-layer structures.
Vacuum shrink bags are thermoformable or pre-made pouches engineered from coextruded films—typically combining polyethylene sealant layers with nylon or EVOH barrier substrates—to evacuate headspace and conform tightly to irregular product geometry under heat-shrinking conditions. The primary commercial purpose centers on extending chilled protein shelf life while enabling retail-ready presentation with minimal purge loss. Multi-layer bags command the thickest margin pools where oxygen transmission rates below 1 cc/m²/day justify premium positioning for aged beef and processed charcuterie. Polyethylene dominates tonnage across single-layer commodity applications, though nylon-reinforced constructions are capturing fastest growth in value terms as processors specify sub-five-mil structures for bone-in primal cuts.
REACH compliance through ECHA governs monomer migration thresholds for European food-contact films, while FDA 21 CFR 177.1390 regulates laminate adhesives and barrier polymers in U.S. interstate commerce. USDA-FSIS labeling and safe-handling overlays further constrain bag surface print chemistry for case-ready meat programs. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions, which threaten to mandate minimum recycled content in shrink films without proven mechanical compatibility.
Market Dynamics
Protein centralization across slaughter-to-retail corridors is compressing bag specification cycles as processors consolidate procurement around automated vacuum-shrink lines. EFSA's tightening migration limits for food-contact plastics are forcing rapid reformulation of multi-layer barrier films.
Growth Catalysts
- REACH compliance deadlines:ECHA's phased monomer migration thresholds are accelerating replacement of legacy single-layer polyethylene with nylon-reinforced coextrusions in European meatpacking operations.
- Case-ready meat programs:USDA-FSIS labeling requirements for safe-handling overlays are standardizing high-barrier bag formats across North American retail private-label supply chains.
- Germany's meatpacking corridor:Centralized slaughter-to-retail operations in Lower Saxony and Bavaria are deploying automated vacuum-shrink lines that favor pre-made pouch formats over thermoformable films.
Market Restraints
- Caprolactam supply concentration:Nylon 6 resin production clusters in Northeast Asia create input cost volatility for EVOH-nylon multi-layer structures.
- Recycled content incompatibility:Pending EU Packaging and Packaging Waste Regulation revisions threaten mechanical performance of shrink films without proven post-consumer recycled stream compatibility.
- Adhesive laminate limitations:FDA 21 CFR 177.1390 constraints on solvent-based polyurethane adhesives restrict oxygen-scavenging layer bonding in ultra-high-barrier applications.
Strategic Opportunities
- India's cold chain expansion:FSSAI-mandated food safety modernization is creating first-mover advantage for vacuum-shrink bag suppliers targeting poultry and seafood export processors in Andhra Pradesh and Gujarat.
- Dual carbon goals in China:NMPA-aligned green manufacturing incentives are opening procurement channels for bio-based sealant layers in domestic protein packaging.
- Direct-to-retail e-commerce:Last-mile chilled delivery networks in South Korea are specifying vacuum-shrink formats for meal-kit portion control, bypassing traditional foodservice redistribution.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Specialized die design and layer ratio optimization skills are concentrated among aging workforces in German and Italian film equipment OEMs.
- Migration testing timeline compression:EFSA's accelerated scientific opinion cycles are forcing simultaneous reformulation and regulatory submission without full shelf-life validation.
- Legacy thermoformer integration:Retrofitting automated bagging systems into existing slaughter-floor layouts requires custom conveyor engineering that extends commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Shrink Bags Market |
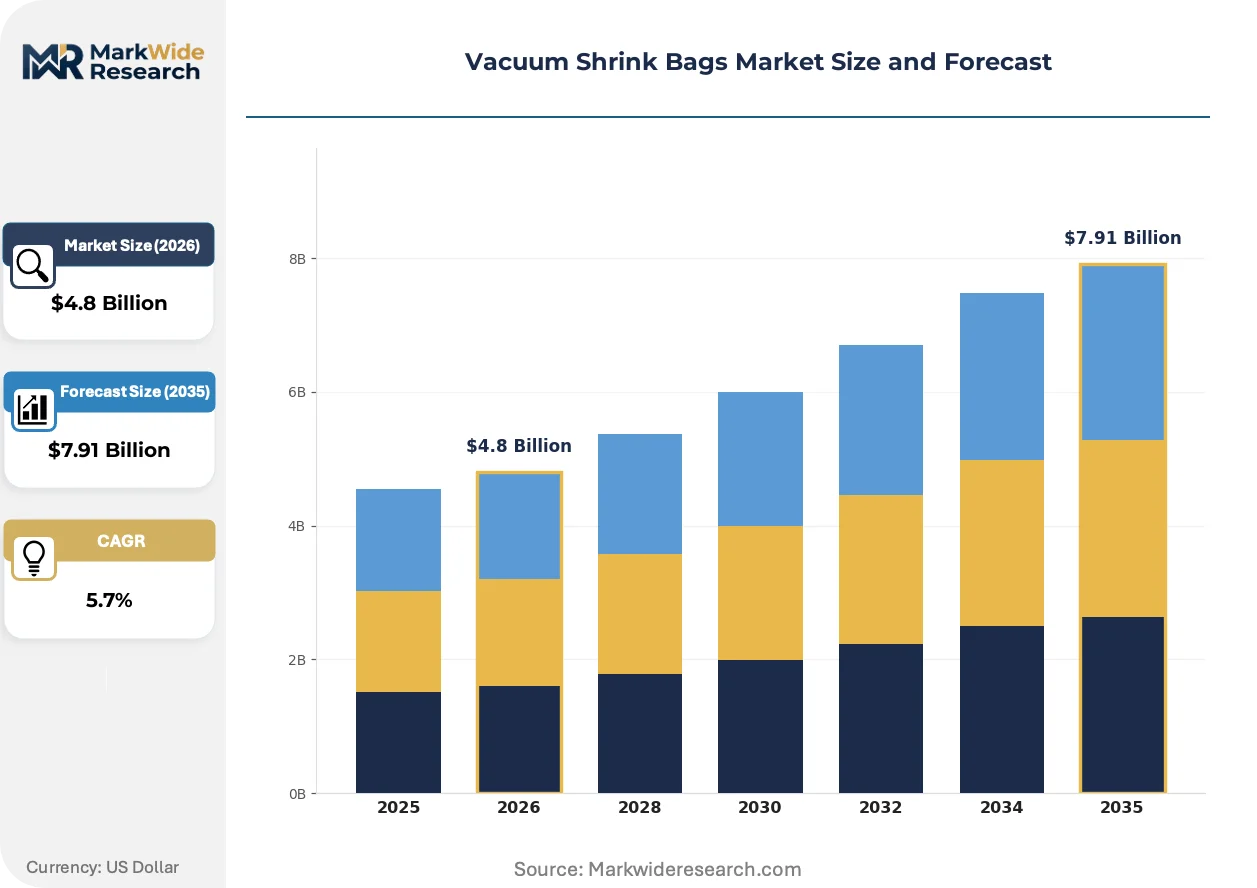
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centerfold Bags, Single Layer Bags, Multi-Layer Bags, Gusseted Bags Material: Polyethylene, Polypropylene, Nylon, Polyester End User: Food Industry, Textile Industry, Electronics, Pharmaceuticals Thickness: Lightweight, Medium, Heavy Duty, Extra Heavy Duty |
| Companies Covered | Amcor, Sealed Air Corporation, Cryovac, Winpak Ltd., Bemis Company Inc., Koch Supplies, Flexopack SA, Weston Brands, LEM Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Shrink Bags Market Evolving Landscape
Barrier film architecture is bifurcating between commodity polyethylene tonnage and precision-engineered multi-layer structures as oxygen transmission specifications tighten for aged protein segments. Equipment automation and regulatory chemistry are converging to reshape competitive positioning.
Active oxygen-scavenging layers integrated directly into nylon-EVOH coextrusions are displacing separate sachet-based preservation systems in premium beef aging programs. North American case-ready meat processors are specifying sub-five-mil structures with scavenger loadings above 500 ppm. This convergence is compressing purge loss metrics while extending case-ready shelf life claims from 21 to 35 days.
EFSA's 2023 updated scientific opinion on cyclic oligomer migration is forcing reformulation of nylon 6 sealant layers across European protein packaging. The industrial consequence is accelerated qualification of bio-based polyamide alternatives from castor oil feedstocks. German meatpackers in the Ruhr corridor are piloting these structures for bratwurst and cured sausage applications ahead of anticipated 2025 enforcement windows.
Consolidated procurement by protein redistributors is compressing supplier qualification cycles from 18 months to 90 days. Traditional butcher-counter operators are losing share to centralized case-ready programs that specify bag formats at the slaughterhouse level. This concentration is most visible in Brazil's southern beef belt, where JBS and Marfrig are standardizing vacuum-shrink specifications across their export-oriented packing plants.
Vacuum Shrink Bags Market Segmentation
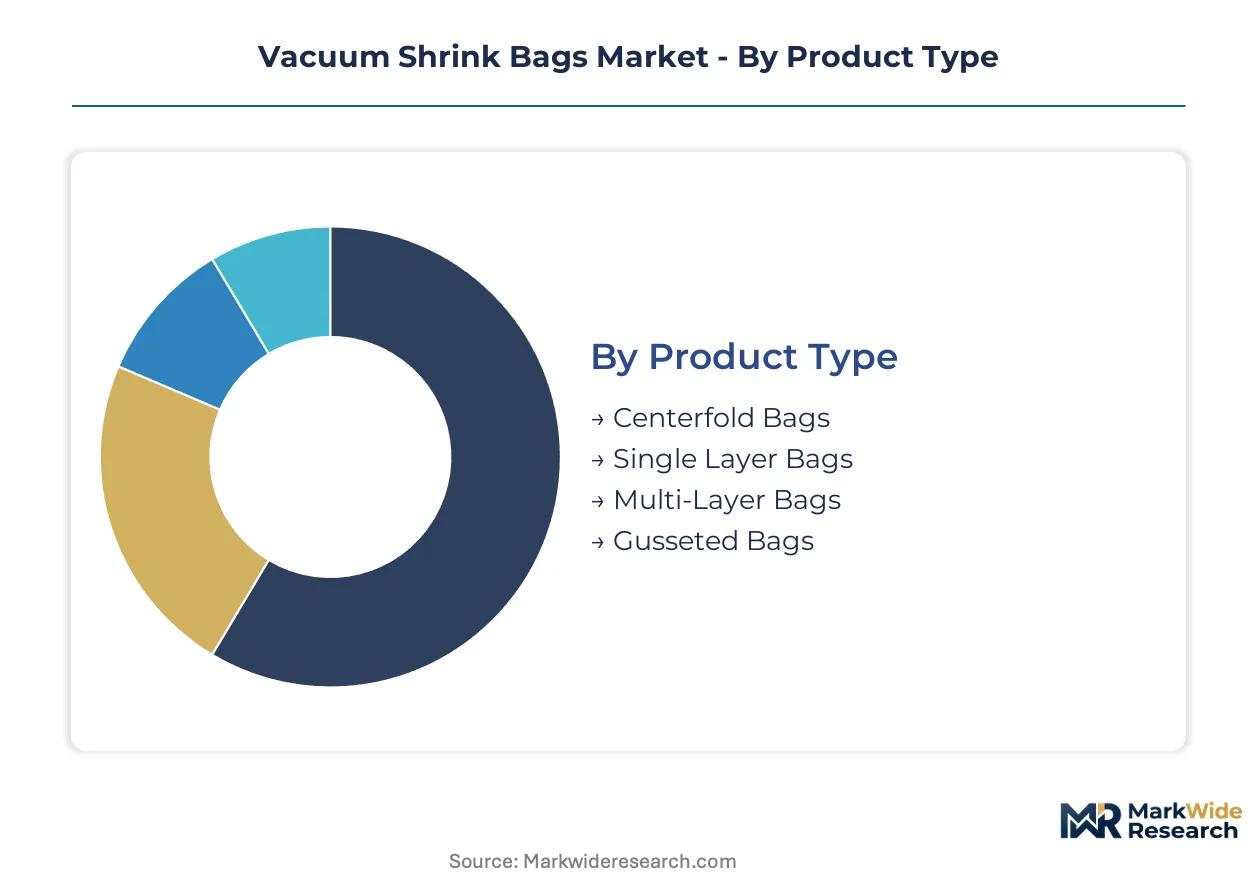
Segmentation in vacuum shrink bags reveals how margin pools concentrate in barrier-engineered formats versus commodity tonnage. Material architecture and end-use specifications determine pricing power across protein packaging, electronics, and pharmaceutical applications.
Product Type:
Margin pools concentrate in precision-engineered multi-layer constructions where oxygen transmission specifications command premium positioning, while commodity single-layer formats compete on throughput scale.
- Multi-Layer Bags:Coextruded nylon-EVOH-polyethylene laminates achieve oxygen transmission rates below 1 cc/m²/day for aged beef and charcuterie. German meatpackers in Lower Saxony specify these for automated vacuum-shrink lines handling case-ready retail programs.
- Single Layer Bags:Homogeneous polyethylene constructions dominate high-volume commodity applications where barrier performance is secondary to cost efficiency. These formats face margin compression as processors consolidate procurement around higher-performance alternatives.
- Centerfold Bags:Continuous rollstock designed for form-fill-seal equipment in centralized protein operations.
- Gusseted Bags:Side-folded designs accommodating irregular primal cuts and bone-in portions in butcher-counter and foodservice channels.
The dominant share belongs to Single Layer Bags, while Multi-Layer Bags is closing the gap fastest.
Material:
Input cost volatility and regulatory migration limits are reshaping material selection priorities across European and North American supply chains.
- Nylon:Polyamide 6 and 66 grades provide puncture resistance and structural integrity for bone-in primal cuts. EFSA's tightening cyclic oligomer thresholds are accelerating reformulation toward bio-based polyamide alternatives from castor oil feedstocks in German pilot programs.
- Polyethylene:Linear low-density and metallocene grades constitute the sealant layer foundation across virtually all coextruded structures. This material anchors tonnage but yields thinnest margins in undifferentiated commodity applications.
- Polypropylene:Oriented and cast films serve niche high-temperature applications where thermal resistance exceeds polyethylene capabilities.
- Polyester:PET substrates appear in specialized pharmaceutical and electronics packaging requiring dimensional stability and clarity.
Polyethylene retains volume leadership, though Nylon is expanding most quickly in value terms.
End User:
Application-specific barrier requirements and regulatory overlays fragment demand patterns across protein, healthcare, and industrial segments.
- Food Industry:Protein processors drive specification cycles through centralized slaughter-to-retail corridors. USDA-FSIS labeling requirements and EFSA migration limits constrain surface chemistry and adhesive selection for case-ready meat programs in North America and Europe.
- Electronics:Static-dissipative and moisture-barrier formats protect semiconductor components and precision assemblies during global distribution.
- Textile Industry:Compression packaging for bulk garment and fabric shipments emphasizes clarity and puncture resistance over gas barrier performance.
- Pharmaceuticals:FDA 21 CFR compliance and USP Class VI biocompatibility requirements govern material selection for medical device and drug product containment.
Food Industry commands the dominant position, with Electronics gaining share fastest on precision manufacturing supply chain expansion.
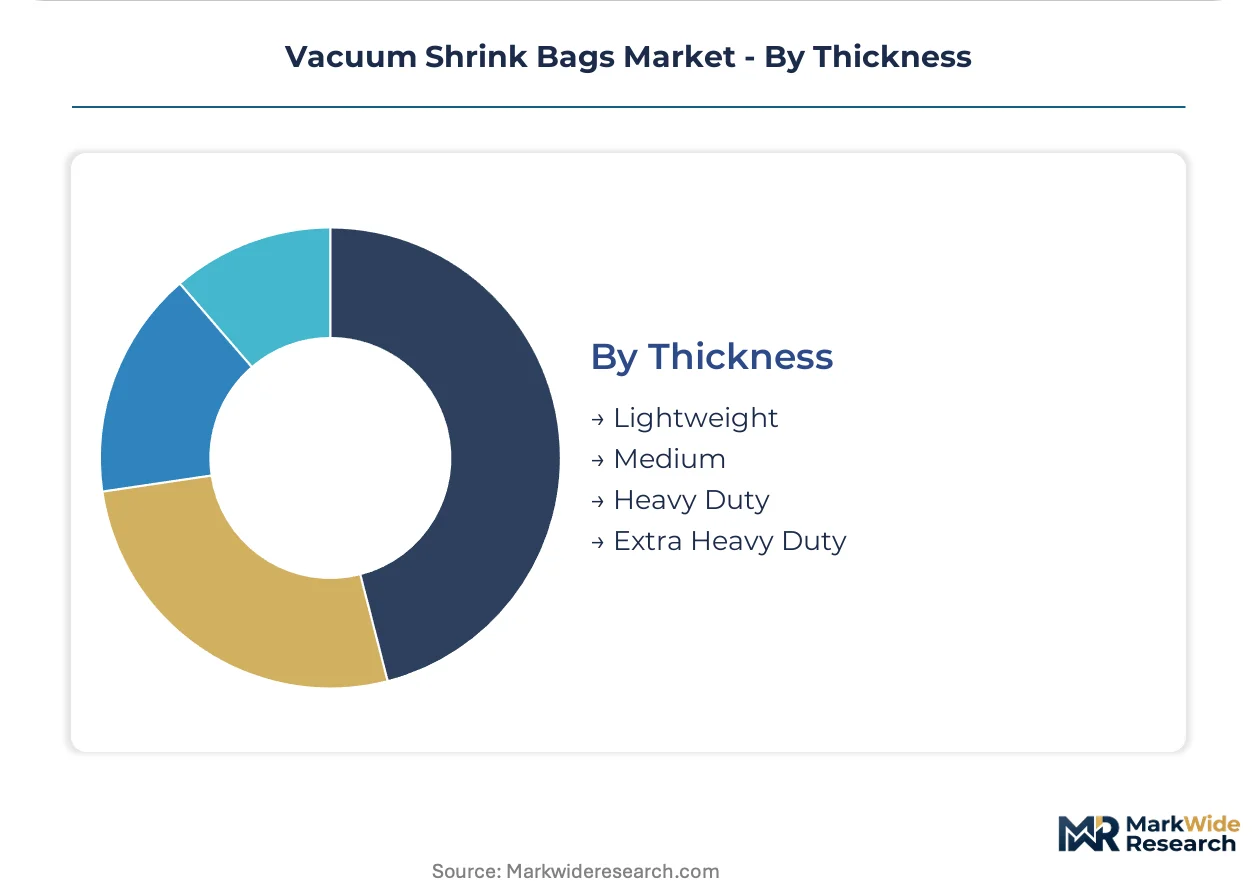
Thickness:
Structural specification directly correlates with product protection requirements and equipment compatibility across manual and automated packaging lines.
- Heavy Duty:Sub-five-mil to seven-mil constructions balance puncture resistance against thermoforming efficiency for bone-in primal cuts. North American case-ready processors specify these with integrated oxygen-scavenging layers to extend shelf life claims.
- Medium:Three-mil to five-mil formats serve standard case-ready and retail-ready applications where handling severity does not demand maximum gauge.
- Lightweight:Sub-three-mil structures target cost-sensitive commodity applications with minimal barrier requirements.
- Extra Heavy Duty:Above-seven-mil specifications address extreme puncture threats from sharp bone structures and abrasive surface textures in export-oriented beef operations.
Medium thickness holds the largest installed base, while Heavy Duty is climbing the fastest on premium protein segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European vacuum-shrink bag distribution, while the Rhine-Alpine corridor feeds automated packaging lines across the continent's protein processing belt.
Germany
Lower Saxony's slaughter-to-retail corridor drives specification cycles for high-barrier multi-layer formats. EFSA's tightening cyclic oligomer migration limits are accelerating reformulation of nylon 6 sealant layers ahead of 2025 enforcement. Ruhr corridor meatpackers pilot bio-based polyamide alternatives from castor oil feedstocks for bratwurst applications.
United States
USDA-FSIS labeling requirements for safe-handling overlays standardize bag formats across retail private-label supply chains. FDA 21 CFR 177.1390 constraints on solvent-based polyurethane adhesives restrict oxygen-scavenging layer bonding. Midwest protein processors deploy automated vacuum-shrink lines from Nebraska to Iowa.
China
NMPA-aligned green manufacturing incentives open procurement channels for bio-based sealant layers in domestic protein packaging. Dual carbon goals reshape material selection priorities across Yangtze River Delta processing clusters. Shandong Peninsula exporters specify sub-five-mil structures for chilled pork shipments.
Brazil
JBS and Marfrig standardize vacuum-shrink specifications across export-oriented packing plants in the southern beef belt. ANVISA's food-contact polymer regulations constrain adhesive chemistry for case-ready programs. São Paulo state processors consolidate procurement around automated lines serving Mercosur distribution.
India
FSSAI-mandated food safety modernization creates first-mover advantage for suppliers targeting poultry and seafood export processors. Andhra Pradesh and Gujarat cold chain expansion drives specification of vacuum-shrink formats for chilled protein distribution. Mumbai-JNPT port connectivity enables direct export to Middle Eastern retail channels.
Vacuum Shrink Bags Market Competitive Landscape
Listed leaders compete with private specialists across resin compounding and automated systems integration. The market structure concentrates around three to five vertically integrated film converters controlling high-barrier multi-layer supply. Strategic archetypes include captive resin compounders, automated equipment integrators, and regional pouch fabricators. Dominant competitive moves span backward integration into nylon supply chains and strategic partnerships with protein redistributors.
Within the premium-tier vector, Amcor anchors positioning through upstream control of nylon supply chains for oxygen-scavenging structures. Sealed Air Corporation exemplifies the equipment-integrated archetype with automated bagging systems tied to retail programs. Cryovac occupies a position representing captive resin compounding specialization for high-barrier shrink applications. These three entities collectively represent the convergence of material science and protein packaging automation.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air Corporation |
| Cryovac |
| Winpak Ltd. |
| Bemis Company Inc. |
| Koch Supplies |
| Flexopack SA |
| Weston Brands |
| LEM Products |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German meatpackers and nylon resin suppliers lock in both EVOH barrier layer access and eighteen-month price visibility against caprolactam volatility. These arrangements concentrate procurement power among processors running automated vacuum-shrink lines in Lower Saxony and Bavaria.
Pricing Analysis
Volume-discount tiering structures separate multi-layer coextrusion orders above five million units from smaller batch runs. Pricing stratifies across premium oxygen-scavenging grades, standard nylon-reinforced constructions, and economy single-layer polyethylene formats. Cost compression in commodity tonnage is intensifying because Brazilian processors are consolidating procurement around JBS and Marfrig specifications. Foodservice redistributors exhibit highest price sensitivity, while aged beef programs for retail private-label chains tolerate premium positioning.
Supply Chain Analysis
BASF's Ludwigshafen caprolactam complex underwrites European nylon 6 supply for EVOH multi-layer films. Northeast Asian resin production clusters and Middle Eastern ethylene feedstock sources feed global coextrusion lines. Single-source vulnerability concentrates in German equipment OEMs for specialized die design. Distribution runs through protein redistributor networks that specify bag formats at slaughterhouse level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated vacuum-shrink line interoperability is reshaping competitive positioning as case-ready meat programs standardize bag specifications across slaughter-to-retail corridors. Equipment-integrated suppliers capture platform economics from protein centralization.
For Market Incumbents: Shield high-barrier multi-layer margins through captive resin compounding and backward integration into nylon supply chains. Cryovac's compounding specialization and Sealed Air's automated systems integration represent defensive templates against emerging Asian film converters. Prioritize REACH-compliant reformulation ahead of EFSA's 2025 enforcement windows. For New Entrants and Emerging Players: Anchor in India's FSSAI-mandated cold chain expansion, where Andhra Pradesh poultry processors lack qualified vacuum-shrink bag suppliers. Target seafood export channels through Mumbai-JNPT port connectivity to Middle Eastern retail. Pursue equipment-integrated partnerships rather than commodity film supply. For Investors and Strategic Acquirers: Regional pouch fabricators with bio-based polyamide pilot programs offer acquisition exposure to EFSA-driven reformulation cycles. Long-term viability hinges on migration testing capabilities and layer ratio optimization expertise. Watch for ECHA enforcement acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nylon Supply | Amcor's upstream control over polyamide resin secures margin capture in oxygen-scavenging structures. |
| Bio-Based Sealant Layer Development | German Ruhr corridor pilots of castor oil-derived polyamides anticipate EFSA cyclic oligomer limits. |
| Automated Bagging System Deployment | Midwest protein processors from Nebraska to Iowa standardize case-ready formats through equipment integration. |
| REACH-Compliant Reformulation | EFSA's tightened migration thresholds force replacement of legacy single-layer polyethylene in European meatpacking. |
| India Cold Chain Partnership | FSSAI modernization creates first-mover positioning for suppliers targeting Gujarat seafood export processors. |
Research Methodology
The analysis maps coextruded film architectures, automated packaging equipment tiers, and protein processor procurement patterns, each validated through film equipment OEMs, resin compounders, and meatpacking procurement directors. Primary interviews with layer ratio optimization technicians and secondary validation through EFSA scientific opinions, ECHA migration threshold documentation, and USDA-FSIS labeling guidelines support bottom-up and top-down triangulation.
Consistency checks against customs data for caprolactam trade flows and protein packaging machinery import records validate volume and value outputs across the projection horizon. Segmentation dimensions include material architecture, thickness specification, and end-use barrier requirements. CAGRs derive from protein centralization trajectories and regulatory compliance cost modeling.
Underlying assumptions cover EFSA enforcement timing and caprolactam price stability, with deviation risk concentrated in EU Packaging and Packaging Waste Regulation recycled content mandates. Practitioners should keep alternative scenarios live as bio-based polyamide qualification timelines and German equipment OEM consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag in Drum Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Piping Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Bag Dump Stations Market