
 Non-Laminated Heat-Sealed Bags Market | 2026-2036
Non-Laminated Heat-Sealed Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Laminated Heat-Sealed Bags Market Analytics
Food service distributors and quick-service restaurant chains is collapsing toward e-commerce fulfillment centers and direct-to-consumer grocery platforms as primary demand anchors. Mondi leverages its European manufacturing footprint to sustain supply continuity for heat-sealed pouch lines. Sealed Air Corporation dominates the North American channel with proprietary barrier technologies for protein packaging. Amcor Plc anchors global capacity through integrated resin-to-film operations across multiple continents.
Non-laminated heat-sealed bags are single-ply polymer containers sealed through controlled thermal fusion of polyethylene or polypropylene films, typically ranging from 1.5 to 6 mil thickness, designed for cost-sensitive applications where multi-layer barrier performance is unnecessary. Gusseted bags and stand-up pouches within the product type category capture expanding share in dry goods and frozen food segments where cube efficiency and shelf presence matter. Recycled polyethylene and biodegradable film formulations are gaining fastest within material segments, though virgin polyethylene still occupies the largest volume position due to cost parity and established converter infrastructure.
FDA food-contact substance regulations and California's SB 54 recycling mandates shape material selection and compliance costs for domestic suppliers, while EU REACH restrictions on certain polymer additives influence export-oriented producers. ISO 22000 food safety management standards and BRC packaging certification requirements create tiered market access barriers that favor mid-to-large converters with dedicated quality systems. Stakeholders must monitor evolving extended producer responsibility frameworks and resin price volatility to calibrate capacity commitments and material qualification pipelines.
Market Dynamics
Quick-service restaurant chains and food service distributors are consolidating procurement around direct-to-consumer fulfillment channels, compressing traditional distributor intermediaries and rewiring volume flows toward e-commerce platforms and regional cold-chain hubs.
Growth Catalysts
- California SB 54 mandates:Extended producer responsibility frameworks are accelerating converter investment in recycled polyethylene qualification pipelines to maintain access to the state's retail and food processing corridors.
- Quick-service restaurant expansion:Portion-controlled packaging specifications for frozen protein and dry goods are pulling heat-sealed pouch volumes into centralized commissary operations.
- Biodegradable film formulations:PLA and PHA blends are capturing shelf presence in organic and private-label dry goods segments where brand differentiation commands placement premiums.
Market Restraints
- Resin price volatility:Virgin polyethylene feedstock costs tied to natural gas liquids pricing create margin compression for converters without backward integration into resin production.
- Gulf Coast petrochemical concentration:Hurricane exposure and freeze-event disruption risk at Texas-Louisiana ethylene crackers creates supply continuity exposure for domestic film extrusion.
- Multi-layer barrier substitution:Vacuum skin packs and high-barrier laminates are displacing non-laminated formats in premium protein segments requiring extended shelf life.
Strategic Opportunities
- Texas distribution corridor expansion:Dallas-Fort Worth and Houston cold-chain infrastructure investments are creating regional hub capacity for direct retailer and food service fulfillment.
- FDA food-contact substance notifications:Streamlined clearance pathways for post-consumer recycled content are enabling faster material qualification cycles versus historical timelines.
- Direct-to-consumer grocery platforms:Fulfillment center specifications for cube-optimized shipping configurations are favoring gusseted and stand-up pouch formats over rigid alternatives.
Industry Challenges
- BRC packaging certification timelines:Quality system documentation and audit scheduling create 12-18 month onboarding windows for mid-tier converters seeking tier-one food manufacturer approval.
- ISO 22000 implementation costs:Hazard analysis and prerequisite program documentation requirements demand dedicated quality personnel that strain smaller converter operating models.
- Legacy extrusion equipment retrofitting:Processing biodegradable films on lines calibrated for polyethylene requires screw and die modifications that extend changeover downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Laminated Heat-Sealed Bags Market |
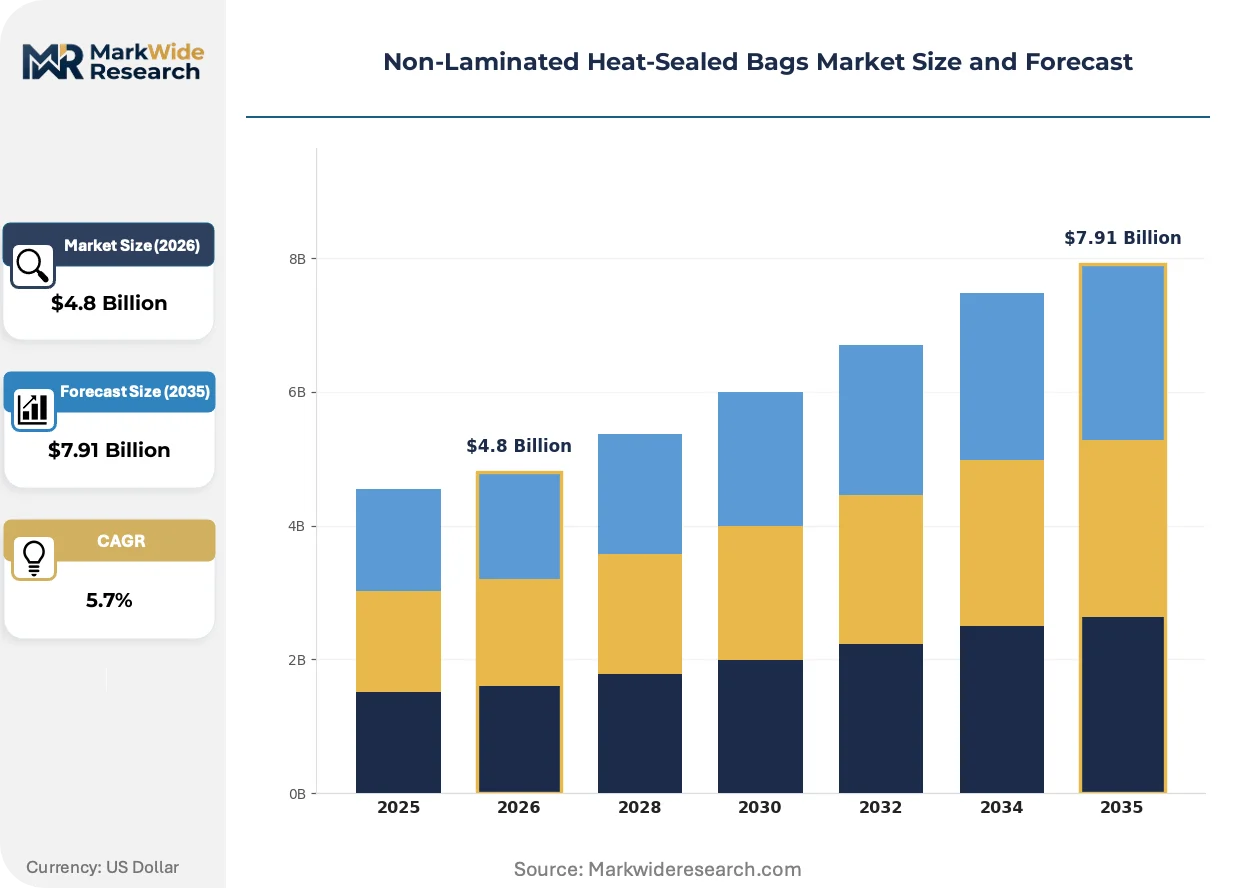
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Pouches, Custom Shapes Material: Polyethylene, Polypropylene, Recycled Plastic, Biodegradable Film End User: Food Industry, Pharmaceutical, Retail, Industrial Packaging Closure Type: Zip Lock, Heat Seal, Self-Adhesive, Twist Tie |
| Companies Covered | Amcor Plc, Berry Global, Mondi, Huhtamaki, Sonoco Products Company, International Paper, Constantia Flexibles, Sealed Air Corporation, Uflex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Laminated Heat-Sealed Bags Market Evolving Landscape
Material science advances and regulatory compliance architectures are fragmenting converter strategies between cost-optimized virgin polyethylene scale and specialty sustainable film qualification.
Recycled polyethylene resin streams are bifurcating converter investment priorities. Post-industrial scrap reprocessing dominates near-term supply security for major film extruders. Post-consumer mechanical recycling is capturing expanding share in retail-branded applications where California SB 54 compliance creates procurement preference. This technology is bifurcating the supplier base between commodity-scale virgin producers and specialized recycled-content qualifiers.
FDA food-contact substance regulations are tightening additive disclosure requirements for recycled content streams. Domestic converters face expanded testing documentation burdens for each resin batch qualification. Protein packaging and frozen food segments are responding with dedicated quality personnel and third-party laboratory partnerships to accelerate notification timelines.
Food service procurement patterns are compressing supplier rosters around integrated fulfillment capabilities. Distributor consolidation is displacing fragmented local converter relationships in favor of national accounts with multi-regional extrusion and converting footprint. Quick-service restaurant chains in Texas and California distribution corridors are most visibly consolidating volume around vendors with captive resin supply and direct retailer drop-ship capacity.
Non-Laminated Heat-Sealed Bags Market Segmentation
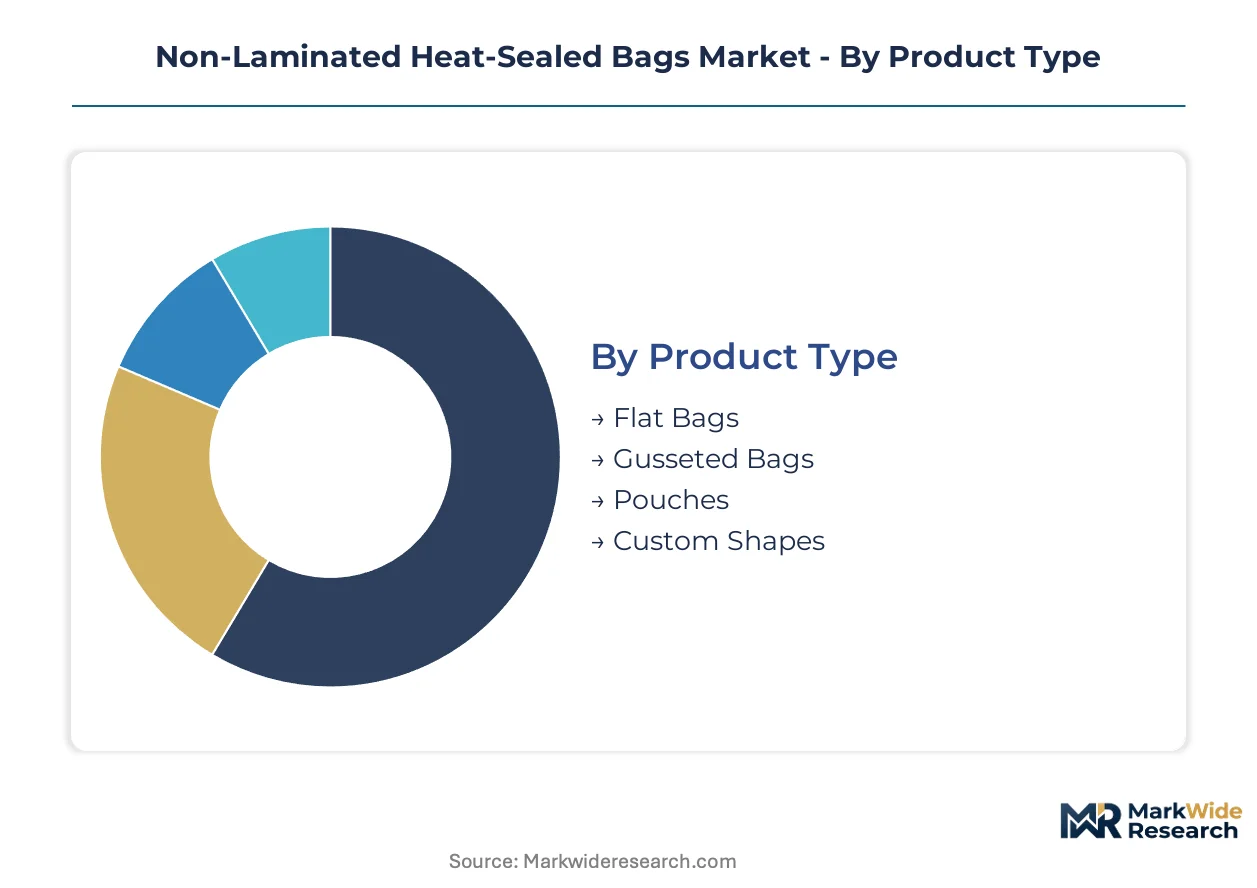
Segmentation in non-laminated heat-sealed bags reveals how FDA food-contact regulations and state-level mandates fragment converter strategies across material grades and closure specifications. Each dimension carries distinct compliance burdens and margin profiles that reshape procurement patterns among food service operators and quick-service restaurant chains.
Product Type:
Regulatory differentiation in FDA food-contact substance notifications creates tiered qualification timelines across bag geometries, with stand-up configurations requiring extended stability testing versus flat formats.
- Flat Bags:Single-ply polyethylene or polypropylene films in 1.5-4 mil thickness dominate portion-controlled protein packaging for quick-service restaurant commissaries. Texas and California distribution corridors concentrate procurement around converters with captive resin supply and direct drop-ship capacity to cold-chain hubs.
- Gusseted Bags:Side-folded constructions expand cube efficiency for dry goods and frozen food segments where shelf presence and shipping density matter. E-commerce fulfillment centers favor these configurations for optimized parcel utilization, pulling volume toward regional extruders with integrated converting lines.
- Pouches:Stand-up formats with bottom gussets capture placement in organic and private-label dry goods where brand differentiation commands premium positioning.
- Custom Shapes:Die-cut configurations serve specialized industrial and pharmaceutical applications requiring dimensional precision beyond standard extrusion widths.
Flat bags handle the majority of throughput; gusseted bags are the fastest mover on share.
Material:
Cost tier stratification separates virgin polyethylene scale players from specialty recyclers facing California SB 54 compliance premiums and biodegradable film qualifiers absorbing technology risk.
- Polyethylene:Virgin LDPE and LLDPE grades maintain volume leadership through cost parity and established converter infrastructure across Gulf Coast petrochemical corridors. FDA food-contact regulations permit streamlined additive packages that accelerate batch qualification versus recycled streams.
- Polypropylene:Higher clarity and temperature resistance position cast PP films for hot-fill and retort applications where polyethylene softening limits performance. Texas-based food processors specify these grades for centralized commissary operations requiring thermal stability.
- Recycled Plastic:Post-industrial scrap reprocessing dominates near-term supply security for major extruders, while post-consumer mechanical recycling captures expanding share in retail-branded applications.
- Biodegradable Film:PLA and PHA blends serve organic segments where placement premiums offset material cost disadvantages and processing equipment retrofit requirements.
Polyethylene commands the dominant volume position; biodegradable film is climbing the fastest on regulatory pressure.
End User:
Application-specific performance requirements fragment specifications across food safety certification tiers, with BRC and ISO 22000 compliance creating onboarding windows that favor integrated converters over fragmented local suppliers.
- Food Industry:Quick-service restaurant chains and food service distributors consolidate procurement around direct-to-consumer fulfillment channels, compressing traditional intermediaries. Frozen protein and dry goods specifications pull heat-sealed pouch volumes into centralized commissary operations with dedicated quality personnel.
- Pharmaceutical:USP Class VI and extractables testing requirements impose documentation burdens that exclude smaller converters lacking laboratory partnerships or dedicated regulatory staff.
- Retail:Private-label and branded dry goods segments drive gusseted and stand-up pouch adoption for shelf presence and cube-optimized shipping configurations.
- Industrial Packaging:Component and hardware applications tolerate lower clarity standards, opening procurement to wider converter bases with less stringent food-contact qualification pipelines.
Food Industry absorbs the dominant share of volume; Pharmaceutical is expanding most quickly on compliance-driven supplier consolidation.
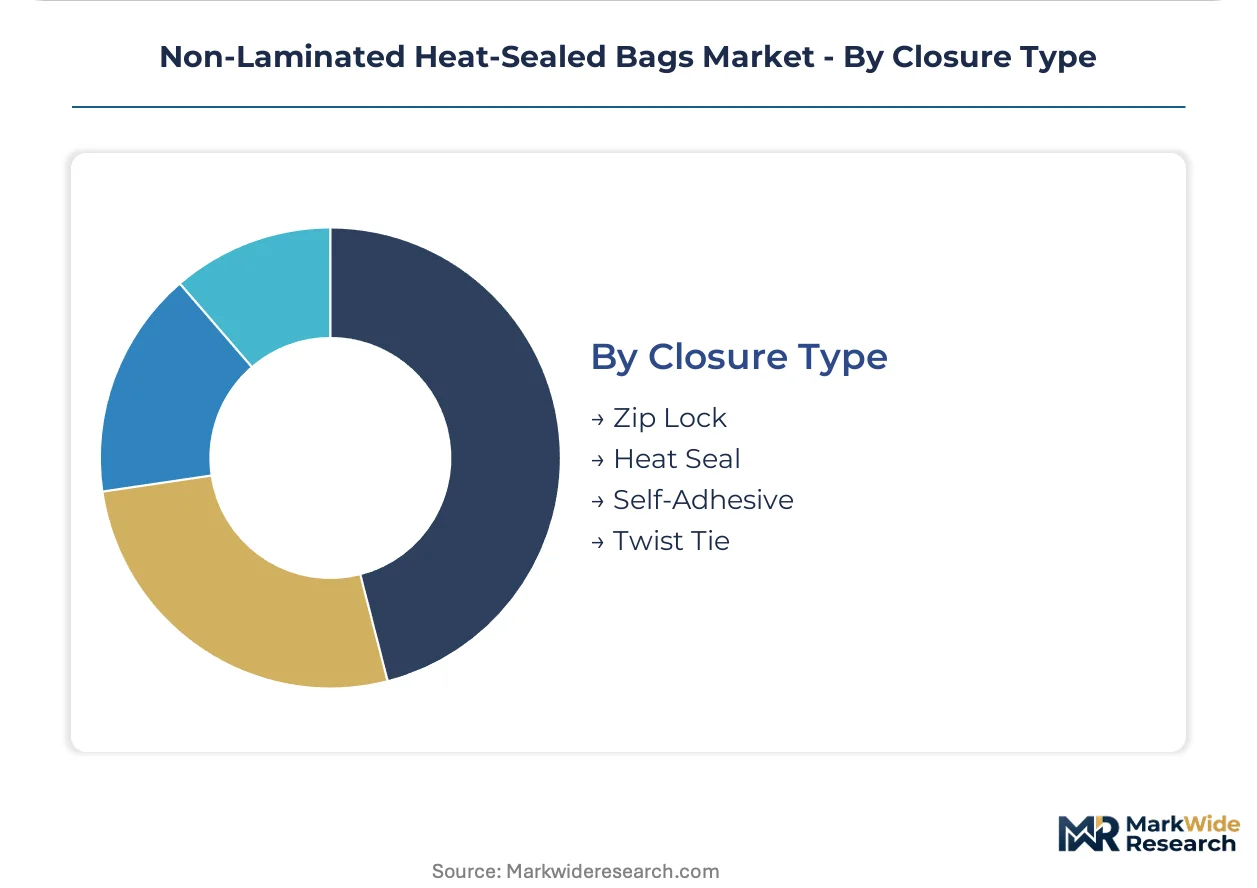
Closure Type:
Customer type differentiation separates resealable specifications for multi-use consumer applications from permanent heat-seal formats optimized for portion control and tamper evidence.
- Zip Lock:Interlocking track closures enable resealability for multi-serve dry goods and refrigerated items where consumer convenience supports brand loyalty. Quick-service restaurant chains specify these for back-of-house ingredient management.
- Heat Seal:Permanent thermal fusion dominates portion-controlled packaging where tamper evidence and extended shelf stability are prioritized over resealability.
- Self-Adhesive:Strip-seal formats serve light-duty retail and industrial applications where resealability is desired without zipper track cost premiums.
- Twist Tie:Mechanical closures persist in bakery and produce segments where breathability and low unit cost outweigh barrier performance requirements.
Heat Seal carries the majority of volume throughput; Zip Lock is gaining share fastest on food service operational specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor spanning Texas and Louisiana anchors North American resin supply for film extrusion, while California's port infrastructure channels Asian biodegradable film imports. Distribution gravity concentrates around Dallas-Fort Worth cold-chain hubs and Los Angeles basin fulfillment centers.
United States
Quick-service restaurant chains consolidate procurement around Texas and California distribution corridors. FDA food-contact substance notifications impose batch-level testing burdens on recycled polyethylene streams. Dallas-Fort Worth cold-chain infrastructure investments create regional hub capacity for direct retailer fulfillment.
Germany
EU REACH restrictions on polymer additives shape export-oriented converter formulations. ECHA substance evaluation processes extend material qualification timelines versus FDA pathways. The Rhine-Ruhr industrial cluster hosts integrated film extruders serving Central European food processors.
China
Dual carbon goals accelerate domestic converter investment in biodegradable film capacity. SAMR food-contact material standards tighten additive disclosure requirements. The Yangtze River Delta concentration of flexible packaging converters supplies Asian quick-service restaurant chains.
India
FSSAI packaging safety regulations create compliance entry barriers for imported film grades. BIS certification requirements for food-contact plastics fragment supplier qualification. Maharashtra and Gujarat industrial corridors concentrate domestic extrusion capacity for regional food processors.
Brazil
ANVISA pharmaceutical packaging standards open specialized demand for custom-shaped heat-sealed configurations. The São Paulo industrial belt anchors South American flexible packaging conversion. Local food processors specify virgin polyethylene grades to avoid import duty exposure on specialized films.
Non-Laminated Heat-Sealed Bags Market Competitive Landscape
Listed leaders compete with private specialists across resin integration and regional footprint dimensions. The vendor base concentrates around three tiers: integrated resin-to-film operators with captive polyethylene supply, regional converters serving single-country food processors, and specialty qualifiers focused on recycled content and biodegradable formulations. Dominant competitive moves include backward integration into resin reprocessing and multi-regional extrusion capacity expansion to capture quick-service restaurant national account contracts.
Within the integrated tier, Amcor Plc and Sealed Air Corporation exemplify scale-driven positioning through global manufacturing footprints. Mondi occupies a distinct position bridging European supply continuity with North American distribution reach. These three entities represent the archetype of converters leveraging resin integration and multi-continental extrusion assets to serve consolidated food service procurement.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global |
| Mondi |
| Huhtamaki |
| Sonoco Products Company |
| International Paper |
| Constantia Flexibles |
| Sealed Air Corporation |
| Uflex Ltd. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day resin qualification timelines for recycled polyethylene streams concentrate pricing power among Gulf Coast integrated producers with captive ethylene supply, while converters lacking backward integration absorb margin compression from virgin feedstock volatility.
Pricing Analysis
Volume-discount tiering structures separate national quick-service restaurant accounts securing long-term offtake contracts from regional food service distributors purchasing on spot indices. Price differentiation rests on FDA food-contact certification grade and captive resin supply status, with integrated converters commanding premiums over merchant-market-dependent competitors. Cost compression in standard-grade virgin polyethylene is intensifying as Texas-Louisiana ethylene capacity expansions outpace demand growth. Quick-service restaurant chains exhibit lowest price sensitivity due to specification lock-in, while independent retail distributors face highest pressure to qualify lower-cost recycled alternatives.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-West Coast trade lanes elevate inbound logistics costs for biodegradable film imports from Chinese PLA producers. Raw material supply concentrates in the United States, Saudi Arabia, and China, with Gulf Coast ethylene crackers, Middle Eastern polyethylene exporters, and Yangtze River Delta film extruders anchoring global capacity. The supply chain draws from natural gas liquids feedstock, polymer additive packages, and masterbatch colorants. Single-source vulnerability concentrates around Texas-Louisiana hurricane exposure. Distribution runs through Dallas-Fort Worth cold-chain hubs and California fulfillment centers serving direct-to-consumer grocery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated quick-service restaurant chains and national food service distributors, fragmenting local converter relationships as procurement centralizes around multi-regional vendors with integrated fulfillment capabilities.
For Market Incumbents: Secure captive resin supply through backward integration into post-industrial reprocessing or long-term ethylene offtake agreements with Gulf Coast crackers. Defend margin position by accelerating FDA food-contact notification timelines for recycled content streams before California SB 54 compliance deadlines tighten procurement preferences. Multi-layer barrier substitution in premium protein segments represents the most acute substitution threat requiring dedicated quality personnel investment. For New Entrants and Emerging Players: Anchor in biodegradable film qualification for organic and private-label dry goods segments where brand differentiation commands placement premiums unavailable in commoditized virgin polyethylene. Target Texas distribution corridor expansion as the most penetrable geography, where Dallas-Fort Worth cold-chain infrastructure investments outpace incumbent converter capacity. Pursue direct-to-consumer grocery platform specifications as the primary go-to-market angle, emphasizing cube-optimized gusseted and stand-up pouch formats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recycled-content qualification pipelines as FDA testing documentation burdens and equipment retrofit costs for biodegradable film processing strain smaller converter balance sheets. Long-term viability favors integrated resin-to-film operators with multi-regional extrusion footprints capable of serving consolidated national accounts. Acquisition target archetype: mid-tier converters with established BRC packaging certification and underutilized capacity in Texas or California corridors. Watch resin price volatility relative to natural gas liquids pricing as the critical inflection signal for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Reprocessing | Captive supply of post-industrial recycled polyethylene secures California SB 54 compliance and margin protection. |
| FDA Food-Contact Substance Notification Acceleration | Streamlined clearance pathways for recycled content enable faster material qualification versus historical timelines. |
| Texas Distribution Corridor Capacity Expansion | Dallas-Fort Worth and Houston cold-chain infrastructure investments capture regional hub demand from consolidated buyers. |
| Biodegradable Film Equipment Retrofit | Screw and die modifications for PLA and PHA blends access organic segment placement premiums. |
| Multi-Regional Extrusion Footprint Buildout | Integrated converting assets across Gulf Coast and California corridors serve national quick-service restaurant accounts. |
Research Methodology
Desk research of FDA food-contact substance notification databases, customs and trade flow records for polyethylene resin imports, and SEC filings from integrated packaging converters preceded structured interviews with film extrusion plant managers, quick-service restaurant procurement directors, food service distributor category buyers, and flexible packaging regulatory affairs specialists. Secondary validation drew from American Chemistry Council resin production reports, California Department of Resources Recycling and Recovery compliance filings, and ISO 22000 certification registry data. Bottom-up volume estimates triangulated against top-down demand aggregation from end-use consumption patterns.
Variance decomposition across material grade, product geometry, closure specification, and end-use certification tier informed the analytical framework over the projection horizon. Segmentation dimensions modeled include virgin versus recycled content status, flat versus gusseted versus stand-up pouch configuration, heat-seal versus zip-lock closure type, and food industry versus pharmaceutical versus retail end-use. CAGRs derived from logistic curve fitting to historical shipment data adjusted for regulatory inflection points. Industry-specific forecast inputs encompassed ethylene cracker capacity utilization rates and quick-service restaurant commissary expansion pipelines.
Material uncertainties — resin price volatility tied to natural gas liquids markets, hurricane disruption at Gulf Coast petrochemical facilities, and accelerated biodegradable film substitution in organic segments — sit outside the modeled envelope. Forecasts reflect assumptions regarding California SB 54 implementation timelines and FDA notification pathway efficiency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Type-C Bulk Bags Market