
 Stackable Container Market | 2026-2036
Stackable Container Market Size, Share, and Industry Trends Forecast 2026-2036
Stackable Container Market Analytics
Food-grade polymer certification is reorganizing procurement priorities across the stackable container industry. Schoeller Allibert leverages its European pooling network to dominate closed-loop supply chains for fresh produce. ORBIS Corporation anchors North American demand through heavy-duty plastic designs engineered for automotive component sequencing. Brambles Limited extends its CHEP share-and-reuse platform into intermediate bulk containers, competing on asset velocity rather than unit sales.
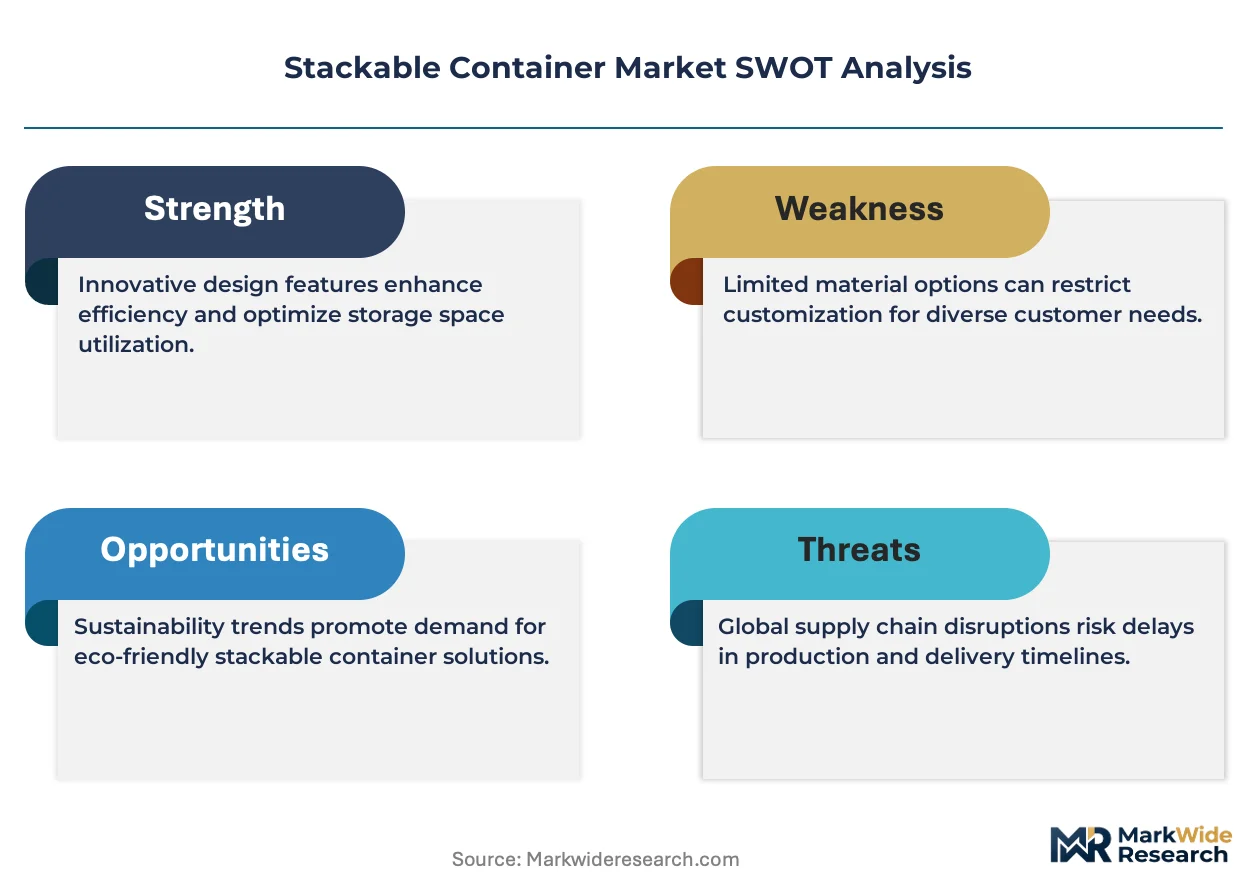
Stackable containers are rigid or semi-rigid receptacles engineered with interlocking feet and nesting features, typically molded from high-density polyethylene or polypropylene to withstand static loads exceeding 500 kg in warehouse racking systems. Their primary commercial purpose centers on unitizing goods for storage density, transport efficiency, and automated handling compatibility across distribution networks. Plastic containers lead unit volume due to durability and washability in food and pharmaceutical circuits, while metal variants command premium positioning in hazardous material and heavy industrial applications where flame resistance and load ratings exceed polymer capabilities. Cardboard formats occupy a shrinking but persistent niche in lightweight retail display and single-trip export packaging where return logistics prove uneconomical.
The FDA Food Safety Modernization Act and EU REACH chemical compliance frameworks govern material contact approvals and substance restrictions for food-facing containers, directly shaping resin formulations and additive packages available to manufacturers. ISO 6780 standardization for flat pallets and associated container base dimensions determines interoperability across regional logistics networks, creating compliance barriers for non-conforming product entries. Stakeholders must monitor evolving extended producer responsibility schemes in California and the European Union, as these programs will shift end-of-life collection costs upstream to container producers and reshape total cost of ownership calculations for buyers evaluating material alternatives.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing cold chain logistics operators to accelerate fleet turnover toward reusable formats, compressing payback period calculations for container procurement.
Growth Catalysts
- REACH chemical compliance frameworks:ECHA substance restrictions are eliminating legacy additive packages, creating replacement demand for certified food-grade resins across European fresh produce distribution networks.
- Automotive component sequencing:Just-in-time manufacturing protocols in Germany and Mexico are standardizing European pooled container formats for inbound parts logistics, locking in format specifications.
- High-density polyethylene durability:Washability ratings exceeding 500 cycles in pharmaceutical circuits are displacing single-use corrugated alternatives in temperature-controlled distribution.
Market Restraints
- Polypropylene resin price volatility:Feedstock fluctuations tied to naphtha cracking economics in the US Gulf Coast are compressing margin buffers for molded container producers.
- ISO 6780 dimensional compliance:Non-conforming base footprint designs face interoperability barriers across pooled logistics networks, fragmenting addressable demand.
- Metal container substitution:Flame-resistant steel formats retain hazardous material handling certifications that exceed polymer load ratings in heavy industrial applications.
Strategic Opportunities
- California extended producer responsibility schemes:Upstream cost shifting for end-of-life collection creates first-mover advantage for closed-loop pooling platform operators.
- RFID-embedded track-and-trace convergence:Integration of passive sensor tags with warehouse management systems enables asset velocity monetization beyond unit sales.
- India cold chain infrastructure gaps:Underpenetrated pharmaceutical distribution networks present format standardization opportunities for insulated stackable designs.
Industry Challenges
- FDA Food Safety Modernization Act certification timelines:Material contact approval delays average 18-24 months, freezing product development pipelines for new resin formulations.
- Legacy warehouse racking incompatibility:Automated storage and retrieval systems designed for single-use pallets require retrofitting to accommodate reusable container foot profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stackable Container Market |
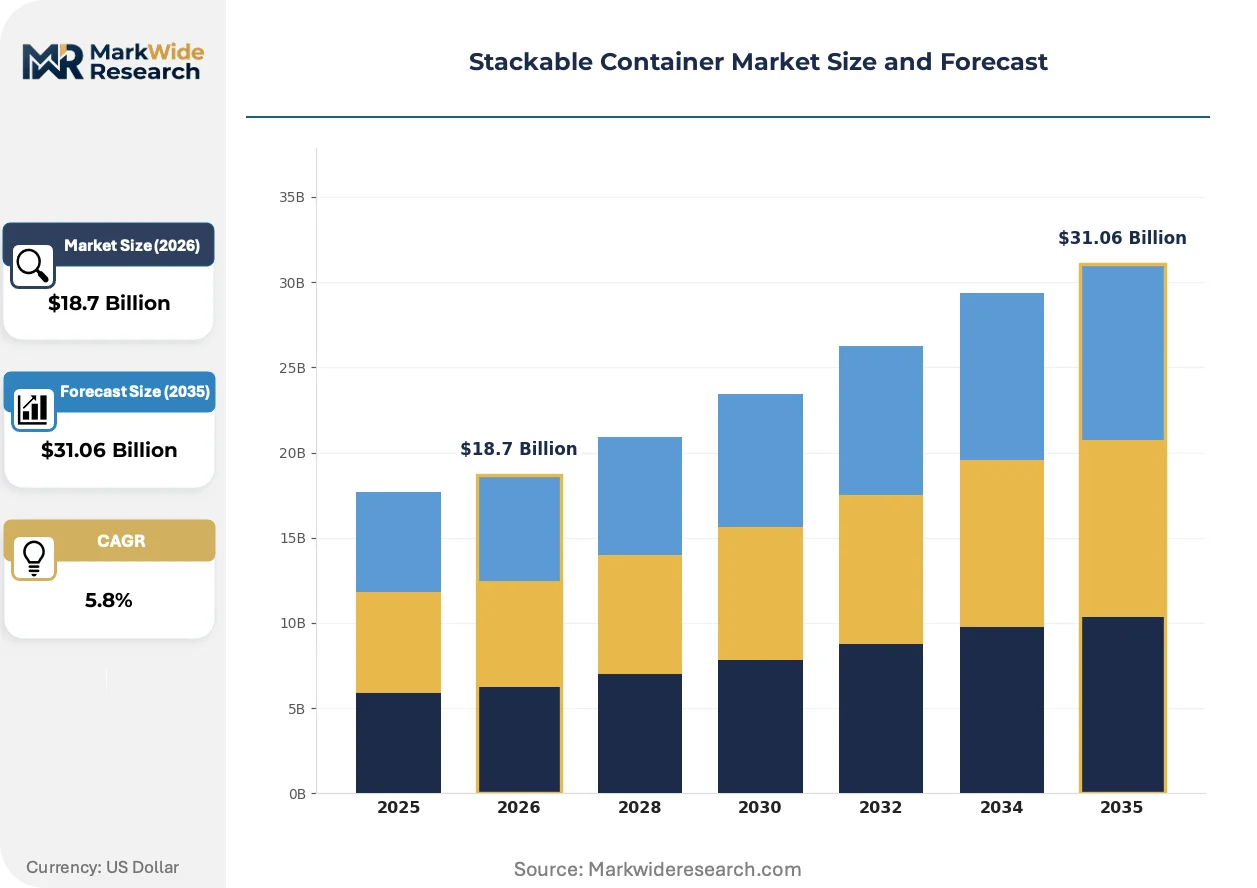
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Cardboard, Wooden Application: Food Storage, Shipping, Retail Display, Waste Management Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | ORBIS Corporation, Schoeller Allibert, Brambles Limited, SSI SCHAEFER, Georg UTZ Holding AG, Polymer Logistics, Monoflo International, Greif, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stackable Container Market Evolving Landscape
Active material science development is decomposing traditional durability-weight tradeoffs, enabling lighter formats that retain static load ratings. Three developments are compressing competitive positioning.
Embedded passive RFID tagging is decomposing asset visibility limitations in closed-loop supply chains. Pharmaceutical distributors in Germany and the Netherlands are retrofitting existing fleets with temperature-logging sensors. This convergence is compressing insurance premiums for high-value cargo by enabling real-time deviation alerts.
REACH substance restrictions are eliminating phthalate-based plasticizers from food-contact applications. ECHA authorization requirements are forcing reformulation of polypropylene additive packages. European fresh produce pooling networks are accelerating supplier audits to preempt compliance gaps.
Leasing-based procurement is displacing capital purchase models among mid-sized grocery distributors. Third-party pooling operators in France and Spain are absorbing fleet maintenance and wash-cycle logistics. This shift concentrates buying power with platform operators capable of multi-site asset deployment.
Stackable Container Market Segmentation
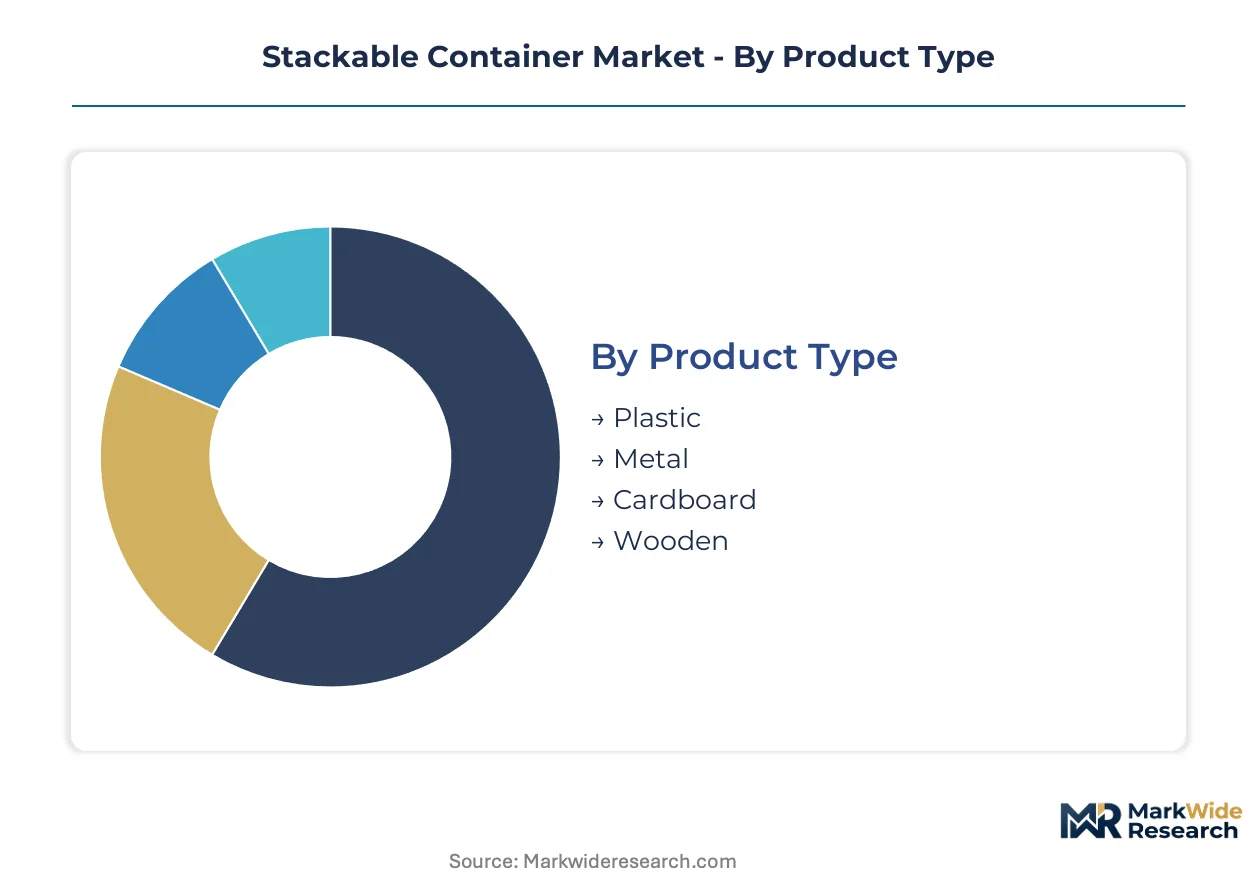
Segmentation in the stackable container market reveals how regulatory compliance, load-bearing requirements, and return logistics economics partition demand across material formats and end-use circuits. Procurement decisions diverge sharply between food-grade certified applications governed by FDA and EFSA contact approvals versus industrial segments prioritizing flame resistance and static load ratings.
Product Type:
REACH substance restrictions and FDA material contact approvals create divergent compliance burdens across material categories, directly shaping resin formulation costs and certification timelines.
- Plastic:High-density polyethylene and polypropylene formulations dominate food and pharmaceutical circuits due to washability exceeding 500 cycles. German automotive suppliers and Dutch fresh produce distributors are standardizing European pooled container formats, locking in polymer specifications.
- Metal:Flame-resistant steel variants retain hazardous material handling certifications that exceed polymer capabilities in heavy industrial applications. Demand concentrates in chemical processing and defense logistics where load ratings surpass 1000 kg static capacity.
- Cardboard:Lightweight corrugated formats occupy shrinking single-trip export niches where return logistics prove uneconomical.
- Wooden:Pallet-collars and crate formats persist in agricultural bulk handling and construction material distribution.
Established volume favors plastic; emerging adoption favors metal in hazardous material segments.
Application:
Cold chain infrastructure investment and just-in-time manufacturing protocols are redistributing demand across end-use verticals based on temperature control requirements and sequencing precision.
- Food Storage:EU Packaging and Packaging Waste Regulation mandates are accelerating reusable container fleet turnover. French and Spanish grocery distributors are migrating from capital purchase models toward third-party pooling arrangements that absorb wash-cycle logistics.
- Shipping:ISO 6780 dimensional compliance determines interoperability across regional logistics networks. Non-conforming base footprint designs face exclusion from pooled networks.
- Retail Display:Lightweight formats with branding surfaces serve in-store merchandising where single-trip economics dominate.
- Waste Management:Industrial recycling circuits utilize heavy-duty formats for collection and sortation of post-consumer materials.
Food storage commands the steepest expansion trajectory; retail display faces compression from sustainability mandates.
Size:
Automated storage and retrieval system compatibility and manual handling ergonomics partition demand across dimensional tiers.
- Small:Pharmaceutical component kits and precision automotive parts utilize compact footprints compatible with dense warehouse racking.
- Medium:European pooled container standards concentrate procurement in this tier for fresh produce and inbound parts logistics.
- Large:Bulk ingredient handling in food processing and chemical distribution drives volume.
- Extra Large:Intermediate bulk container formats compete with flexible intermediate bulk containers in liquid and granular material handling.
Medium formats anchor pooled network standardization; extra large formats gain traction in chemical logistics.
Distribution Channel:
Asset velocity monetization and fleet maintenance capabilities are consolidating procurement power with platform operators versus transactional sales.
- Online:Direct-to-manufacturer configurators serve customized industrial specifications with extended lead times.
- Retail:Standardized formats for small-scale agricultural and light industrial buyers.
- Wholesale:Regional distributors aggregate demand from mid-sized food processors and automotive tier suppliers.
- Direct Sales:Closed-loop pooling platforms operated by CHEP and Schoeller Allibert dominate multi-site asset deployment for grocery and automotive networks.
Direct sales concentrate with pooling platforms; wholesale retains fragmented mid-market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. German automotive buyers prioritize ISO 6780 dimensional compliance over unit cost. Indian pharmaceutical distributors face capital constraints that favor leasing models over fleet ownership.
United States
California extended producer responsibility schemes are shifting end-of-life collection costs upstream to container producers. FDA Food Safety Modernization Act certification timelines average 18-24 months for new resin formulations. Cold chain logistics operators in the Central Valley are retrofitting automated storage systems to accommodate reusable container foot profiles.
Germany
Just-in-time manufacturing protocols at automotive plants in Bavaria and Baden-Württemberg standardize European pooled container formats for inbound parts sequencing. ECHA REACH substance restrictions are eliminating phthalate-based plasticizers from food-contact applications. Fresh produce distributors in the Hamburg port cluster are migrating toward third-party pooling arrangements.
China
Dual carbon goals under MEE oversight are accelerating fleet turnover toward reusable formats in temperature-controlled distribution. GB standards for food-contact materials govern resin formulation approvals. Pharmaceutical distributors in the Yangtze River Delta are deploying RFID-embedded containers for real-time deviation alerts.
India
Underpenetrated cold chain infrastructure in pharmaceutical distribution creates format standardization opportunities for insulated stackable designs. FSSAI food safety mandates are tightening material contact requirements. Logistics operators in Maharashtra and Gujarat are absorbing fleet maintenance through emerging pooling platforms.
Netherlands
Rotterdam port authorities are enforcing EU Packaging and Packaging Waste Regulation mandates for transport packaging recovery. EFSA compliance frameworks determine additive package approvals for food-facing containers. Dutch fresh produce pooling networks are accelerating supplier audits to preempt REACH compliance gaps.
Stackable Container Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. Asset-heavy pooling platforms compete on fleet velocity and wash-cycle logistics rather than unit manufacturing margins. Molded container specialists differentiate through food-grade polymer certification and ISO 6780 dimensional precision. The market structure concentrates procurement power with platform operators capable of multi-site deployment. Dominant competitive moves include strategic partnerships with grocery distributors and capacity expansion in automotive supply corridors.
Within the pooling platform tier, Brambles Limited and Schoeller Allibert exemplify asset-velocity monetization models. ORBIS Corporation anchors North American positioning through heavy-duty plastic designs. These three represent divergent geographic emphases—Australian-listed, European-headquartered, and US-based respectively—while converging on closed-loop service architectures that absorb maintenance logistics from end-users.
| Leading Market Players |
|---|
| ORBIS Corporation |
| Schoeller Allibert |
| Brambles Limited |
| SSI SCHAEFER |
| Georg UTZ Holding AG |
| Polymer Logistics |
| Monoflo International |
| Greif |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Phthalate-free additive packages replacing legacy plasticizers in food-contact resins are simultaneously relocating formulation expertise toward REACH-compliant European suppliers and compressing margin structures for non-certified producers. This substitution dynamic concentrates pricing power with certified compounders while forcing procurement cost recalculations across container fleets.
Pricing Analysis
Wash-cycle service revenue drives lifetime value for pooling platform operators, displacing pure unit-sales economics. Three-tier pricing structure across premium food-grade certification, standard industrial grades, and economy single-trip formats segments buyer tiers. Cost compression in standard-grade polymer containers intensifies due to naphtha feedstock volatility in Gulf Coast cracking economics. Small-scale agricultural buyers exhibit highest price sensitivity; pharmaceutical cold chain operators prioritize certification compliance over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor European pooled container manufacturing and wash-cycle infrastructure. High-density polyethylene resin draws from naphtha crackers in the US Gulf Coast and Middle Eastern feedstock hubs; RFID tag assemblies source from East Asian electronics manufacturers. Single-source vulnerability concentrates in specialized food-grade additive packages subject to ECHA authorization delays. Distribution runs through closed-loop pooling platforms operated by CHEP and Schoeller Allibert, bypassing traditional wholesale channels for multi-site grocery and automotive networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against flexible intermediate bulk containers and collapsible bag-in-box formats that undercut rigid container economics in liquid handling. Incumbents must harden their position through asset-velocity advantages and certification barriers.
For Market Incumbents: Consolidate pooling platform density in automotive supply corridors to lock in just-in-time sequencing contracts. Expand backward integration into captive wash-cycle facilities to absorb logistics costs that third-party operators cannot match. Metal container specialists threaten polymer dominance in hazardous material segments; preempt with flame-resistant polymer formulations.
For New Entrants and Emerging Players: FDA Food Safety Modernization Act fast-track certification for pharmaceutical-grade resins opens white-space in temperature-controlled distribution. Target underpenetrated Indian cold chain infrastructure where FSSAI compliance mandates are tightening but pooling platforms remain nascent. Lead with leasing-based procurement models that eliminate capital barriers for mid-sized grocery distributors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pooling platform operators in France and Spain seeking exit liquidity. Five-to-ten-year viability hinges on RFID-embedded fleet monetization beyond unit sales. Monitor California extended producer responsibility implementation timelines as inflection indicator for upstream cost-shifting magnitude.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Additive Reformulation | ECHA authorization requirements force resin supplier consolidation toward certified compounders. |
| RFID Fleet Retrofit Programs | Temperature-logging sensor integration enables real-time deviation alerts for pharmaceutical distributors. |
| Backward Integration into Wash-Cycle Logistics | Captive facility ownership absorbs maintenance costs that erode third-party pooling margins. |
| European Pooled Format Standardization | ISO 6780 dimensional compliance locks automotive suppliers into interoperable container specifications. |
| Leasing-Based Procurement Platform Launch | Asset-light models concentrate buying power with operators capable of multi-site deployment. |
Research Methodology
Operator-level perspectives from cold chain logistics directors, automotive tier supplier procurement managers, grocery distribution network planners, and polymer compounder technical sales leads anchored the qualitative base. These primary insights combined with secondary validation from FDA material contact approval databases, ECHA REACH substance restriction registers, EU Packaging and Packaging Waste Regulation implementation trackers, and customs trade flow records. Bottom-up fleet deployment estimates triangulated against top-down packaging spend allocations across food, pharmaceutical, and automotive verticals.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios and regulatory implementation lag assumptions. Segmentation dimensions modeled include material format, application circuit, dimensional tier, and distribution channel architecture. CAGRs derived from trend extrapolation of fleet turnover rates and substitution elasticities between reusable and single-use formats. Industry-specific inputs incorporated automotive production sequencing intensity and pharmaceutical cold chain infrastructure buildout trajectories.
Decision-makers should treat outputs as directional under stable regulatory implementation schedules and resin feedstock supply continuity; material deviation in ECHA authorization timelines or naphtha cracking economics would warrant model refresh. Specific risks include REACH substance restriction scope expansion and California extended producer responsibility cost allocation rulings. Recalibration cycles align with material shifts in EU packaging waste recovery mandates and FDA certification backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Carboy Market
Containers
Disposable Cups and Lids Market
Containers
Slip Lid Can Market
Containers
Takeaway Containers Market
Containers
North America Insulated Shipping Containers Market
Containers
Foldable Steel Containers Market
Containers
Screw Top Pails Market
Containers
Global Food Containers Market
Containers
Laminated Bulk Bins Market
Containers
Wooden Barrels Market
Containers
Oblong Jar Market
Containers
Algeria Container Glass Market
Containers
Light Resistant Containers Market
Containers
Collapsible Sleeve Containers Market
Containers
Lab Storage Container Market
Containers
PET Containers Market