

Rigid IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid IBC Market Insights
Aftermarket service revenue is narrowing as a margin pool migration between new container sales and refurbishment cycles intensifies. Greif leverages its global collection network to capture recurring reconditioning contracts. Mauser Packaging Solutions anchors its position through backward integration into resin compounding and steel cage fabrication. Schütz competes via specialized UN-certified designs for hazardous chemical transport.
A rigid intermediate bulk container is a reusable industrial vessel, typically constructed from high-density polyethylene with a galvanized steel tubular cage, engineered to store and transport 250 to 1,000 liters of liquid or granular materials. Plastic containers dominate unit volumes due to corrosion resistance and lower tare weight, while metal variants command premium positioning in solvent and high-temperature applications. Chemical storage represents the most mature application segment with established replacement cycles, whereas pharmaceutical transport offers faster expansion as aseptic filling requirements tighten. Manufacturing plants constitute the largest end-user category by installed base, though logistics providers represent the fastest-growing procurement channel as third-party pooling models expand.
The US Department of Transportation and the UN Recommendations on the Transport of Dangerous Goods govern container certification, while EPA regulations on chemical containment influence material specifications and inspection frequencies. European REACH compliance and the EU Packaging and Packaging Waste Directive shape recyclability mandates and material traceability requirements. Stakeholders must monitor regulatory divergence between regional hazardous goods frameworks and assess whether localized reconditioning investments or centralized manufacturing scales offer superior unit economics under tightening circularity rules.
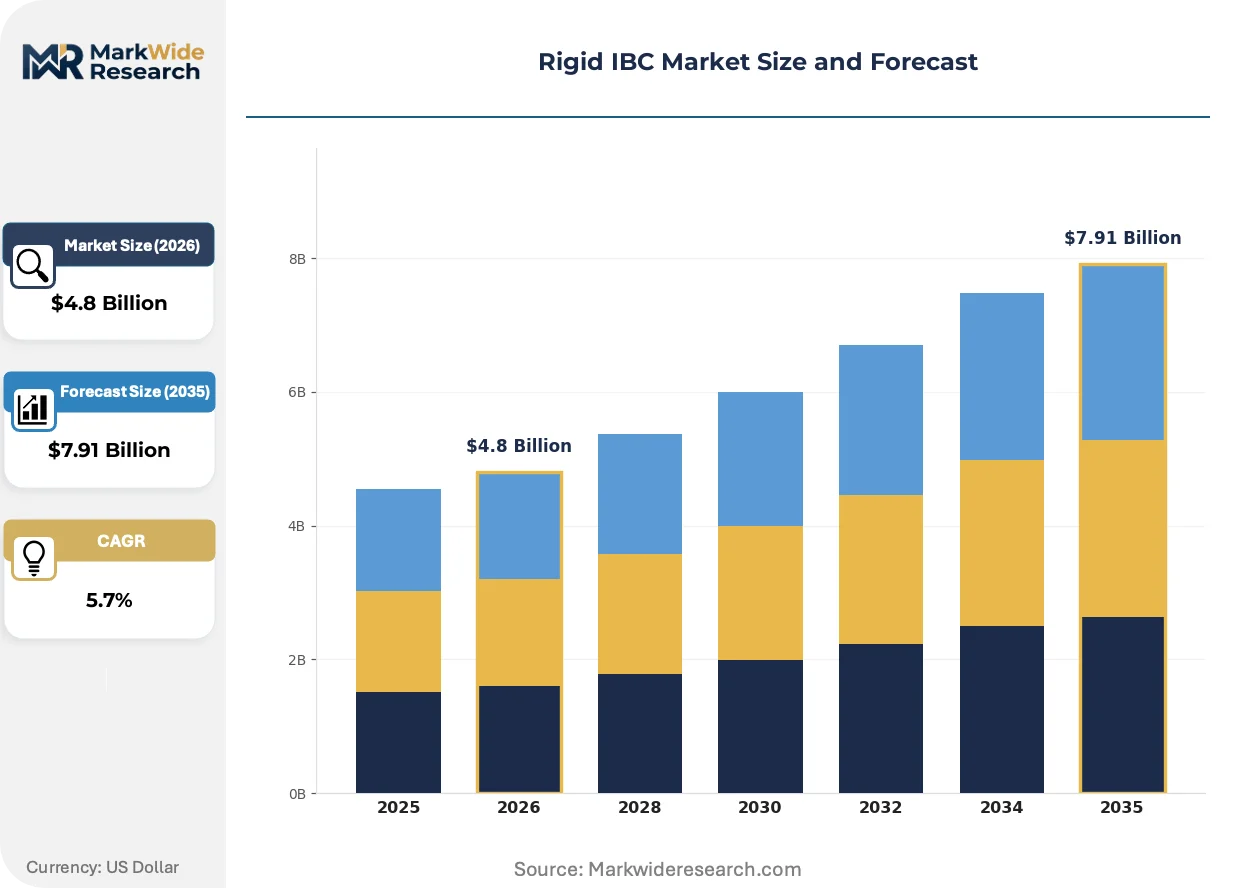
Market Dynamics
Chemical manufacturers are systematically replacing legacy drum systems with rigid IBCs to reduce handling costs and align with tightening UN-certified transport mandates across hazardous material corridors.
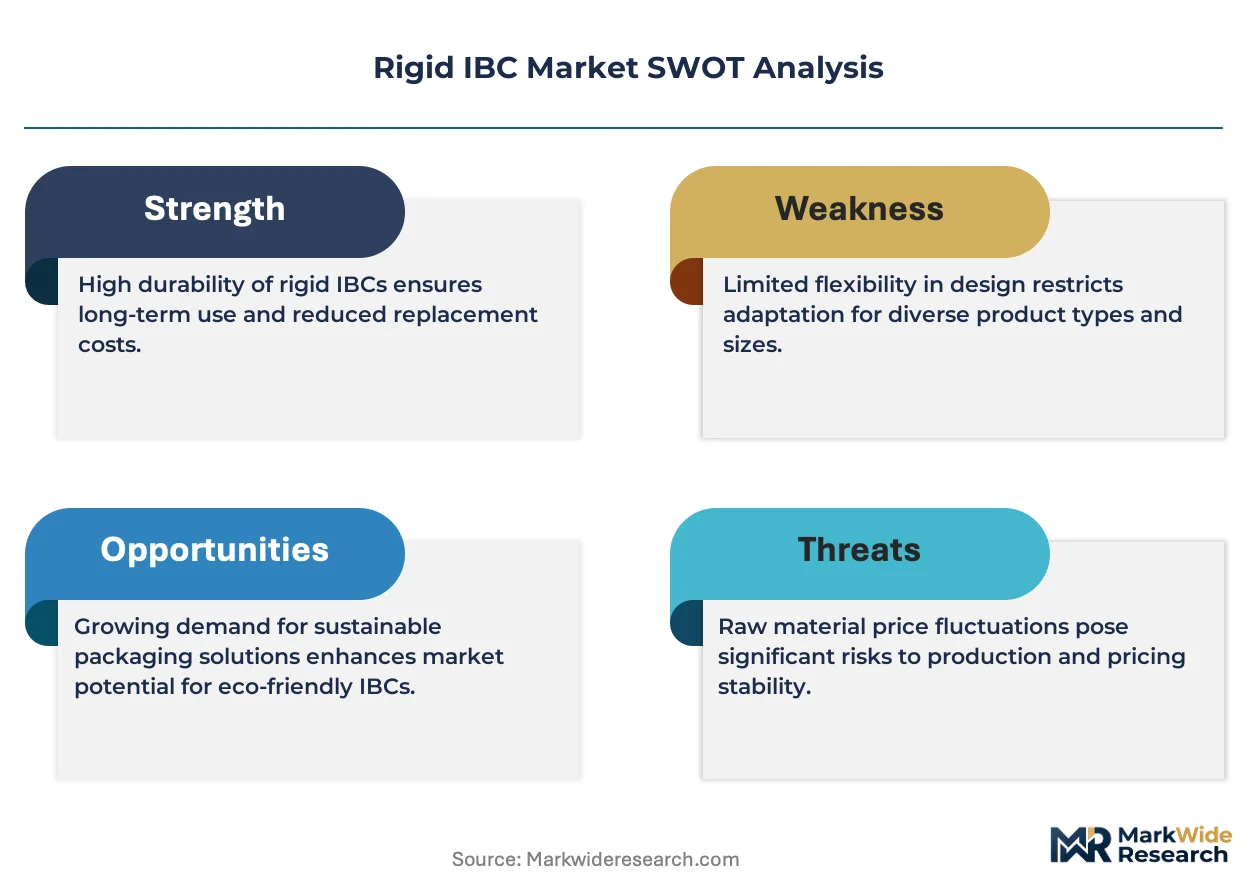
Growth Catalysts
- REACH compliance mandates:European chemical handlers must demonstrate full material traceability and recyclability, accelerating container standardization toward reusable IBC formats.
- Integrated chemical park expansion:Germany, China, and the United States are densifying co-located production clusters where shared IBC pooling networks minimize cross-site logistics friction.
- Corrosion-resistant HDPE formulations:Advanced polymer blends now withstand aggressive solvent exposure previously requiring metal drums, expanding addressable chemical categories.
Market Restraints
- Steel cage input volatility:Galvanized steel tubular components face pricing pressure from energy-intensive smelting operations concentrated in specific supplier geographies.
- Reconditioning capacity concentration:Third-party refurbishment networks remain thin outside Germany and the US Midwest, creating service gaps for dispersed chemical processors.
- Metal drum substitution persistence:Solvent and high-temperature applications still favor stainless steel alternatives where thermal stability exceeds polymer limits.
Strategic Opportunities
- Pharmaceutical aseptic transport:Tightened filling requirements create demand for specialized UN-certified designs with validated sterilization protocols.
- Third-party pooling channel expansion:Logistics providers are building asset-light IBC fleets that chemical manufacturers lease rather than own, shifting procurement toward service contracts.
- EU circularity rules:The Packaging and Packaging Waste Directive incentivizes localized reconditioning investments with preferential treatment under extended producer responsibility frameworks.
Industry Challenges
- UN certification timeline compression:Evolving dangerous goods classifications require frequent design revalidation, stretching engineering resources.
- Legacy drum system integration:Chemical plants with entrenched filling and handling infrastructure face capital-intensive retooling to accommodate IBC dimensions and connection standards.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid IBC Market Trends and Innovations
Sensor-enabled asset tracking and predictive maintenance protocols are reshaping how chemical handlers manage container fleets, converting passive storage vessels into connected supply chain nodes.
RFID-embedded IBCs are digitizing container lifecycle management. Major chemical distributors are retrofitting existing fleets with passive and active tracking tags to monitor location, fill status, and residual contamination risk. This connectivity layer compresses turnaround times between reconditioning cycles and enables dynamic pooling optimization across multi-site operations.
REACH substance restrictions are tightening material specifications for polymer liners and gasket compounds. ECHA evaluations of phthalate plasticizers and certain stabilizers are forcing reformulation investments, with downstream consequences for container suppliers serving European export markets. German chemical handlers are responding by demanding full material disclosure certificates upstream.
Asset-as-a-service contracting is displacing outright purchase models among mid-sized chemical processors. Third-party pooling operators now bundle container provision, tracking, cleaning, and regulatory documentation into per-use fees. This shift concentrates procurement influence with specialized logistics providers rather than traditional packaging distributors, most visible in the US Gulf Coast petrochemical corridor.
Rigid IBC Market Segmentation
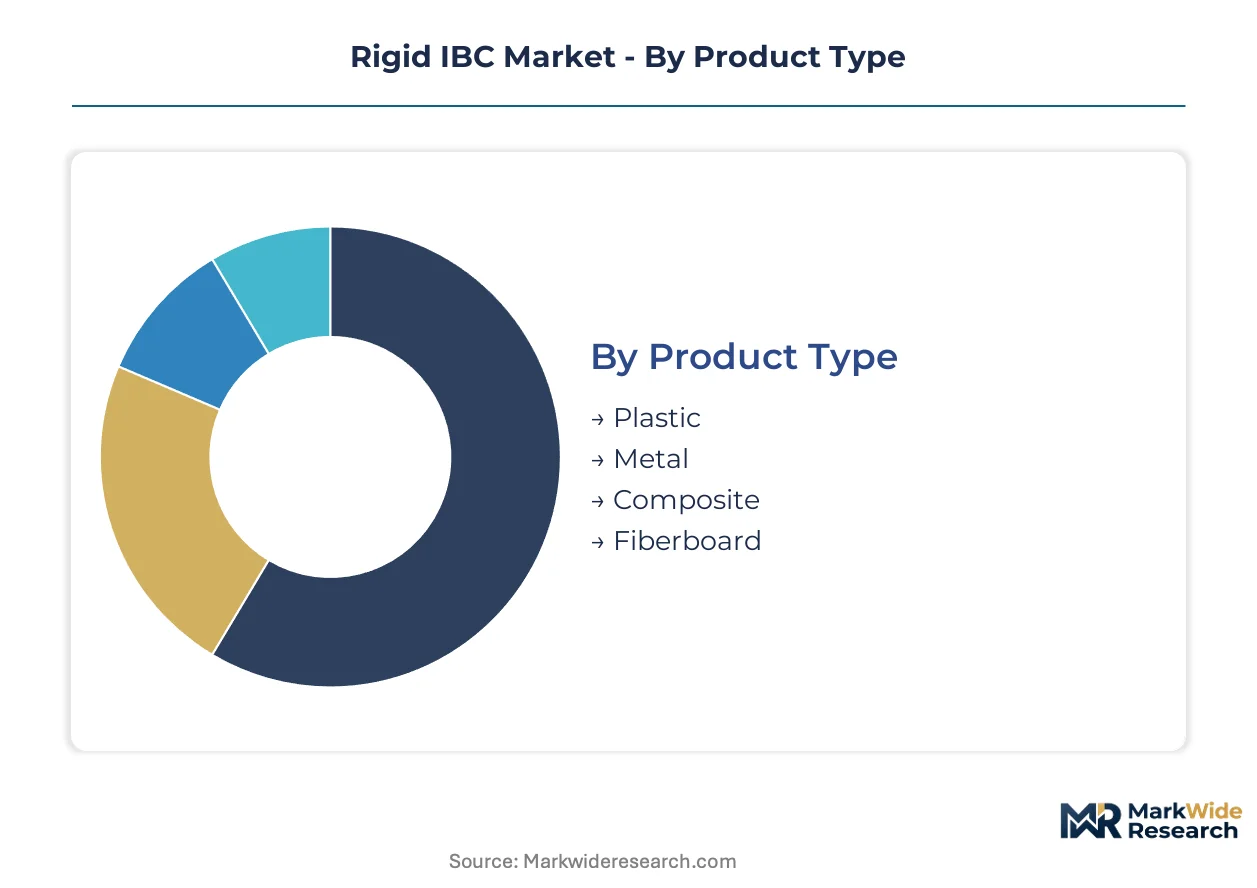
Segmentation in the rigid IBC market reveals distinct procurement patterns across material technologies and operational scales. Container selection hinges on chemical compatibility mandates, capacity utilization economics, and the regulatory density of specific transport corridors.
Product Type:
Mature formats dominate installed base volumes while emerging alternatives capture specialized niches requiring thermal or structural performance beyond standard specifications.
- Plastic:High-density polyethylene construction with galvanized steel tubular cages delivers corrosion resistance and lower tare weight for liquid chemical handling. Demand concentrates in German integrated chemical parks where REACH-mandated material traceability favors standardized reusable formats with full polymer disclosure certificates.
- Metal:Stainless steel variants withstand solvent exposure and elevated temperatures exceeding polymer limits. Processing clusters along the US Gulf Coast favor these units for petrochemical intermediates where thermal stability governs safety protocols.
- Composite:Hybrid constructions blend polymer liners with reinforced outer shells for intermediate performance requirements.
- Fiberboard:Single-use corrugated formats serve non-hazardous dry bulk applications with minimal reconditioning infrastructure.
Plastic retains volume leadership; Metal holds the steepest expansion curve among premium-tier replacements.
Capacity:
Procurement patterns track filling line compatibility and payload optimization across multimodal transport modes.
- 1000 Liters:The maximum standard cube dimension optimizes truck and railcar cube utilization for liquid chemicals. Third-party pooling operators in China prioritize this format for export-oriented chemical processors seeking container standardization across port corridors.
- 500 Liters:Mid-scale units match batch processing volumes in pharmaceutical aseptic filling operations. FDA-regulated facilities in New Jersey and North Carolina specify this capacity for validated sterilization protocols with shorter campaign cycles.
- 250 Liters:Compact footprint serves laboratory-scale chemical handlers and specialty batch operations.
- 750 Liters:Intermediate volume bridges batch and continuous processing lines with flexible handling equipment.
1000 Liter formats anchor fleet deployments; 500 Liter configurations gain share fastest in pharmaceutical contract manufacturing.
Application:
Regulatory stringency varies sharply across transport categories, driving material specification divergence and certification complexity.
- Chemical Storage:The most mature segment with established replacement cycles and UN-certified design standards. German chemical handlers under ECHA oversight demand full material traceability for aggressive solvent contact applications.
- Pharmaceutical Transport:Aseptic filling requirements and validated sterilization protocols create specialized demand. FDA-regulated facilities in the United States specify containers with documented cleaning validation and endotoxin testing.
- Food Processing:FDA and USDA compliance mandates material grades suitable for edible oil and liquid ingredient handling.
- Agricultural Chemicals:EPA registration requirements for pesticide formulations influence liner compatibility specifications.
Chemical Storage maintains installed base dominance; Pharmaceutical Transport climbs fastest on tightening GMP enforcement.
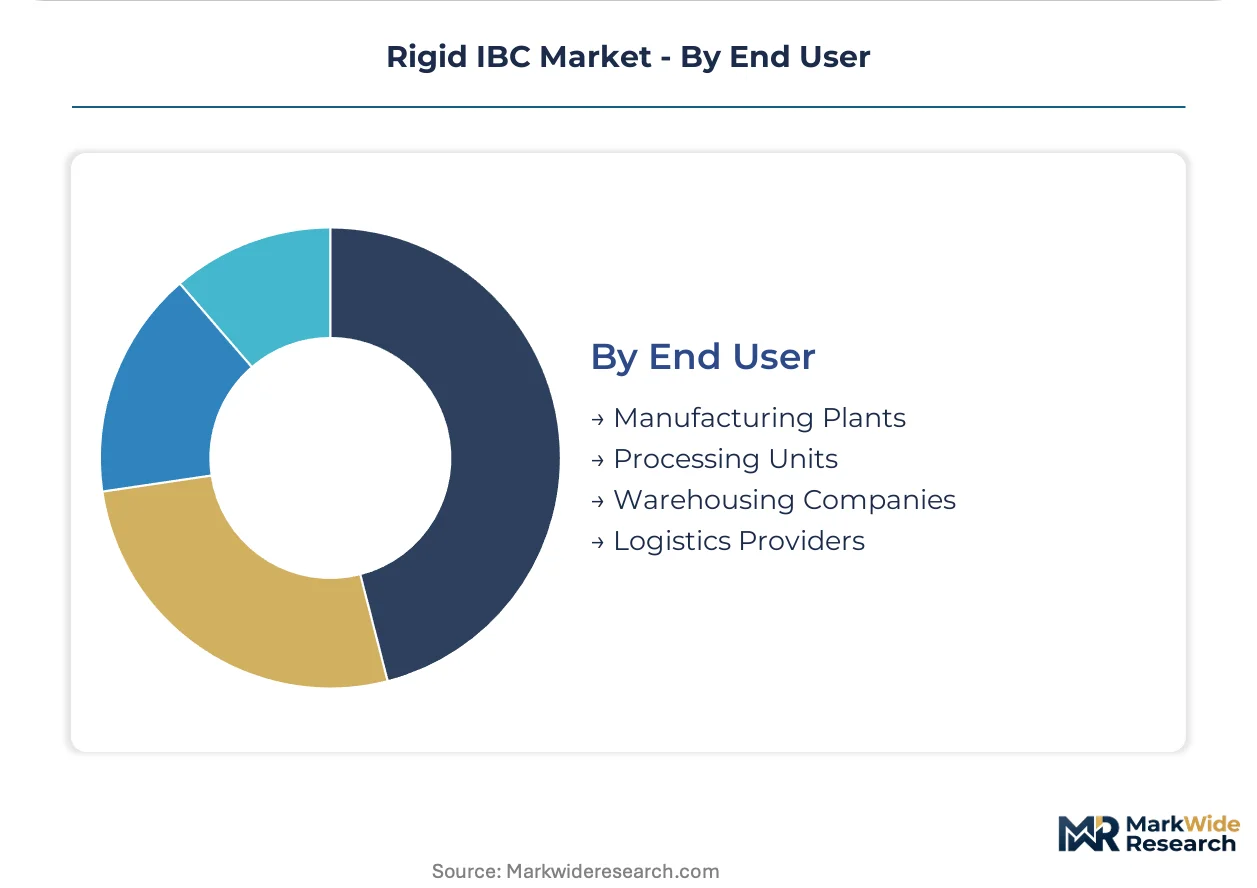
End User:
Asset ownership models are fragmenting as service-based procurement displaces capital expenditure approaches.
- Manufacturing Plants:The largest installed base category with captive fleet ownership and on-site reconditioning capabilities. Major chemical producers in Louisiana and Texas operate dedicated wash facilities supporting continuous production schedules.
- Logistics Providers:Third-party pooling models are expanding most quickly as asset-light fleet management gains traction. Specialized operators in the US Midwest now bundle container provision, tracking, and regulatory documentation into per-use contracting.
- Processing Units:Contract manufacturers and toll processors favor flexible leasing arrangements over fixed asset commitments.
- Warehousing Companies:Storage-focused operators prioritize stackability and footprint efficiency in distribution center configurations.
Manufacturing Plants retain procurement volume leadership; Logistics Providers capture the steepest expansion trajectory through pooling model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany demonstrate the lowest price elasticity, absorbing premium UN-certified formats without volume compression, while processors in India and Southeast Asia retain acute sensitivity to steel cage input costs and reconditioning service availability.
United States
Gulf Coast petrochemical corridors drive demand for metal variants handling high-temperature intermediates. EPA chemical containment regulations mandate inspection frequencies that favor reusable formats with documented cleaning validation. Louisiana and Texas host captive wash facilities supporting continuous production schedules at major chemical producers.
Germany
Integrated chemical parks in Ludwigshafen and Leverkusen operate dense shared pooling networks minimizing cross-site logistics friction. REACH compliance mandates full material traceability and recyclability certificates upstream from container suppliers. ECHA oversight of aggressive solvent contact applications accelerates standardization toward reusable IBC formats with complete polymer disclosure.
China
Export-oriented processing clusters in Jiangsu and Zhejiang provinces prioritize 1000-liter standardization across port corridors. MEE environmental regulations on hazardous waste transport influence container inspection and reconditioning infrastructure investments. Yangtze River Delta chemical parks densify co-located production capacity served by third-party pooling operators.
India
Specialty chemical manufacturers in Gujarat and Maharashtra balance cost pressures against emerging UN-certified transport mandates for export markets. CDSCO pharmaceutical regulations shape aseptic filling requirements in contract manufacturing hubs near Hyderabad and Mumbai. Domestic reconditioning networks remain thin outside western industrial corridors, constraining fleet rotation economics.
Rigid IBC Market Competitive Landscape
Vertically integrated packaging conglomerates and specialized industrial container fabricators split the market along asset-ownership versus service-contracting lines. The structure concentrates among multinational operators with captive reconditioning networks and regional specialists serving price-sensitive procurement channels. Three archetypes dominate: global pooling-network operators, backward-integrated resin-and-cage manufacturers, and UN-certified design specialists. Competitive moves center on geographic expansion of wash-and-refurbishment facilities and portfolio diversification into sensor-enabled fleet tracking.
Within the integrated conglomerate tier, Greif and Mauser Packaging Solutions anchor positions through captive supply chain control and global collection infrastructure. Schütz occupies a specialist position exemplifying UN-certified design capabilities for hazardous chemical transport. Time Technoplast represents the emerging-market fabricator archetype, sitting within cost-competitive manufacturing clusters serving regional export demand.
| Leading Market Players |
|---|
| Greif |
| Mauser Packaging Solutions |
| Schütz |
| Time Technoplast |
| Snyder Industries |
| Hoover Ferguson Group |
| Pyramid Technoplast |
| Brambles |
| Schoeller Allibert |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European reconditioning networks drives both supplier pricing power and buyer procurement consolidation toward integrated pooling operators. German chemical handlers absorb premium UN-certified formats without volume compression, while dispersed processors in India face acute steel cage input cost volatility.
Pricing Analysis
Reconditioning service contracts now drive lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels separating UN-certified hazardous designs from food-grade and single-use formats. Price differentiation centers on certification grade and geographic delivery density, with REACH-mandated material disclosure certificates commanding premiums in German integrated chemical parks. Cost compression in standard-grade plastic containers intensifies because HDPE resin feedstock tracks energy-intensive naphtha cracking economics. Logistics providers show lowest price sensitivity due to pooled fleet depreciation models, whereas mid-sized Indian specialty chemical manufacturers retain acute sensitivity to steel cage input costs.
Supply Chain Analysis
Export-control regimes on advanced polymer compounding technologies limit flow of corrosion-resistant HDPE formulations to certain processing clusters. Supply concentrates in Germany, China, and the United States, where integrated chemical parks anchor captive reconditioning infrastructure. Raw material dependencies center on high-density polyethylene resin, galvanized steel tubular components, and specialized gasket compounds. Single-source vulnerability in European steel cage fabrication creates exposure to energy-intensive smelting operations concentrated in specific supplier geographies. Distribution runs through third-party pooling operators bundling container provision, tracking, cleaning, and regulatory documentation into per-use contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. UN certification timelines and REACH material traceability mandates embed switching costs that protect established positions.
For Market Incumbents: Pre-empt emerging pooling-network competitors by expanding captive wash-and-refurbishment capacity into the US Gulf Coast and Yangtze River Delta corridors. Anchor backward integration into resin compounding to secure HDPE formulation control against feedstock volatility. Defensive consolidation through certification investment in pharmaceutical aseptic designs protects against specialized UN-certified design specialists.
For New Entrants and Emerging Players: Mid-market pharmaceutical contract manufacturers in India represent the most penetrable entry point, where CDSCO aseptic filling requirements outpace domestic reconditioning infrastructure development. Specialized agricultural chemical handlers in Brazil seeking EPA-aligned container formats for export markets offer second-tier white space. Go-to-market execution through asset-as-a-service contracting rather than outright sales displaces capital-constrained processors from incumbent distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among third-party pooling operators with integrated tracking and regulatory documentation capabilities. Long-term viability across the projection horizon rests on regulatory density expansion rather than cyclical volume growth. Acquisition targets should display dense geographic reconditioning footprints with validated sterilization protocols. The signal to watch is MEE environmental regulation enforcement tightening in Chinese chemical parks, which would force container standardization toward reusable formats and accelerate pooling model penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New wash-and-refurbishment facilities in Louisiana and Texas support continuous Gulf Coast petrochemical production schedules. |
| Backward Integration | In-house HDPE resin compounding secures formulation control against naphtha cracking feedstock volatility. |
| Long-term Supply Agreement | Multi-year steel cage offtake contracts with German smelting operations hedge galvanized tubular input cost exposure. |
| Joint Venture | Pooling-network partnerships with Yangtze River Delta chemical parks accelerate third-party fleet deployment. |
| Geographic Expansion | Reconditioning infrastructure buildout in Gujarat and Maharashtra addresses Indian specialty chemical export demand. |
Research Methodology
A standing panel of plant managers at integrated chemical parks, procurement leads at downstream pharmaceutical contract manufacturers, distribution channel partners in third-party pooling networks, and technical R&D directors in polymer formulation provided ongoing calibration. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA chemical containment regulation filings. Bottom-up container shipment tracking and top-down chemical industry production capacity analysis enabled triangulation across modeling approaches.
Scenario-bracketing framed analytical development across the analysis window, with segmentation dimensions covering material technology, capacity tier, application category, and end-user ownership model. CAGRs derived from installed base replacement cycles, pooling-network penetration trajectories, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated REACH substance restriction evaluations and UN dangerous goods classification revisions.
Macroeconomic conditions sit as an overlay; deviation in energy-intensive smelting input costs and naphtha cracking economics would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and reconditioning infrastructure buildout rates. Material shifts in ECHA phthalate plasticizer restrictions or MEE hazardous waste transport enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.