
 Global Low Temperature Powder Coatings Market | 2026-2036
Global Low Temperature Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Temperature Powder Coatings Market Intelligence
Multi-source resin procurement is pivoting toward captive supply partnerships as formulators seek stability in polyester and epoxy feedstock access. Akzo Nobel N.V. leverages its integrated pigment operations to secure margin control across architectural aluminum lines. PPG Industries Inc. anchors North American distribution through direct service models with metal fabricators. Axalta Coating Systems differentiates via thermal-curable technology leadership in electrical component applications.
Low temperature powder coatings are thermosetting polymer systems formulated to crosslink below 150°C, enabling protective finishes on heat-sensitive metals, plastics, and assembled components without substrate warping or adhesive failure. The technology eliminates solvent emissions through 100% solid-content application, serving industries where energy reduction and VOC compliance are operational priorities. Polyester resins dominate volume in architectural and furniture segments where exterior durability commands premium positioning, while epoxy-polyester hybrids capture expanding share in electrical components requiring balanced chemical resistance and dielectric stability. UV-curable formulations represent the fastest-growing technology category as appliance producers in East Asia adopt line-speed acceleration protocols.
EPA air quality standards in the United States restrict hazardous air pollutant emissions from coating operations, compelling metal fabricators to convert liquid spray booths to powder recovery systems. REACH registration requirements in the European Union govern isocyanate and heavy-metal content in curing agents, directly influencing formulation R&D priorities at ECHA-registered suppliers. China's MEE enforces GB standards on industrial VOC discharge limits, tightening compliance windows for solvent-free technology adoption across manufacturing provinces. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification costs and reformulation timelines that will reshape competitive access.
Market Dynamics
REACH restrictions on volatile organic compounds across the European Union are forcing solvent-free powder formulations into automotive component manufacturing in Germany and China, while captive resin partnerships consolidate supply security for formulators.
Growth Catalysts
- Automotive Heat-Sensitive Substrate Protection:Component manufacturers in Germany and China are expanding adoption of low-temperature curing systems to coat assembled electronics and plastic-composite parts without thermal degradation.
- REACH VOC Restrictions:The European Union's regulatory framework on volatile organic compound emissions is accelerating conversion from liquid solvent coatings to 100% solid-content powder systems across metal fabrication.
- UV-Curable Line Speeds:Appliance producers in East Asian manufacturing clusters around Shanghai and Guangzhou are adopting ultraviolet-accelerated curing protocols to compress coating cycle times.
Market Restraints
- Specialized Resin Supply Concentration:Polyester and epoxy feedstock access depends on a limited number of petrochemical suppliers concentrated in East Asia and the Middle East, creating vulnerability to regional production disruptions.
- Curing Agent Regulatory Friction:ECHA registration requirements governing isocyanate content in curing agents impose extended reformulation timelines and certification costs on European formulators.
- Substrate Compatibility Limitations:Low-temperature powder coatings face technical constraints in achieving adhesion on certain engineered plastics and multi-material assemblies, restricting application breadth.
Strategic Opportunities
- India Manufacturing Infrastructure:Underpenetrated coating capacity in Indian automotive and appliance production clusters presents expansion potential as domestic OEMs localize component supply chains.
- Electrical Component Dielectric Applications:Epoxy-polyester hybrid formulations are capturing share in electrical insulation markets where balanced chemical resistance and dielectric stability command premium positioning.
- China MEE VOC Enforcement:China's Ministry of Ecology and Environment tightening of GB standards on industrial VOC discharge limits is mandating solvent-free technology adoption across manufacturing provinces.
Industry Challenges
- Formulation Chemistry Expertise Gap:Shortage of chemists skilled in UV-curable and hybrid resin crosslinking mechanisms is constraining R&D throughput at mid-tier coating houses.
- Legacy Liquid Spray Booth Conversion:Metal fabricators face capital intensity in converting solvent-based spray operations to powder recovery systems with electrostatic application infrastructure.
- Multi-Jurisdiction Certification Complexity:Divergent compliance windows between EPA air quality standards, REACH registration requirements, and China's GB standards force parallel certification tracks for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Temperature Powder Coatings Market |
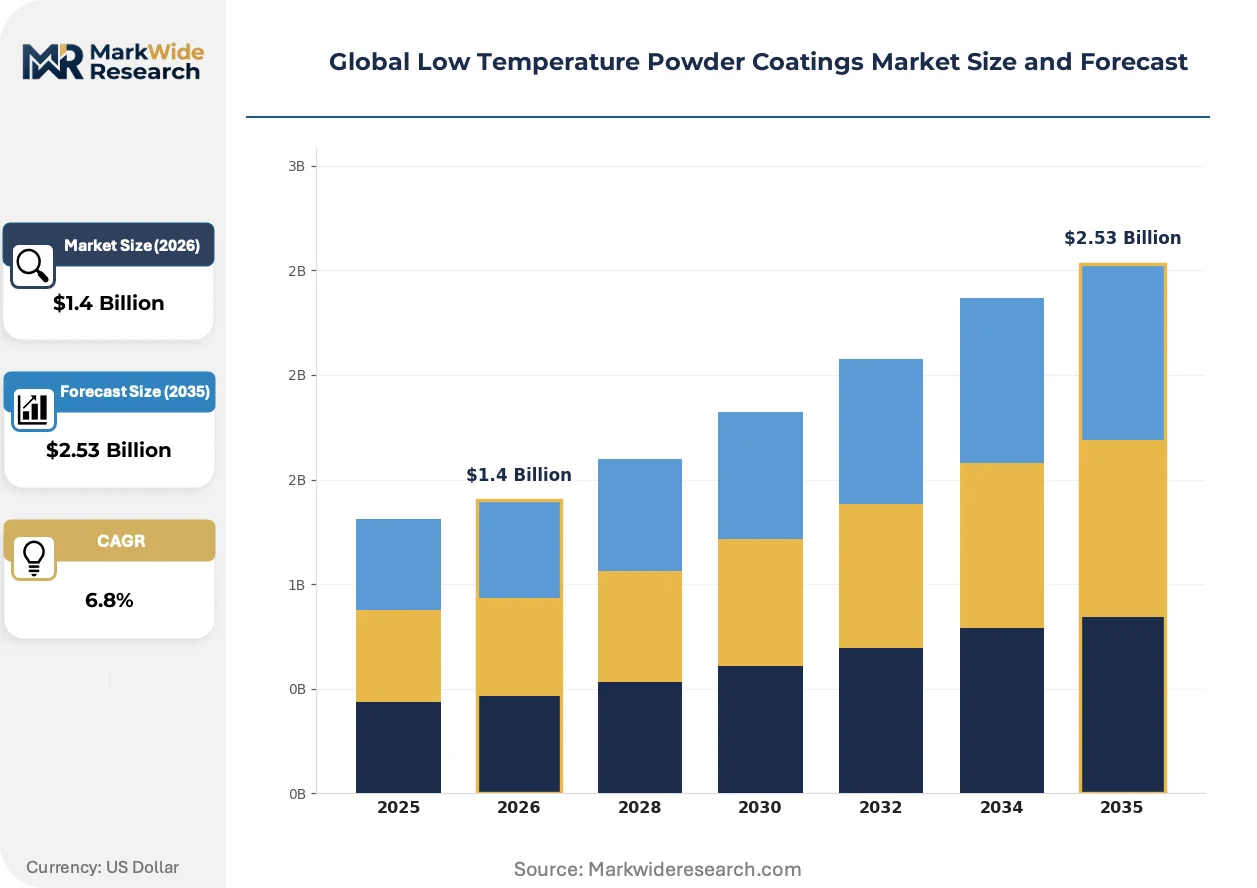
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Epoxy-Polyester Hybrid, Acrylic, Fluoropolymer Technology: Curing Agents, Thermal-Curable, UV-Curable, Infrared-Curable, Solvent-Free Application: HVAC Equipment, Metal Furniture, Architectural Aluminum, Electrical Components, Household Appliances End User: Metal Fabricators, Electrical Manufacturers, Furniture Makers, Appliance Producers |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., Axalta Coating Systems, The Sherwin-Williams Company, Jotun Group, TIGER Coatings GmbH & Co. KG, IGP Powder Coatings, Teknos Group, Protech Powder Coatings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Temperature Powder Coatings Market Strategic Shifts & Innovations
Active reformulation toward energy-reduction targets and regulatory compliance is compressing curing temperature thresholds while accelerating line-speed capabilities across automotive and appliance production.
UV-curable powder coating technology is overtaking thermal-curable systems in East Asian appliance manufacturing. This technology enables crosslinking through photoinitiator activation rather than conventional heat exposure, allowing substrate temperatures below 120°C. Appliance producers in Shanghai and Guangzhou manufacturing clusters are adopting these systems to protect heat-sensitive electronics and plastic inserts while achieving line speeds incompatible with traditional oven curing. UV-curable formulations are overtaking thermal systems as the default specification for high-volume consumer goods production.
China's Ministry of Ecology and Environment enforcement of GB standards on industrial VOC discharge limits is mandating solvent-free coating adoption across manufacturing provinces. The regulatory framework imposes tightening compliance windows on metal fabricators and component suppliers, compelling capital investment in powder recovery infrastructure. Appliance and electronics producers in Guangdong and Jiangsu provinces are responding with accelerated conversion timelines, prioritizing low-temperature powder systems that eliminate solvent emissions while reducing energy consumption.
Buyer consolidation among automotive tier-one suppliers is compressing qualification cycles and standardizing coating specifications across multi-faculty supply networks. Procurement teams at German and Chinese component manufacturers are consolidating approved vendor lists, favoring formulators with integrated pigment operations and captive resin supply. Direct service models are displacing distributor-mediated relationships in North American metal fabrication, while East Asian manufacturing clusters retain specialized coating infrastructure through regional chemical partnerships.
Global Low Temperature Powder Coatings Market Segmentation
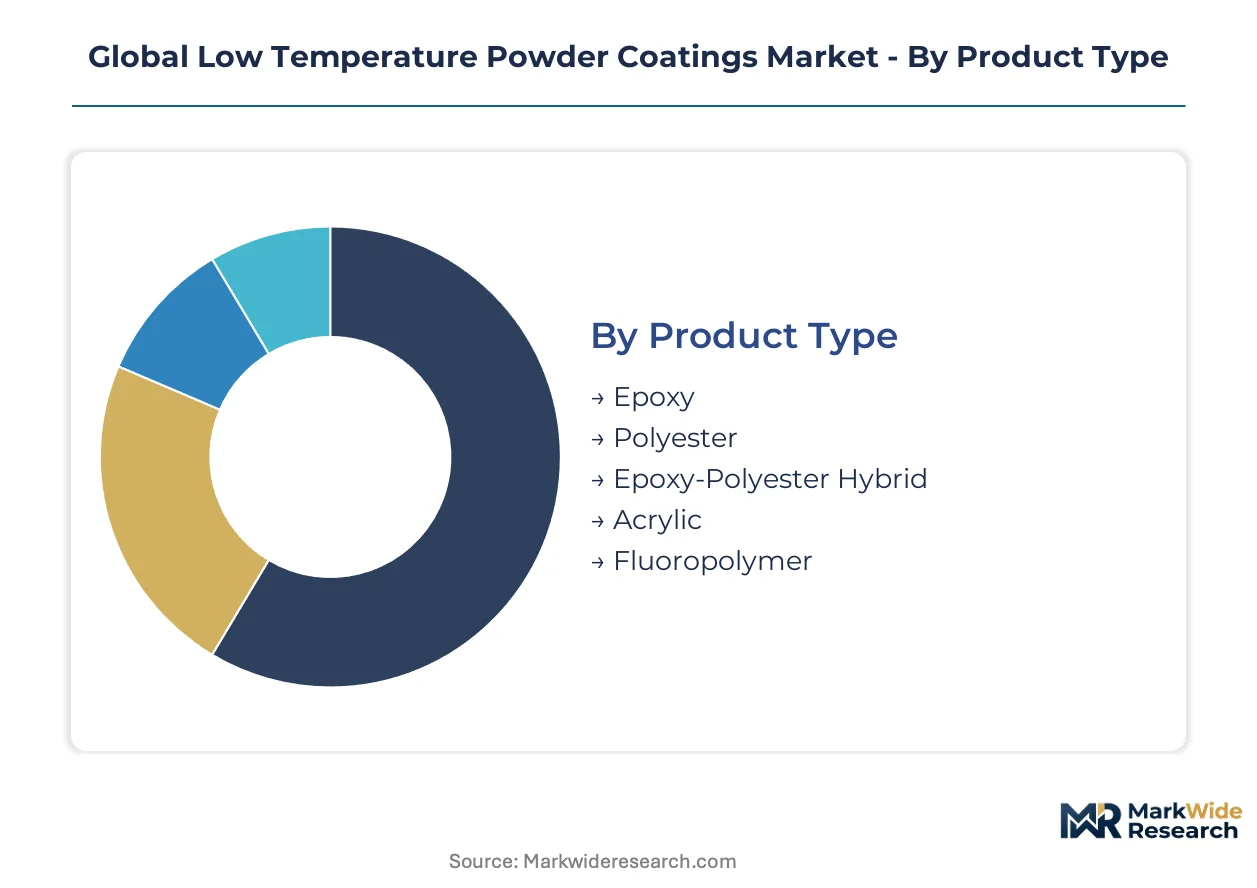
Segmentation in low temperature powder coatings reveals distinct technical and commercial boundaries. Resin chemistry determines substrate compatibility and curing thresholds. Application-specific formulations command divergent pricing and supply chain configurations across manufacturing verticals.
Product Type:
Standalone resin systems dominate volume in protective coating lines, while hybrid formulations embed into multi-substrate assembly processes requiring adhesion flexibility.
- Epoxy:Thermosetting polymer delivering superior chemical resistance and dielectric properties through dense crosslink density. Electrical manufacturers in Germany specify epoxy systems for transformer housings and switchgear components where insulation integrity withstands aggressive industrial environments.
- Polyester:Saturated resin backbone engineered for exterior durability and UV stability in architectural applications. Metal fabricators across Guangdong province deploy polyester powders on aluminum extrusions for building facades, balancing weathering performance against cost efficiency under tightening MEE VOC enforcement.
- Epoxy-Polyester Hybrid:Combines chemical resistance with mechanical flexibility for general industrial finishes.
- Acrylic:Delivers high-gloss decorative surfaces with excellent color retention for premium furniture segments.
- Fluoropolymer:Ultra-weatherable coating for extreme exposure environments requiring decades-long service life.
Volume placements concentrate in Polyester; the faster expansion belongs to Epoxy-Polyester Hybrid.
Technology:
Cost tiers separate thermal infrastructure investments from premium UV-capable line upgrades, with solvent-free formulations anchoring regulatory compliance positioning.
- Curing Agents:Chemical hardeners including blocked isocyanates and amine-functional compounds that activate crosslinking at reduced temperatures. Formulators in the European Union navigate ECHA registration requirements for isocyanate content, extending reformulation timelines while securing REACH-compliant supply.
- UV-Curable:Photoinitiator-activated systems enabling substrate temperatures below 120°C through ultraviolet radiation crosslinking. Appliance producers in Shanghai manufacturing clusters adopt UV protocols to protect heat-sensitive electronics while compressing coating cycle times incompatible with conventional oven curing.
- Thermal-Curable:Conventional heat-activated crosslinking requiring specialized oven infrastructure.
- Infrared-Curable:Targeted wavelength heating for rapid surface curing on complex geometries.
- Solvent-Free:100% solid-content formulations eliminating VOC emissions entirely.
Capital deployment clusters in Thermal-Curable; the steepest expansion trajectory runs through UV-Curable.
Application:
Application segments align with customer technical sophistication and batch size economics, from mass-produced consumer goods to custom architectural specifications.
- Household Appliances:Protective and decorative finishes for refrigerators, washing machines, and cooking equipment requiring scratch resistance and thermal stability. East Asian producers around Guangzhou integrate low-temperature powders to coat assembled units containing plastic inserts and electronic modules without warping.
- Electrical Components:Insulating coatings for motors, transformers, and circuit housings demanding dielectric strength. German automotive tier-one suppliers specify epoxy-based low-temperature systems for battery enclosures and power electronics where thermal management limits curing temperatures.
- HVAC Equipment:Corrosion-resistant finishes for heating and cooling system housings.
- Metal Furniture:Decorative and protective coatings for office and residential furniture frames.
- Architectural Aluminum:Exterior-grade finishes for building curtain walls and window systems.
Shipment volumes anchor in Household Appliances; Electrical Components gain share fastest.
End User:
Customer type determines procurement sophistication, with integrated manufacturers commanding captive formulation partnerships versus merchant market distributors.
- Metal Fabricators:Custom coating operations serving construction, industrial equipment, and transportation OEMs with batch-process flexibility. North American fabricators convert legacy liquid spray booths to powder recovery systems under EPA air quality standards, prioritizing low-temperature formulations to expand substrate compatibility.
- Appliance Producers:High-volume manufacturers with continuous coating lines and stringent color consistency requirements. Chinese producers in Jiangsu province mandate solvent-free technology adoption under MEE GB standards, consolidating approved vendor lists around formulators with captive resin supply.
- Electrical Manufacturers:Insulation-focused coating consumers with dielectric performance specifications.
- Furniture Makers:Decorative finish buyers emphasizing aesthetic consistency and scratch resistance.
Procurement scale concentrates in Appliance Producers; the most rapid capacity expansion sits with Electrical Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock concentration in East Asia and the Middle East anchors resin supply for low temperature powder coatings, while automotive and appliance manufacturing clusters in Germany, China, and the United States drive formulation demand.
Germany
Automotive tier-one suppliers in Stuttgart and Munich specify epoxy-based low temperature systems for battery enclosures and power electronics. REACH registration requirements at ECHA govern isocyanate content in curing agents, extending reformulation timelines for local formulators. Bavarian metal fabricators convert legacy liquid spray booths to powder recovery systems under tightening VOC enforcement.
China
Appliance producers in Shanghai and Guangzhou manufacturing clusters adopt UV-curable protocols to compress coating cycle times. MEE enforcement of GB standards on industrial VOC discharge limits mandates solvent-free technology adoption across Jiangsu and Guangdong provinces. Yangtze River Delta coating houses consolidate approved vendor lists around formulators with captive resin supply partnerships.
United States
Metal fabricators in Michigan and Ohio expand substrate compatibility through low temperature formulations. EPA air quality standards restrict hazardous air pollutant emissions from coating operations, compelling conversion to powder recovery systems. Southeast automotive suppliers around Tennessee and South Carolina qualify low temperature systems for plastic-composite component finishing.
India
Domestic OEMs in Maharashtra and Tamil Nadu localize component supply chains, creating coating capacity expansion potential. BIS standards govern industrial chemical formulations, establishing compliance baselines for imported resin systems. Gujarat petrochemical corridors develop downstream polyester and epoxy production to reduce import dependency.
Global Low Temperature Powder Coatings Market Key Industry Players
Global majors compete with regional champions across resin supply integration and application-specific formulation depth. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive pigment operations, mid-scale specialists in thermal-curable and UV-accelerated technologies, and regional coating houses serving localized metal fabrication networks. Dominant competitive moves include backward integration into polyester and epoxy feedstock production, plus direct service model deployment to displace distributor relationships.
Within the integrated chemical tier, Akzo Nobel N.V. and PPG Industries Inc. represent archetypes of pigment-integrated margin control, while Axalta Coating Systems exemplifies technology leadership positioning in electrical component applications. Dutch and American conglomerates anchor architectural aluminum and automotive lines through direct service infrastructure. German specialists including TIGER Coatings GmbH & Co. KG occupy positions in premium industrial finishes, reflecting European precision manufacturing heritage. Nordic and Swiss coating houses sit within the mid-tier specialist segment, serving regional appliance and furniture producers with customized formulation capabilities.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Jotun Group |
| TIGER Coatings GmbH & Co. KG |
| IGP Powder Coatings |
| Teknos Group |
| Protech Powder Coatings Inc. |
| Others |
Cost & Logistics Intelligence
Automotive tier-one supplier consolidation around approved vendor lists in Germany and China is compressing procurement cycles and mandating captive resin partnerships, forcing formulators to absorb qualification costs and compress margin structures across specification tiers.
Pricing Analysis
Warranty-backed technical service bundling separates premium formulators from commodity suppliers in low temperature powder coatings, with Akzo Nobel and PPG commanding 15-20% price premiums for on-site color matching and application troubleshooting. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with REACH-registered and EPA-compliant formulations occupying the top tier. Cost compression in economy-grade polyester systems is intensifying because Chinese MEE enforcement is flooding compliant capacity into export markets. Appliance producers in Jiangsu province exhibit highest price sensitivity, while German electrical manufacturers prioritize dielectric performance over unit cost.
Supply Chain Analysis
REACH and EPA certification gating restricts qualified supplier pools to ECHA-registered and EPA-permitted formulators, creating procurement friction for buyers seeking dual-jurisdiction compliance. Resin feedstock concentration centers on China, South Korea, and Saudi Arabia for polyester and epoxy precursors, with formulation houses drawing from petrochemical corridors in the Yangtze River Delta and Jubail Industrial City. Single-source vulnerability runs through blocked isocyanate curing agents produced at three European facilities. Distribution runs through direct service teams for automotive and appliance accounts, while metal fabricators access materials via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low temperature powder coatings market is becoming a backward-integration race, with formulators pursuing captive polyester resin production to secure margin control as petrochemical feedstock volatility intensifies.
For Market Incumbents: Extend pigment-integration advantages into architectural aluminum lines by qualifying proprietary color systems with German fabricators facing REACH compliance deadlines. Lock in five-year resin supply agreements with Yangtze River Delta producers before MEE enforcement tightens feedstock export windows. Defend against UV-curable specialists by accelerating photoinitiator formulation partnerships with Shanghai appliance clusters. For New Entrants and Emerging Players: Begin with electrical component dielectric applications in India, where BIS standardization is creating first-mover certification advantages for epoxy-polyester hybrid suppliers. Target Maharashtra automotive OEMs localizing battery enclosure coating capacity. Establish technical service partnerships with Gujarat petrochemical corridors developing downstream resin production to reduce import dependency. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale UV-curable specialists given East Asian appliance line-speed acceleration protocols. Long-term viability favors formulators with demonstrated ECHA registration track records and captive supply partnerships spanning the analysis window. Watch for MEE enforcement intensity in Guangdong province as the inflection signal for Chinese capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyester supply secures margin control for Akzo Nobel against feedstock volatility. |
| UV-Curable Line Conversion | Photoinitiator-activated systems enable Shanghai appliance producers to compress coating cycle times. |
| REACH-Compliant Curing Agent Reformulation | ECHA-registered isocyanate alternatives open German automotive qualification pathways. |
| Direct Service Model Deployment | On-site technical support displaces distributor relationships with Michigan metal fabricators. |
| India Manufacturing Infrastructure Partnership | Maharashtra OEM localization creates coating capacity expansion potential for early entrants. |
Research Approach
Multi-period observation of MEE enforcement intensity, REACH registration timelines, and UV-curable line adoption rates anchored the trend analysis, supplemented by interviews with coating R&D directors, automotive tier-one procurement leads, appliance production engineers, and regional chemical distributors. Secondary validation drew from EPA air quality enforcement databases, ECHA registration dossiers, Chinese customs trade statistics, and SEC 10-K filings of listed coating manufacturers. Bottom-up volume estimates triangulated against top-down petrochemical feedstock consumption data.
The input-output matrix framed demand-side projections through resin chemistry segmentation, curing technology tiers, and end-use application intensity across automotive, appliance, and electrical manufacturing verticals. CAGRs were derived from regression analysis of historical adoption curves and regulatory compliance deadlines. Key forecast inputs included MEE GB standard implementation schedules and German automotive platform electrification timelines.
Feedstock price volatility, regulatory enforcement intensity divergence, and substrate compatibility breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding ECHA registration completion rates and Chinese provincial MEE inspection schedules. A model refresh is warranted upon material change in REACH candidate list expansion or MEE VOC discharge limit tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Clear Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Carpet Back Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Can Coatings Market
Coatings
Glazes Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Bio-Fouling Prevention Coatings Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Heavy Duty Glass Coating Market