
 Cardiovascular Disease Drugs Market | 2026-2036
Cardiovascular Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Disease Drugs Market Analysis
The cardiovascular disease drugs market is pivoting on a widening divergence between premium biologic therapies and commoditized small-molecule generics. Pfizer leverages its manufacturing scale to dominate injectable anticoagulant supply chains. Bristol-Myers Squibb anchors its position through deep specialization in antiplatelet innovation. AstraZeneca competes aggressively in the SGLT2 inhibitor expansion beyond diabetes into heart failure indications.
Cardiovascular disease drugs comprise pharmacological agents targeting hypertension, thrombosis, dyslipidemia, and heart failure through mechanisms including ACE inhibition, platelet aggregation blockade, and HMG-CoA reductase suppression, with formulations ranging from immediate-release tablets to long-acting transdermal patches designed for sustained plasma concentration. Antihypertensives and statins represent mature, high-volume segments where margin pools have compressed under generic erosion. Injectable biologics and novel antiplatelets constitute the fastest-expanding drug classes, commanding premium pricing through demonstrated mortality benefit in acute coronary syndrome protocols.
The FDA, EMA, and WHO set divergent evidentiary standards for cardiovascular outcomes trials, with FDA's breakthrough therapy designation accelerating market access while EMA's MDR-aligned pharmacovigilance demands reshape post-approval commitment structures. China's NMPA now requires domestic cardiovascular trial data for novel anticoagulant approvals, fragmenting global development strategies. Stakeholders must monitor how CMS's evolving coverage with evidence determination framework will reshape reimbursement for emerging PCSK9 inhibitors and siRNA therapeutics.
Market Dynamics
The cardiovascular disease drugs market pivots on Medicare reimbursement compression for chronic therapies and the FDA's breakthrough therapy designation accelerating novel anticoagulant commercialization timelines. Hospital formulary expansion for injectable biologics is reshaping competitive positioning between premium and commoditized segments.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses development timelines for novel antiplatelet agents, enabling faster market entry for mortality-benefit therapies in acute coronary syndrome protocols.
- SGLT2 Inhibitor Label Expansion:Cardiologists now prescribe diabetes-origin molecules for heart failure with reduced ejection fraction, creating demand pull beyond traditional antihypertensive and statin categories.
- Injectable Anticoagulant Formulary Growth:Hospital systems are expanding preferred drug lists for parenteral thrombosis prophylaxis, driven by demonstrated reductions in post-surgical venous thromboembolism events.
Market Restraints
- Generic Erosion in Small-Molecule Statins:Patent expiry for atorvastatin and rosuvastatin has collapsed pricing power in dyslipidemia, compressing margin pools available for reinvestment in cardiovascular R&D.
- EMA MDR-Aligned Pharmacovigilance:Post-approval commitment structures for novel anticoagulants now require extended real-world evidence collection, extending cost recovery periods and regulatory burden.
- Active Pharmaceutical Ingredient Concentration:Heparin sodium API supply concentrates in Chinese manufacturing clusters, exposing formulation networks to geopolitical friction and quality inspection disruptions.
Strategic Opportunities
- China NMPA Domestic Trial Mandate:Novel anticoagulant developers must generate China-specific cardiovascular outcomes data, fragmenting global development strategies but creating first-mover advantage for compliant entrants.
- siRNA Therapeutic Distribution:Infrequent-dosing RNA interference therapies for dyslipidemia enable direct-to-specialist channel models bypassing traditional retail pharmacy networks.
- CMS Coverage with Evidence Determination:Emerging frameworks for PCSK9 inhibitors create pathways for conditional reimbursement tied to real-world effectiveness monitoring.
Industry Challenges
- Cardiovascular Outcomes Trial Talent Scarcity:Recruitment of biostatisticians experienced in time-to-event analysis for mortality endpoint studies lags demand from competing therapeutic areas.
- Legacy EHR Integration Complexity:Hospital systems struggle to embed anticoagulation dosing algorithms into Cerner and Epic workflows, delaying clinical decision support deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Disease Drugs Market |
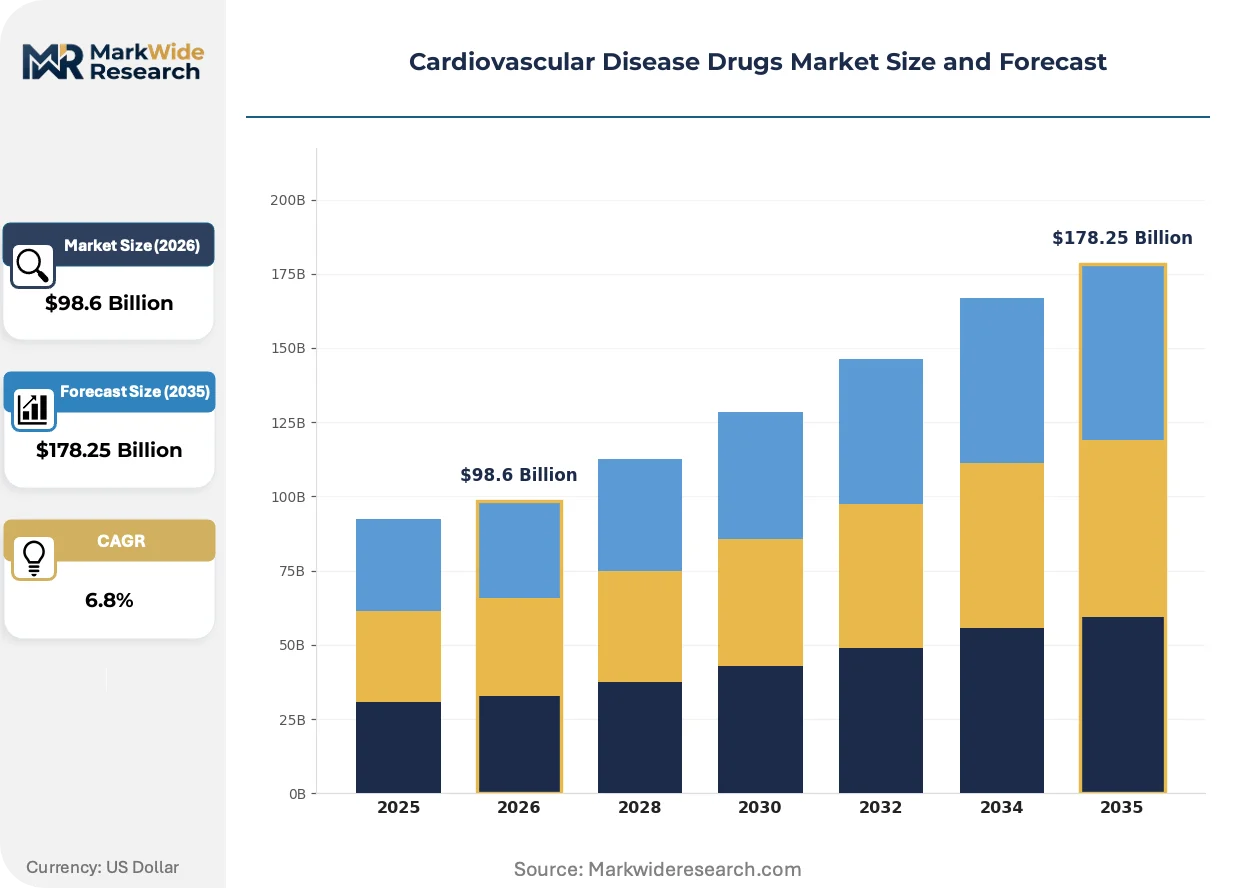
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Antihypertensives, Antiplatelets, Statins, Beta-blockers Administration Route: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare, Pharmacies Formulation Type: Tablet, Capsule, Solution, Patch |
| Companies Covered | Bristol-Myers Squibb, Eli Lilly and Company, AstraZeneca, Pfizer, Novartis, Bayer, Daiichi Sankyo, Sanofi, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Disease Drugs Market Emerging Trajectories
RNA-based therapeutics and digital biomarker integration are compressing development timelines while fragmenting traditional prescriber-pharmaceutical relationships. These shifts favor developers with specialized manufacturing capabilities and real-world evidence infrastructure.
siRNA therapeutics targeting PCSK9 is unifying cholesterol management through twice-yearly dosing protocols that eliminate adherence gaps inherent in daily statin regimens. Specialty pharmacy networks are adopting these molecules for high-risk familial hypercholesterolemia patients. The technology is unifying pricing power around outcomes-based contracts rather than pill-volume metrics.
REACH regulation in Europe is tightening evidentiary requirements for cardiovascular device-drug combination products, forcing manufacturers to generate additional toxicology data for transdermal delivery systems. The industrial consequence extends development timelines for patch-based antihypertensives by 18-24 months. German and French regulators are now requiring separate MDR compliance documentation for drug-eluting stent coatings.
Hospital procurement committees are consolidating anticoagulant purchasing through single-source contracts tied to total cost of care metrics rather than unit price. Integrated delivery networks in Texas and Florida are displacing traditional wholesaler relationships with direct manufacturer agreements. This concentration is most visible in Medicare Advantage–dominated markets where capitated reimbursement aligns formulary decisions with readmission risk.
Cardiovascular Disease Drugs Market Segmentation
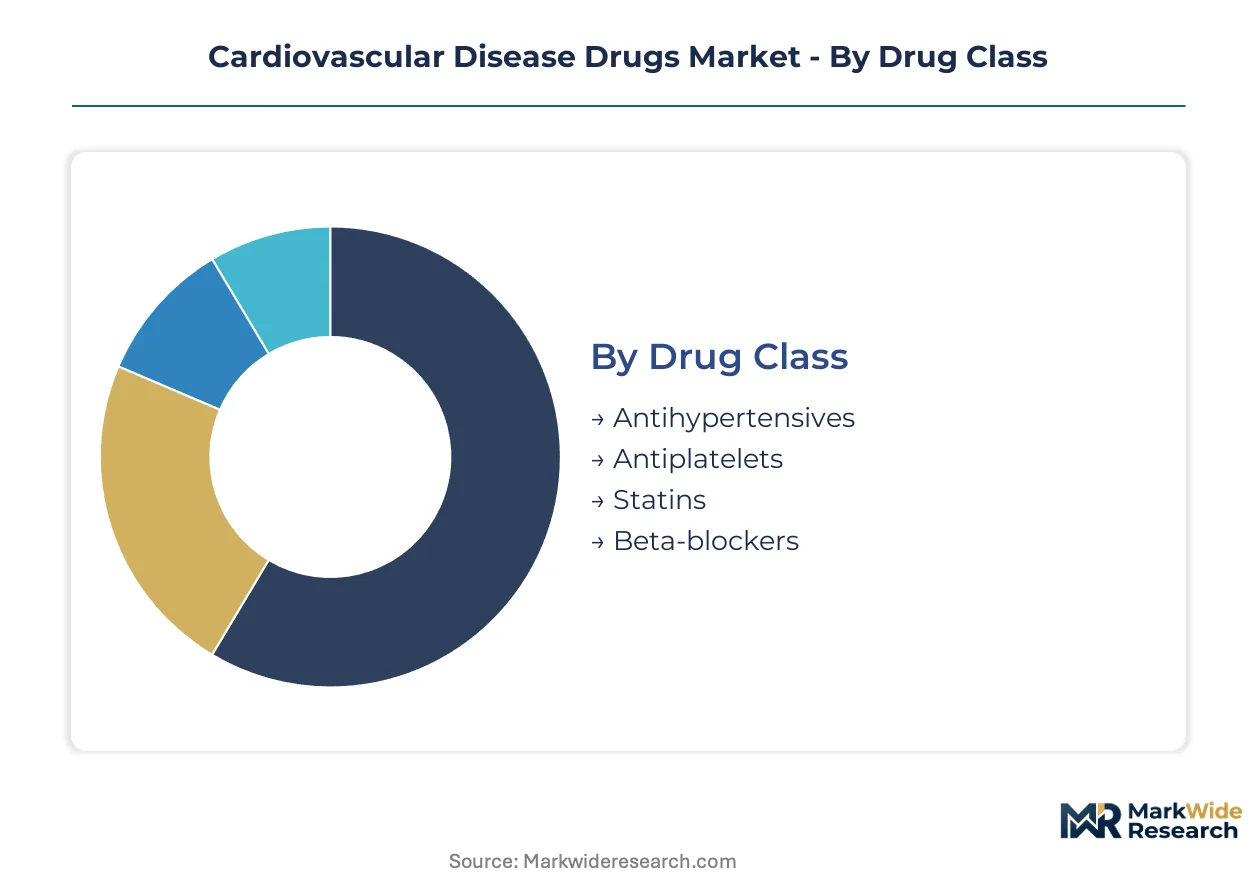
Cardiovascular disease drugs fragment across four structural dimensions that determine prescribing economics. Drug class and administration route dominate hospital formulary negotiations, while end-user channel and formulation type shape reimbursement pathways and patient adherence profiles.
Drug Class:
Pricing power concentrates in molecules demonstrating mortality benefit in acute coronary syndrome protocols.
- Antihypertensives:ACE inhibitors and ARBs constitute high-volume maintenance therapy with compressed margins under generic saturation. Demand clusters in Medicare Advantage plans where capitated reimbursement ties formulary placement to readmission risk reduction.
- Antiplatelets:P2Y12 inhibitors and aspirin combinations command premium pricing through demonstrated stent thrombosis prevention. Hospital procurement committees in Texas and Florida consolidate purchasing through single-source contracts tied to total cost of care metrics.
- Statins:HMG-CoA reductase inhibitors face collapsed pricing power following atorvastatin and rosuvastatin patent expiry.
- Beta-blockers:Post-myocardial infarction protocols sustain volume despite generic erosion across carvedilol and metoprolol formulations.
Antihypertensives lead on scale; antiplatelets lead on momentum.
Administration Route:
Hospital formulary expansion favors parenteral delivery for acute intervention settings.
- Oral:Immediate-release and extended-release tablets dominate chronic disease management through retail pharmacy distribution. Medicare Part D reimbursement structures prioritize generic substitution, compressing originator molecule persistence.
- Injectable:Subcutaneous anticoagulants reduce post-surgical venous thromboembolism events in orthopedic and cardiac surgery protocols. Integrated delivery networks negotiate direct manufacturer agreements displacing traditional wholesaler relationships.
- Intravenous:ICU and emergency department settings require rapid anticoagulation reversal capability.
- Transdermal:Patch-based delivery systems face extended development timelines under REACH regulation toxicology requirements.
Oral formulations retain volume dominance; injectable routes are gaining share fastest through hospital formulary expansion.
End User:
Reimbursement channel determines pricing architecture and clinical decision support integration requirements.
- Hospitals:Inpatient acute care settings drive injectable anticoagulant procurement through value-based purchasing metrics. Epic and Cerner EHR integration complexity delays anticoagulation dosing algorithm deployment.
- Clinics:Cardiology and internal medicine practices manage dose titration for oral heart failure therapies.
- Homecare:Infrequent-dosing siRNA therapeutics enable direct-to-specialist channel models bypassing retail pharmacy networks.
- Pharmacies:Specialty pharmacy networks adopt PCSK9 inhibitors for familial hypercholesterolemia patients under outcomes-based contracts.
Hospitals anchor procurement volume; homecare channels show steepest expansion trajectory through RNA therapeutic distribution.
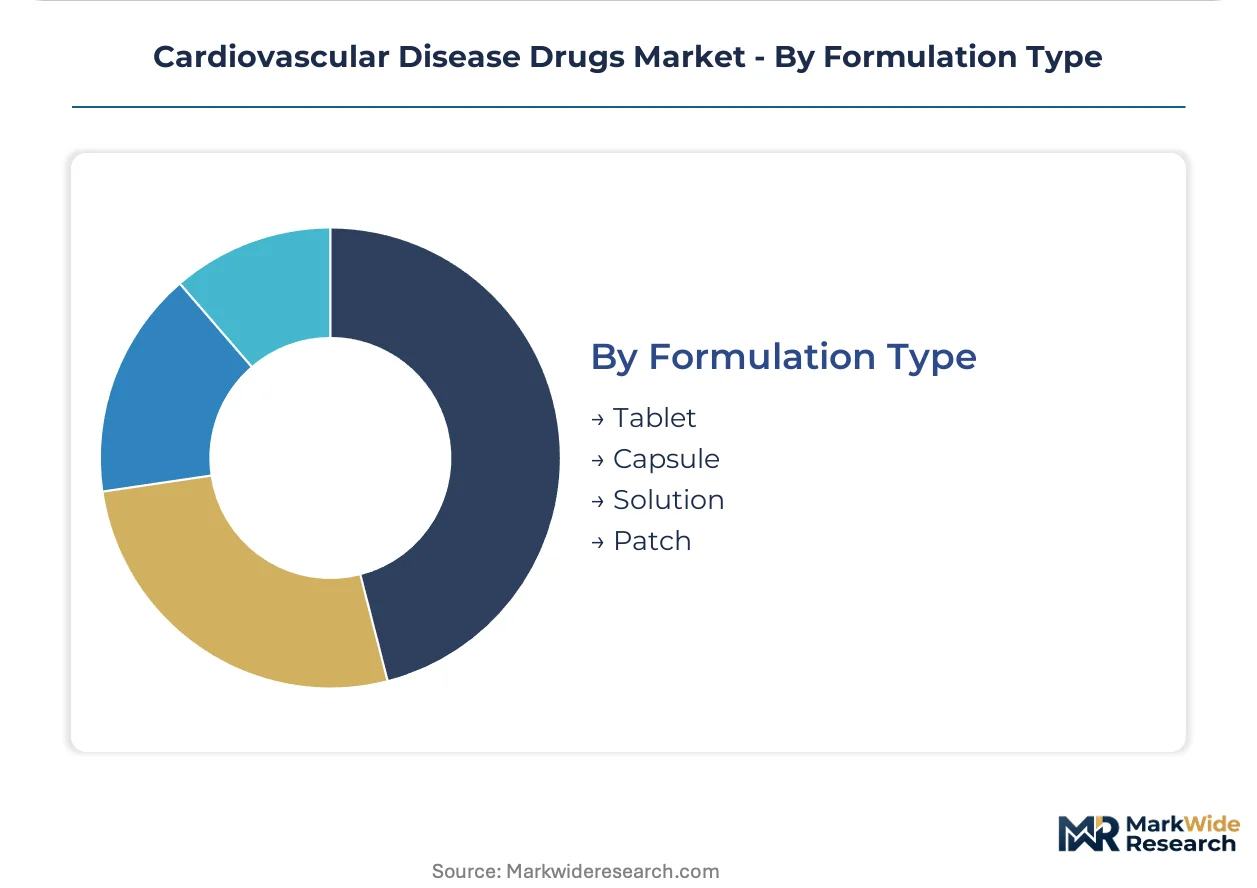
Formulation Type:
Manufacturing complexity and bioavailability requirements shape competitive moats.
- Tablet:Immediate-release and film-coated solid oral dosage forms dominate statin and antihypertensive dispensing. High-speed production lines at Pfizer manufacturing facilities supply global generic substitution demand.
- Capsule:Modified-release formulations enable 24-hour plasma concentration maintenance for beta-blocker compliance.
- Solution:Pediatric and geriatric liquid formulations address swallowing difficulty in polypharmacy populations.
- Patch:Transdermal antihypertensives require additional MDR compliance documentation for drug-eluting coating toxicology under German and French regulator frameworks.
Tablets maintain manufacturing scale leadership; patches face regulatory headwinds extending development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular clinical trial sites cluster around academic medical centers in the United States, Germany, and Japan, drawing biostatisticians and principal investigators into dense talent networks that anchor regional development gravity.
United States
Medicare Advantage capitation drives formulary consolidation for heart failure therapies at Texas Medical Center and Cleveland Clinic networks. FDA breakthrough therapy designations compress anticoagulant commercialization timelines for sponsors with mortality-benefit data. Philadelphia and Boston corridors host dense contract research organizations supporting cardiovascular outcomes trial execution.
Germany
Statutory health insurance funds negotiate reference pricing for antihypertensive generics, compressing originator persistence in ambulatory care. EMA MDR-aligned pharmacovigilance extends post-approval commitment periods for novel antiplatelets. Heidelberg and Munich academic hospitals anchor the EU's largest concentration of interventional cardiology training programs.
China
NMPA domestic trial mandates fragment global development strategies for novel oral anticoagulants seeking approval. Shanghai and Beijing bioclusters attract multinational cardiovascular R&D investment through streamlined IND review pathways. Yangtze River Delta manufacturing bases supply heparin sodium API under intensified quality inspection protocols.
Japan
PMDA sakigake designation accelerates priority review for siRNA therapeutics targeting PCSK9 in familial hypercholesterolemia. Tokyo and Osaka university hospitals maintain strict separation between inpatient injectable protocols and outpatient oral therapy management. Aging demographics expand demand for anticoagulation in atrial fibrillation stroke prevention.
Switzerland
Swissmedic parallel scientific advice harmonizes cardiovascular outcomes trial design with EMA expectations for multinational submissions. Basel and Zurich anchor European headquarters for antiplatelet and anticoagulant developers seeking regulatory efficiency. Cantonal hospital procurement committees consolidate purchasing through single-source contracts tied to total cost of care metrics.
Cardiovascular Disease Drugs Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cardiovascular therapeutics value chain. Large-scale pharmaceutical manufacturers with captive API supply and global distribution infrastructure face pressure from specialty biotech developers with RNA-based platforms and targeted cardiovascular indications. The market structure consolidates around three archetypes: diversified conglomerates with manufacturing depth, focused biopharmaceutical innovators with breakthrough therapy designations, and emerging RNA therapeutic specialists with infrequent-dosing protocols. Competitive intensity centers on M&A activity targeting siRNA and antisense platforms, alongside strategic partnerships between hospital systems and manufacturers for direct anticoagulant procurement.
Among diversified pharmaceutical conglomerates, Bristol-Myers Squibb and Pfizer exemplify archetypes with manufacturing scale and antiplatelet specialization. AstraZeneca occupies a position bridging diabetes-origin molecules into heart failure indications through SGLT2 inhibitor label expansion. These three anchors represent competitive positioning strategies spanning generic defense, biologic premiumization, and cross-indication portfolio leverage.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| AstraZeneca |
| Pfizer |
| Novartis |
| Bayer |
| Daiichi Sankyo |
| Sanofi |
| Boehringer Ingelheim |
| Others |
Supply Flow & Price Mechanics
Biostatistician talent pools concentrated in Philadelphia and Boston corridors widen pricing spreads between mortality-benefit biologics and commoditized small-molecule generics, as labor-intensive cardiovascular outcomes trials inflate development costs for premium antiplatelet therapies while Indian and Chinese API manufacturing compresses statin price floors.
Pricing Analysis
Bundled outcomes-based contracts for hospital anticoagulant procurement now separate from unbundled per-unit pharmacy reimbursement, with three-tier pricing structure across premium biologics, standard branded small molecules, and economy generics. Price differentiation hinges on FDA breakthrough therapy designation tier and Medicare Advantage capitation scale. Cost compression in the statin category intensifies because of Indian API oversupply. Medicare Part D plans exhibit highest price sensitivity; integrated delivery networks in capitated markets show lowest.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement committees now require qualified heparin sodium suppliers from both China and India to mitigate quality inspection disruption risk. Active pharmaceutical ingredient production draws from Yangtze River Delta clusters, Ahmedabad chemical corridors, and Basel captive facilities. Supply chain vulnerability centers on single-source dependence for porcine-derived heparin precursors. Distribution runs through direct manufacturer agreements with Texas and Florida integrated delivery networks displacing traditional wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
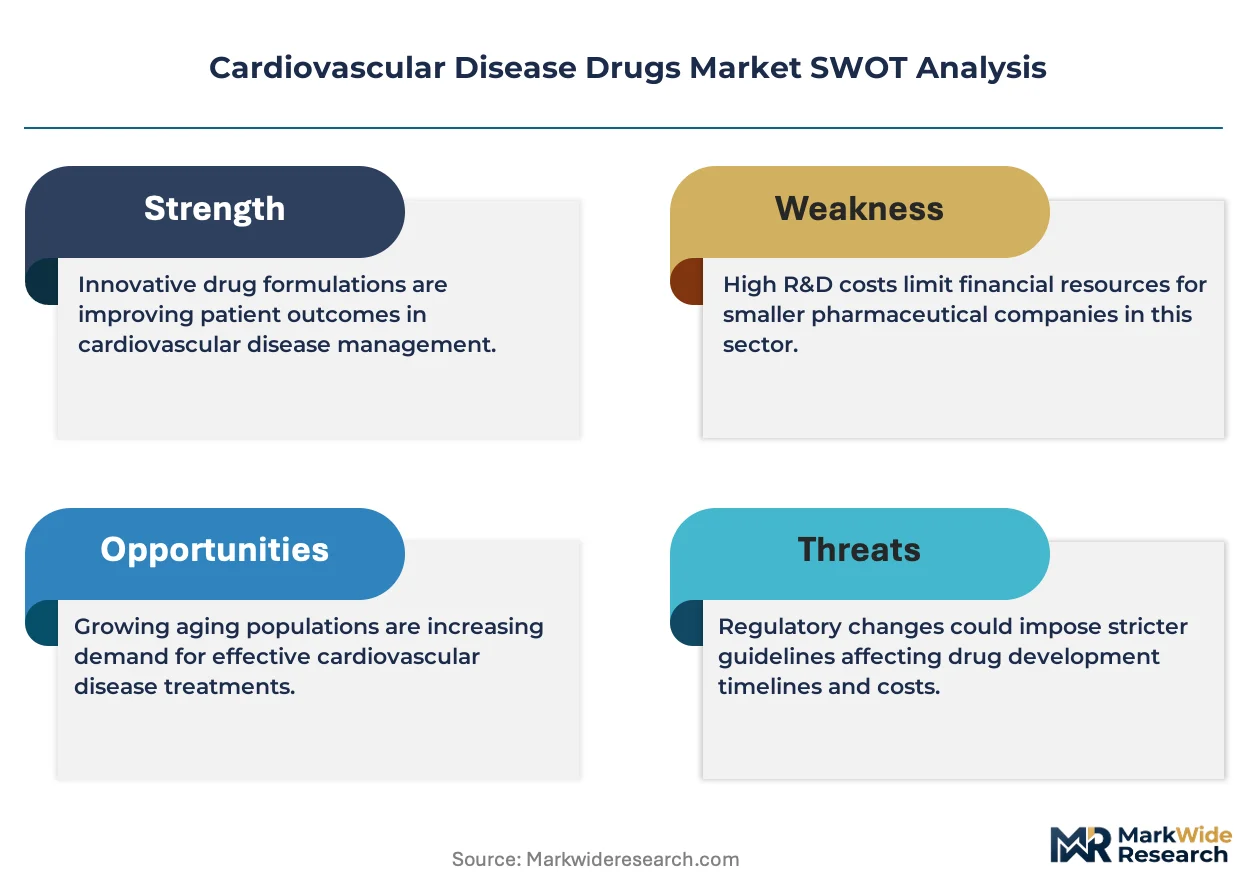
This market functions as a geographic-arbitrage play where sponsors generating China-specific cardiovascular outcomes data capture NMPA first-mover premiums unavailable to EU-centric developers, exploiting the regulatory cost differential between fragmented domestic trial mandates and centralized EMA submission pathways.
For Market Incumbents: Cement formulary lock-in through Epic and Cerner EHR integration of anticoagulation dosing algorithms, defending against RNA therapeutic entrants bypassing retail pharmacy networks. Deepen backward integration into heparin sodium API through Yangtze River Delta manufacturing partnerships to offset Chinese quality inspection volatility.
For New Entrants and Emerging Players: Specialty pharmacy networks offer the most penetrable channel for siRNA therapeutics targeting familial hypercholesterolemia, exploiting outcomes-based contract infrastructure built by PCSK9 predecessors. Penetrate Medicare Advantage-dominated markets in Texas and Florida where capitated reimbursement aligns formulary access with readmission risk reduction.
For Investors and Strategic Acquirers: Large pharmaceutical conglomerates seeking biologic premiumization are the most active acquirer in this space, particularly those lacking RNA platform capabilities. Long-term viability favors developers with infrequent-dosing protocols and real-world evidence infrastructure. Monitor CMS coverage with evidence determination framework expansion as the inflection signal for conditional reimbursement scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | China-specific cardiovascular outcomes data satisfies NMPA domestic trial mandates for novel anticoagulants. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses commercialization timelines for mortality-benefit antiplatelets. |
| Licensing Agreement | Specialty pharmacy network partnerships enable direct-to-specialist distribution of infrequent-dosing siRNA therapeutics. |
| Manufacturing Scale-Up | Captive heparin sodium API production insulates formulation networks from Chinese quality inspection disruptions. |
| Pipeline Diversification | SGLT2 inhibitor label expansion beyond diabetes into heart failure indications creates cross-therapeutic leverage. |
Methodological Framework
Bottom-up hospital formulary modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Triangulation between prescriber-level demand signals and manufacturing capacity data ensures segmentation integrity across drug class and administration route dimensions.
Historical trendline analysis of patent expiry cycles, generic erosion velocities, and biologic penetration curves informed projection framework construction across the analysis window. Segmentation modeling incorporates treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derive from reconciling volume-weighted price trajectories with patient population epidemiology shifts. Forecast inputs include Medicare Advantage penetration rates and NMPA domestic trial completion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakthrough therapy designation velocity and CMS coverage with evidence determination framework expansion. Deviation in China API quality inspection intensity or EMA MDR-aligned pharmacovigilance enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Tachycardia Market