
 Global Hyperlipidemia Drugs Market | 2026-2036
Global Hyperlipidemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyperlipidemia Drugs Market Foresight
Outcome-based reimbursement for chronic disease management is pivoting how pharmaceutical firms structure their commercial contracts with payers. Pfizer Inc. leverages its manufacturing scale to sustain supply security for high-volume statin portfolios across multiple continents. Amgen Inc. differentiates through its concentrated R&D investment in next-generation biologic therapies targeting refractory lipid disorders. Daiichi Sankyo Company Limited anchors its competitive position in Asian markets through specialized distribution partnerships with regional cardiology networks.
Hyperlipidemia drugs comprise pharmacological agents designed to modulate serum lipid profiles through inhibition of cholesterol synthesis, enhancement of bile acid excretion, or interference with PCSK9-mediated LDL receptor degradation, typically formulated as oral tablets or subcutaneous injectables with dosing frequencies ranging from daily to biweekly depending on mechanism of action. These therapeutics serve the primary commercial purpose of reducing atherosclerotic cardiovascular disease risk in patients with inherited or acquired dyslipidemias. The statin drug class dominates prescription volume globally due to decades of established clinical efficacy data and generic availability, while PCSK9 inhibitors represent the fastest-expanding margin pool as biologic pricing power persists in specialty pharmacy channels. Injectable administration routes command premium positioning against oral tablets, particularly among patients with familial hypercholesterolemia requiring aggressive LDL reduction beyond statin tolerance thresholds.
The FDA maintains stringent cardiovascular outcomes trial requirements for novel hyperlipidemia therapies seeking approval, while the EMA enforces post-authorization safety monitoring through its pharmacovigilance framework, and Japan's PMDA applies localized clinical bridging study standards that extend development timelines for Western-origin molecules. These regulatory architectures directly shape demand by determining which patient populations gain reimbursed access to advanced therapies and which manufacturers commit to region-specific evidence generation. Stakeholders must monitor evolving FDA guidance on surrogate endpoint acceptability for combination lipid-lowering therapies, as this determination will influence pipeline prioritization decisions across the industry.
Market Dynamics
Injectable PCSK9 inhibitors are compressing the therapeutic hierarchy for familial hypercholesterolemia, forcing cardiology centers to reconfigure their frontline protocols and reimbursement negotiations simultaneously.
Growth Catalysts
- Medicare reimbursement evolution:The United States Centers for Medicare & Medicaid Services is expanding coverage for preventive cardiology services, directly expanding addressable patient populations for advanced lipid-lowering therapies.
- FDA accelerated approval pathways:The FDA's streamlined cardiovascular outcomes trial requirements are compressing development timelines for novel combination therapies targeting refractory dyslipidemias.
- Cardiology center infrastructure:Specialty infusion clinics are proliferating across tertiary care networks, enabling supervised administration of biologic therapies previously confined to hospital settings.
Market Restraints
- Biologic manufacturing concentration:Single-source dependence on mammalian cell culture facilities in Switzerland and Ireland creates supply vulnerability for monoclonal antibody therapies.
- Statin generic commoditization:Atorvastatin and rosuvastatin price erosion in retail pharmacy channels is compressing manufacturer willingness to fund cardiovascular outcomes research.
- EMA pharmacovigilance burden:Post-authorization safety monitoring requirements for novel mechanisms extend commercialization timelines by 18-24 months for European market entry.
Strategic Opportunities
- Japan's PMDA bridging study pathway:Localized clinical data requirements for Western-origin molecules create first-mover advantages for firms committing to region-specific evidence generation.
- Subcutaneous auto-injector convergence:Integration of connected device technology with biologic formulations enables real-world adherence monitoring and value-based contract structuring.
- Community pharmacy lipid clinics:Retail healthcare expansion into point-of-care cholesterol testing creates direct-to-patient channels bypassing traditional specialist referral bottlenecks.
Industry Challenges
- Lipidology specialist scarcity:Fellowship-trained clinicians capable of managing complex familial hypercholesterolemia cases remain concentrated in academic medical centers, limiting protocol rollout.
- Real-world evidence integration:Electronic health record fragmentation across hospital systems complicates outcomes tracking for value-based reimbursement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyperlipidemia Drugs Market |
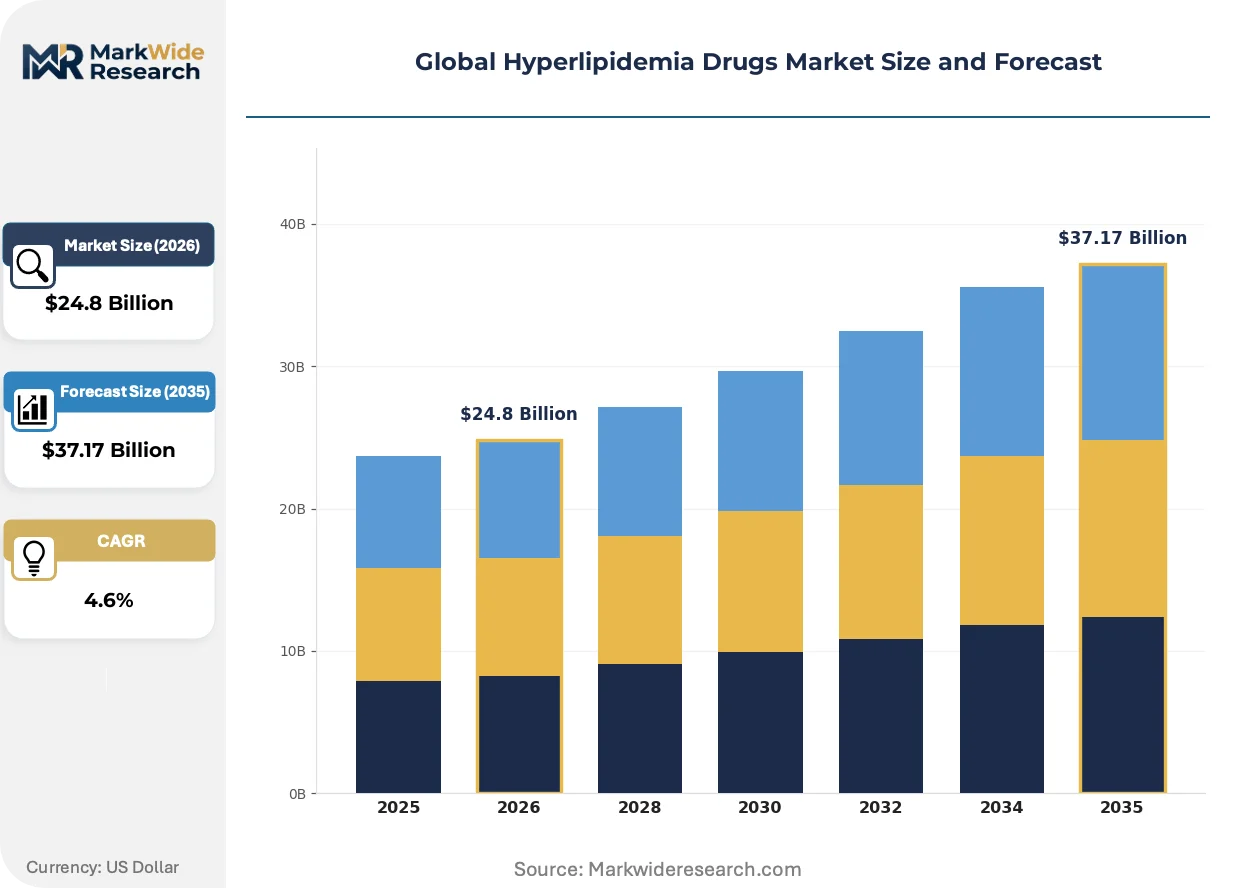
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Statins, Fibrates, Bile Acid Sequestrants, PCSK9 Inhibitors, Niacin Target Patient Group: Familial Hypercholesterolemia, Mixed Dyslipidemia, Hypertriglyceridemia, Lipoprotein Disorder Administration Route: Oral Tablets, Injectable, Sublingual, Transdermal End User: Specialty Clinics, Cardiology Centers, Research Institutes, Pharmaceutical Distributors |
| Companies Covered | AstraZeneca, Merck & Co., Inc., Pfizer Inc., Amgen Inc., Sanofi, Novartis AG, Daiichi Sankyo Company Limited, Viatris Inc., GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyperlipidemia Drugs Market Shifts & Advancements
Gene silencing technologies and oral small-molecule PCSK9 inhibitors are disrupting the injectable biologic paradigm, while regulatory agencies recalibrate evidence standards for combination therapies.
RNA interference therapeutics targeting PCSK9 synthesis is integrating into phase III development pipelines as a once-annual dosing alternative to monoclonal antibody maintenance regimens. Cardiology centers in the United States and Germany are prioritizing these candidates for patient populations with demonstrated adherence failures on biweekly injection schedules. The technology is integrating long-acting depot formulations that compress pharmacy benefit management complexity while extending protected revenue periods.
The FDA's draft guidance on surrogate endpoint acceptability for fixed-dose combination lipid-lowering therapies is reshaping clinical trial design priorities across the industry. Manufacturers must now demonstrate incremental cardiovascular risk reduction beyond statin monotherapy rather than relying solely on LDL-C percentage changes. Specialty pharmaceutical firms with existing cardiovascular outcomes infrastructure are responding by pooling trial data across multiple dyslipidemia indications to satisfy evidentiary thresholds.
Hospital procurement committees are consolidating formularies around outcomes-guarantee contracts that tie reimbursement to patient-level LDL target achievement. This displaces traditional volume-based purchasing agreements in integrated delivery networks spanning the United States. The shift is most visible in Medicare Advantage populations, where risk-bearing physician organizations bear direct financial exposure for preventable cardiovascular events.
Global Hyperlipidemia Drugs Market Segmentation
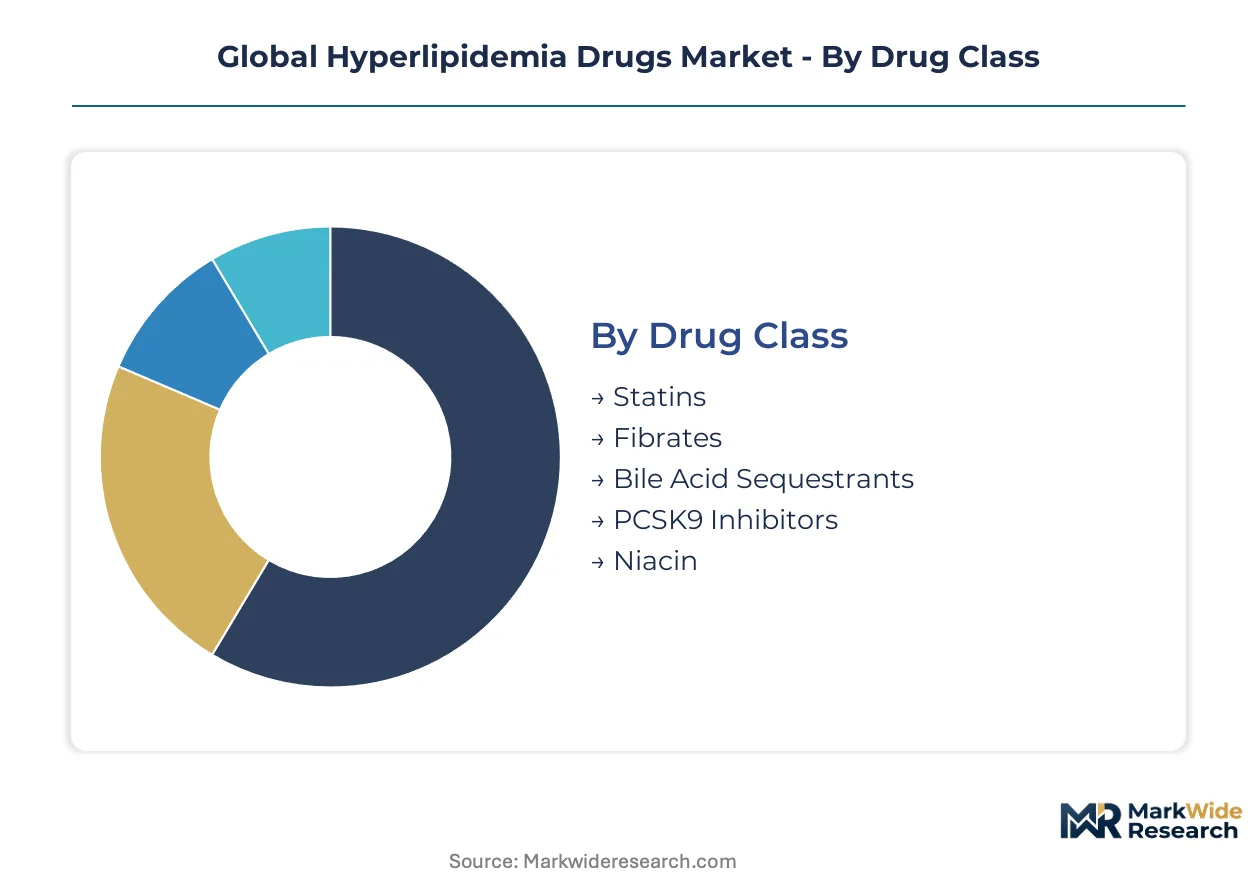
Hyperlipidemia drug segmentation reveals how capital allocation, patient complexity, and reimbursement pathways fragment commercial opportunity across distinct therapeutic modalities. Manufacturers must align R&D investment with the specific evidence requirements and margin structures governing each category.
Drug Class:
Capital intensity varies sharply across mechanisms, with biologic manufacturing demanding substantially higher upfront facility investment than small-molecule synthesis.
- Statins:Oral HMG-CoA reductase inhibitors remain the volume foundation of global prescription activity. Demand concentrates in primary care networks across the United States and Germany, where generic atorvastatin and rosuvastatin dominate maintenance therapy for secondary cardiovascular prevention.
- PCSK9 Inhibitors:Monoclonal antibodies and emerging RNA interference therapeutics target refractory familial hypercholesterolemia. Cardiology centers in Switzerland and the United States absorb the majority of injectable volume, driven by LDL reduction requirements beyond statin tolerance thresholds.
- Fibrates:Peroxisome proliferator-activated receptor agonists address hypertriglyceridemia through distinct metabolic pathways.
- Bile Acid Sequestrants:Resin-based cholesterol absorption blockers serve niche populations with statin intolerance.
- Niacin:Vitamin B3 derivatives persist in combination regimens despite diminished monotherapy utilization.
Statins absorb the bulk of installed manufacturing capacity; PCSK9 inhibitors are expanding most quickly.
Target Patient Group:
Patient complexity determines pricing power, with inherited disorders commanding premium reimbursement versus acquired metabolic conditions.
- Familial Hypercholesterolemia:Genetic LDL receptor defects create lifelong therapeutic demand requiring aggressive lipid lowering. Specialty lipid clinics in the United Kingdom and the Netherlands prioritize these patients for PCSK9 inhibitor access, constrained by payer prior authorization requirements.
- Mixed Dyslipidemia:Combined cholesterol and triglyceride elevations drive polypharmacy utilization. Cardiology centers in Japan manage these cases through combination statin-fibrate protocols, subject to PMDA safety monitoring for myopathy risk.
- Hypertriglyceridemia:Elevated triglyceride-specific interventions target pancreatitis prevention.
- Lipoprotein Disorder:Rare lipid metabolism defects require specialized diagnostic and therapeutic pathways.
Familial hypercholesterolemia captures the steepest pricing premium; mixed dyslipidemia generates the highest absolute prescription volume.
Administration Route:
Delivery modality shapes patient adherence economics and channel strategy, with injectable formats requiring cold-chain infrastructure absent from oral distribution.
- Oral Tablets:Daily or intermittent dosing dominates maintenance therapy across all patient severities. Retail pharmacy networks in the United States and France process the majority of dispenses, supported by decades of patient familiarity and generic substitution protocols.
- Injectable:Subcutaneous monoclonal antibodies and emerging siRNA formulations enable biweekly to quarterly dosing. Specialty pharmacy channels in Germany and the United States manage temperature-controlled distribution and patient training programs.
- Sublingual:Rapid absorption formats address acute compliance scenarios.
- Transdermal:Patch-based delivery remains experimental for lipid-modifying agents.
Oral tablets retain the deepest patient penetration; injectable formats are climbing the fastest as biologic adoption accelerates.
End User:
Site-of-care economics determine formulary access, with hospital-based cardiology centers capturing complex cases excluded from community management.
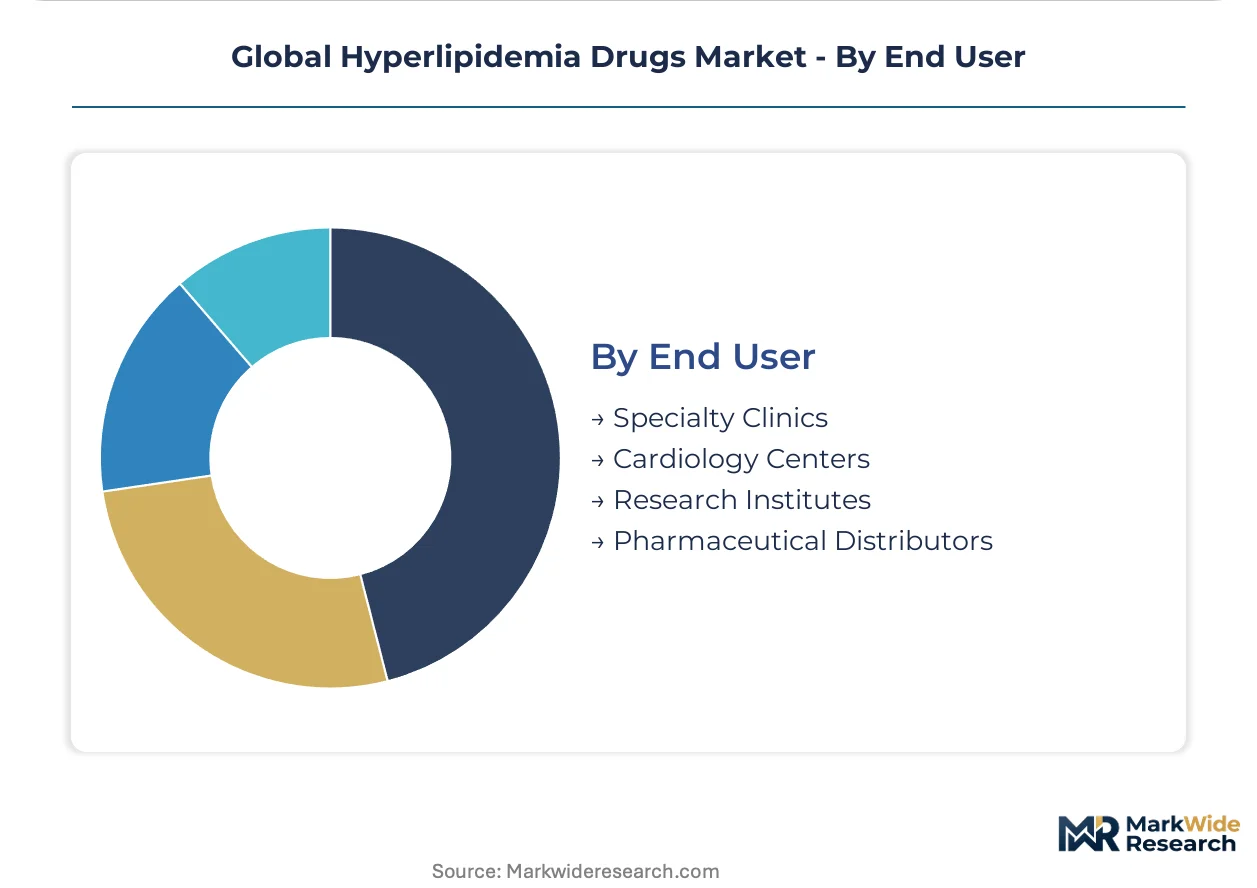
- Cardiology Centers:Tertiary care institutions manage familial hypercholesterolemia and refractory cases requiring combination biologic therapy. Centers in the United States and Switzerland are consolidating around outcomes-based contracts tying reimbursement to LDL target achievement.
- Specialty Clinics:Dedicated lipidology practices provide diagnostic and therapeutic coordination for complex dyslipidemias. Networks in Germany and the United Kingdom are expanding nurse-led monitoring programs to extend specialist capacity.
- Research Institutes:Academic medical centers conduct cardiovascular outcomes trials and gene therapy investigations.
- Pharmaceutical Distributors:Wholesale and specialty channels manage product flow to institutional and retail endpoints.
Cardiology centers command the highest per-patient revenue; specialty clinics are gaining share fastest through retail healthcare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for PCSK9 biologics clusters in Switzerland and Ireland, while consumption gravity tilts toward the United States and Germany where cardiology center infrastructure supports injectable therapy adoption.
United States
Medicare Advantage risk-bearing organizations drive demand for outcomes-guarantee contracts tied to LDL target achievement. The FDA's accelerated approval pathways compress development timelines for novel combination therapies. Cardiology centers in Cleveland and Houston consolidate formularies around injectable biologics for familial hypercholesterolemia patients.
Germany
Specialty lipidology clinics expand nurse-led monitoring programs to extend specialist capacity for complex dyslipidemia cases. EMA pharmacovigilance frameworks enforce post-authorization safety monitoring that extends commercialization timelines. The Rhine-Ruhr metropolitan region anchors distribution infrastructure for temperature-controlled biologic supply chains.
Japan
PMDA bridging study requirements for Western-origin molecules create first-mover advantages for firms committing to localized evidence generation. METI incentives support domestic manufacturing partnerships for RNA interference therapeutics. Tokyo and Osaka academic medical centers prioritize phase III trial enrollment for once-annual dosing candidates.
Switzerland
Single-source mammalian cell culture facilities supply monoclonal antibody therapies to European and Asian markets. Swissmedic maintains stringent batch release standards that shape regional quality benchmarks. Basel and Zurich host concentrated biologics manufacturing clusters serving global cardiology center networks.
India
CDSCO regulatory pathways for biosimilar statins expand generic manufacturing capacity for export markets. Government procurement programs for preventive cardiology services extend addressable patient populations in tier-two cities. Hyderabad and Ahmedabad pharmaceutical clusters specialize in high-volume oral statin synthesis for emerging market distribution.
Global Hyperlipidemia Drugs Market Competitive Landscape
Top-tier vendors anchor the biologics segment through concentrated R&D investment in next-generation mechanisms, while mid-tier generics manufacturers compete on statin volume and supply security across multiple continents. The market structure fragments across three strategic archetypes: multinational pharmaceutical conglomerates with cardiovascular outcomes infrastructure, regional specialists leveraging distribution partnerships with cardiology networks, and contract manufacturing organizations capturing biologic production scale. Dominant competitive moves include strategic partnerships for real-world evidence generation and geographic expansion through localized clinical bridging studies.
Within the multinational conglomerate tier, Pfizer Inc. and Amgen Inc. occupy positions defined by manufacturing scale and biologic pricing power respectively. Daiichi Sankyo Company Limited exemplifies the regional specialist archetype through its anchored position in Asian markets. These three entities collectively represent the competitive spectrum spanning high-volume oral portfolios, injectable biologic innovation, and geographically concentrated distribution networks.
| Leading Market Players |
|---|
| AstraZeneca |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Sanofi |
| Novartis AG |
| Daiichi Sankyo Company Limited |
| Viatris Inc. |
| GSK plc |
| Others |
Supply & Pricing Matrix
Outcomes-guarantee contracts from Medicare Advantage risk-bearing organizations are forcing manufacturers to restructure pricing models around LDL target achievement rather than volume-based purchasing, compelling supply chains to absorb inventory risk while cardiology centers consolidate formulary access.
Pricing Analysis
Margin tightening in injectable biologics reflects statin generic commoditization and payer prior authorization requirements. Three-tier pricing structure across premium PCSK9 inhibitors, standard branded statins, and economy generics governs procurement. Cost compression in oral small-molecule portfolios accelerates because atorvastatin and rosuvastatin face unlimited generic substitution. Primary care networks exhibit highest price sensitivity; familial hypercholesterolemia patients in specialty lipid clinics demonstrate lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Returns and temperature excursion protocols for monoclonal antibodies create reverse-logistics complexity that oral tablet distribution avoids. Manufacturing concentrates in Switzerland, Ireland, and India for biologics, APIs, and generic synthesis respectively. Cold-chain infrastructure draws from specialized mammalian cell culture facilities and sterile fill-finish operations. Single-source dependence on Swiss and Irish biologic production creates vulnerability to batch release delays. Distribution runs through specialty pharmacy channels for injectables and retail networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's cardiovascular outcomes trial requirements function as a cost-of-compliance moat, privileging manufacturers with existing clinical infrastructure and capital reserves while excluding undercapitalized entrants from novel therapy approval pathways.
For Market Incumbents: Extend real-world evidence generation capabilities through electronic health record partnerships to defend against oral small-molecule PCSK9 disruptors. Deepen manufacturing scale in Switzerland and Ireland to secure biologic supply continuity against single-source vulnerability. Prioritize connected auto-injector technology to lock in adherence monitoring contracts with Medicare Advantage organizations. For New Entrants and Emerging Players: Capture Japan's PMDA bridging study pathway for Western-origin molecules by committing to localized clinical evidence generation ahead of multinational conglomerates. Target community pharmacy lipid clinics in tier-two United States markets where specialist referral bottlenecks create direct-to-patient access. Pursue biosimilar statin manufacturing partnerships with Indian CDSCO-registered facilities to serve emerging market procurement programs. For Investors and Strategic Acquirers: The window for entry favors regional specialists with anchored distribution partnerships in Asian cardiology networks and existing cardiovascular outcomes infrastructure. Long-term viability hinges on pipeline positioning in RNA interference and gene silencing modalities. Monitor FDA draft guidance finalization on surrogate endpoint acceptability as the inflection signal for combination therapy investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcomes trials satisfy FDA evidentiary thresholds for novel combination therapies. |
| Regulatory Approval Pathway | PMDA bridging studies unlock first-mover positioning in Japan's concentrated academic medical center networks. |
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Switzerland secures monoclonal antibody supply continuity. |
| Pipeline Diversification | RNA interference therapeutics address adherence failures in biweekly injection patient populations. |
| Reimbursement Strategy | Outcomes-guarantee contracts with Medicare Advantage align pricing with LDL target achievement metrics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases provided validation layers. Bottom-up prescription volume modeling and top-down market sizing triangulated demand estimates across mechanism-of-action categories.
Reconciliation of prescription audit streams, procurement database extracts, and pricing survey panels informed analytical framework construction across the analysis window. Segmentation dimensions included drug class, target patient group, administration route, and end-user site-of-care. CAGRs derived from trend extrapolation of historic prescription growth adjusted for pipeline entry timing and regulatory approval probability. Forecast inputs incorporated Medicare reimbursement evolution trajectories and cardiology center infrastructure expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA surrogate endpoint guidance finalization, biosimilar entry timing, and RNA interference clinical readouts. Practitioners should monitor EMA pharmacovigilance burden adjustments and PMDA bridging study requirement modifications for early signals of regional access expansion or contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Global Statin Market
Cardiovascular
Angina Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
US Statin Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market