
 Global Coronary Artery Bypass Grafting Market | 2026-2036
Global Coronary Artery Bypass Grafting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coronary Artery Bypass Grafting Market Foresight
Ambulatory surgical centers are reorganizing procurement patterns for coronary artery bypass grafting systems as hospital networks decentralize cardiac service lines. Medtronic leverages its end-to-end perfusion portfolio to anchor high-volume on-pump contracts across integrated delivery networks. Terumo Corporation specializes in off-pump stabilization technologies that differentiate its position among surgeons pursuing beating-heart techniques. Abbott Laboratories extends its vascular closure and graft monitoring capabilities into cardiac surgery workflows through interventional cardiology cross-training.
Coronary artery bypass grafting is a surgical revascularization procedure that creates alternative conduits around stenosed coronary arteries using autologous vessels, synthetic materials, or composite constructs to restore myocardial perfusion. The procedure typically requires cardiopulmonary bypass support or specialized stabilization platforms to maintain hemodynamic stability during anastomosis construction. Off-pump CABG commands substantial volume in mature healthcare systems where cost containment and reduced intensive care utilization drive purchasing criteria. Minimally invasive CABG and robotic CABG represent faster-growing technique categories where capital equipment amortization and specialized training requirements create margin concentration for vendors with bundled service contracts.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern graft biocompatibility validation and long-term patency claims across the United States and European markets. Japan's PMDA enforces stringent clinical evidence standards for synthetic graft materials that delay market entry relative to Western timelines. China's NMPA has accelerated review timelines for domestically manufactured cardiac surgical devices under innovation channel designations. Stakeholders must monitor evolving reimbursement thresholds for robotic-assisted procedures and hybrid coronary revascularization protocols as payer frameworks recalibrate site-of-service incentives.
Market Dynamics
Hybrid operating room infrastructure expansion is restructuring capital allocation across cardiac surgery delivery networks, forcing vendors to bundle imaging, perfusion, and robotic platforms into single-source contracts rather than standalone device sales.
Growth Catalysts
- EU MDR conformity assessments:Synchronized technical documentation standards across European markets are compressing multi-country approval timelines for graft biocompatibility validation.
- Beating-heart stabilization platforms:Off-pump CABG technique refinement is reducing intensive care utilization and accelerating discharge protocols in cost-constrained health systems.
- Japan's hybrid OR infrastructure:Metropolitan hospital networks in Tokyo and Osaka are integrating intraoperative imaging with conventional bypass procedures, creating demand for compatible graft delivery systems.
Market Restraints
- Synthetic graft material validation costs:Long-term patency studies required by Japan's PMDA impose five-to-seven-year development timelines that deter mid-scale manufacturers from market entry.
- Autologous vein supply constraints:Saphenous vein harvest limitations in diabetic and peripheral vascular disease populations restrict conduit availability for multi-vessel revascularization.
- Perfusionist workforce concentration:Cardiopulmonary bypass specialist training programs cluster in the United States, Germany, and Japan, creating operational bottlenecks for on-pump procedure expansion elsewhere.
Strategic Opportunities
- China's NMPA innovation channel:Accelerated review designations for domestically manufactured cardiac surgical devices are opening procurement access to tier-one municipal hospitals in Shanghai and Beijing.
- Robotic anastomosis training networks:Vendor-captive education programs for minimally invasive CABG are creating switching costs that lock hospital systems into platform-specific consumable streams.
- Ambulatory surgical center cardiac service lines:Hospital network decentralization is creating site-of-service arbitrage for select low-complexity bypass procedures in United States metropolitan markets.
Industry Challenges
- Cross-functional surgical team assembly:Hybrid OR protocols require simultaneous coordination of cardiac surgeons, interventional cardiologists, and perfusion specialists, straining scheduling and credentialing systems.
- Capital equipment amortization pressure:Robotic CABG platforms require procedure volume thresholds exceeding 200 cases annually to achieve cost neutrality against conventional sternotomy approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coronary Artery Bypass Grafting Market |
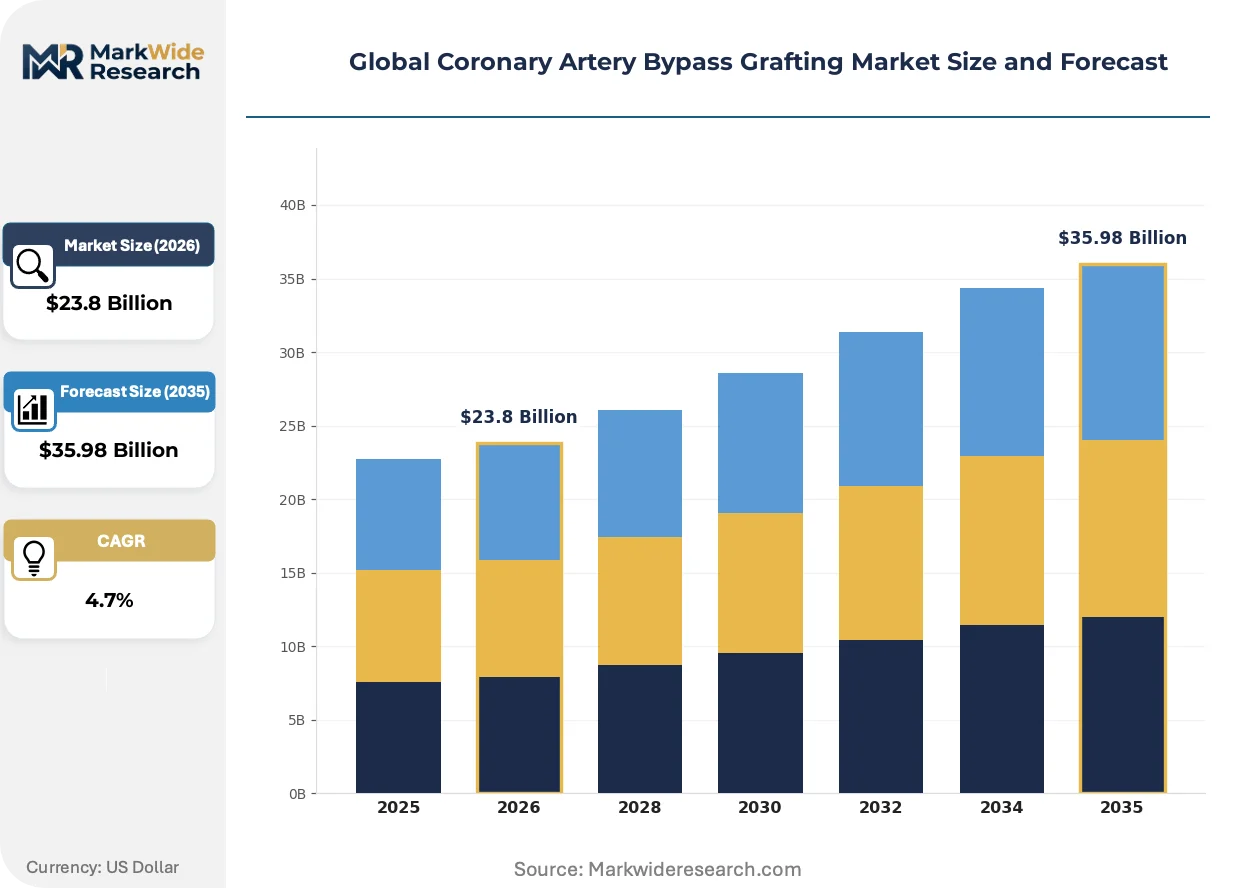
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.98 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Surgery Technique: On-pump CABG, Off-pump CABG, Minimally Invasive CABG, Robotic CABG Graft Type: Autologous Vein, Autologous Artery, Synthetic Graft, Composite Graft Patient Age Group: Pediatric, Adult, Geriatric, Octogenarian Healthcare Setting: Cardiac Surgery Centers, General Hospitals, Specialty Clinics, Ambulatory Surgical Centers |
| Companies Covered | Medtronic, Terumo Corporation, Getinge AB, Edwards Lifesciences, LivaNova, Abbott Laboratories, B. Braun Melsungen AG, W. L. Gore & Associates, Inc., Guidant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coronary Artery Bypass Grafting Market Shifts & Advancements
Endovascular coronary intervention capabilities are bleeding into surgical revascularization workflows, forcing graft manufacturers to design products compatible with both open and catheter-based delivery methods.
Endoscopic vein harvesting systems are fragmenting traditional open-harvest technique dominance. Ambulatory surgical centers and short-stay cardiac units in the United States are adopting these platforms to reduce leg wound complications and accelerate patient mobilization. This technology is fragmenting the historical correlation between procedure volume and inpatient bed requirements, enabling decentralized service line economics.
Japan's PMDA has tightened clinical evidence standards for synthetic graft materials, requiring extended follow-up data that exceeds Western regulatory thresholds. Domestic manufacturers in Tokyo and Osaka are responding by prioritizing autologous tissue engineering collaborations over polymer-based development pipelines. Synthetic graft developers are redirecting commercialization resources toward United States FDA 510(k) pathways where predicate device arguments remain viable.
Hospital purchasing committees are consolidating cardiac surgery procurement authority at integrated delivery network headquarters, displacing individual surgeon preference as the primary vendor selection mechanism. Bundled payment contracts for coronary revascularization episodes in United States Medicare Advantage plans are reinforcing this concentration. Germany's statutory health insurance funds are piloting analogous procurement centralization for cardiac surgical devices across university hospital alliances.
Global Coronary Artery Bypass Grafting Market Segmentation
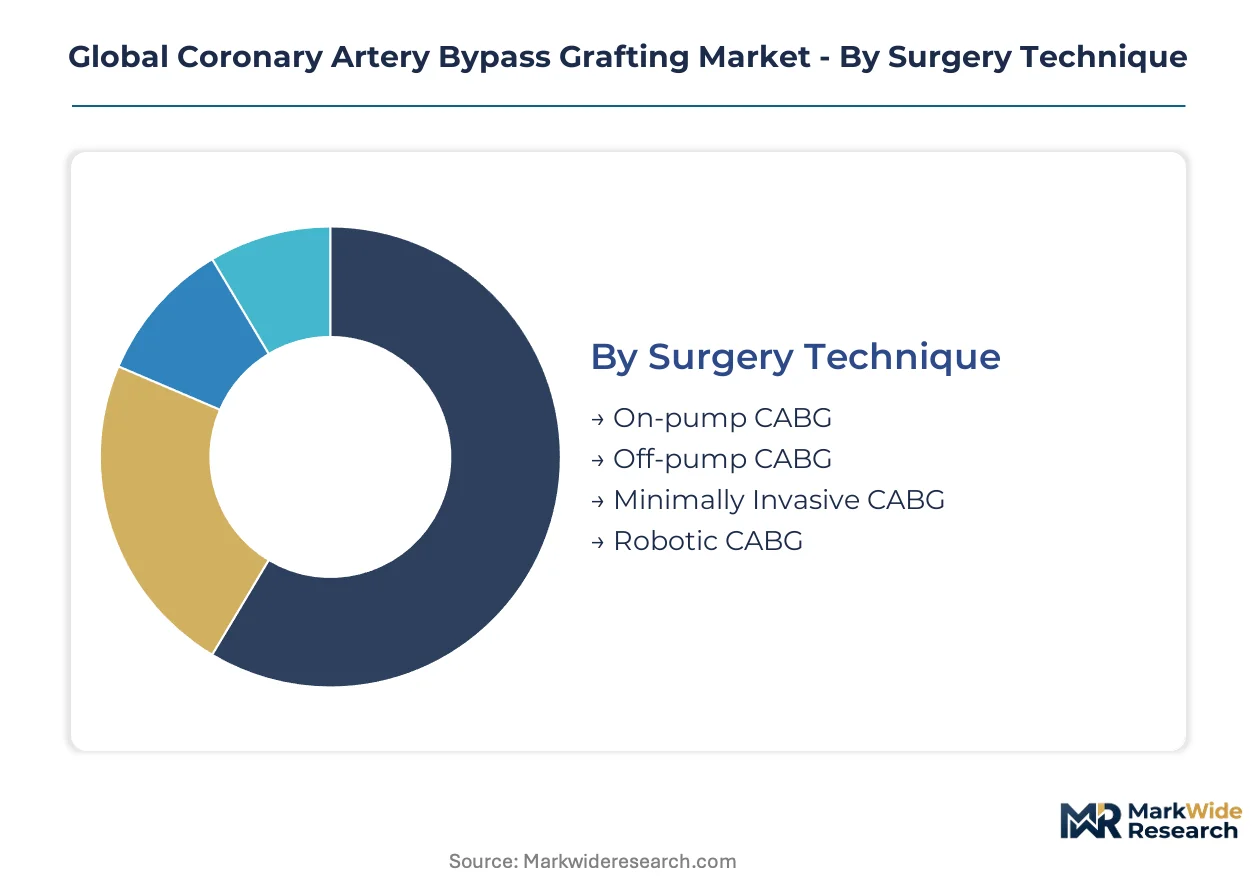
Segmentation in coronary artery bypass grafting reveals how technique selection, conduit choice, and site-of-service economics fragment procurement decisions across healthcare systems. Vendors must align product portfolios with distinct clinical workflows and reimbursement frameworks that vary by procedure complexity and patient risk profile.
Surgery Technique:
On-pump CABG dominates domestic procedure volumes in the United States, Germany, and Japan where perfusionist training infrastructure supports conventional bypass workflows. Off-pump CABG and robotic approaches command premium positioning in export-oriented healthcare systems seeking to reduce intensive care utilization.
- On-pump CABG:Cardiopulmonary bypass support enables complete cardiac arrest during multi-vessel anastomosis construction. Demand concentrates in integrated delivery networks across the United States and German university hospital alliances where high case volumes amortize perfusion team costs.
- Off-pump CABG:Beating-heart stabilization platforms eliminate extracorporeal circulation. Japanese metropolitan hospitals in Tokyo and Osaka favor this technique for cost containment and reduced postoperative ventilation requirements in elderly populations.
- Minimally Invasive CABG:Small thoracotomy approaches reduce sternal wound complications. European cardiac surgery centers adopt these platforms to differentiate service lines.
- Robotic CABG:Telemanipulator systems enable endoscopic internal mammary artery harvest. Adoption clusters in United States metropolitan markets with capital equipment subsidies from integrated delivery networks.
On-pump CABG holds the largest share; momentum sits with robotic CABG as hybrid operating room infrastructure expands.
Graft Type:
Cost tier stratification separates autologous harvesting systems from synthetic material platforms, with composite constructs occupying mid-tier pricing bands across procurement frameworks.
- Autologous Vein:Saphenous vein grafts remain the standard conduit for multi-vessel revascularization. Supply constraints in diabetic populations across the United States and Germany drive investment in endoscopic harvest technologies.
- Autologous Artery:Internal mammary artery grafts deliver superior long-term patency. Japanese surgeons prioritize bilateral internal mammary artery harvest for diabetic patients despite extended operative times.
- Synthetic Graft:Polymer-based conduits address autologous vessel insufficiency. PMDA validation timelines deter development pipelines in Japan.
- Composite Graft:Sequential anastomosis configurations optimize limited conduit supply. Adoption accelerates in European markets with vein-sparing protocols.
Autologous vein grafts dominate procurement volumes; composite grafts are climbing the fastest as surgeons adapt to conduit scarcity.
Patient Age Group:
Application intensity varies by demographic risk profile, with geriatric and octogenarian segments driving complexity premiums in reimbursement frameworks.
- Pediatric:Congenital heart defect corrections require specialized conduit sizing. Volume concentrates in United States children's hospital networks and German pediatric cardiac centers.
- Adult:Standard-risk coronary artery disease represents baseline procedure economics. General hospitals across all major markets maintain capacity for this demographic.
- Geriatric:Comorbidity burden elevates perioperative risk stratification requirements. Japanese healthcare settings lead adoption of off-pump techniques for this cohort.
- Octogenarian:Frailty indices influence graft selection toward single-vessel strategies. Ambulatory surgical centers in United States metropolitan markets pilot low-complexity protocols.
Adult patients anchor procedure volume; octogenarian segments show steepest expansion trajectory as population aging accelerates across developed healthcare systems.
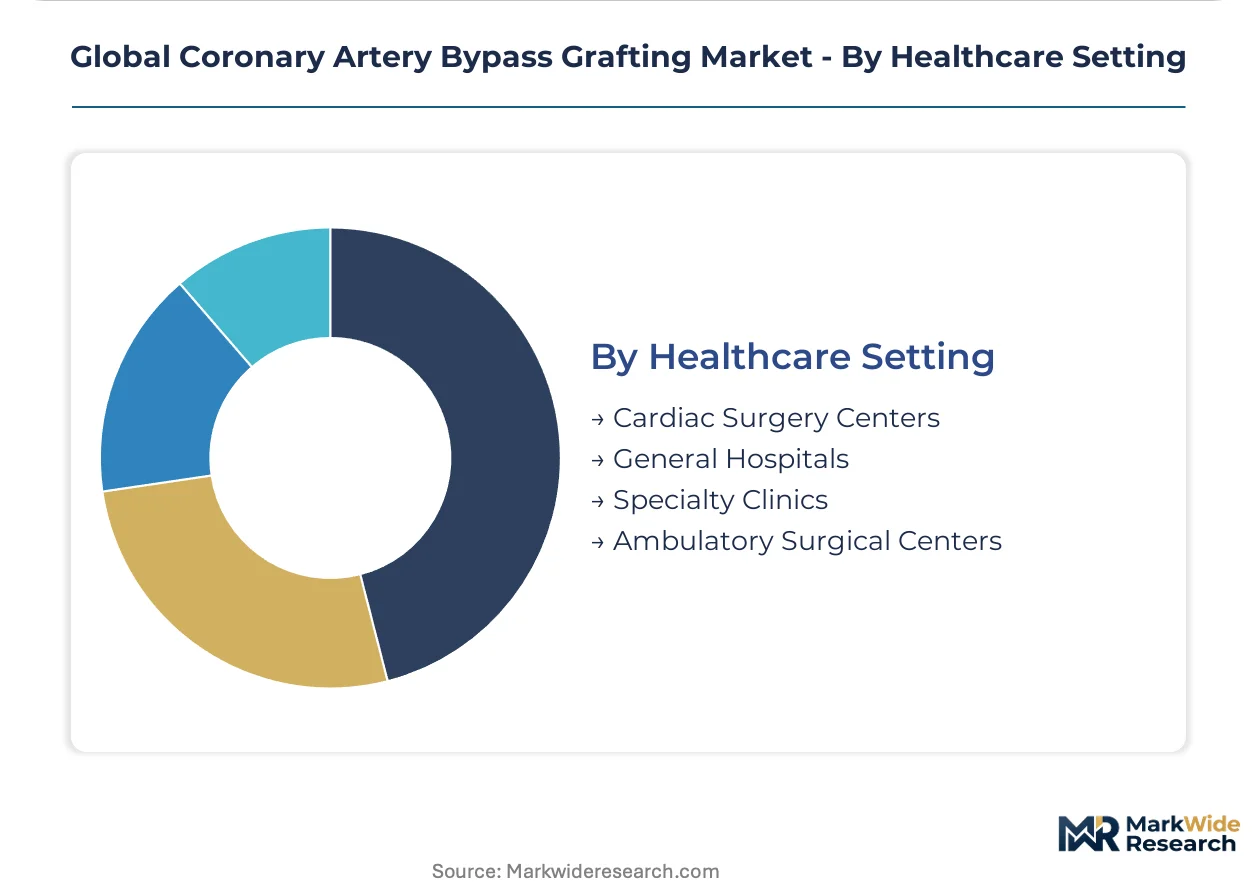
Healthcare Setting:
Customer type fragmentation separates capital-intensive cardiac surgery centers from decentralized ambulatory platforms, reshaping vendor sales force deployment.
- Cardiac Surgery Centers:Dedicated facilities achieve economies of scale in high-complexity revascularization. German university hospital alliances concentrate procurement authority at this tier.
- General Hospitals:Mixed-service facilities balance cardiac surgery against competing priorities. Volume share is declining as networks centralize specialty services.
- Specialty Clinics:Focused cardiac practices emphasize diagnostic-to-treatment continuity. These settings drive preoperative planning technology adoption.
- Ambulatory Surgical Centers:Short-stay facilities capture select low-complexity cases. United States Medicare site-of-service differentials accelerate this channel's expansion.
Cardiac surgery centers command premium pricing; ambulatory surgical centers are gaining share fastest as hospital networks decentralize service line economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgical device manufacturing clusters in the United States, Germany, and Japan concentrate perfusion technology production and graft material innovation. These three countries anchor hybrid operating room deployment and drive regulatory precedent for coronary revascularization platforms.
United States
Medicare Advantage bundled payment contracts for coronary revascularization episodes concentrate procurement authority at integrated delivery network headquarters. FDA 510(k) clearance pathways enable faster synthetic graft predicate device approvals than Japanese or European timelines. Metropolitan hospital networks in Houston and Cleveland expand hybrid operating room infrastructure to capture complex multi-vessel cases.
Germany
Statutory health insurance funds pilot centralized cardiac surgical device procurement across university hospital alliances, displacing individual surgeon preference. EU MDR conformity assessments synchronize technical documentation standards for graft biocompatibility validation across European markets. The Rhine-Ruhr and Bavarian hospital networks concentrate beating-heart stabilization platform adoption for cost containment.
Japan
Metropolitan hospital networks in Tokyo and Osaka integrate intraoperative imaging with conventional bypass procedures. PMDA enforces stringent clinical evidence standards for synthetic graft materials that impose five-to-seven-year development timelines. Domestic manufacturers in Osaka prioritize autologous tissue engineering collaborations over polymer-based development pipelines.
China
Tier-one municipal hospitals in Shanghai and Beijing accelerate procurement of domestically manufactured cardiac surgical devices through NMPA innovation channel designations. The country's national medical products regulator has compressed review timelines for local manufacturers. Yangtze River Delta medical device clusters scale perfusion equipment production for hospital network expansion.
India
Domestic cardiac surgery volume concentrates in Delhi-NCR, Mumbai, and Chennai metropolitan hospital networks seeking cost-efficient off-pump techniques. The national pharmaceutical regulator enforces clinical trial requirements for imported synthetic graft materials that extend registration timelines. Apollo and Max Healthcare hospital chains centralize procurement for multi-vessel revascularization platforms across South Asian markets.
Global Coronary Artery Bypass Grafting Market Competitive Landscape
Concentration sits with diversified cardiovascular technology conglomerates that bundle perfusion, monitoring, and graft delivery platforms into single-source contracts. The vendor base separates into three tiers: end-to-end portfolio suppliers, off-pump stabilization specialists, and regional perfusion equipment fabricators. Strategic moves center on integrated delivery network captive contracting and hybrid operating room bundling rather than standalone device sales.
Among diversified cardiovascular technology conglomerates, Medtronic anchors the end-to-end perfusion portfolio tier while Terumo Corporation occupies the off-pump stabilization specialist position. Abbott Laboratories exemplifies the interventional-to-surgical crossover archetype through vascular closure and graft monitoring capabilities. These three companies represent distinct competitive positioning vectors based on technique specialization and workflow integration depth.
| Leading Market Players |
|---|
| Medtronic |
| Terumo Corporation |
| Getinge AB |
| Edwards Lifesciences |
| LivaNova |
| Abbott Laboratories |
| B. Braun Melsungen AG |
| W. L. Gore & Associates, Inc. |
| Guidant Group |
| Others |
Supply & Pricing Matrix
Endoscopic vein harvesting systems displacing open-harvest techniques are redrawing procurement geography toward United States and German device clusters while compressing margins on conventional conduit preparation platforms. This substitution simultaneously elevates capital equipment pricing tiers in metropolitan hospital networks and erodes disposable revenue streams for traditional harvest instrument suppliers.
Pricing Analysis
EU MDR conformity assessments dictate the pricing tier structure across European markets by imposing differentiated compliance cost burdens on synthetic graft developers versus autologous platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates robotic CABG platform bundles from off-pump stabilization systems and conventional on-pump consumables. Cost compression in standard-tier perfusion circuits is intensifying because integrated delivery networks in the United States are consolidating procurement authority at headquarters level. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare site-of-service reimbursement differentials, while Japanese university hospital alliances show lowest sensitivity given PMDA-mandated quality validation requirements.
Supply Chain Analysis
The United States, Germany, and Japan anchor perfusion equipment manufacturing and graft material innovation for coronary revascularization platforms. Supply chains draw from medical-grade polymer suppliers in the United States, precision pump component fabricators in Germany, and biocompatible coating specialists in Japan. Single-source vulnerability concentrates in extracorporeal circulation membrane production where two German suppliers dominate global capacity. Distribution runs through integrated delivery network central procurement offices in the United States and university hospital alliance purchasing consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technique fragmentation across on-pump, off-pump, robotic, and hybrid approaches is creating specialized vendor niches that resist commoditization by diversified cardiovascular conglomerates. Ambulatory surgical center expansion in United States metropolitan markets exemplifies this demand-side shift, rewarding focused platform developers over end-to-end portfolio suppliers.
For Market Incumbents: Consolidate perfusion technology market share through captive contracting with integrated delivery networks facing capital equipment amortization pressure from robotic CABG platform investments. Deepen backward integration into biocompatible graft material production to offset synthetic conduit validation cost escalation under Japan's PMDA timelines. Lock hospital systems into multi-year service contracts that embed switching costs ahead of EU MDR recertification waves. For New Entrants and Emerging Players: Lead with endoscopic vein harvesting platform specialization targeting ambulatory surgical center cardiac service lines in United States metropolitan markets where hospital network decentralization is accelerating. China's NMPA innovation channel for domestically manufactured cardiac surgical devices offers the most penetrable regulatory pathway for tier-one municipal hospital procurement access. Pursue vendor-captive training program partnerships with metropolitan hospital networks to establish platform-specific consumable lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed off-pump stabilization specialists seeking exit liquidity as robotic CABG platform adoption matures. Long-term viability over the five-to-ten year horizon favors vendors with hybrid operating room bundling capabilities rather than standalone device positioning. Monitor integrated delivery network robotic CABG case volume thresholds as the critical inflection signal for platform economics sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Medtronic's end-to-end perfusion portfolio anchors high-volume on-pump contracts across United States integrated delivery networks. |
| CE Marking Pathway | EU MDR conformity assessments compress multi-country approval timelines for graft biocompatibility validation across European markets. |
| Software Companion Development | Abbott Laboratories extends vascular closure and graft monitoring capabilities into cardiac surgery workflows through interventional cardiology cross-training. |
| Reimbursement Strategy | United States Medicare site-of-service differentials accelerate ambulatory surgical center channel expansion for select low-complexity bypass procedures. |
| FDA Submission | Predicate device arguments under FDA 510(k) pathways remain viable for synthetic graft developers redirecting resources from Japan's PMDA. |
Research Methodology
A standing panel of cardiac surgeons, perfusion specialists, hospital purchasing committee directors, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval records, and hospital procurement contract registries. Bottom-up demand modeling across surgery technique, graft type, and healthcare setting segments was triangulated with top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks including CMS Medicare procedure data, Japanese Ministry of Health surgical statistics, and German statutory health insurance fund reimbursement records across the projection horizon. Segmentation dimensions modeled encompass surgery technique, graft material category, patient age group, and healthcare setting with CAGRs derived from procedure volume elasticity to hybrid operating room infrastructure deployment. Industry-specific forecast inputs incorporated perfusionist workforce concentration patterns and regulatory approval timeline differentials by geography.
The analysis sits within stated boundaries; outcomes outside sustained hybrid operating room capital expenditure levels or significant reimbursement framework recalibration would require model adjustment. Forecasts reflect documented assumptions regarding technique adoption trajectories and regulatory pathway stability. Recalibration cycles align with material shifts in integrated delivery network procurement centralization and ambulatory surgical center regulatory authorization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Heart Lung Machine Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Cardiomyopathy Medication Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market