
 US Statin Market | 2026-2036
US Statin Market Size, Share, and Industry Trends Forecast 2026-2036
US Statin Market Analytics
Integrated delivery networks is rotating toward risk-bearing contracts that reward LDL target achievement. Pfizer Inc. leverages its manufacturing scale to dominate hospital formulary placements for atorvastatin. Merck & Co. anchors the generic simvastatin segment through sustained channel control with major pharmacy benefit managers. Amgen Inc. differentiates via PCSK9 combination strategies that extend its cardiovascular portfolio beyond traditional statin mechanisms.
Statins comprise a class of HMG-CoA reductase inhibitors that block cholesterol biosynthesis in hepatic cells, with atorvastatin and rosuvastatin offering the highest potency at lowest milligram doses. These agents serve as first-line pharmaceutical intervention for atherosclerotic cardiovascular disease risk reduction across outpatient and inpatient settings. Atorvastatin leads the product type landscape due to its established efficacy profile and broad generic availability that compresses pricing while expanding access. The therapy area segmentation tilts toward hyperlipidemia management as the foundational indication, though cardiovascular disease prevention represents the fastest-growing application as payors intensify focus on upstream risk mitigation.
FDA oversees statin safety labeling and new indication approvals, while CMS reimbursement policies directly shape prescribing economics through Medicare Part D formularies and quality metrics tied to star ratings. The IRA Medicare drug price negotiation program introduces structural pressure on branded statin economics, compelling manufacturers to recalibrate portfolio prioritization. Stakeholders must monitor how FDA guidance on combination lipid therapies intersects with CMS value-based payment models to determine pipeline investment and commercialization sequencing.
Market Dynamics
The IRA Medicare drug price negotiation program is compressing branded statin margins while accelerating generic substitution, forcing manufacturers to recalibrate around value-based contracting and combination therapy portfolios.
Growth Catalysts
- Medicare Advantage penetration:Risk-bearing contracts in the Southeast reward LDL target achievement, expanding statin prescribing protocols in cardiology clinics.
- PCSK9 inhibitor convergence:Combination strategies with traditional HMG-CoA reductase inhibitors extend therapeutic utility for high-risk patient populations.
- Preventive care prioritization:CMS quality metrics tied to star ratings intensify focus on upstream cardiovascular risk mitigation in outpatient settings.
Market Restraints
- Generic commoditization:Atorvastatin and simvastatin price compression limits revenue per prescription across pharmacy benefit manager channels.
- Regulatory labeling friction:FDA safety warnings for muscle-related adverse effects constrain prescriber confidence in high-intensity dosing protocols.
- Biologic substitution threat:Monoclonal antibody therapies for familial hypercholesterolemia displace traditional statins in orphan indication segments.
Strategic Opportunities
- Integrated delivery network expansion:Hospital formulary placements for fixed-dose combinations capture inpatient-to-outpatient care transitions.
- Metabolic disease corridors:Mississippi Delta and Appalachian regions present underpenetrated demand where diabetes prevalence intersects with cardiovascular comorbidity.
- Digital therapeutic adjacency:Remote patient monitoring platforms enable adherence tracking that satisfies value-based reimbursement requirements.
Industry Challenges
- Clinical trial recruitment bottlenecks:Cardiovascular outcome studies require extended follow-up periods that strain development timelines for novel formulations.
- Legacy EHR integration:Electronic health record systems in rural health clinics lack interoperability with population health management tools that track lipid panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Statin Market |
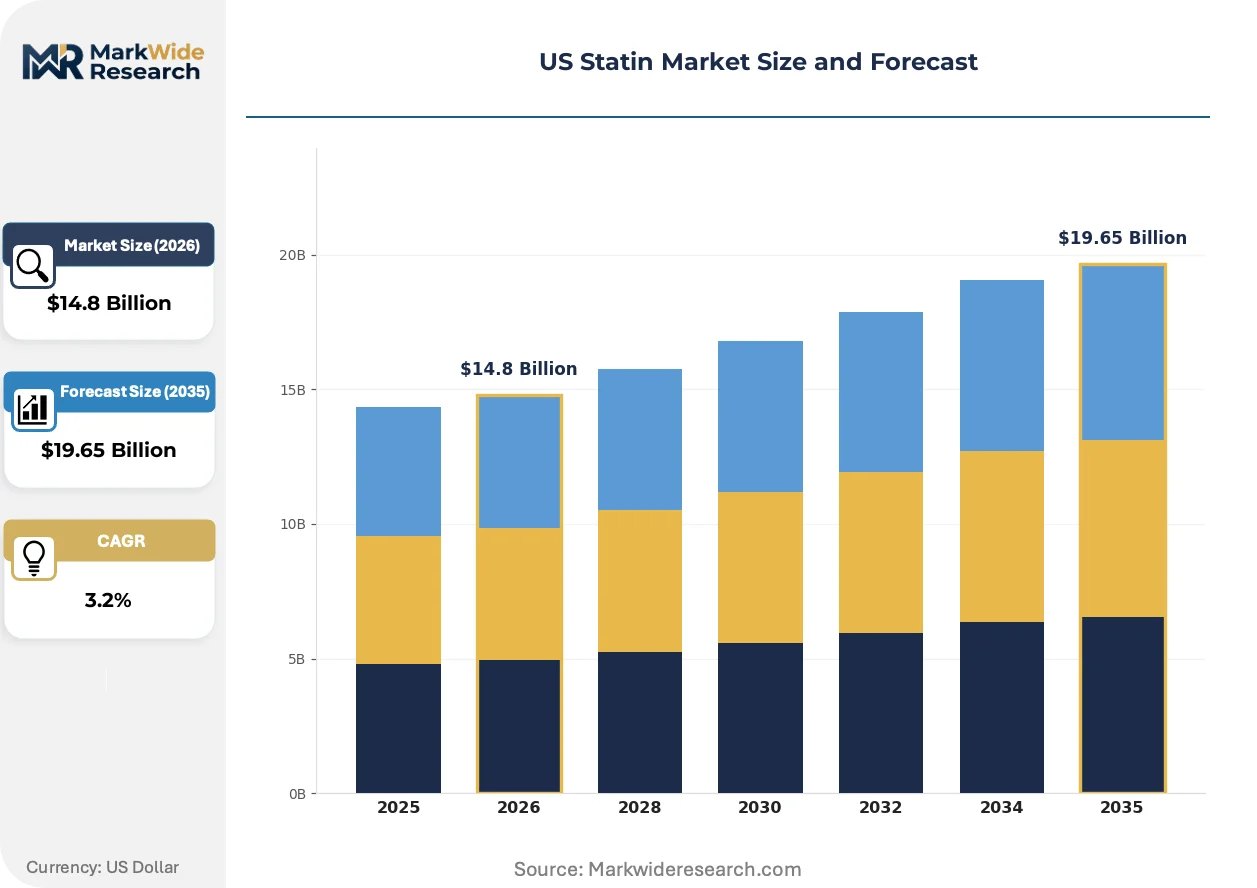
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $19.65 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atorvastatin, Rosuvastatin, Simvastatin, Pravastatin Therapy Area: Hyperlipidemia, Cardiovascular Disease, Dyslipidemia, Prevention End User: Physicians, Hospitals, Pharmacies, Clinics Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | Novartis AG, GlaxoSmithKline, Pfizer Inc., Sun Pharmaceutical, Abbott, Merck & Co., Amgen Inc., Aurobindo Pharma, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Statin Market Evolving Landscape
Pharmaceutical innovation in lipid management is diverging along two paths: precision dosing algorithms and non-statin mechanism expansion. This bifurcation reshapes R&D allocation and commercial positioning across the cardiovascular portfolio.
Pharmacogenomic testing for CYP3A4 and SLCO1B1 variants is bifurcating the prescribing landscape. Large integrated delivery networks in Texas and Florida deploy preemptive genetic screening to stratify myopathy risk before atorvastatin initiation. This capability compresses trial-and-error dosing cycles while creating tiered patient segments that demand customized care protocols.
CMS star rating methodologies now incorporate medication adherence metrics for cholesterol-lowering therapies. Medicare Advantage plans in Georgia and North Carolina deploy nurse care coordinators to intervene on non-adherent beneficiaries. This policy mechanism elevates adherence programs from cost centers to revenue-protecting infrastructure.
Specialty pharmacy channels are capturing statin dispensing volume from retail chains. Patients on high-intensity regimens receive coordinated refill management and side-effect counseling through limited distribution networks. This channel migration concentrates most visibly in Medicare Part D populations with multiple cardiovascular comorbidities.
US Statin Market Segmentation
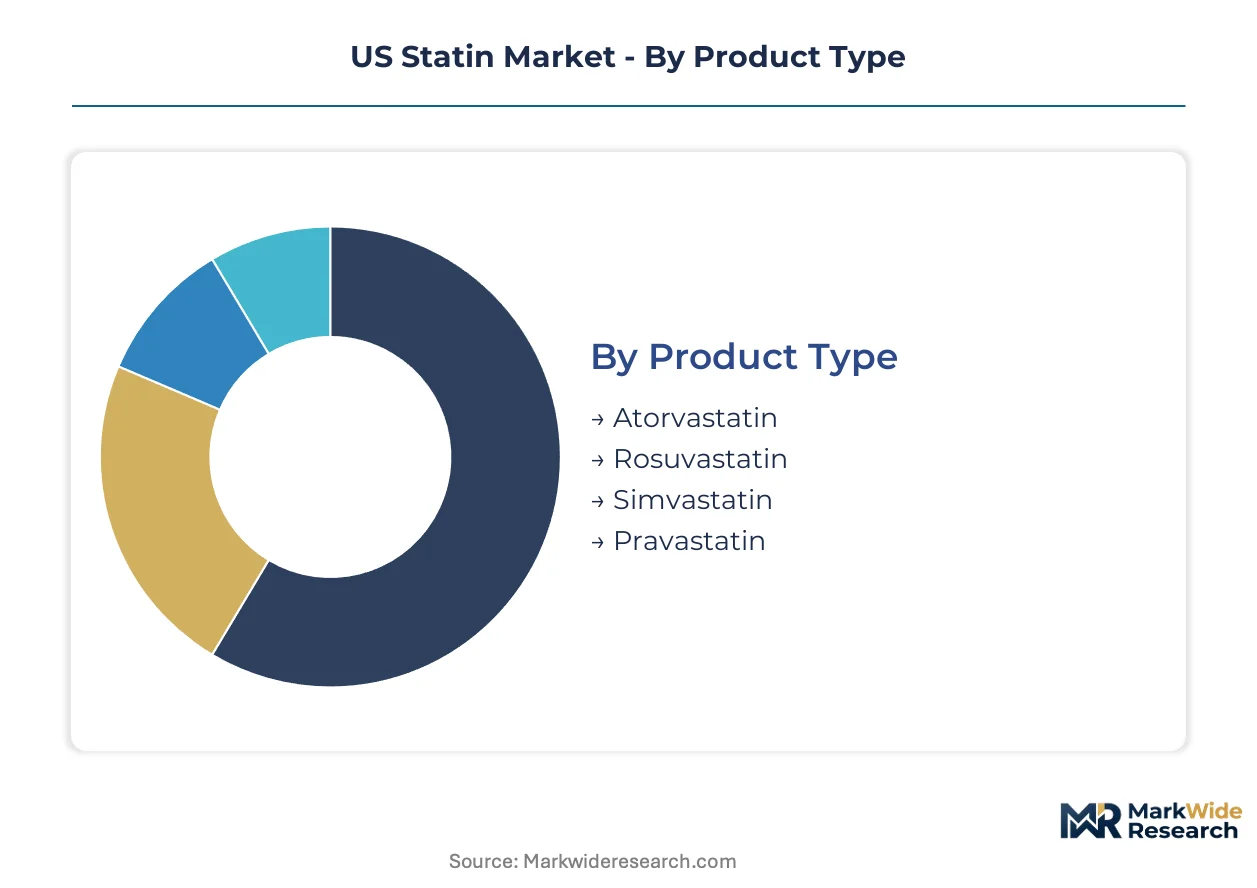
Statin segmentation reveals how prescribing economics fragment across potency tiers, clinical settings, and reimbursement channels. Understanding these divides exposes where manufacturers capture margin versus where commoditization erodes returns.
Product Type:
Margin pools concentrate in high-potency molecules where generic substitution lags and hospital formulary placement commands premium positioning.
- Atorvastatin:This HMG-CoA reductase inhibitor delivers the highest LDL reduction per milligram among traditional statins, with established efficacy in both primary and secondary prevention protocols. Demand concentrates in Southeast Medicare Advantage corridors where CMS star ratings for cholesterol management intensify prescribing volume. Pfizer's manufacturing scale secures dominant hospital formulary placements despite generic availability.
- Rosuvastatin:The most potent statin at lowest doses, rosuvastatin offers hydrophilic properties that reduce CYP3A4 drug interaction risk versus lipophilic alternatives. Prescribing clusters in Florida and Texas integrated delivery networks deploying pharmacogenomic screening for myopathy risk stratification. AstraZeneca's Crestor franchise maintains pricing power through indication breadth.
- Simvastatin:Merck anchors this commoditized segment through sustained pharmacy benefit manager channel control.
- Pravastatin:Water-soluble profile suits elderly polypharmacy patients in rural Appalachian clinics with limited metabolic monitoring.
The dominant share belongs to atorvastatin, while rosuvastatin is closing the gap fastest through high-intensity indication expansion.
Therapy Area:
Application focus determines whether reimbursement flows through preventive care incentives or acute intervention budgets.
- Hyperlipidemia:Foundational indication for statin therapy targeting elevated LDL-C and triglyceride levels in outpatient settings. Mississippi Delta health systems prioritize this segment where diabetes prevalence intersects with cardiovascular comorbidity and value-based contracts reward lipid target achievement.
- Cardiovascular Disease:Secondary prevention in post-MI and stroke patients drives the steepest expansion trajectory as payors intensify upstream risk mitigation investments. Georgia and North Carolina Medicare Advantage plans deploy nurse care coordinators specifically for this population to protect star ratings.
- Dyslipidemia:Complex lipid disorders including mixed hyperlipidemia and elevated Lp(a) occupy specialist referral pathways.
- Prevention:Primary prevention in intermediate-risk patients faces FDA labeling friction on muscle-related adverse effects.
Cardiovascular disease commands the largest therapy spend, though prevention applications are expanding most quickly under risk-bearing contracts.
End User:
Customer type dictates whether procurement runs through centralized hospital purchasing or fragmented retail dispensing.
- Physicians:Individual and group practice prescribing dominates volume in suburban and rural markets where electronic health record systems lack interoperability with population health tools.
- Hospitals:Inpatient initiation protocols and discharge prescribing concentrate in Southeast integrated delivery networks capturing care transitions through fixed-dose combination formularies.
- Pharmacies:Retail chains face volume migration to specialty channels for high-intensity regimens requiring adherence monitoring.
- Clinics:Federally qualified health centers in Appalachian metabolic disease corridors present underpenetrated demand.
Hospitals capture the dominant procurement position, while clinics are gaining share fastest through community health center expansion.
Distribution Channel:
Channel configuration determines adherence infrastructure investment and margin capture through care coordination services.
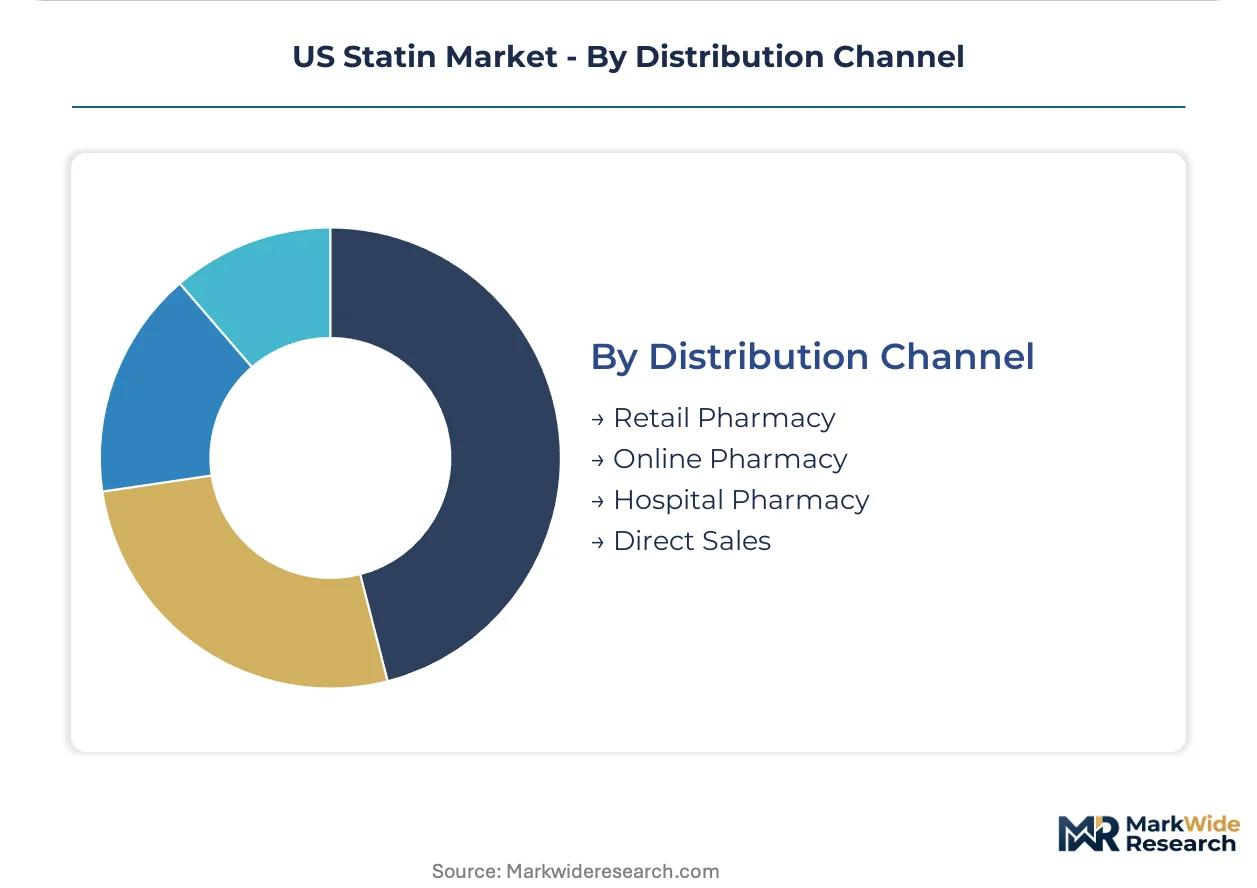
- Retail Pharmacy:CVS and Walgreens maintain volume leadership in maintenance statin dispensing despite specialty channel encroachment.
- Online Pharmacy:Amazon Pharmacy and mail-order platforms expand share through 90-day refill incentives in Medicare Part D plans.
- Hospital Pharmacy:Captures inpatient-to-outpatient transitions with coordinated refill management for complex cardiovascular patients.
- Direct Sales:Limited to institutional contracts with large integrated delivery networks in Texas and Florida.
Retail pharmacy retains dominant volume, though hospital pharmacy is climbing the fastest through care transition capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 pharmaceutical distribution corridor anchors statin supply chain efficiency, connecting Atlantic seaboard manufacturing clusters to Southeast Medicare Advantage population centers.
Southeast
Medicare Advantage penetration and metabolic disease prevalence intersect across Georgia, North Carolina, and Florida, driving LDL target achievement protocols in Atlanta and Charlotte cardiology clinics. CMS star rating methodologies reward lipid management outcomes, intensifying nurse care coordinator deployment. The Mississippi Delta corridor presents underpenetrated demand where diabetes prevalence meets cardiovascular comorbidity.
Texas
Integrated delivery networks in Houston and Dallas deploy pharmacogenomic screening for CYP3A4 and SLCO1B1 variants to stratify myopathy risk before atorvastatin initiation. FDA label expansions for high-intensity dosing reshape prescriber confidence in these metropolitan clusters. Risk-bearing contracts with Medicare Advantage plans concentrate prescribing volume through hospital formulary placements.
Appalachia
Federally qualified health centers in rural Kentucky, West Virginia, and Tennessee serve elderly polypharmacy patients with limited metabolic monitoring capabilities. Pravastatin prescribing dominates due to water-soluble profiles reducing drug interaction risk. Legacy EHR systems lack interoperability with population health tools tracking lipid panels.
Florida
Retiree density and Medicare Part D enrollment create concentrated demand for high-intensity statin regimens in Miami, Tampa, and Orlando metropolitan areas. Specialty pharmacy channels capture dispensing volume from retail chains through coordinated refill management. AstraZeneca's Crestor franchise maintains pricing power through indication breadth in these markets.
Midwest
Hospital formulary placements in Chicago, Detroit, and Cleveland integrated delivery networks capture inpatient-to-outpatient care transitions through fixed-dose combination strategies. Generic atorvastatin price compression limits revenue per prescription across pharmacy benefit manager channels. The IRA Medicare drug price negotiation program accelerates substitution toward commoditized simvastatin alternatives.
US Statin Market Competitive Landscape
Concentration sits with large-cap pharmaceutical manufacturers commanding hospital formulary placement and pharmacy benefit manager channel control. The market structure tilts toward tiered competition where manufacturing scale determines generic substitution economics. Three archetypes dominate: legacy brand holders defending indication breadth, generic volume leaders optimizing cost-position, and biologic innovators extending cardiovascular portfolios beyond traditional mechanisms. Competitive moves center on value-based contracting alignment and combination therapy portfolio diversification.
Among legacy pharmaceutical manufacturers, Pfizer Inc., Merck & Co., and Amgen Inc. exemplify distinct strategic positioning within the statin value chain. Pfizer anchors manufacturing scale advantages for atorvastatin despite generic availability. Merck occupies the commoditized simvastatin segment through sustained channel control. Amgen represents biologic convergence strategies combining PCSK9 inhibitors with traditional HMG-CoA reductase inhibition.
| Leading Market Players |
|---|
| Novartis AG |
| GlaxoSmithKline |
| Pfizer Inc. |
| Sun Pharmaceutical |
| Abbott |
| Merck & Co. |
| Amgen Inc. |
| Aurobindo Pharma |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hospital purchasing consortia and generic API manufacturers lock in supply access for atorvastatin while compressing price visibility through multi-year volume commitments. These contract structures concentrate procurement leverage within Southeast integrated delivery networks, where Medicare Advantage star rating incentives intensify demand predictability and enable forward price locking.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the statin landscape by potency intensity and generic substitution lag. Premium tiering attaches to high-intensity rosuvastatin and branded combination therapies where FDA label breadth sustains pricing power; standard tiering captures generic atorvastatin volume through pharmacy benefit manager rebates; economy tiering commoditizes simvastatin with minimal differentiation. Cost compression in the economy tier is intensifying because IRA Medicare price negotiation accelerates substitution toward lowest-cost alternatives. Hospital procurement committees exhibit least price sensitivity due to formulary lock-in, while independent rural clinics demonstrate highest sensitivity to per-prescription acquisition costs.
Supply Chain Analysis
Active pharmaceutical ingredient sourcing from India and China concentrates manufacturing risk for generic statin precursors, with intermediate HMG-CoA reductase inhibitor synthesis tethered to Gujarat and Zhejiang chemical clusters. Fermentation-derived mevalonate pathway inputs and synthetic statin side chains draw from these geographies, while finished dosage form production localizes in US-based contract manufacturers. Single-source vulnerability in CYP3A4 metabolic profiling reagents constrains pharmacogenomic screening deployment. Distribution runs through specialty pharmacy channels for high-intensity regimens requiring adherence monitoring, with retail chains handling maintenance therapy volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Statin Market tracks a cyclical recovery pattern as Medicare Advantage penetration crests and IRA pricing compression forces portfolio recalibration toward value-based contracting. Generic substitution waves and combination therapy innovation create alternating pressure and release cycles across the forecast horizon.
For Market Incumbents: Fortify hospital formulary placement through fixed-dose combination portfolios that capture inpatient-to-outpatient care transitions. Deepen channel control with specialty pharmacy networks for high-intensity regimens requiring adherence infrastructure. Biologic substitution threat from PCSK9 monoclonal antibodies demands defensive indication expansion into familial hypercholesterolemia segments where traditional statins retain cost advantage.
For New Entrants and Emerging Players: Anchor in Mississippi Delta and Appalachian metabolic disease corridors where federally qualified health centers present underpenetrated demand and limited incumbent presence. Target pravastatin prescribing in rural elderly polypharmacy populations where water-soluble profiles reduce drug interaction risk. Deploy remote patient monitoring platforms as adherence-tracking entry wedge that satisfies CMS value-based reimbursement requirements.
For Investors and Strategic Acquirers: Specialty pharmacy platforms with integrated care coordination capabilities offer acquisition exposure to channel migration trends concentrating Medicare Part D volume. Long-term viability hinges on adherence infrastructure ownership rather than molecule differentiation as generic commoditization accelerates. Monitor FDA guidance on combination lipid therapies as inflection indicator for pipeline investment recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Captures care transitions through hospital formulary placement in Southeast IDNs. |
| Pharmacogenomic Screening Partnership | Enables CYP3A4 risk stratification for myopathy reduction in Texas and Florida networks. |
| Specialty Pharmacy Channel Expansion | Concentrates high-intensity regimen dispensing with adherence monitoring infrastructure. |
| Value-Based Contracting Alignment | Aligns manufacturer economics with Medicare Advantage LDL target achievement incentives. |
| PCSK9 Combination Portfolio | Extends cardiovascular positioning beyond traditional HMG-CoA reductase mechanisms. |
Research Methodology
Initial hypotheses were tested against primary input from formulary directors, hospital procurement managers, payer access specialists, and cardiology clinic administrators and refined through secondary validation. FDA filings, CMS Medicare Part D utilization data, ClinicalTrials.gov entries, and pharmacy benefit manager formulary databases anchored quantitative segmentation. Bottom-up prescription volume modeling and top-down reimbursement flow analysis triangulated market sizing across potency tiers and therapy areas.
Variance-decomposition framing separated volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled included product potency tier, therapy area application, end-user procurement type, and regional Medicare Advantage penetration cluster. CAGRs were derived from prescription trajectory analysis calibrated to demographic cardiovascular risk expansion and regulatory pricing intervention timing. Forecast inputs incorporated IRA negotiation schedule impacts and pharmacogenomic adoption curves in major metropolitan markets.
Decision-makers should treat outputs as directional under assumptions of stable CMS star rating methodologies and continued Medicare Advantage growth; material deviation in IRA implementation pace or FDA combination therapy guidance would warrant model refresh. Practitioners should keep alternative scenarios live as biologic substitution thresholds and value-based contract penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Aortic Coarctation Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Vasculitis Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Tachycardia Market
Cardiovascular
Stroke Management Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Bifurcation Lesions Market