
 Prinzmetal Angina Therapeutics Market | 2026-2036
Prinzmetal Angina Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Prinzmetal Angina Therapeutics Market Analytics
Market Context with Strategic Players
The capability gap between large-cap pharmaceutical manufacturers and mid-tier cardiovascular specialists is collapsing as R&D scale requirements for vasospastic angina therapies intensify. Pfizer Inc. leverages its established calcium channel blocker infrastructure to sustain manufacturing economies across multiple dosage formulations. AstraZeneca PLC anchors its competitive position through integrated cardiovascular portfolios that span emergency and preventive care segments. Bayer AG differentiates via antiplatelet agent specialization that competes directly in dual-therapy protocols for refractory Prinzmetal angina cases.
Technical Definition and Structural Segments
Prinzmetal angina therapeutics comprise pharmacological agents targeting coronary artery vasospasm, specifically calcium channel blockers such as amlodipine and nifedipine that inhibit L-type calcium channels to prevent smooth muscle contraction, alongside nitrates that provide nitric oxide-mediated vasodilation for acute symptom relief. These therapies serve the primary commercial purpose of reducing transient myocardial ischemia episodes and preventing malignant arrhythmias in patients with documented coronary spasm disorders. Calcium channel blockers occupy the dominant revenue position within product type segmentation due to their established efficacy as maintenance therapy for vasospastic angina prevention. The intravenous delivery mode segment leads hospital-based emergency treatment protocols, while sublingual formulations retain critical positioning in outpatient clinic settings where rapid symptom abort is clinically prioritized.
Regulatory Frame and Forward-Looking Close
FDA cardiovascular safety guidance, EMA's Committee for Medicinal Products for Human Use standards, and Japan's PMDA pharmacovigilance requirements collectively shape clinical development pathways and post-market surveillance obligations for anti-ischemic agents targeting vasospastic disorders. These regulatory frameworks mandate rigorous QT interval monitoring and drug-drug interaction studies that directly influence formulation decisions and label expansion strategies across the therapeutic landscape. Stakeholders must monitor evolving FDA guidance on proarrhythmic risk assessment as this regulatory signal will determine which next-generation calcium channel modulators advance through Phase III development for Prinzmetal angina indications.
Market Dynamics
Hospital formularies are consolidating calcium channel blocker procurement around single-source contracts, compressing vendor margins while elevating quality-assurance requirements for anti-ischemic agents.
Growth Catalysts
- FDA cardiovascular safety mandates:QT interval monitoring requirements for new anti-ischemic agents are accelerating clinical trial standardization and reducing development risk for compliant sponsors.
- Specialist cardiology center density:Concentrated demand in Germany, Japan, and the United States creates predictable revenue streams for targeted therapeutic deployment.
- Dual-therapy protocols:Antiplatelet-calcium channel blocker combinations for refractory vasospastic angina are expanding addressable patient populations beyond monotherapy responders.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for dihydropyridine calcium channel blockers clusters in specific coastal Chinese provinces, exposing formulators to geopolitical disruption risk.
- EMA proarrhythmic assessment burden:Thorough QT study requirements add 18-24 months to development timelines for novel calcium channel modulators.
- Generic nifedipine substitution:Off-patent immediate-release formulations capture maintenance therapy volume in price-sensitive hospital systems.
Strategic Opportunities
- Underpenetrated outpatient clinics:Sublingual nitrate protocols in rural United States cardiology practices remain below evidence-based prescribing guidelines.
- Japan PMDA pharmacovigilance alignment:Streamlined post-market surveillance pathways for established calcium channel blockers reduce regulatory overhead for label expansions.
- Remote patient monitoring integration:Wearable ECG devices paired with vasospasm detection algorithms enable preemptive dosing adjustments.
Industry Challenges
- Specialized electrophysiology talent scarcity:QT interval analysis expertise for regulatory submission documentation commands premium compensation and extends hiring timelines.
- Legacy EHR integration complexity:Vasospastic angina diagnostic codes lack standardization across hospital systems, complicating real-world evidence collection for payor negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prinzmetal Angina Therapeutics Market |
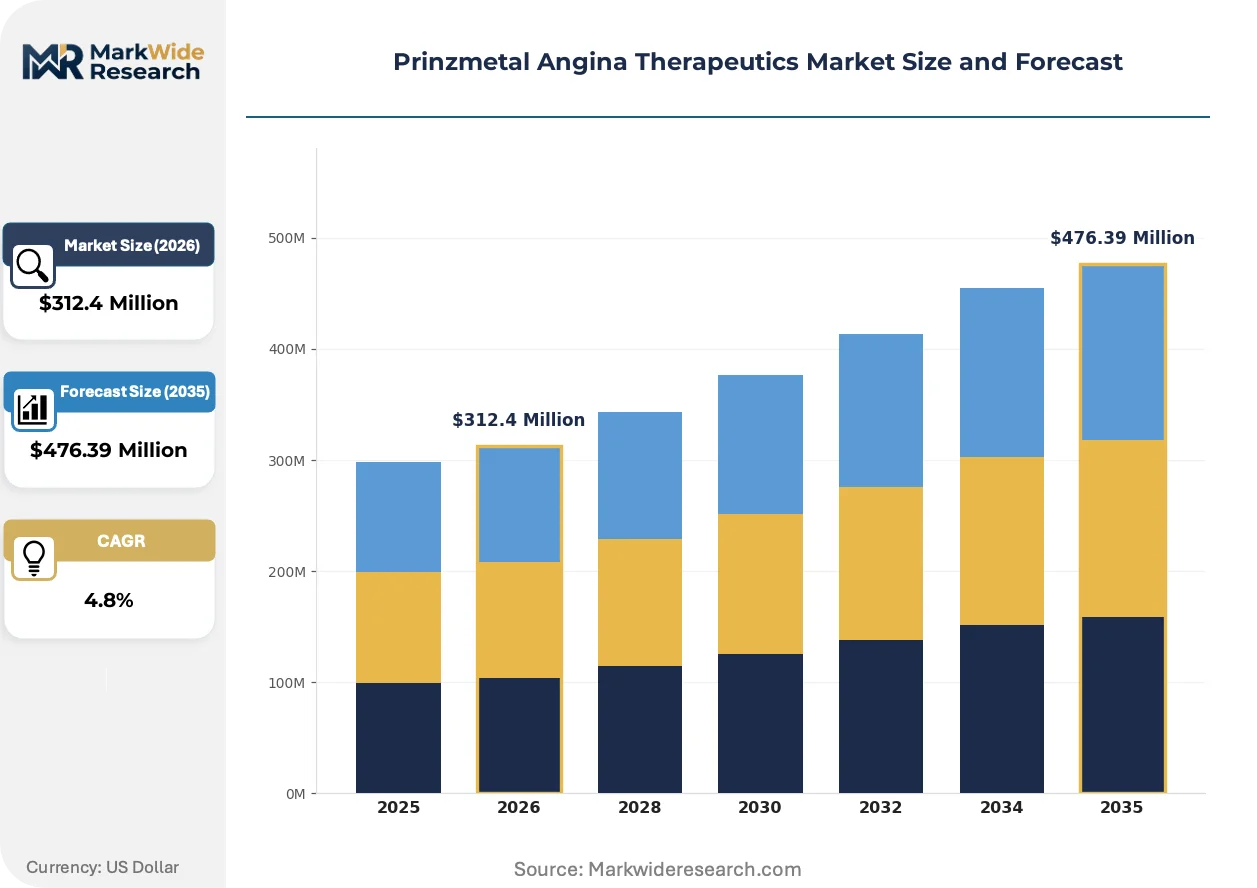
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrates, Calcium Channel Blockers, Beta-Blockers, Antiplatelet Agents End User: Hospitals, Outpatient Clinics, Cardiology Centers, Research Institutions Therapy Area: Cardiovascular Disease, Pain Management, Emergency Treatment, Preventive Care Delivery Mode: Oral, Intravenous, Sublingual, Transdermal |
| Companies Covered | Pfizer Inc., AstraZeneca PLC, Bayer AG, Novartis AG, Sanofi S.A., Gilead Sciences Inc., Eli Lilly and Company, Amgen Inc., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prinzmetal Angina Therapeutics Market Evolving Landscape
Long-acting calcium channel blocker formulations are displacing immediate-release alternatives in maintenance protocols, while regulatory pressure on cardiac safety endpoints intensifies development rigor across all anti-ischemic classes.
Extended-release nifedipine and amlodipine formulations are fragmenting the maintenance therapy segment by reducing dosing frequency and improving adherence metrics in outpatient settings. Specialist cardiology centers in Germany and Japan are adopting these platforms at accelerated rates compared to general hospital formularies. The technology is fragmenting competitive positioning between large-cap manufacturers with scale formulation capabilities and mid-tier specialists dependent on contract manufacturing.
EMA's Committee for Medicinal Products for Human Use issued refined cardiovascular safety guidance requiring standardized provocation testing for coronary spasm disorders in clinical development programs. The industrial consequence is elevated trial costs and extended recruitment periods for novel vasodilatory agents. Early-phase sponsors are responding by prioritizing established calcium channel blocker reformulations over mechanistically novel targets.
Hospital procurement departments are consolidating anti-ischemic purchasing into cardiovascular therapeutic class committees with mandatory pharmacoeconomic review. This behavioral shift displaces individual physician preference in formulary decisions across United States academic medical centers. The concentration is most visible in tertiary care systems where bundled payment models for acute coronary syndrome episodes create incentive alignment around standardized vasospasm protocols.
Prinzmetal Angina Therapeutics Market Segmentation
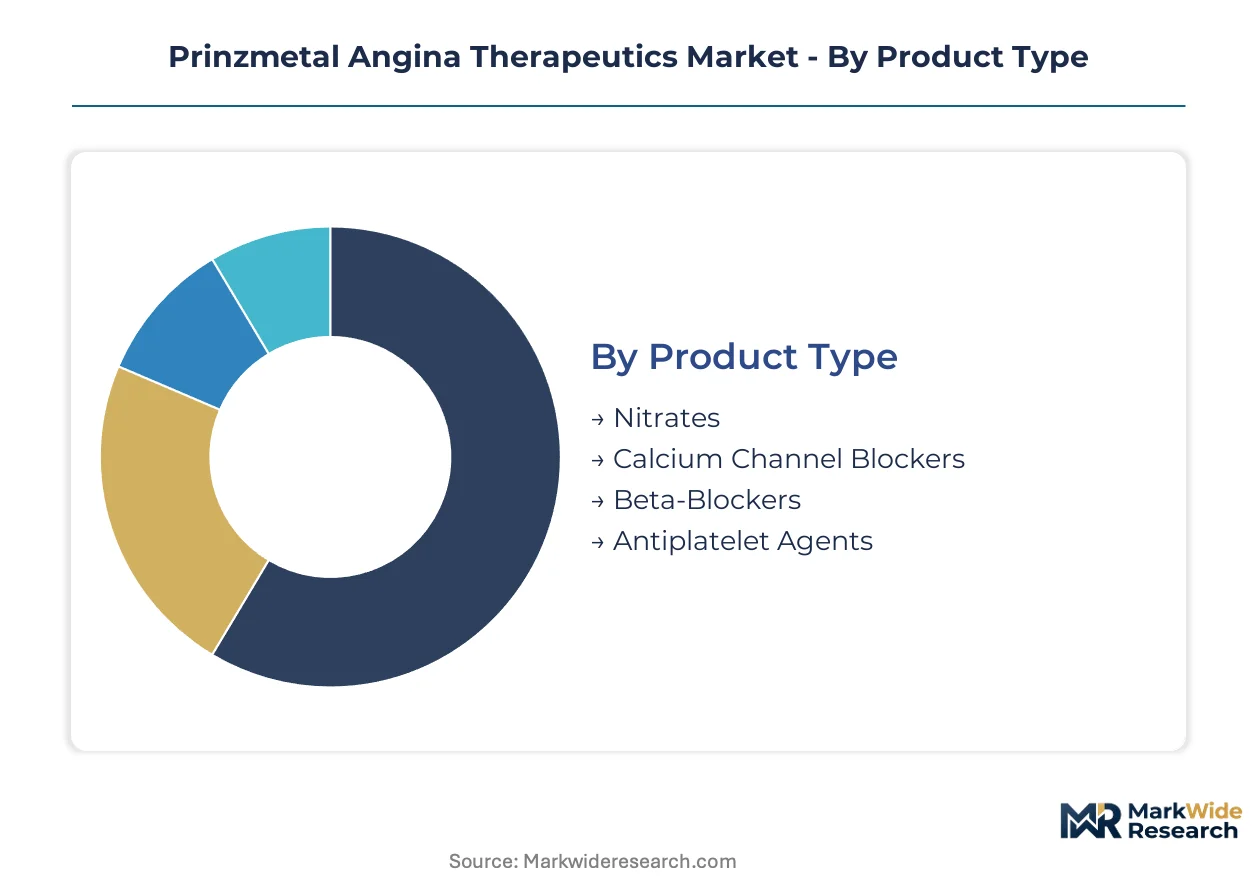
Prinzmetal angina therapeutics segmentation reveals distinct substitution dynamics across pharmacological classes and care settings. Product type fragmentation determines pricing power, while delivery mode selection directly shapes patient adherence and emergency response protocols.
Product Type:
Generic substitution pressure concentrates most intensely on mature cardiovascular agents with expired patent protection, forcing branded manufacturers toward reformulation strategies and combination therapies.
- Calcium Channel Blockers:Dihydropyridine derivatives such as amlodipine and nifedipine inhibit L-type calcium channels to prevent coronary smooth muscle contraction. Hospital formularies in Germany and Japan concentrate procurement around extended-release formulations that reduce dosing frequency and improve maintenance therapy adherence.
- Nitrates:Nitric oxide donors including nitroglycerin provide rapid vasodilation through cyclic GMP-mediated smooth muscle relaxation. Sublingual formulations dominate outpatient clinic demand in the United States where rapid symptom abort remains clinically prioritized over long-term prevention.
- Beta-Blockers:Non-selective agents carry theoretical risk of unopposed alpha stimulation in vasospastic disorders, limiting their role to specific comorbidity contexts.
- Antiplatelet Agents:Aspirin and P2Y12 inhibitors address thrombotic complications in refractory cases with documented spasm-induced plaque disruption.
Calcium channel blockers retain volume leadership; antiplatelet agents hold the steepest expansion curve as dual-therapy protocols gain specialist acceptance.
End User:
Procurement authority is migrating from individual physicians toward centralized pharmacy committees, reshaping vendor access patterns across care settings.
- Hospitals:Tertiary care systems manage acute vasospastic episodes through emergency department protocols and coronary care unit admissions. Bundled payment models for acute coronary syndrome episodes in United States academic medical centers create incentive alignment around standardized calcium channel blocker selection.
- Cardiology Centers:Specialist facilities in Japan and Germany perform diagnostic provocation testing and maintain longitudinal vasospastic angina registries. These centers drive adoption of extended-release formulations and combination therapies through protocol-driven prescribing.
- Outpatient Clinics:Rural United States practices remain below evidence-based sublingual nitrate prescribing guidelines.
- Research Institutions:Academic centers conduct mechanistic studies and registry maintenance for rare vasospastic phenotypes.
Hospitals dominate absolute volume; cardiology centers are climbing the fastest as specialist referral networks consolidate.
Therapy Area:
Reimbursement coding distinctions between emergency intervention and chronic disease management determine commercial prioritization across therapeutic applications.
- Cardiovascular Disease:Coronary vasospasm management represents the core indication with established diagnostic criteria and treatment algorithms.
- Emergency Treatment:Acute symptom termination requires rapid-onset formulations with demonstrated hemodynamic stability.
- Preventive Care:Maintenance therapy aims to reduce episode frequency and prevent malignant arrhythmia.
- Pain Management:Chest pain symptom control without underlying ischemia documentation carries lower reimbursement value.
Cardiovascular disease anchors revenue concentration; emergency treatment is expanding most quickly as pre-hospital protocol standardization advances.
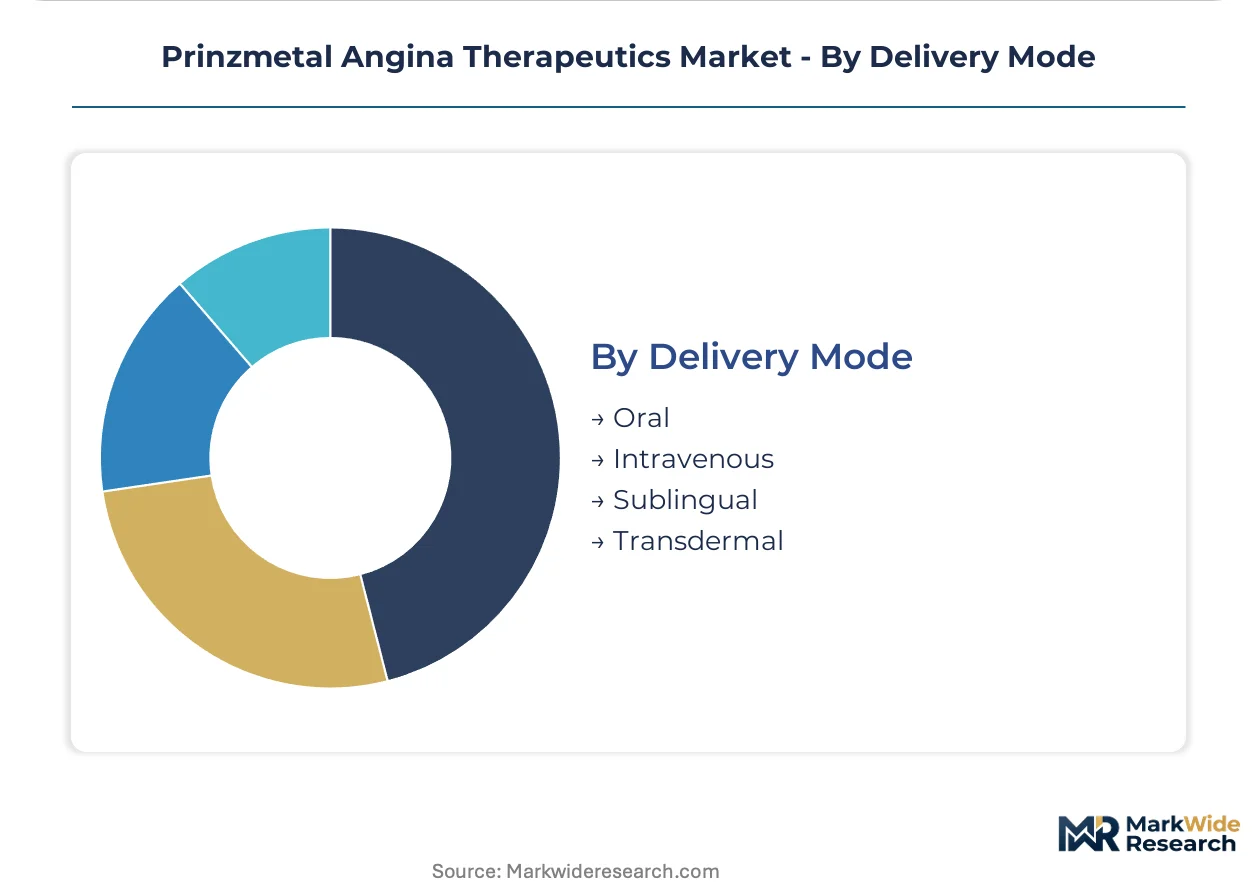
Delivery Mode:
Formulation technology investments concentrate where bioavailability challenges and onset speed requirements create defendable manufacturing expertise.
- Oral:Extended-release tablets and capsules dominate maintenance therapy with improved pharmacokinetic profiles over immediate-release alternatives.
- Intravenous:Hospital-based emergency protocols require sterile formulations with precise titration capability for hemodynamic control.
- Sublingual:Rapid buccal absorption bypasses first-pass metabolism for acute symptom relief in outpatient settings.
- Transdermal:Nitroglycerin patches provide sustained prophylaxis with lower peak-trough variability than oral nitrates.
Oral formulations command the largest patient-day volume; intravenous delivery is gaining share fastest as emergency department protocol standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement elasticity varies sharply by geography. United States buyers absorb premium extended-release formulations while German tenders drive aggressive generic substitution. Japanese cardiology centers sustain branded pricing through protocol-driven standardization.
United States
Tertiary care systems concentrate vasospastic angina treatment in academic medical centers with bundled payment incentives. FDA cardiovascular safety mandates on QT interval monitoring shape formulary decisions. The Cleveland Clinic and Mayo Clinic anchor specialist referral networks that standardize calcium channel blocker selection.
Germany
EMA Committee for Medicinal Products for Human Use standards elevate clinical evidence requirements for anti-ischemic agents. University hospitals in Heidelberg and Munich maintain longitudinal vasospastic angina registries that drive protocol adoption. Cardiology centers prioritize extended-release formulations to reduce dosing frequency.
Japan
PMDA pharmacovigilance requirements create streamlined post-market surveillance for established calcium channel blockers. Tokyo and Osaka specialist centers perform diagnostic provocation testing at density unmatched elsewhere. Maintenance therapy adherence metrics exceed global benchmarks through protocol-driven prescribing.
United Kingdom
NICE technology appraisals constrain reimbursement for novel anti-ischemic agents without demonstrated mortality benefit. London teaching hospitals and the Oxford-Cambridge corridor concentrate electrophysiology expertise for QT analysis. Regional cardiology networks consolidate procurement around standardized vasospasm protocols.
Canada
Health Canada cardiovascular safety guidance aligns with FDA standards while provincial formularies exercise independent price negotiation. Toronto and Montreal academic centers participate in international vasospastic angina registries. Hospital procurement committees increasingly require pharmacoeconomic evidence for calcium channel blocker selection.
Prinzmetal Angina Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Prinzmetal angina therapeutics landscape. Large-cap pharmaceutical manufacturers sustain manufacturing economies through multi-dosage formulation scale, while mid-tier cardiovascular specialists concentrate on narrow therapeutic class expertise. The market structure rewards players with integrated cardiovascular portfolios spanning emergency and preventive care segments. Dominant competitive moves include strategic partnerships for extended-release formulation technology and geographic expansion into Japanese and German specialist cardiology networks.
Among large-cap diversified manufacturers, Pfizer Inc., AstraZeneca PLC, and Bayer AG occupy positions defined by cardiovascular infrastructure depth. Pfizer represents the calcium channel blocker manufacturing scale archetype. AstraZeneca exemplifies integrated portfolio strategy across acute and chronic cardiovascular indications. Bayer anchors the antiplatelet specialization segment that competes in dual-therapy protocols. These three entities collectively illustrate how established cardiovascular franchises determine competitive positioning in vasospastic angina therapeutics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca PLC |
| Bayer AG |
| Novartis AG |
| Sanofi S.A. |
| Gilead Sciences Inc. |
| Eli Lilly and Company |
| Amgen Inc. |
| Merck & Co. Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between hospital procurement committees and calcium channel blocker manufacturers lock in supply access while anchoring price visibility across the forecast window. These contracts concentrate purchasing power in United States academic medical centers and German university hospitals, compressing margins for immediate-release nifedipine while preserving premium positioning for extended-release formulations.
Pricing Analysis
After-sales service revenue from patient monitoring programs and adherence support contracts drives lifetime value for branded calcium channel blocker portfolios. Three-tier pricing structure across premium extended-release, standard oral formulations, and economy generic substitutes segments the market by therapeutic sophistication. Cost compression in the generic tier intensifies as Chinese API suppliers expand dihydropyridine manufacturing capacity. Price-sensitive hospital systems in Germany and Canada prioritize immediate-release substitutions, while Japanese cardiology centers absorb premium pricing for protocol-standardized maintenance therapies.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital procurement for intravenous calcium channel blockers used in emergency vasospastic episodes, contrasting with just-in-time inventory for outpatient oral maintenance therapies. Active pharmaceutical ingredient production for dihydropyridine derivatives concentrates in coastal Chinese provinces and select Indian manufacturing clusters, with formulation finishing distributed across Germany, Japan, and the United States. The supply chain rests on nifedipine base compound, specialized extended-release polymer matrices, and sterile injectable-grade solvents. Single-source vulnerability in Chinese API manufacturing exposes formulators to geopolitical disruption risk. Distribution runs through regional pharmaceutical wholesalers serving hospital networks and specialist cardiology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital buyer power is consolidating through cardiovascular therapeutic class committees that displace individual physician preference, fragmenting vendor access across United States tertiary care systems and German university hospital networks.
For Market Incumbents: Shield extended-release formulation market share by securing sole-source contracts with Japanese and German specialist cardiology centers where protocol-driven prescribing sustains premium positioning. Accelerate backward integration into API manufacturing to reduce exposure to Chinese supply concentration. Invest in QT interval analysis capabilities to preempt FDA cardiovascular safety guidance evolution. For New Entrants and Emerging Players: Differentiate on remote patient monitoring integration by pairing wearable ECG devices with vasospasm detection algorithms for preemptive dosing adjustments. Target underpenetrated rural United States outpatient clinics where sublingual nitrate prescribing remains below evidence-based guidelines. Pursue partnership pathways with established calcium channel blocker manufacturers for extended-release formulation technology licensing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive API supply and multi-dosage formulation scale. Long-term viability hinges on regulatory compliance infrastructure and specialist center relationships rather than novel mechanistic targets. Acquisition focus should center on mid-tier cardiovascular specialists with established Japanese PMDA pharmacovigilance pathways. Monitor FDA proarrhythmic risk assessment guidance evolution as the primary inflection signal for next-generation calcium channel modulator development viability.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Pfizer and AstraZeneca leverage polymer matrix expertise to reduce dosing frequency and improve adherence metrics in outpatient settings. |
| API Manufacturing Scale-Up | Backward integration into dihydropyridine production mitigates supply concentration risk in Chinese coastal provinces. |
| Specialist Center Partnership | Cleveland Clinic and Mayo Clinic referral networks standardize calcium channel blocker selection across United States academic medical centers. |
| Remote Monitoring Integration | Wearable ECG device partnerships enable preemptive dosing adjustments and create differentiated service revenue streams. |
| Regulatory Compliance Investment | Thorough QT study capabilities accelerate FDA submission timelines for novel anti-ischemic agents. |
Research Methodology
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and specialist cardiologists provided ongoing calibration throughout the analysis. Primary interviews with these stakeholders combined with secondary validation from FDA cardiovascular safety guidance documents, EMA Committee for Medicinal Products for Human Use standards, Japan PMDA pharmacovigilance filings, and ClinicalTrials.gov registry data. Bottom-up patient population modeling and top-down therapeutic class revenue triangulation anchored market size estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from historical growth pattern analysis and forward-looking adoption curve modeling incorporated inputs from calcium channel blocker prescription volume trends and specialist cardiology center expansion rates.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA cardiovascular safety regimes; material policy shifts would require re-modeling of development timeline assumptions and post-market surveillance cost structures. Revision becomes warranted when FDA proarrhythmic risk assessment guidance crosses thresholds that alter Phase III investment viability for novel calcium channel modulators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Tachycardia Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
US Statin Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Stroke Management Market
Cardiovascular
Vasculitis Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market