
 Copper Sulphate Market | 2026-2036
Copper Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Sulphate Market Analysis
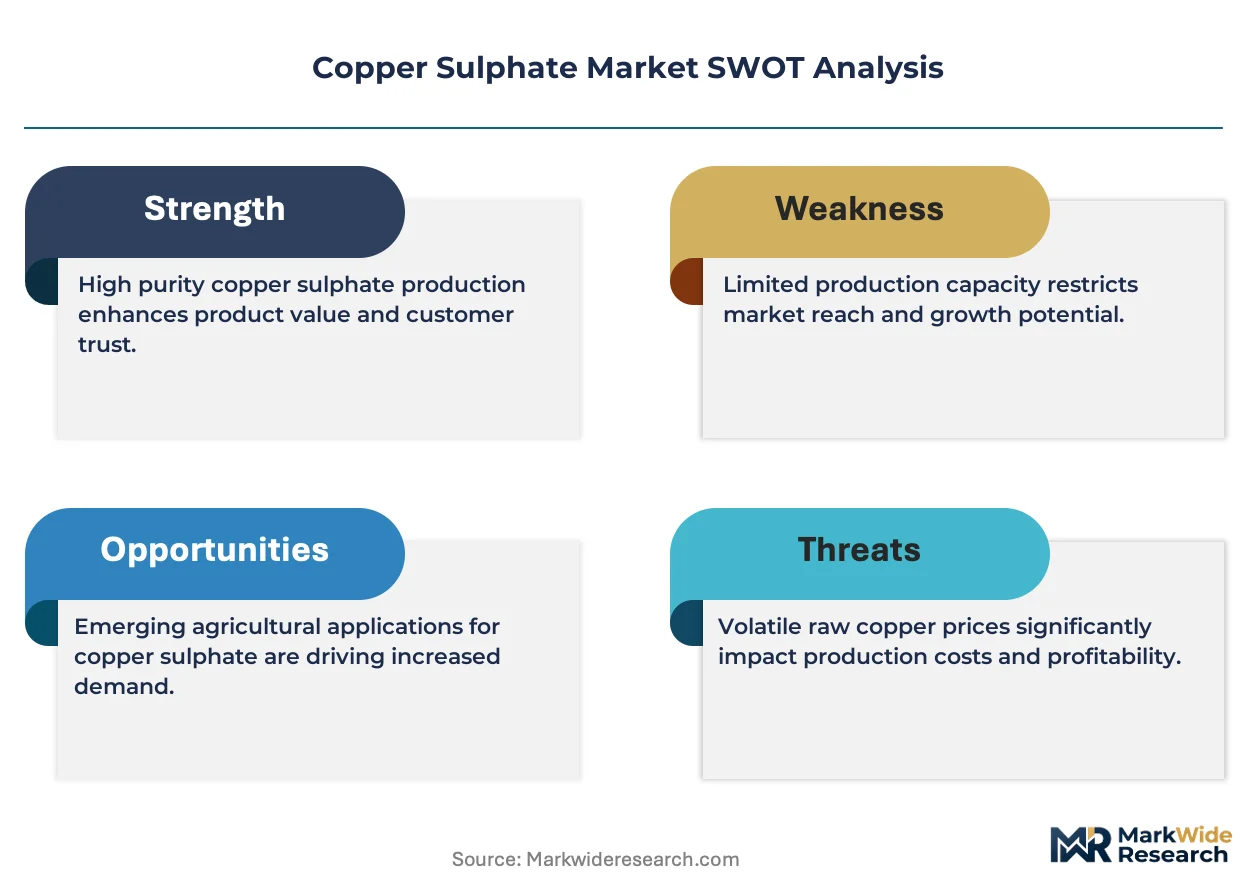
ISO 22000 certification for food-grade copper sulphate is collapsing the supplier base, as smaller producers lack the analytical infrastructure to verify heavy-metal limits below 10 ppm. Sumitomo Metal Mining Co., Ltd. leverages captive copper smelting in Japan to sustain pharmaceutical-grade output with documented batch traceability. BASF SE anchors European supply through backward integration into copper refining and proprietary crystallization protocols.
Copper sulphate denotes a blue crystalline salt with the chemical formula CuSO₄·5H₂O, produced through the reaction of copper oxide or scrap with sulfuric acid followed by controlled evaporation and crystallization; the pentahydrate form delivers 25.5% nominal copper content and functions primarily as a micronutrient additive, algaecide, and electroplating electrolyte. Crystal-grade material dominates value capture in pharmaceutical and high-purity industrial applications, while powder formulations lead volume in agricultural fungicide blending where dissolution speed matters less than cost. Water treatment applications are expanding fastest in municipal systems, driven by stricter effluent copper limits that favor precise dosing over bulk alternatives.
EPA registration under FIFRA governs agricultural fungicide formulations in the United States, while REACH restricts impurities in European industrial grades; China's GB standards for feed additives impose parallel purity floors that reshape export eligibility. ECHA classification of copper compounds as reproductive toxicants is forcing reformulation investments among fungicide blenders. Stakeholders must monitor regulatory divergence on crystallization-derived versus electrowinning-derived material, as origin-based distinctions are hardening in premium segments.
Market Dynamics
Regulatory divergence on heavy-metal thresholds is fragmenting the supplier base, as REACH, EPA FIFRA, and China's GB standards impose incompatible purity verification protocols that favor integrated copper refiners over standalone chemical processors.
Growth Catalysts
- Soil micronutrient supplementation:China's agricultural intensification programs mandate copper-enriched fertilizers for wheat and rice belts, generating sustained offtake from provincial blending facilities.
- REACH reproductive toxicity reclassification:ECHA's 2023 hazard designation forces fungicide formulators to source higher-purity crystalline grades, compressing the addressable supplier pool to certified refiners.
- Municipal algaecide conversion:US water utilities facing phosphorus discharge limits are substituting copper-based algae control for phosphonate chemistries in reservoir management.
Market Restraints
- Copper scrap feedstock volatility:Secondary copper supply fluctuations in China and Chile directly impact sulfuric acid leaching economics for sulfate producers without captive smelting.
- Electrowinning substitution in electroplating:Acid copper plating baths increasingly favor direct electrowon cathode dissolution over purchased sulfate crystals, compressing industrial-grade demand.
- ISO 22000 certification concentration:Food-grade heavy-metal testing infrastructure costs above $2 million per facility exclude regional Chinese and Indian processors from export-qualified supply.
Strategic Opportunities
- Pharmaceutical-grade crystallization:Documented batch traceability for parenteral nutrition applications commands 4-5x agricultural-grade pricing, rewarding investment in GMP-compliant production lines.
- Closed-loop mine water treatment:Chilean and Peruvian copper concentrators require on-site sulfate generation for cyanide destruction and heavy-metal precipitation, creating captive demand clusters.
- EU Green Deal circularity mandates:CSRD reporting requirements on industrial byproduct valorization incentivize European smelters to monetize acid plant output as certified sulfate rather than neutralization waste.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS operation and heavy-metal speciation expertise required for sub-10 ppm verification exceeds availability in traditional mining chemistry labor pools.
- Dual-registration burden:FIFRA pesticide and TSCA industrial chemical filings for multi-use products demand parallel toxicology studies that extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Sulphate Market |
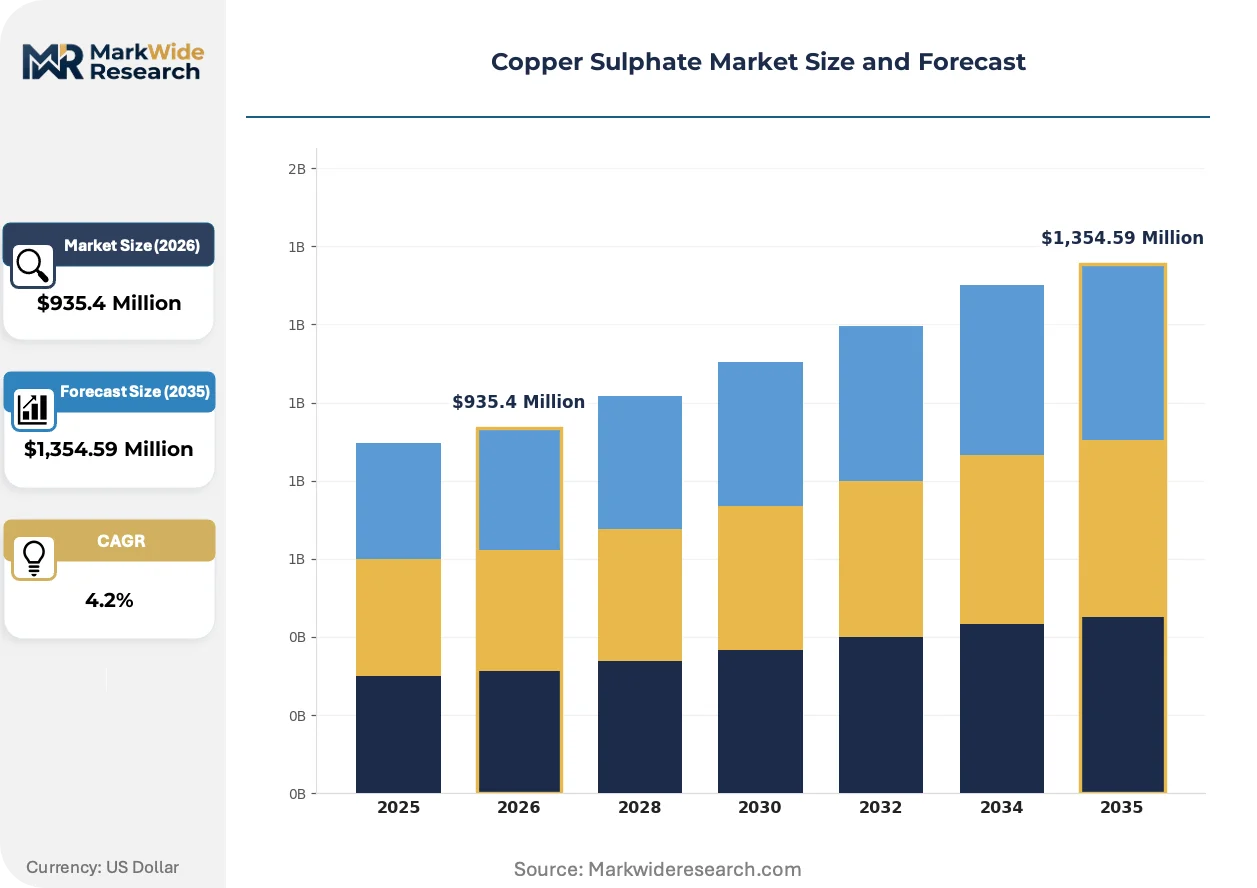
| Market Size in 2026 | $935.4 Million |
| Market Size in 2035 | $1,354.59 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystals, Powder, Granules, Solution Application: Agricultural Chemicals, Textile Dyeing, Water Treatment, Fungicides End User: Agriculture, Industrial, Pharmaceutical, Construction Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | Sumitomo Metal Mining Co., Ltd., JX Nippon Mining & Metals Corp., Highnic Group, BASF SE, Beneut Enterprise Co. Ltd., Old Bridge Chemicals Inc., Noah Technologies Corp., Changsha Haolin Chemicals Co. Ltd., Glencore plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Sulphate Market Emerging Trajectories
Process intensification in copper refining and crystallization control is compressing the cost-performance frontier between commodity agricultural grades and high-purity specialty tiers, enabling new entrants to challenge incumbent positioning.
Membrane electrolysis for direct copper sulfate electrosynthesis is miniaturizing the capital footprint for regional production units. Indonesian and Zambian mining juniors are piloting containerized systems that bypass traditional smelter-sulfuric acid infrastructure. This distributed architecture is compressing freight costs to East African agricultural markets previously served by Chinese export volumes.
ECHA's 2024 update to REACH Annex XVII restricted substances list adds copper compounds to candidate SVHC status for aquatic toxicity. German and Dutch formulators are accelerating reformulation timelines for fungicide blends, shifting procurement specifications toward electrowinning-derived material with documented lower arsenic content. The premium crystalline segment is absorbing compliance costs through supply chain consolidation.
Consolidated procurement by Brazilian and Argentinian grain cooperatives is displacing fragmented distributor networks across Mercosur agricultural zones. These buying groups now contract directly with Chilean refiners for seasonal volume commitments, bypassing traditional Miami-based trading intermediaries. The channel compression is most visible in soybean fungicide pre-mix procurement for the Cerrado expansion belt.
Copper Sulphate Market Segmentation
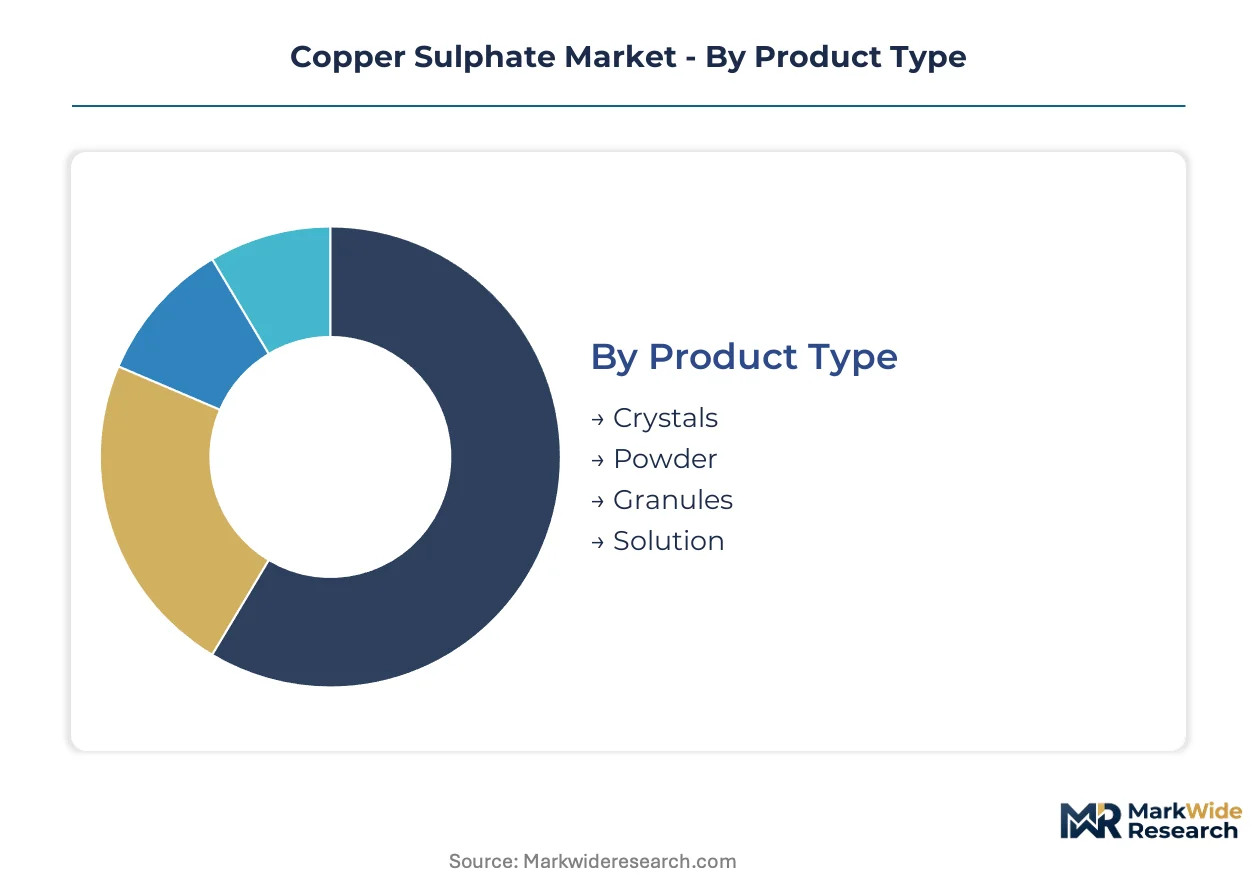
Regulatory thresholds for heavy-metal content and crystallization purity are fragmenting copper sulphate supply into incompatible grade tiers. Each segment now carries distinct certification burdens that reshape procurement patterns across agricultural, pharmaceutical, and industrial channels.
Product Type:
REACH Annex XVII restrictions and EPA FIFRA registration requirements enforce divergent purity protocols across physical forms, compressing the qualified supplier base for premium grades.
- Crystals:Pentahydrate crystalline material delivers 25.5% nominal copper content with documented batch traceability. Pharmaceutical and electroplating applications in Germany and Japan concentrate demand here, driven by ECHA reproductive toxicity reclassification forcing higher-purity sourcing.
- Powder:Milled crystalline product optimized for rapid dissolution in agricultural fungicide blending. China's provincial fertilizer facilities generate sustained offtake, though dissolution speed matters less than cost in this tier.
- Granules:Compact agglomerated form reduces dust generation during bulk handling. Brazilian grain cooperatives increasingly specify granules for Cerrado soybean fungicide pre-mixes.
- Solution:Pre-dissolved aqueous preparation for precise dosing in municipal water treatment systems. US utilities facing phosphorus discharge limits favor this form for reservoir algae control.
Crystals handle the majority of throughput; Solution is the fastest mover on share.
Application:
Cost stratification separates commodity agricultural grades from certified specialty tiers, with analytical infrastructure investments determining segment accessibility.
- Agricultural Chemicals:Dominant consumption channel encompassing soil micronutrient supplements and fungicide formulations. China's wheat and rice belt intensification programs mandate copper-enriched fertilizers, generating sustained provincial blending facility offtake.
- Water Treatment:Municipal and industrial effluent management applications expanding most quickly. Stricter copper discharge limits in US and EU systems favor precise dosing over bulk alternatives.
- Fungicides:Crop protection formulations requiring EPA FIFRA registration or REACH compliance. ECHA's aquatic toxicity candidate SVHC status is accelerating German and Dutch reformulation timelines.
- Textile Dyeing:Mordant and color fixation applications in synthetic fiber processing. Indian and Bangladeshi textile clusters maintain steady demand for standard-grade material.
Agricultural Chemicals commands the volume base; Water Treatment is climbing the fastest on share expansion.
End User:
Customer type determines certification tier, with ISO 22000 and GMP infrastructure costs excluding regional processors from pharmaceutical and food-grade supply.
- Agriculture:Provincial blending facilities, grain cooperatives, and plantation operations across Mercosur and Southeast Asia. Consolidated procurement by Brazilian and Argentinian buying groups now bypasses traditional trading intermediaries.
- Pharmaceutical:Parenteral nutrition and API manufacturing requiring documented batch traceability. GMP-compliant production lines command pricing multiples over agricultural grades.
- Industrial:Electroplating, metal finishing, and chemical synthesis operations. Acid copper plating baths increasingly favor direct electrowon cathode dissolution over purchased sulfate crystals.
- Construction:Wood preservation and concrete additive applications. Standard-grade powder dominates this price-sensitive segment.
Agriculture absorbs the dominant share of volume; Pharmaceutical is gaining share fastest on margin expansion.
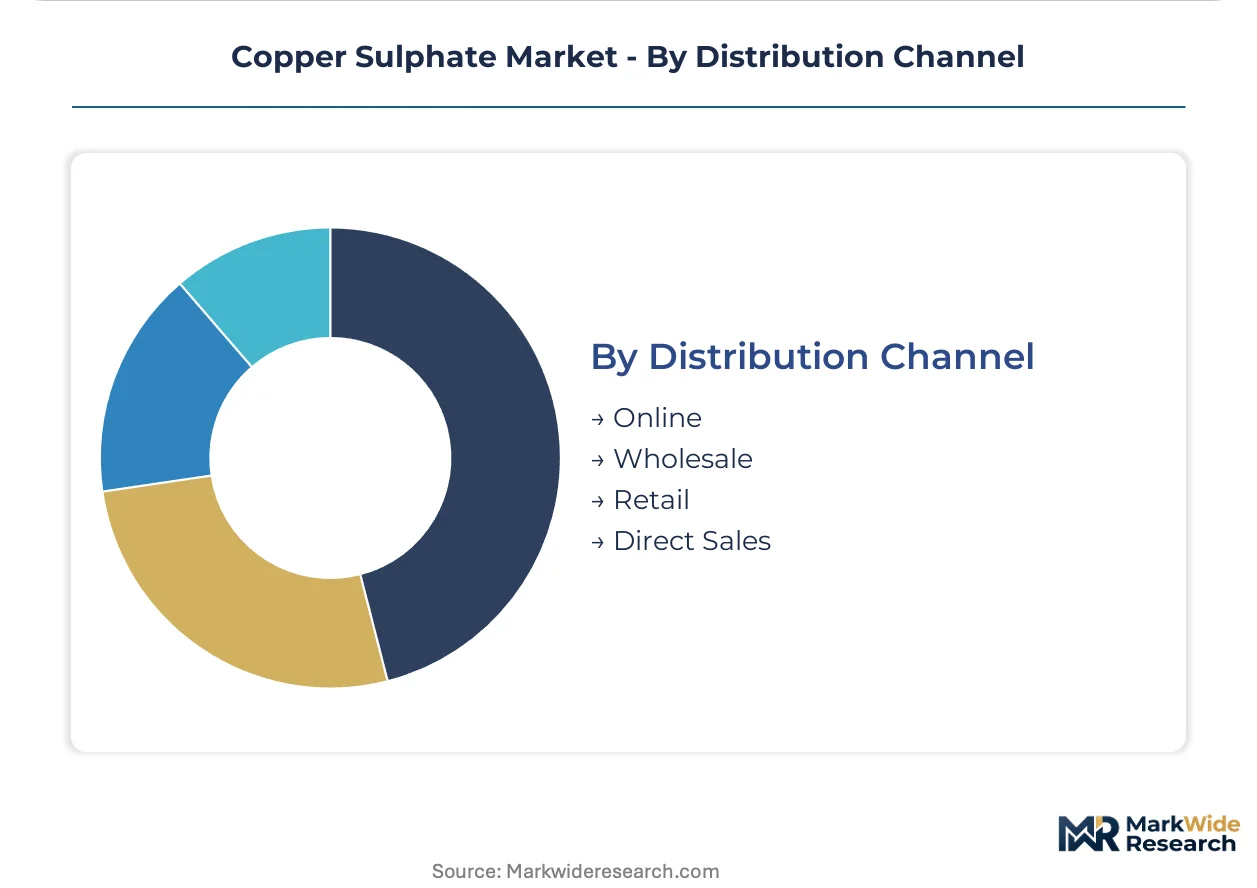
Distribution Channel:
Supply chain configuration determines channel viability, with certification documentation requirements favoring direct relationships over fragmented intermediary networks.
- Direct Sales:Refiner-to-formulator contracts for certified grades requiring batch documentation. Chilean refiners increasingly serve Brazilian cooperatives through seasonal volume commitments.
- Wholesale:Bulk volume distribution through chemical distributors and trading houses. Miami-based intermediaries are losing share to channel compression in Mercosur agricultural zones.
- Retail:Small-package sales to specialty growers and maintenance operations. Limited to standard agricultural and consumer algaecide grades.
- Online:Emerging platform-based procurement for standardized specifications. ISO 22000 and REACH documentation challenges constrain penetration in certified grades.
Direct Sales captures the primary volume flow; Online is expanding most quickly from a small base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government agricultural intensification programs and tightening purity regulations are redrawing procurement geographies for copper sulphate. National fertilizer mandates and water treatment infrastructure investments concentrate demand in specific industrial corridors.
China
Provincial blending facilities in Shandong and Jiangsu provinces generate sustained offtake for wheat and rice belt fertilization programs. GB standards for feed additives impose purity floors that reshape export eligibility for domestic refiners. The Yangtze River Delta agrochemical manufacturing clusters absorb substantial crystalline-grade volumes for fungicide formulation.
United States
EPA FIFRA registration requirements govern agricultural fungicide formulations while municipal utilities facing phosphorus discharge limits convert to copper-based algae control. The Ohio River Valley electroplating corridor maintains steady industrial-grade consumption. Chicago-based water treatment distributors increasingly specify pre-dissolved solutions for reservoir management.
Germany
ECHA's REACH reproductive toxicity reclassification forces fungicide formulators to source higher-purity crystalline grades from certified refiners. The Ruhr industrial basin concentrates electroplating demand for documented batch-traceable material. Bavarian pharmaceutical manufacturers command premium pricing for parenteral nutrition applications.
Brazil
Consolidated procurement by grain cooperatives across the Cerrado expansion belt displaces fragmented distributor networks for soybean fungicide pre-mixes. ANVISA registration requirements parallel EPA protocols for agricultural chemical imports. São Paulo state blending facilities now contract directly with Chilean refiners for seasonal volume commitments.
Japan
METI guidelines on industrial chemical purity support pharmaceutical-grade crystallization with documented batch traceability. The Kansai region's captive copper smelting infrastructure sustains high-purity output for domestic electroplating and API manufacturing. Osaka-based refiners leverage backward integration into copper refining to meet ECHA-equivalent specifications.
Copper Sulphate Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with integrated copper refiners holding structural advantages in purity-verified segments. The supplier base compresses around ISO 22000 and GMP compliance investments that exclude regional processors. Three archetypes dominate: captive smelter operators with acid plant monetization, standalone chemical processors serving commodity agricultural grades, and pharmaceutical-grade crystallization specialists. Capacity expansion and supply chain consolidation represent the dominant competitive vectors as formulators seek documented provenance.
Among Japanese-listed mining-chemical conglomerates, Sumitomo Metal Mining Co., Ltd. and JX Nippon Mining & Metals Corp. exemplify the captive smelter archetype with integrated acid plant output. BASF SE anchors European supply through proprietary crystallization protocols and backward integration into copper refining. These three occupy positions where documented batch traceability and REACH-compliant purity verification command pricing multiples over agricultural-grade alternatives.
| Leading Market Players |
|---|
| Sumitomo Metal Mining Co., Ltd. |
| JX Nippon Mining & Metals Corp. |
| Highnic Group |
| BASF SE |
| Beneut Enterprise Co. Ltd. |
| Old Bridge Chemicals Inc. |
| Noah Technologies Corp. |
| Changsha Haolin Chemicals Co. Ltd. |
| Glencore plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Chilean refiners and Brazilian grain cooperatives lock in both supply access and price visibility for crystalline-grade material, insulating premium tiers from copper scrap volatility while exposing standard agricultural grades to spot-market swings in Chinese sulfuric acid leaching economics.
Pricing Analysis
Certification level creates the primary spread across copper sulphate tiers, with ISO 22000 and GMP-compliant pharmaceutical grades commanding substantial premiums over agricultural powder formulations. Three-tier pricing structure across pharmaceutical, industrial, and agricultural levels reflects analytical infrastructure investments and batch traceability documentation. Cost compression in standard agricultural powder is intensifying because Chinese provincial blending facilities prioritize dissolution speed over purity verification. Smallholder cooperatives in Mercosur zones exhibit highest price sensitivity, while Bavarian parenteral nutrition manufacturers show least sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites sulfuric acid feedstock flows to Southeast Asian agrochemical clusters, creating logistical vulnerability for Indonesian membrane electrolysis pilots. Supply concentrates in Chile, China, and Japan, with captive copper smelting infrastructure determining grade accessibility. Secondary copper scrap from Chilean concentrators and Chinese recycling networks feeds sulfate production, tethering output to metal price cycles. Tariff exposure on US EPA FIFRA-registered formulations threatens cross-border agricultural chemical trade. Distribution runs through direct refiner-to-formulator contracts for certified grades, with wholesale chemical distributors retaining commodity agricultural volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified analytical services and batch-documentation subscriptions are expanding faster than base chemical production, transforming copper sulphate from commodity transaction to compliance-linked service relationship.
For Market Incumbents: Fortify positioning through backward integration into copper refining and captive acid plant monetization. Expand crystallization capacity in Japan and Germany to meet ECHA reproductive toxicity reclassification demand. Invest in ICP-MS infrastructure to exclude regional Chinese competitors from pharmaceutical-grade supply. Deepen direct contracts with Brazilian grain cooperatives to displace Miami-based trading intermediaries. For New Entrants and Emerging Players: Differentiate on membrane electrolysis miniaturization for containerized regional production in East African agricultural markets. Target municipal water treatment solution sales in US Midwest utilities facing phosphorus discharge limits. Pursue Indonesian and Zambian mining juniors as anchor customers for cyanide destruction and heavy-metal precipitation applications. Lead with precise dosing service models rather than bulk crystal commodity positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade crystallization specialists with documented GMP batch traceability. Five-to-ten-year viability favors integrated copper refiners over standalone chemical processors exposed to scrap feedstock volatility. Acquisition focus should center on Japanese and German facilities with ECHA-equivalent certification infrastructure. Watch for ECHA SVHC final listing on copper compounds as inflection indicator for reformulation-driven grade substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive smelting secures acid plant output for sulfate monetization under EU Green Deal circularity mandates. |
| Membrane Electrolysis Miniaturization | Containerized systems bypass traditional smelter infrastructure for East African agricultural market access. |
| ISO 22000 Certification Investment | Heavy-metal testing infrastructure excludes regional competitors from food-grade export-qualified supply. |
| Direct Refiner-Cooperative Contracts | Seasonal volume commitments with Brazilian buying groups displace Miami-based trading intermediaries. |
| Pharmaceutical-Grade Crystallization Expansion | GMP-compliant production lines command pricing multiples for parenteral nutrition applications in Germany and Japan. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the copper sulphate value chain, including plant managers at Chilean and Chinese refiners, procurement leads at Brazilian grain cooperatives, regulatory affairs specialists navigating EPA FIFRA and REACH compliance, and technical R&D directors at electroplating facilities. Secondary validation drew from customs and trade flow databases, ECHA regulatory filings, SEC 10-K disclosures from listed mining-chemical conglomerates, and GB standards documentation from Chinese feed additive regulators. Bottom-up volume modeling triangulated against top-down copper consumption forecasts.
Across the analysis window, projections incorporate grade-tier segmentation by crystallization purity, end-use industry stratification across agricultural chemicals and pharmaceutical applications, packaging format differentiation between bulk powder and pre-dissolved solutions, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Forecast inputs included Chinese agricultural intensification program mandates, US municipal water treatment conversion rates, and ECHA SVHC regulatory timeline scenarios.
Material uncertainties — copper scrap feedstock price spikes, REACH Annex XVII expansion to final SVHC status, and membrane electrolysis technology diffusion rates — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory compliance cost pass-through and certification infrastructure investment continuity. Revision becomes warranted when ECHA reproductive toxicity classification triggers mandatory reformulation timelines across German and Dutch fungicide blenders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market