
 Sodium Nitrate Market | 2026-2036
Sodium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Nitrate Market Intelligence
A multi-source procurement strategy is shifting toward captive nitrate production among large chemical conglomerates. SQM leverages its caliche ore deposits in Chile's Atacama Desert to sustain low-cost natural sodium nitrate extraction. Deepak Nitrite Limited anchors Indian supply through backward integration into nitric acid and sodium nitrite precursors. BASF competes on pharmaceutical-grade purification standards for European food and drug manufacturers.
Sodium nitrate is an inorganic alkali metal salt with the chemical formula NaNO₃, typically manufactured through the neutralization of nitric acid with sodium carbonate or sodium hydroxide, yielding a white crystalline solid with melting point near 308°C and solubility of 92 grams per 100 milliliters of water at 25°C. Its primary commercial purpose centers on nitrogen donation for fertilizers, oxidation support in industrial processes, and antimicrobial preservation in cured meat products. The fertilizers segment dominates volume offtake but carries thin margins tied to commodity nitrogen pricing cycles, while pharmaceutical-grade material commands premium pricing due to stringent USP and EP monograph compliance. Food preservation applications occupy a stable mid-tier position, with demand anchored by traditional cured meat processors in Europe and North America who resist substitution despite clean-label pressures.
EPA standards under the Clean Water Act and OSHA permissible exposure limits shape industrial handling protocols for sodium nitrate dust and effluent in United States manufacturing facilities, while REACH registration and the EU Fertilizing Products Regulation govern purity thresholds and environmental release criteria across European value chains. India's BIS certification requirements for fertilizer-grade material create non-tariff barriers that favor domestic producers such as Deepak Nitrite Limited over importers. Stakeholders must monitor divergence between pharmaceutical-grade specification tightening and fertilizer-grade commoditization to allocate capital across the grade spectrum.
Market Dynamics
Captive nitrate production among large chemical conglomerates is reshaping procurement patterns, as fertilizer-grade commoditization squeezes margins while pharmaceutical-grade purity thresholds tighten under evolving EPA and REACH frameworks.
Growth Catalysts
- Brazilian agricultural expansion:Soybean and corn producers in Mato Grosso and Paraná states are expanding nitrogen-efficient fertilizer applications, driving offtake for sodium nitrate soil amendments amid volatile urea pricing cycles.
- REACH purity escalation:The EU Fertilizing Products Regulation is tightening contaminant thresholds for food-grade material, forcing upgrade investments that expand the addressable premium-grade market.
- East Asian dye manufacturing:Chemical corridors around Weifang in Shandong Province are absorbing captive nitrate output for azo dye intermediates and explosive chemical precursors.
Market Restraints
- Caliche ore concentration:Natural sodium nitrate extraction remains geographically trapped in Chile's Atacama Desert, creating single-source vulnerability for low-cost supply.
- Ammonium nitrate substitution:Industrial explosives manufacturers in mining sectors are displacing sodium nitrate with higher-energy-density alternatives, compressing volume in traditional oxidation applications.
- Clean-label meat processing:European and North American cured meat processors face consumer pressure to reduce synthetic preservative use, threatening stable food-grade demand.
Strategic Opportunities
- Indian pharmaceutical-grade gap:CDSCO and BIS certification requirements for injectable-grade material remain underpenetrated by domestic producers, creating import substitution potential.
- Dual-use explosive precursor controls:EU regulation on explosives precursors is diverting demand toward tracked, certified supply chains that favor established pharmaceutical-grade producers.
- Solar thermal salt storage:Molten salt energy storage systems are converging with sodium nitrate formulations for high-temperature heat transfer fluids in concentrated solar power installations.
Industry Challenges
- Pharmaceutical USP/EP compliance timelines:Batch certification for injectable-grade material requires extended validation cycles that strain working capital for mid-scale producers.
- Legacy effluent handling infrastructure:United States manufacturing facilities face OSHA permissible exposure limit enforcement for sodium nitrate dust, requiring capital-intensive ventilation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Nitrate Market |
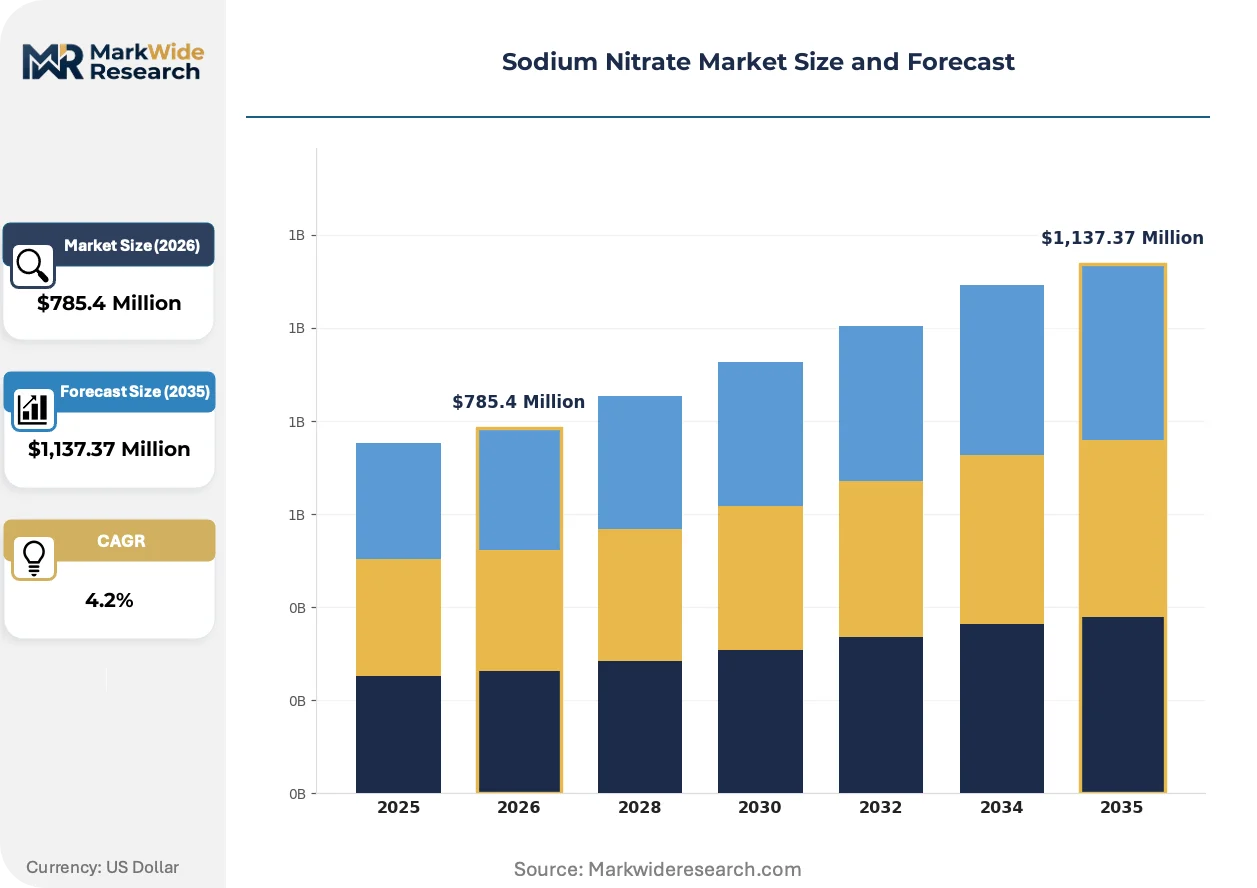
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,137.37 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Food Preservation, Pharmaceuticals, Chemical Manufacturing Application: Agricultural Use, Industrial Use, Food Industry, Healthcare End User: Agricultural Producers, Food Processors, Pharmaceutical Companies, Chemical Industries Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ACF BAQUEDANO, Acf Nitratos S.A, SQM, Quality Chemicals S.L, Jost Chemical Co., BASF, Deepak Nitrite Limited, Shijiazhuang Fengshan Chemical Co. Ltd., Weifang Haiye Chemistry And Industry Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Nitrate Market Strategic Shifts & Innovations
Process intensification in nitric acid neutralization and crystallization is compressing energy intensity, while regulatory-grade differentiation is fragmenting what was historically a commodity market into distinct purity-tier value chains.
Membrane-based crystallization technology is converging with continuous manufacturing platforms to reduce water consumption and impurity carryover in pharmaceutical-grade production. European and North American food and drug manufacturers are adopting these systems to preemptively meet tightening EP monograph specifications. The structural consequence is a widening capability gap between batch-oriented fertilizer-grade producers and continuous-process pharmaceutical specialists.
EPA's evolving guidelines under the Clean Water Act are tightening effluent nitrate discharge limits for manufacturing facilities in the United States. Industrial processors must install advanced biological denitrification or ion-exchange recovery systems to maintain operating permits. Food-grade and pharmaceutical-grade producers with existing purification infrastructure are adapting more readily than fertilizer-grade operations, accelerating grade-based competitive stratification.
Buyer concentration among large agricultural cooperatives in Brazil and Argentina is compressing contract negotiation cycles and demanding multi-year price locks. Traditional spot-market traders are losing share to direct procurement relationships with caliche ore extractors and integrated nitric acid producers. This pattern is most visible in the Paraná River basin, where soybean crushing conglomerates now contract directly with Chilean suppliers for containerized fertilizer-grade shipments.
Sodium Nitrate Market Segmentation
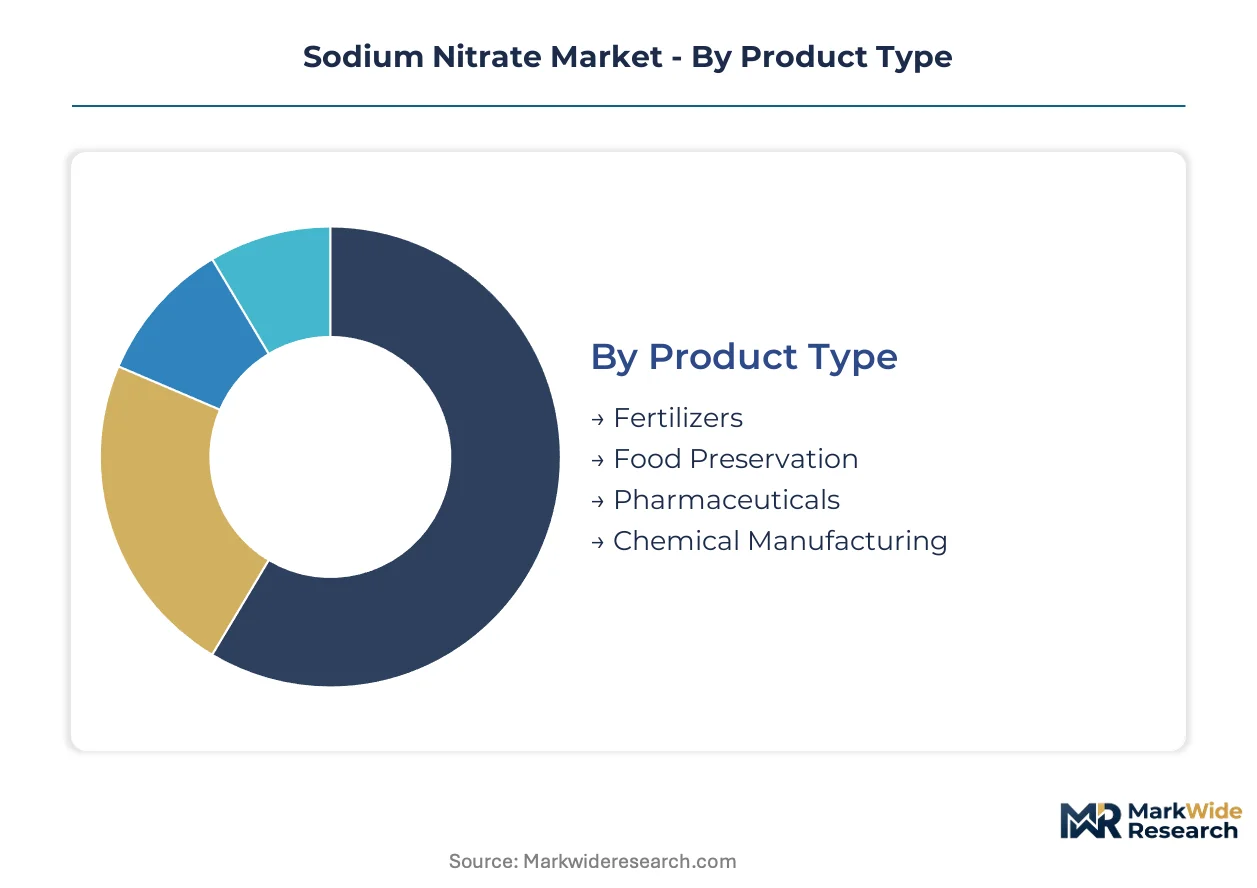
Sodium nitrate grades fragment sharply by purity specification, with fertilizer-grade commanding volume and pharmaceutical-grade extracting margin. Buyers select across this spectrum based on regulatory compliance burden and end-use certification requirements rather than commodity pricing alone.
Product Type:
Cost tier determines procurement patterns, as buyers trade purity premiums against compliance mandates and application criticality.
- Fertilizers:Technical-grade material with 98-99% purity serves nitrogen-deficient soils in Brazil's Cerrado and Argentina's Pampas. Agricultural cooperatives in Mato Grosso negotiate multi-year contracts directly with Chilean caliche extractors to bypass distributor markups amid volatile urea cycles.
- Pharmaceuticals:Injectable-grade sodium nitrate meets USP and EP monograph standards with heavy metal limits below 10 ppm. CDSCO certification requirements in India and FDA compliance in the United States restrict viable suppliers to continuous-process specialists with validated batch documentation.
- Food Preservation:Cured meat processors in Europe and North America specify food-grade material with antimicrobial efficacy against Clostridium botulinum.
- Chemical Manufacturing:Azo dye intermediates and explosives precursors absorb industrial-grade output from Shandong Province chemical corridors.
Volume sits with Fertilizers; growth tilts toward Pharmaceuticals.
Application:
Application maturity separates legacy oxidation uses from emerging energy storage formulations.
- Agricultural Use:Soil amendment applications concentrate in South American soybean-corn rotation systems where sodium nitrate's immediate nitrogen availability outperforms slow-release alternatives during critical growth windows.
- Industrial Use:Molten salt thermal storage systems for concentrated solar power installations are absorbing technical-grade formulations as heat transfer fluids in Spain and Morocco.
- Food Industry:Traditional cured meat processing resists substitution despite clean-label pressures from European retail chains.
- Healthcare:Dialysis solutions and vasodilator formulations require injectable-grade material with endotoxin limits below 2.5 EU/g.
Application breadth runs widest in Industrial Use; regulatory stringency peaks in Healthcare.
End User:
Customer scale dictates contract structure, with agricultural conglomerates demanding direct procurement and pharmaceutical buyers insisting on audit rights.
- Agricultural Producers:Large cooperatives in Brazil's Paraná River basin bypass traditional traders to secure containerized shipments from Atacama Desert operations.
- Pharmaceutical Companies:European drug manufacturers impose extended validation cycles and on-site quality audits that exclude batch-oriented fertilizer producers.
- Food Processors:North American cured meat specialists maintain stable offtake despite consumer pressure to reduce synthetic preservatives.
- Chemical Industries:Weifang-based dye manufacturers and explosives formulators source captive nitrate from integrated nitric acid operations.
Contract leverage concentrates with Agricultural Producers; certification burden falls heaviest on Pharmaceutical Companies.
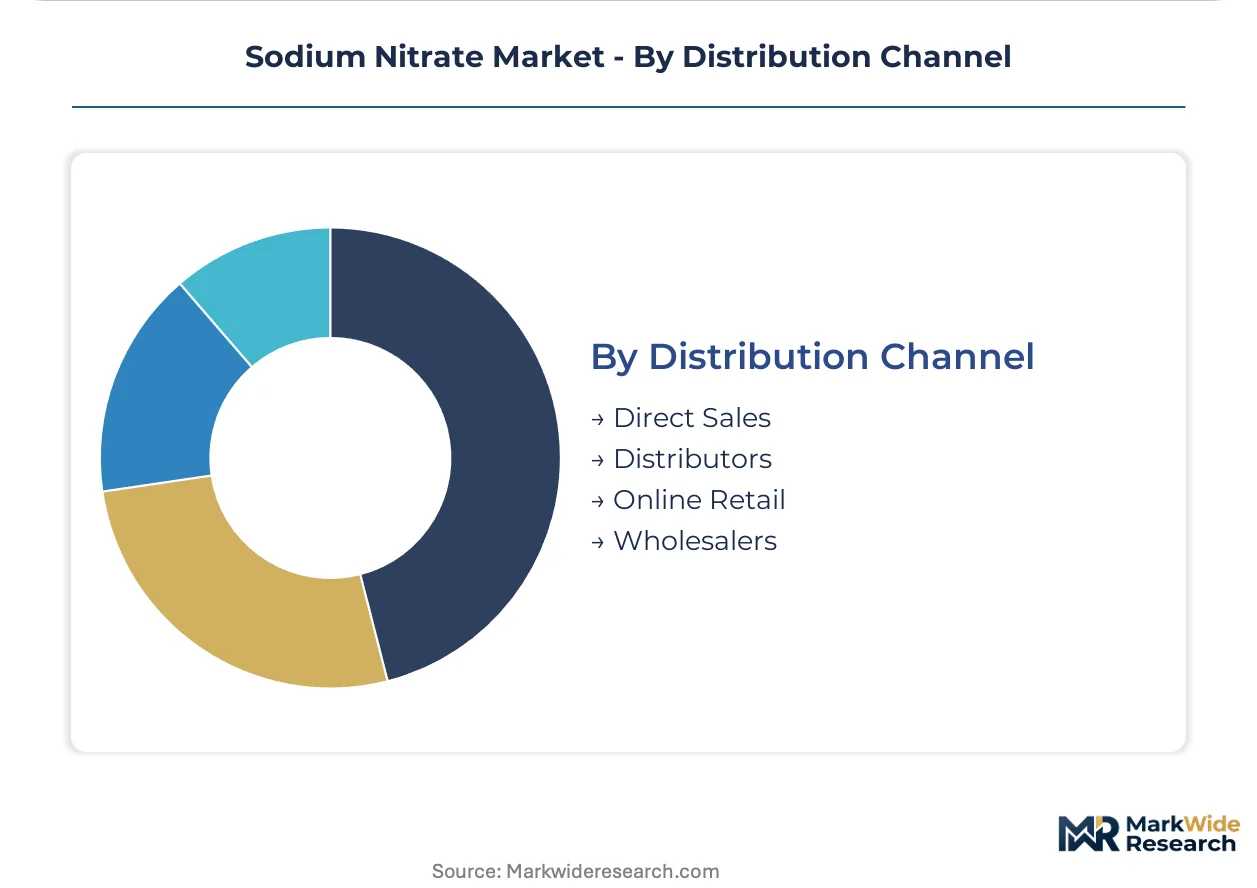
Distribution Channel:
Channel selection tracks shipment scale and documentation requirements, with bulk fertilizer moving direct and specialty grades requiring intermediary custody verification.
- Direct Sales:Containerized fertilizer-grade shipments from Chilean ports to Brazilian crushing conglomerates eliminate distributor margins.
- Distributors:Regional chemical distributors in India manage BIS certification documentation for fertilizer-grade imports.
- Wholesalers:Aggregated procurement for mid-scale food processors in Europe consolidates smaller volume requirements.
- Online Retail:Laboratory-grade quantities for research institutions and small-scale pharmaceutical formulators.
Shipment scale favors Direct Sales; documentation complexity sustains Distributor relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama Desert caliche ore deposits anchor low-cost natural sodium nitrate extraction. Regional demand patterns diverge sharply between agricultural nitrogen substitution in South America and pharmaceutical-grade purification requirements in Europe and North America.
Chile
Caliche ore mining in the Atacama Desert sustains the world's lowest-cost natural sodium nitrate supply. SQM operates under Chile's environmental licensing framework administered by the Superintendency of the Environment. Antofagasta and Tarapacá regions concentrate extraction and primary processing infrastructure serving export markets.
Brazil
Soybean and corn producers in Mato Grosso and Paraná states drive fertilizer-grade offtake for nitrogen-efficient soil amendments. ANVISA regulates food-grade sodium nitrate imports under Resolution RDC No. 239 for meat preservative applications. The Paraná River basin hosts crushing conglomerates that contract directly with Chilean suppliers for containerized shipments.
China
Shandong Province chemical corridors around Weifang absorb captive nitrate output for azo dye intermediates and explosives precursors. MEE enforces wastewater discharge standards under the Water Pollution Prevention and Control Law that tighten effluent nitrate limits. The province's integrated nitric acid producers feed regional dye and specialty chemical value chains.
Germany
Pharmaceutical and food manufacturers in North Rhine-Westphalia and Bavaria demand EP monograph-compliant material for injectable formulations and cured meat processing. ECHA administers REACH registration requirements that escalate purity thresholds for food-grade imports. The Rhine-Ruhr industrial cluster hosts BASF operations serving European drug and food clients.
India
Deepak Nitrite Limited anchors domestic supply through backward integration into nitric acid precursors in Gujarat and Maharashtra. CDSCO certification requirements for pharmaceutical-grade material and BIS standards for fertilizer-grade imports create non-tariff barriers favoring domestic producers. Mumbai-Pune chemical belt concentrates formulation and distribution infrastructure.
Sodium Nitrate Market Key Industry Players
Global majors compete with regional champions across grade-specific purification capabilities. The vendor base stratifies between Atacama-based natural extractors, European pharmaceutical specialists, and Asian integrated chemical producers. Three archetypes dominate: caliche ore extractors with geological cost advantages, nitric acid integrators with captive feedstock control, and pharmaceutical-grade purification specialists with validated batch documentation. Competitive moves center on backward integration into nitric acid precursors and multi-year contract locks with agricultural conglomerates.
Within the natural extraction archetype, SQM and ACF Nitratos represent Chilean caliche-based supply. Deepak Nitrite exemplifies the Asian integrated model with in-house nitric acid and sodium nitrite precursors. BASF occupies the pharmaceutical-grade purification tier serving European food and drug manufacturers with EP monograph compliance infrastructure.
| Leading Market Players |
|---|
| ACF BAQUEDANO |
| Acf Nitratos S.A |
| SQM |
| Quality Chemicals S.L |
| Jost Chemical Co. |
| BASF |
| Deepak Nitrite Limited |
| Shijiazhuang Fengshan Chemical Co. Ltd. |
| Weifang Haiye Chemistry And Industry Co., Ltd |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers anchored in Chile's Atacama Desert exercise asymmetric pricing power over fertilizer-grade offtake, while private-equity-rolled pharmaceutical specialists in Europe and North America capture certification premiums that commodity traders cannot match. This ownership-financing divide concentrates supply discipline among caliche extractors and fragments price-setting authority across purity tiers.
Pricing Analysis
Warranty and batch-certification bundling separates pharmaceutical-grade contracts from unbundled fertilizer spot transactions. Three-tier pricing structure across pharmaceutical, food, and fertilizer grades reflects divergent compliance burdens, with USP/EP monograph certification and FDA validation driving 40-60 point spreads between top and bottom tiers. Pricing pressure stems from Brazilian agricultural cooperatives demanding multi-year price locks that compress distributor margins. Agricultural producers exhibit highest price sensitivity, while pharmaceutical buyers prioritize audit rights and documentation over unit economics.
Supply Chain Analysis
Skilled technician availability constraints in Gujarat and Maharashtra chemical belts limit expansion velocity for Indian integrated producers seeking pharmaceutical-grade certification. Supply concentrates in Chile for natural extraction, China for captive chemical manufacturing, and Germany for pharmaceutical purification. Raw material dependencies span caliche ore deposits, nitric acid feedstock, and sodium carbonate reagents. Single-source vulnerability from Atacama Desert concentration creates geopolitical risk exposure. Distribution runs through direct containerized contracts for bulk fertilizer and specialized chemical distributors for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration and EU Fertilizing Products Regulation create barrier-to-entry moats that favor incumbents with existing validation infrastructure over capital-constrained challengers.
For Market Incumbents: Hedge against ammonium nitrate substitution in mining explosives by securing long-term offtake agreements with Brazilian soybean cooperatives in Mato Grosso. Deepen backward integration into nitric acid precursors to protect margin compression from volatile feedstock cycles. Prioritize CDSCO certification investment for injectable-grade capacity in India before domestic competitors close the pharmaceutical-grade gap. For New Entrants and Emerging Players: Begin with molten salt thermal storage formulations for concentrated solar power installations in Spain and Morocco, where technical-grade specifications avoid pharmaceutical compliance timelines. Target Indian pharmaceutical-grade production as the most penetrable white-space, given underpenetrated domestic CDSCO-certified supply. Pursue joint-venture structures with established nitric acid producers to bypass capital-intensive neutralization infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor continuous-process pharmaceutical specialists with validated EP monograph infrastructure in North Rhine-Westphalia and Bavaria, where regulatory escalation is accelerating capability gaps. Long-term viability over a 5-10 year window rests on positioning ahead of solar thermal salt storage scaling and pharmaceutical-grade import substitution in India. Watch ammonium nitrate displacement rates in Australian and South African mining sectors as inflection indicators for industrial-grade demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitric Acid | Deepak Nitrite's captive feedstock control in Gujarat insulates margin from commodity nitrogen volatility. |
| CDSCO Certification Investment | Injectable-grade validation opens Indian pharmaceutical demand currently served by European imports. |
| Long-term Supply Agreement | Direct contracts with Chilean caliche extractors bypass distributor markups for Brazilian agricultural cooperatives. |
| Membrane Crystallization Upgrade | Continuous manufacturing platforms reduce water consumption and impurity carryover for EP compliance. |
| Solar Thermal Salt Partnership | Molten salt energy storage formulations in Spain and Morocco diversify revenue beyond fertilizer commoditization. |
Research Approach
Multi-period observation of caliche ore extraction rates, nitric acid capacity additions, and REACH registration timelines anchored the trend analysis, supplemented by interviews with plant managers at Chilean extraction operations, procurement leads at Brazilian agricultural cooperatives, pharmaceutical regulatory affairs directors in Germany, and technical R&D directors at Indian chemical manufacturers. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA registration databases, and CDSCO certification records. Bottom-up grade-specific volume estimates triangulated against top-down nitrogen fertilizer consumption models.
Input-output matrices mapped nitric acid neutralization capacity to downstream grade-specific demand across fertilizer, pharmaceutical, food preservation, and industrial applications. Segmentation dimensions modeled include purity tier, end-use industry, regional production hub, and certification requirement cluster. CAGRs were derived from slope-consistency checks against historical nitrogen pricing cycles and forward-projected regulatory compliance investment schedules. Industry-specific forecast inputs incorporated urea price volatility correlations and solar thermal salt storage deployment pipelines.
Underlying measurement precision varies by segment; pharmaceutical-grade volume estimates carry tighter precision due to validated batch documentation requirements, while fertilizer-grade spot market transactions exhibit higher measurement error. Forecasts reflect assumptions regarding REACH implementation timelines, Brazilian agricultural credit availability, and Chinese environmental enforcement intensity. A small set of triggers warrants ongoing watch: ammonium nitrate substitution rates in mining, clean-label meat processing regulatory shifts in Europe, and solar thermal salt storage policy support in Mediterranean markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Global Lithium Carbonate Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
North America Titanium Dioxide Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Global Boric Acid Market