
 Copper Smelting Market | 2026-2036
Copper Smelting Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Smelting Market Outlook
Long-term offtake contracts with embedded sulfuric acid credits is realigning revenue models away from pure metal exposure. Freeport-McMoRan leverages captive concentrate supply from Indonesian and Americas assets to sustain margin stability. Jiangxi Copper dominates domestic Chinese smelting capacity and extends logistics control through dedicated rail corridors to coastal ports.
Copper smelting extracts metal from sulfide or oxide concentrates through pyrometallurgical or hydrometallurgical routes, typically yielding matte at 60-70% copper for further conversion to blister and refined grades. Flash smelting technology leads operational throughput due to oxygen-enriched process efficiency and lower energy intensity per ton of anode produced. Copper cathodes command premium pricing differentials over blister copper in contract settlements, while refined copper output concentrates in integrated complexes serving wire rod and semiconductor fabrication feedstock.
EPA emissions standards under the Clean Air Act and China's MEE effluent discharge rules shape capital allocation toward sulfur capture and acid plant retrofits. ISO 14001 environmental management systems and EU REACH compliance requirements constrain market access for non-certified Asian exporters. Stakeholders must weigh concentrate supply diversification against single-source geopolitical exposure when committing to smelter expansion timelines.
Market Dynamics
Flash smelting technology is compressing energy intensity per ton of copper anode produced while China's MEE dual carbon goals force acid plant retrofits at legacy facilities. Concentrate supply concentration in Chile and Indonesia creates procurement leverage asymmetries for smelters without captive mining assets.
Growth Catalysts
- Grid Modernization Mandates:Electrical sector offtake accelerates as utilities in Germany, Japan, and the United States replace aging transmission infrastructure. Copper anode demand from high-voltage cable manufacturing tightens spot availability.
- REACH Compliance Barriers:EU environmental certification requirements restrict market access for non-compliant Asian exporters. Certified smelters capture premium contract terms from European wire rod producers.
- Indonesian Concentrate Expansion:New mining capacity in Southeast Asia diversifies feedstock origins away from Chilean dominance. Smelters with offtake agreements to Indonesian operations secure margin stability.
Market Restraints
- Energy Cost Volatility:Natural gas and electricity price swings at European smelters compress operating margins during peak demand periods. German producers face particular exposure to spot power markets.
- Single-Source Concentrate Risk:Chilean state-controlled mining concentrates global supply leverage. Smelters without diversified offtake portfolios face feedstock interruption vulnerability.
- Technical Limitation in Arsenic Removal:Complex concentrate blends with elevated impurity levels require capital-intensive roasting circuits. Smelters lacking advanced impurity control capacity reject high-arsenic feedstock.
Strategic Opportunities
- Indian Fabrication Demand:Underpenetrated wire rod and semiconductor feedstock markets in South Asia offer volume expansion potential. Domestic smelting capacity lags projected consumption growth.
- Sulfuric Acid Credit Monetization:China's MEE effluent discharge rules create regulatory tailwind for smelters with integrated acid plants. Long-term offtake contracts with embedded acid credits realign revenue models.
- Hydrometallurgical-Hydrogen Convergence:Direct reduction technologies using renewable hydrogen inputs reduce Scope 3 emissions intensity. Pilot deployments in Australia and Canada demonstrate commercial feasibility.
Industry Challenges
- Pyrometallurgical Skill Scarcity:Flash furnace operation and oxygen-enriched process control require specialized engineering expertise. Aging workforce demographics in Germany and Japan constrain knowledge transfer.
- Acid Plant Capex Burden:Sulfur capture retrofit investments at legacy smelters strain balance sheets. Chinese producers face simultaneous MEE compliance deadlines across multiple facility vintages.
- ISO 14001 Certification Timelines:Environmental management system audits create six-to-twelve-month market access delays for expanding Asian exporters. European buyers enforce certificate validity as contract preconditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Smelting Market |
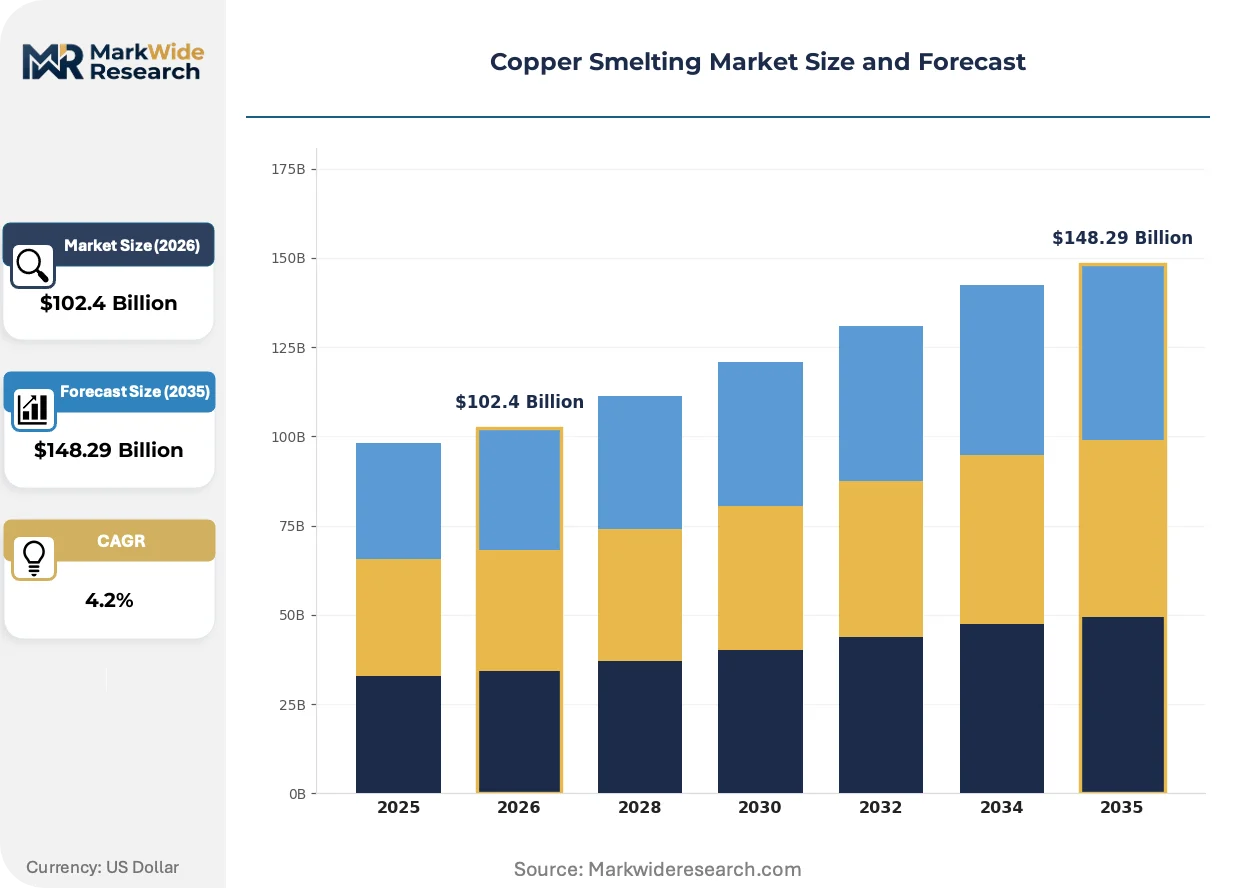
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $148.29 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Flash Smelting, Conventional Smelting, Electric Furnace, Peirce-Smith Converter End User: Construction, Electrical, Transportation, Consumer Electronics Product Type: Copper Anodes, Copper Cathodes, Blister Copper, Refined Copper Application: Building Materials, Wiring, Plumbing, Automotive Components |
| Companies Covered | Freeport-McMoRan Inc., KGHM Polska Miedź S.A., Corporación Nacional del Cobre de Chile, Aurubis AG, Jiangxi Copper Corporation Ltd., Glencore plc, Southern Copper Corporation, Hindalco Industries Limited, BHP Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Smelting Market Strategic Shifts
Oxygen-enriched smelting processes and digital furnace control systems are compressing unit production costs while regulatory frameworks force sulfur emission containment investments. Smelters with integrated logistics infrastructure capture feedstock cost advantages.
Flash converting technology is unifying matte-to-blister processing into continuous single-vessel operations. Integrated complexes in China and Chile deploy this configuration to reduce energy consumption per ton of refined output. The technology is unifying previously separate roasting and converting stages, eliminating intermediate material handling.
China's MEE dual carbon goals tighten emission thresholds at copper smelters through mandatory sulfur capture retrofit timelines. Acid plant investments now dominate capital allocation decisions for producers serving domestic wire rod markets. Smelters in Shandong and Jiangxi provinces accelerate compliance spending ahead of 2025-2027 inspection cycles.
Long-term offtake contracts with embedded sulfuric acid credits displace spot metal sales as the dominant commercial structure. European wire rod producers and Asian semiconductor fabricators negotiate multi-year supply agreements with price linkage to acid byproduct value. This procurement evolution concentrates contract volume with smelters possessing integrated acid plant capacity, particularly visible in German and Japanese buyer behavior.
Copper Smelting Market Segmentation
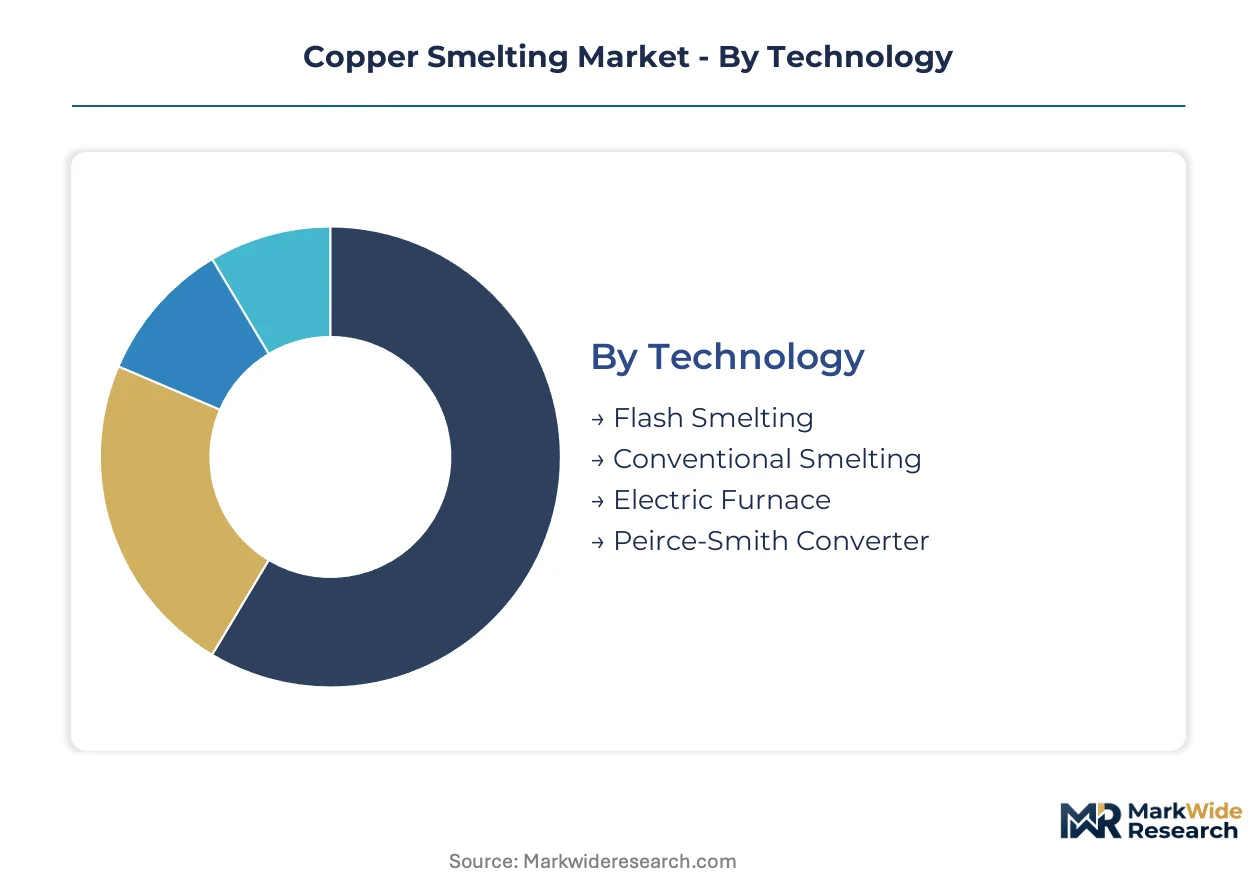
Copper smelting technology selection determines energy intensity and sulfur capture economics. End-use diversification across electrical infrastructure and consumer electronics creates divergent purity requirements. Product type and application segmentation reveal where integrated smelter-refinery complexes command premium positioning.
Technology:
Flash smelting dominates high-volume production while conventional routes retain niche applicability for complex concentrate blends.
- Flash Smelting:Oxygen-enriched processes achieve 60-70% copper matte in single-vessel operations. German and Japanese smelters deploy this configuration for grid modernization wire rod feedstock, leveraging lower energy intensity per ton of anode against rising European natural gas costs.
- Conventional Smelting:Multi-stage roasting and reverberatory furnace arrangements handle high-impurity concentrates with elevated arsenic levels. Chinese producers in Shandong province maintain these circuits for domestic construction-grade blister copper where MEE acid plant retrofits absorb capital priority.
- Electric Furnace:Direct resistance heating suits small-scale secondary copper recovery from scrap feedstock.
- Peirce-Smith Converter:Batch matte-to-blister processing persists at legacy Chilean operations integrated with Codelco concentrate supply.
Mature deployment sits with Peirce-Smith converters at South American integrated complexes. Newer deployment is concentrated in flash smelting expansions across East Asian greenfield sites.
End User:
Electrical sector procurement concentrates contract volume with acid-integrated smelters, while construction demand tolerates lower purity tiers.
- Electrical:High-voltage cable and semiconductor fabrication require cathode purity above 99.99%. German utilities and Japanese chip fabricators negotiate long-term offtake with sulfuric acid credit linkages, tightening spot availability for non-integrated smelters lacking ISO 14001 certification.
- Construction:Building wire and architectural applications accept standard-grade refined copper. Indian infrastructure expansion drives spot market absorption of blister copper from conventional smelters without downstream refining integration.
- Transportation:Electric vehicle motor windings and charging infrastructure demand oxygen-free high-conductivity grades.
- Consumer Electronics:Miniaturized connector applications require ultra-high-purity cathodes with controlled oxygen content.
Margin compression concentrates in construction-grade shipments. Premium capture clusters with electrical sector cathode contracts.
Product Type:
Cathode premiums over blister copper widen when acid plant integration enables sulfur credit monetization under China's MEE discharge rules.
- Copper Cathodes:Electrorefined output at 99.99% purity commands contract premiums from European REACH-compliant wire rod producers. Jiangxi Copper's dedicated rail corridors to coastal ports secure logistics advantages for semiconductor fabrication feedstock shipments.
- Copper Anodes:Fire-refined intermediate product at 99% purity feeds electrolytic refining cells. Indonesian concentrate supply agreements anchor anode production at Freeport-McMoRan's captive smelting assets.
- Blister Copper:Unrefined 98-99% product from converting stage trades at discounts to cathode benchmarks.
- Refined Copper:Cast rod and billet forms for direct fabrication into building materials and automotive components.
Capacity expansion targets cathode and anode tiers. Blister copper output is contracting at modernizing Chinese facilities.
Application:
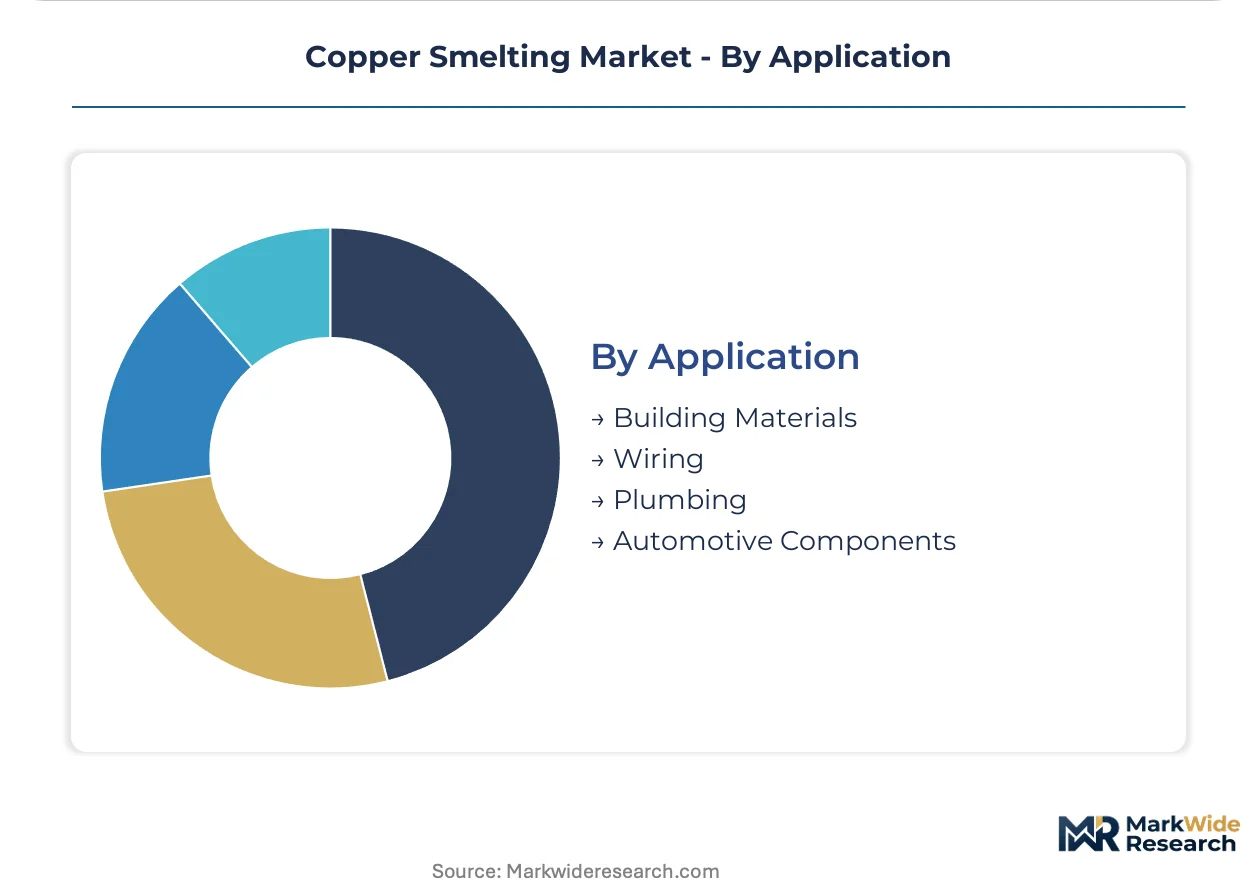
Wiring applications concentrate demand for high-conductivity grades while building materials absorb lower-specification refined copper.
- Wiring:Power transmission and building electrical systems require drawn rod with consistent conductivity. Grid modernization mandates in Germany, Japan, and the United States accelerate offtake from smelters with flash converting technology.
- Building Materials:Roofing, cladding, and architectural fixtures utilize lower-grade refined copper. Indian urbanization drives volume absorption from conventional smelters without acid plant integration.
- Plumbing:Tube and fitting stock demands deoxidized grades with specific thermal expansion characteristics.
- Automotive Components:Heat exchangers and electrical connectors require alloyed copper with precise mechanical properties.
Specification intensity peaks in wiring applications. Plumbing and building materials tolerate broader grade ranges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangxi provinces anchor Chinese smelting capacity expansion as MEE dual carbon deadlines approach. Chilean concentrate flows through dedicated Pacific port infrastructure toward East Asian refining complexes. German utilities and Japanese chip fabricators drive cathode contract premiums through long-term offtake negotiations.
China
Grid modernization and semiconductor fabrication feedstock demand accelerate cathode consumption across coastal provinces. MEE effluent discharge rules mandate sulfur capture retrofits at legacy facilities in Shandong and Jiangxi. Dedicated rail corridors from Jiangxi Copper's inland smelters to coastal ports secure logistics advantages for semiconductor feedstock shipments.
Chile
State-controlled mining concentrates concentrate supply leverage for global smelter procurement. Codelco's refining capacity expansion tightens domestic concentrate availability for export markets. Antofagasta and Calama mining clusters feed Pacific port infrastructure serving East Asian smelter contracts.
Germany
High-voltage cable manufacturing for grid infrastructure replacement drives cathode offtake from REACH-certified smelters. EPA-aligned emissions frameworks through EU industrial policy shape acid plant investment decisions. Hamburg and North Rhine-Westphalia industrial corridors concentrate wire rod fabrication demand.
Japan
Semiconductor fabrication and electric vehicle motor winding applications require ultra-high-purity cathodes with controlled oxygen content. METI industrial policy supports flash smelting technology adoption for energy intensity reduction. Osaka and Nagoya industrial clusters anchor semiconductor feedstock procurement negotiations.
India
Urban infrastructure expansion and underpenetrated wire rod markets absorb construction-grade blister copper from conventional smelters. CEA grid modernization directives accelerate transmission cable demand. Gujarat and Maharashtra industrial corridors concentrate domestic fabrication capacity that lags projected consumption growth.
Copper Smelting Market Competitive Environment
Capital-heavy producers compete with asset-light traders for concentrate procurement leverage and offtake contract security. The vendor base concentrates around integrated mining-smelting complexes and independent custom smelters serving regional wire rod markets. Three archetypes dominate: captive concentrate owners, custom smelters with acid plant integration, and diversified miners with trading operations. Competitive moves center on long-term offtake negotiations with embedded sulfuric acid credits and flash smelting technology licensing for energy intensity reduction.
Among diversified mining conglomerates, Glencore plc and BHP Group Limited occupy positions as concentrate suppliers with trading operations that influence smelter procurement economics. Freeport-McMoRan Inc. exemplifies the captive concentrate archetype through Indonesian and Americas mining assets that anchor margin stability. Aurubis AG represents European custom smelting with REACH certification advantages for German and regional wire rod contract negotiations.
| Leading Market Players |
|---|
| Freeport-McMoRan Inc. |
| KGHM Polska Miedź S.A. |
| Corporación Nacional del Cobre de Chile |
| Aurubis AG |
| Jiangxi Copper Corporation Ltd. |
| Glencore plc |
| Southern Copper Corporation |
| Hindalco Industries Limited |
| BHP Group Limited |
| Others |
Value Chain & Pricing Dynamics
German wire rod producers and Japanese semiconductor fabricators concentrate procurement leverage through multi-year offtake negotiations, locking contract structures to sulfuric acid credit value rather than spot metal benchmarks. This buyer archetype concentration forces pricing models toward outcome-linked arrangements where cathode purity and environmental certification determine settlement terms.
Pricing Analysis
Acid credit monetization anchors value-based pricing for integrated smelters serving REACH-compliant European buyers. Price differentiation separates ISO 14001-certified cathode shipments from standard-grade blister copper, with certification premiums widening as MEE discharge rules tighten in China. Pricing pressure stems from energy cost volatility at German flash smelters exposed to spot power markets. Construction-grade offtake in India shows highest price sensitivity, while semiconductor feedstock contracts in Japan tolerate premium tiers for controlled oxygen content.
Supply Chain Analysis
Specialized pyrometallurgical engineering talent scarcity in Germany and Japan constrains flash furnace commissioning timelines, extending project ramp periods. Supply concentrates in Chile, Indonesia, and China, with concentrate flows drawing from state-controlled mining clusters and captive Southeast Asian assets. Raw material dependencies rest on sulfide concentrate grades, oxygen enrichment systems, and acid plant sulfur capture capacity. Single-source Chilean concentrate risk creates feedstock interruption vulnerability. Distribution runs through dedicated Pacific port infrastructure toward East Asian refining complexes and European wire rod corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The copper smelting sector is consolidating around backward integration into captive concentrate supply and downstream refining capacity. Players are racing to secure offtake agreements with Indonesian mining expansions and acid plant retrofits ahead of MEE compliance deadlines.
For Market Incumbents: Cement concentrate procurement leverage through long-term offtake with Indonesian operations before Codelco's refining expansion tightens export availability. Prioritize flash converting technology licensing for energy intensity reduction at European assets facing natural gas cost volatility. Defend against custom smelter margin compression by locking sulfuric acid credit terms into multi-year cathode contracts with German wire rod producers. For New Entrants and Emerging Players: China's MEE dual carbon goals in Shandong and Jiangxi provinces open a window for acid plant retrofit specialists and flash smelting technology providers. Target underpenetrated Indian wire rod markets where domestic smelting capacity lags projected consumption growth. Pursue joint venture structures with established concentrate suppliers to bypass single-source procurement barriers. For Investors and Strategic Acquirers: The window for entry favors custom smelters with integrated acid plant capacity and REACH certification advantages serving European electrical sector demand. Long-term viability hinges on positioning for hydrometallurgical-hydrogen convergence pilots in Australia and Canada. Watch Indonesian concentrate export policy shifts as the inflection signal for feedstock cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Concentrate Supply | Freeport-McMoRan's Indonesian and Americas mining assets anchor margin stability against Chilean supply concentration. |
| Acid Plant Retrofit Investment | Chinese producers in Shandong province absorb capital priority to satisfy MEE effluent discharge inspection cycles. |
| Flash Smelting Technology Licensing | German and Japanese smelters deploy oxygen-enriched processes to compress energy intensity per ton of anode produced. |
| Long-term Offtake with Embedded Acid Credits | European wire rod producers negotiate multi-year agreements linking cathode pricing to sulfuric acid byproduct value. |
| REACH Certification Program | Aurubis AG leverages environmental compliance to capture premium contract terms from German utility procurement. |
Study Parameters
Independent corroboration across flash smelting technology providers, acid plant engineering firms, and concentrate trading desks underwrites the qualitative findings in this study. Primary interviews with smelter operations directors, procurement leads at German wire rod producers, and regulatory affairs specialists at China's MEE were combined with secondary validation from customs trade data, SEC filings of diversified mining conglomerates, and IEA industrial energy consumption reports. Bottom-up capacity assessments and top-down demand projections from electrical sector cable manufacturers were triangulated.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and concentrate supply expansion phases structured the analytical framework. Segmentation dimensions modeled include smelting technology type, end-use sector purity requirements, product grade tier, and regional regulatory cluster. CAGRs were derived from capacity utilization trends and offtake contract volume trajectories. Forecast inputs incorporated flash converting deployment rates and hydrogen-based hydrometallurgical pilot scalability.
The model assumes a particular technology adoption path; alternative pathways for direct hydrogen reduction smelting would alter the outlook for Scope 3 emissions intensity and capital allocation priorities. Forecasts reflect assumptions regarding MEE inspection cycle enforcement consistency and Chilean state mining export policy continuity. A small set of triggers—Indonesian concentrate export licensing shifts, European natural gas price regime changes, and flash furnace engineering talent availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rubidium Market
Metals
Reconditioned Steel Drums Market
Metals
Electrodeposited Copper Foil Market
Metals
Brazil Aluminum Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Beryllium Copper Plate Market
Metals
Metallurgical Silicon Market
Metals
Copper Foil Market
Metals
Stainless Steel Foil Market
Metals
Gold Smelting Market
Metals
Global Duplex Stainless Steel Market
Metals
Clutch Spring Wires Market
Metals
Titanium Mill Products Market
Metals
Ferro Vanadium Market