
 Benzyl Chloroformate Market | 2026-2036
Benzyl Chloroformate Market Size, Share, and Industry Trends Forecast 2026-2036
Benzyl Chloroformate Market Analysis
Pharmaceutical companies are reorganizing procurement priorities around carbamate intermediates for peptide drug synthesis. Specialty chemical buyers now command larger order volumes than agrochemical formulators in several supply contracts. BASF SE anchors European supply through backward integration into chloroformate feedstock production. Thermo Fisher Scientific Inc. extends its reagent catalog through controlled distribution channels serving contract research organizations. Paushak Limited dominates Indian bulk intermediate output with dedicated capacity for benzyl chloroformate derivatives.
Benzyl chloroformate is a colorless liquid reagent with the formula C8H7ClO2, synthesized via phosgenation of benzyl alcohol and employed primarily to install N-benzyloxycarbonyl protecting groups in amino acid chemistry. Its boiling point of approximately 103°C at 20 mmHg and moisture sensitivity dictate refrigerated storage and anhydrous handling protocols across industrial settings. The application dimension shows pharmaceutical manufacturing leading value capture due to high-purity requirements in GMP environments, while chemical research represents the fastest-expanding volume channel as academic outsourcing accelerates. Within product type, reagents command premium pricing against intermediates because of certification overhead and lot-level traceability demands.
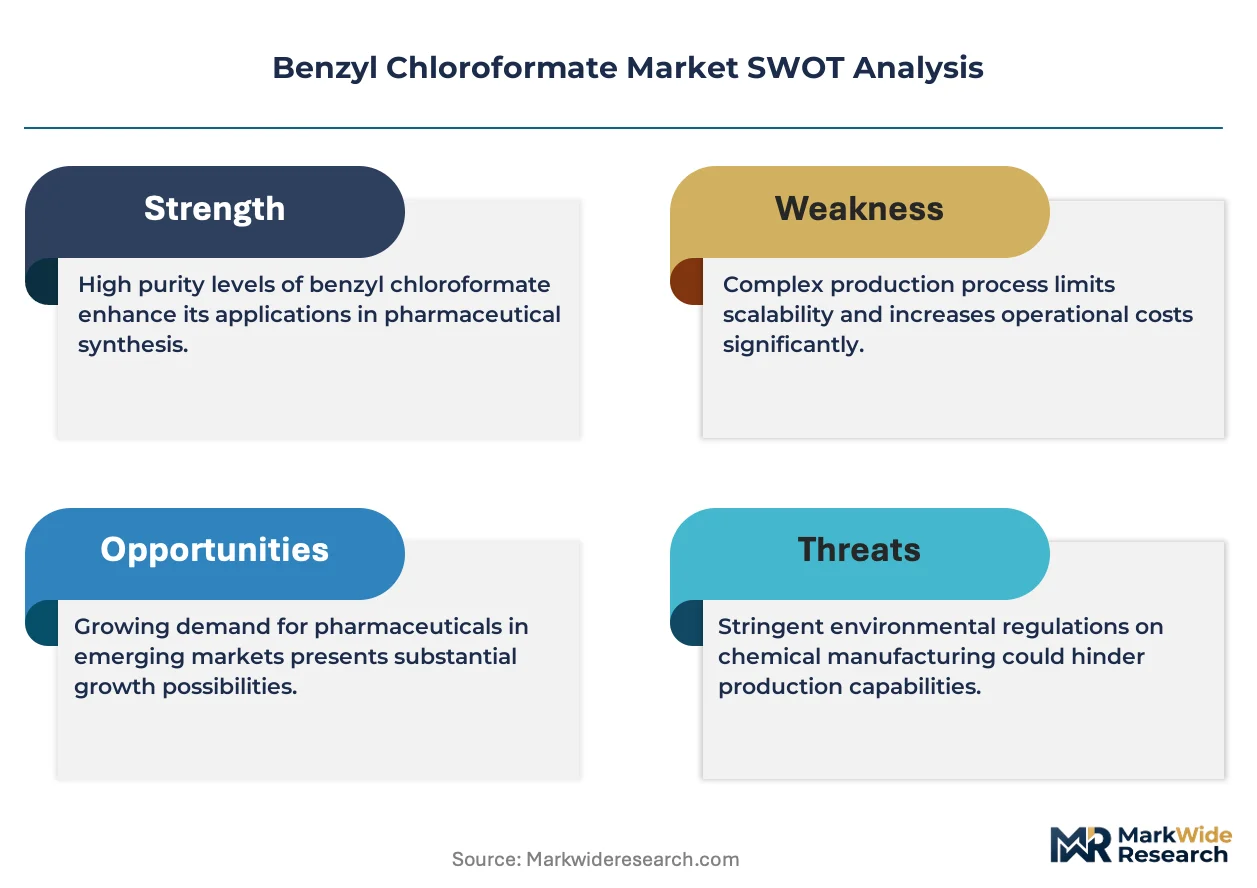
EPA oversight in the United States governs phosgene-derived chemical reporting under TSCA Section 8, while REACH registration in Europe mandates full toxicological dossiers for benzyl chloroformate import and manufacture. India's CDSCO aligns with ICH Q3C guidelines to limit residual solvent carryover in API synthesis using this reagent. Stakeholders must monitor evolving ECHA restriction proposals on chloroformate esters and pre-emptively qualify alternative protecting group chemistries before regulatory thresholds tighten.
Market Dynamics
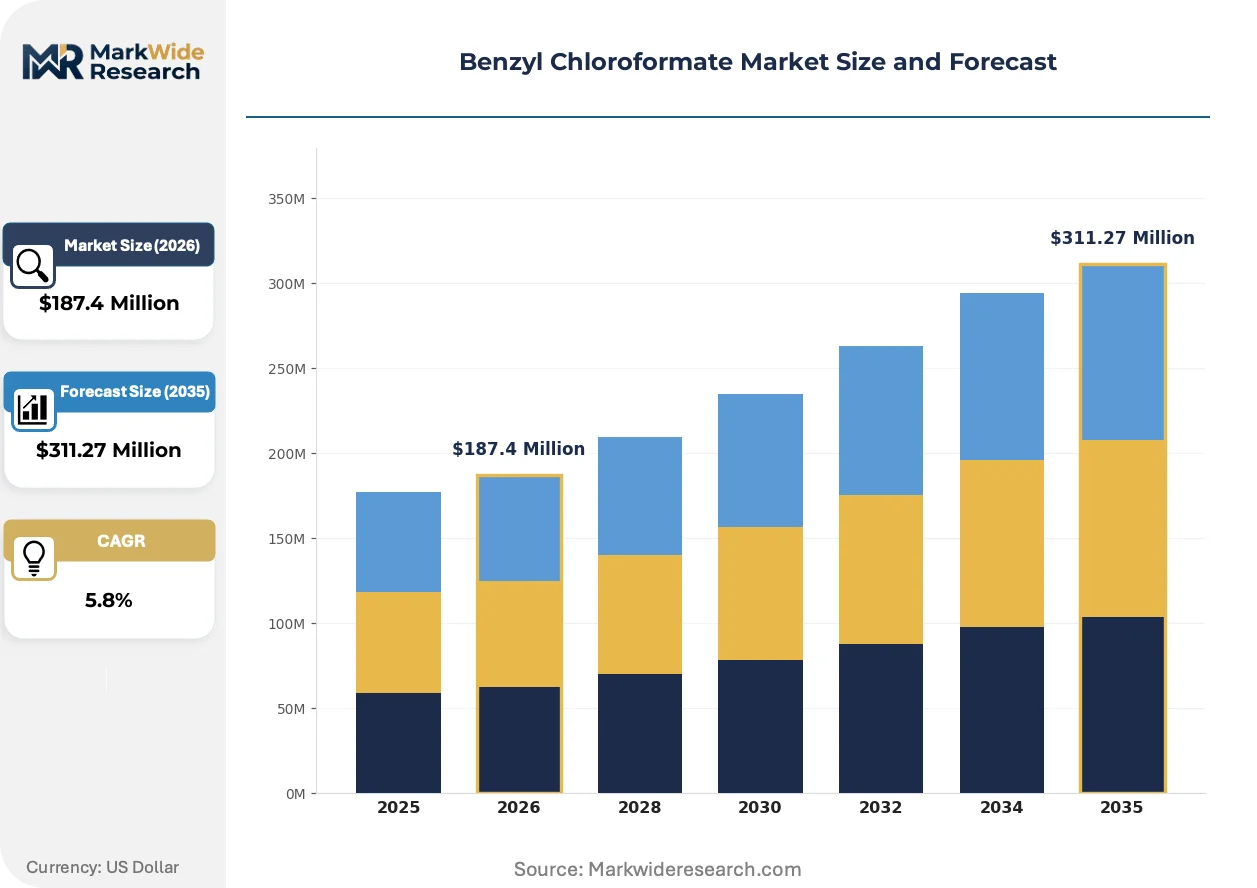
Pharmaceutical peptide synthesis is concentrating demand for high-purity benzyl chloroformate reagents, with CDSCO-registered API producers in India scaling carbamate intermediate output for export markets while REACH compliance costs reshape supplier qualification criteria across Europe.
Growth Catalysts
- Peptide drug pipeline expansion:GLP-1 receptor agonist manufacturing is pulling stronger volumes of N-benzyloxycarbonyl protected amino acids through contract development organizations.
- REACH registration completion:ECHA-mandated toxicological dossiers for chloroformate esters have cleared market access for qualified European suppliers, consolidating procurement toward certified handlers.
- Carbamate chemistry diversification:Agrochemical formulators are repurposing benzyl chloroformate-derived intermediates for novel fungicide active ingredient synthesis.
Market Restraints
- Phosgene feedstock volatility:Chloroformate synthesis depends on phosgene availability, with EPA TSCA Section 8 reporting requirements adding compliance overhead to US-based production economics.
- Moisture sensitivity handling costs:The reagent's reactivity with water necessitates refrigerated anhydrous storage infrastructure, elevating working capital requirements for distributors.
- Fluorenylmethoxycarbonyl substitution:Fmoc protecting group chemistry is displacing Cbz protocols in certain solid-phase peptide synthesis workflows, compressing addressable volume in research segments.
Strategic Opportunities
- CDSCO-registered API export channel:Indian bulk intermediate producers can capture incremental value through backward integration into reagent-grade purification for GMP environments.
- ECHA restriction proposal preparation:Proactive qualification of alternative protecting group chemistries before regulatory thresholds tighten creates first-mover positioning for compliant suppliers.
- Continuous flow phosgenation:Adoption of flow chemistry protocols for benzyl alcohol chloroformate conversion is reducing batch-to-batch variability and enabling on-demand production scales.
Industry Challenges
- Analytical method transfer complexity:Lot-level traceability demands for GMP reagent certification require validated impurity profiling capabilities that strain quality control staffing at mid-scale suppliers.
- Cold chain integrity maintenance:Moisture-sensitive inventory requires specialized warehousing infrastructure, with temperature excursion risks elevated during monsoon logistics in Indian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzyl Chloroformate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Intermediates, Solvents, Catalysts Application: Syntheses, Pharmaceutical Manufacturing, Chemical Research, Agrochemicals End User: Pharmaceutical Companies, Research Laboratories, Chemical Processing Plants, Biotechnology Firms Distribution Channel: Direct Sales, Online Platforms, Distributors, Retailers |
| Companies Covered | Choice Organochem LLp, Paushak Limited, Nacalai Tesque, BASF SE, Tokyo Chemical Industry Co., Ltd., Chemlin Chemical Industry Co., Ltd, MERYER CO., LTD, Thermo Fisher Scientific Inc., Wako Pure Chemical Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzyl Chloroformate Market Emerging Trajectories
Protecting group chemistry is undergoing methodical renovation as solid-phase synthesis automation and regulatory pre-qualification reshape reagent specification standards across pharmaceutical manufacturing.
Continuous flow chloroformate synthesis is supplanting batch phosgenation in advanced intermediate production. Thermo Fisher Scientific and specialized CDMOs are adopting microreactor platforms for benzyl alcohol conversion. This technology is supplanting conventional stirred-tank processes by compressing residence times from hours to minutes while improving thermal safety margins.
ECHA's evolving restriction proposals on chloroformate esters are forcing toxicological re-evaluation across the European supply base. Manufacturers must submit updated exposure scenario dossiers or face import authorization suspension. High-purity reagent suppliers serving GMP peptide synthesis are responding by accelerating alternative protecting group validation programs.
Buyers are consolidating vendor panels around suppliers with integrated phosgene handling capabilities and certified cold chain distribution. CDSCO-registered API producers in India now command larger order volumes than traditional research chemical distributors. This concentration is most visible in Hyderabad and Ahmedabad manufacturing clusters, where backward-integrated suppliers qualify directly for multinational pharmaceutical procurement frameworks.
Benzyl Chloroformate Market Segmentation
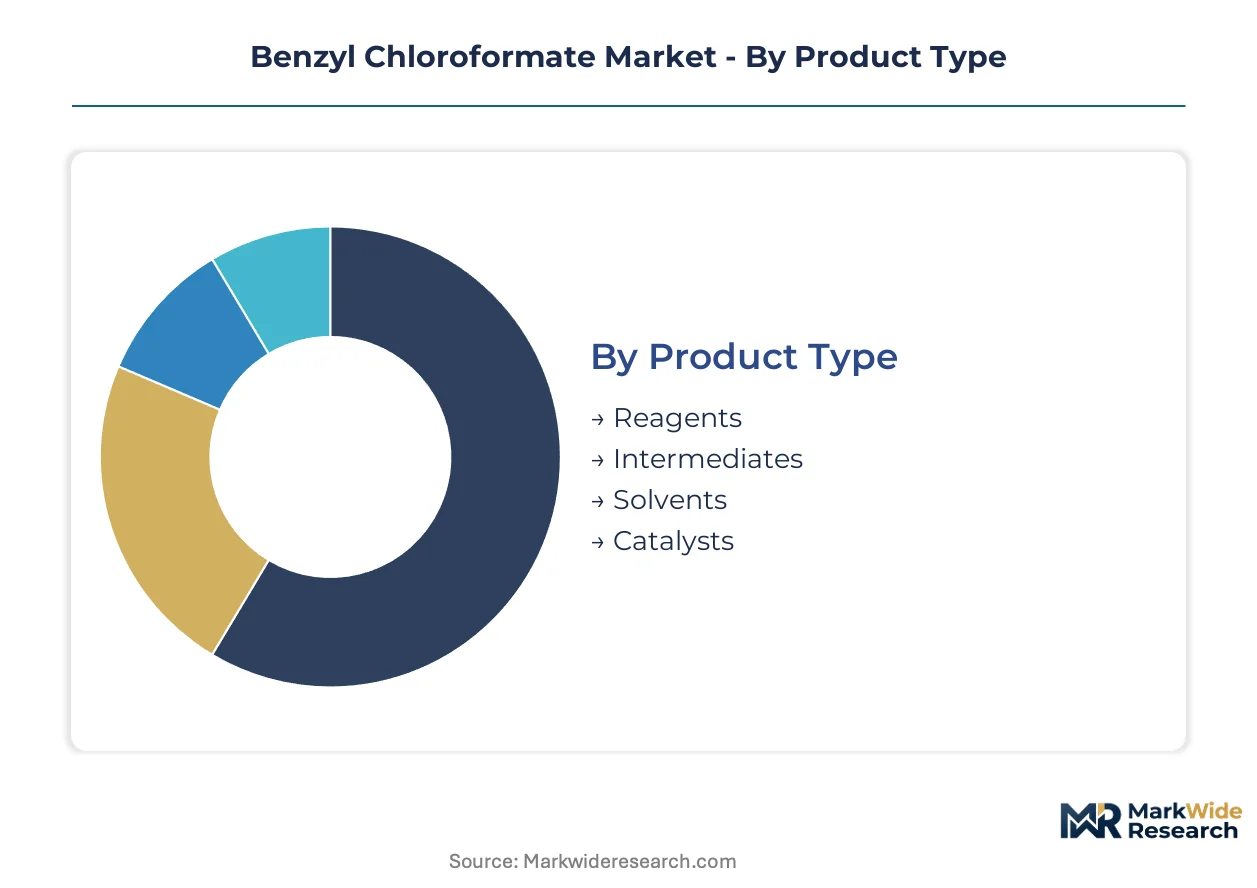
Segmentation in benzyl chloroformate procurement reflects divergent purity requirements, regulatory burdens, and handling infrastructure across customer types. Pharmaceutical buyers demand GMP-certified reagents with full lot traceability, while research laboratories prioritize catalog breadth and rapid fulfillment over certification depth.
Product Type:
Margin pools concentrate in reagent-grade certification overhead and cold chain integrity guarantees rather than commodity intermediate volumes.
- Reagents:High-purity C8H7ClO2 formulations meeting pharmacopeial specifications for peptide synthesis and amino acid protection. Demand concentrates in CDSCO-registered API producers across Hyderabad and Ahmedabad manufacturing clusters, where GMP compliance mandates validated impurity profiling and refrigerated anhydrous storage protocols.
- Intermediates:Technical-grade chloroformate derivatives serving downstream carbamate chemistry without full certification overhead. Bulk volumes flow toward agrochemical formulators repurposing benzyl chloroformate-derived building blocks for novel fungicide active ingredient synthesis.
- Solvents:Formulated diluents and co-solvent systems for reaction media compatibility.
- Catalysts:Chloroformate-activated coupling reagents and promoter systems.
Reagents hold installed capacity. Intermediates is rotating up the share rankings.
Application:
Application tiering tracks the spread between regulated pharmaceutical manufacturing and exploratory research workflows.
- Pharmaceutical Manufacturing:N-benzyloxycarbonyl protecting group installation in GLP-1 receptor agonist peptide synthesis under FDA and EMA oversight. CDMOs command larger order volumes than traditional research chemical distributors as solid-phase synthesis automation scales.
- Syntheses:General organic transformation protocols including carbamate formation and alcohol protection strategies.
- Chemical Research:Academic and institutional outsourcing of amino acid chemistry, expanding most quickly as contract research organizations consolidate procurement around certified handlers with integrated phosgene capabilities.
- Agrochemicals:Intermediate feedstock for crop protection active ingredient development.
Pharmaceutical Manufacturing dominates value capture. Chemical Research is climbing the fastest.
End User:
Customer type segmentation mirrors the divergence between validated GMP supply chains and catalog-based procurement.
- Pharmaceutical Companies:Multinational drug manufacturers requiring REACH-registered or CDSCO-compliant reagent streams with full toxicological dossiers and exposure scenario documentation for ECHA submission.
- Research Laboratories:University and institutional buyers prioritizing SKU breadth and rapid fulfillment over lot-level traceability, though Fmoc substitution is compressing Cbz protocol volumes in certain solid-phase workflows.
- Chemical Processing Plants:Intermediate conversion facilities with captive phosgene handling and batch chloroformate production.
- Biotechnology Firms:Emerging therapeutic developers outsourcing peptide synthesis to qualified CDMO networks.
Pharmaceutical Companies anchor contract value. Biotechnology Firms is gaining share fastest.
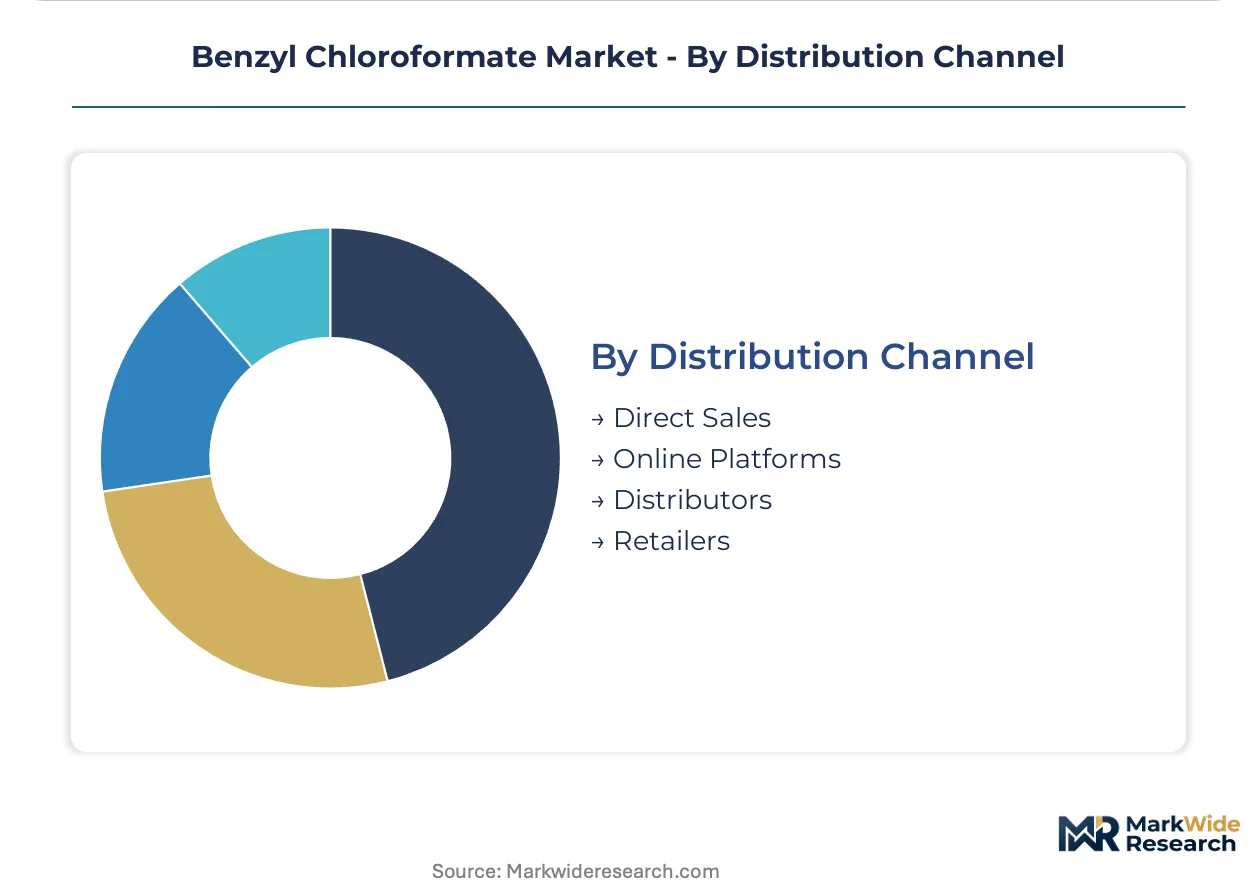
Distribution Channel:
Channel economics hinge on cold chain integrity maintenance and regulatory documentation transfer.
- Direct Sales:Manufacturer-to-manufacturer procurement frameworks bypassing distributor markup, prevalent among backward-integrated suppliers with captive phosgenation and GMP purification capabilities serving multinational pharmaceutical procurement panels.
- Distributors:Specialized chemical handlers with certified refrigerated warehousing and anhydrous handling protocols, qualifying for REACH and TSCA compliance documentation transfer.
- Online Platforms:Catalog-based procurement for research-scale volumes with rapid fulfillment.
- Retailers:Limited presence given moisture sensitivity and regulatory handling requirements.
Direct Sales holds relationship density. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European chloroformate distribution, while the Jawaharlal Nehru Port Trust near Mumbai funnels Indian carbamate exports toward contract manufacturing networks.
United States
GLP-1 peptide manufacturing expansion along the Research Triangle and Greater Boston corridors is pulling reagent volumes toward CDMO networks. EPA TSCA Section 8 reporting requirements govern phosgene-derived chemical handling, adding compliance documentation burdens to domestic production. Houston's petrochemical corridor hosts backward-integrated suppliers with captive chloroformate synthesis serving pharmaceutical procurement panels.
Germany
REACH-registered suppliers command procurement preference as ECHA toxicological dossier requirements filter out uncertified handlers. The country's national chemical regulator mandates full exposure scenario documentation for chloroformate ester import and manufacture. Ludwigshafen's integrated chemical complex anchors European supply through in-house phosgenation and GMP purification capabilities.
India
CDSCO-registered API producers in Hyderabad and Ahmedabad manufacturing clusters are scaling carbamate intermediate output for export markets. The national pharmaceutical regulator aligns with ICH Q3C guidelines to limit residual solvent carryover in synthesis workflows. Paushak Limited dominates bulk intermediate capacity with dedicated benzyl chloroformate derivative production serving multinational drug manufacturers.
China
Specialty chemical exporters are qualifying for REACH-registered supply chains through toxicological dossier preparation and exposure scenario submissions. The national chemical safety regulator enforces GB standards for hazardous chemical production and cross-border shipment documentation. Zhejiang and Jiangsu province manufacturing hubs concentrate technical-grade chloroformate output for agrochemical intermediate conversion.
Japan
Reagent-grade purification capabilities serve domestic peptide synthesis demand with stringent pharmacopeial compliance. The national pharmaceutical and medical device agency oversees GMP reagent certification for amino acid protection chemistry. Osaka and Tokyo metropolitan areas host specialized chemical handlers with certified cold chain distribution for moisture-sensitive inventory.
Benzyl Chloroformate Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and cold chain reach. The supplier base concentrates around three archetypes: multinational chemical conglomerates with backward-integrated phosgenation, regional reagent specialists with GMP purification capabilities, and CDMO-adjacent distributors with certified handling infrastructure. Competitive moves center on REACH registration completion for market access and capacity expansion near Indian pharmaceutical manufacturing clusters.
Within the multinational tier, BASF SE anchors European supply through integrated feedstock production, while Thermo Fisher Scientific Inc. extends reagent catalog breadth through controlled distribution channels. Paushak Limited exemplifies the regional specialist archetype with dedicated Indian capacity for derivative output. These three occupy positions spanning certification-heavy reagent supply and technical-grade intermediate conversion.
| Leading Market Players |
|---|
| Choice Organochem LLp |
| Paushak Limited |
| Nacalai Tesque |
| BASF SE |
| Tokyo Chemical Industry Co., Ltd. |
| Chemlin Chemical Industry Co., Ltd |
| MERYER CO., LTD |
| Thermo Fisher Scientific Inc. |
| Wako Pure Chemical Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day refrigerated inventory cycles concentrate working capital with certified handlers, amplifying pricing power for backward-integrated suppliers with captive phosgenation and GMP purification capabilities serving multinational pharmaceutical procurement panels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified reagents with full lot traceability from technical-grade intermediates and research-scale catalog offerings. Price differentiation hinges on certification depth and cold chain integrity guarantees, with CDSCO-registered API producers in India commanding volume discounts unavailable to academic laboratories. Cost compression in research-grade tiers is intensifying because Fmoc substitution compresses Cbz protocol volumes. Research laboratories exhibit highest price sensitivity due to budget constraints and protecting group substitution options, while pharmaceutical CDMOs prioritize supply security over unit economics.
Supply Chain Analysis
Strategic stockpiling dominates pharmaceutical procurement given moisture sensitivity and monsoon logistics risks, whereas research-scale buyers favor just-in-time fulfillment through distributor networks. Supply concentrates in India, Germany, and China, with phosgene feedstock, benzyl alcohol, and chloroformate conversion capacity as critical inputs. Single-source vulnerability in phosgenation infrastructure elevates risk exposure during ECHA restriction proposal deliberations. Distribution runs through specialized chemical handlers with certified refrigerated warehousing and anhydrous handling protocols qualifying for REACH and TSCA compliance documentation transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cold chain logistics and validated impurity profiling services expand faster than commodity reagent volumes, creating recurring revenue layers that compound customer lifetime value beyond transactional chemical sales.
For Market Incumbents: Fortify procurement relationships through backward integration into phosgene handling and GMP purification capacity near Hyderabad and Ahmedabad manufacturing clusters. Accelerate alternative protecting group validation programs before ECHA restriction thresholds tighten, preserving market access through toxicological dossier maintenance.
For New Entrants and Emerging Players: Anchor in agrochemical intermediate conversion as the most penetrable segment, where technical-grade specifications reduce certification overhead relative to pharmaceutical reagent supply. Pursue continuous flow chloroformate synthesis technology licensing as a differentiated go-to-market angle serving CDMO automation requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates divesting non-core chloroformate derivative operations. Five-to-ten-year viability favors regional specialists with integrated phosgenation and CDSCO-registered export channels. Monitor ECHA restriction proposal advancement as the critical inflection signal for alternative chemistry investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosgenation | Captive feedstock production insulates margin pressure from phosgene volatility and EPA reporting burdens. |
| Continuous Flow Technology Adoption | Microreactor platforms compress residence times and improve thermal safety margins for benzyl alcohol conversion. |
| CDSCO Registration Completion | Indian regulatory alignment enables direct qualification for multinational pharmaceutical procurement frameworks. |
| Alternative Protecting Group Validation | Proactive qualification before ECHA restriction tightening preserves market access and customer relationships. |
| Cold Chain Infrastructure Expansion | Certified refrigerated warehousing addresses moisture sensitivity and monsoon logistics risks in Indian manufacturing clusters. |
Methodological Framework
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings, combining primary interviews with plant managers, procurement leads at downstream CDMOs, distribution channel partners, and technical R&D directors with secondary validation against customs records, SEC 10-K filings, CDSCO registration databases, and ECHA dossier submissions. Bottom-up volume triangulation against top-down value estimates ensures consistency across modeling approaches.
Sensitivity analysis across grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions informs the analytical framework over the projection horizon. CAGRs derive from regression-based trending of historical volume patterns adjusted for regulatory inflection points, with peptide drug pipeline expansion rates and phosgene feedstock availability as critical forecast inputs.
Material uncertainties — ECHA restriction proposal outcomes, phosgene supply disruptions, and Fmoc substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and protecting group chemistry continuity. Revision becomes warranted when chloroformate ester authorization thresholds cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Global Hexane Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Propionaldehyde Market