
 Paraxylene(PX) Market | 2026-2036
Paraxylene(PX) Market Size, Share, and Industry Trends Forecast 2026-2036
Paraxylene(PX) Market Analytics
Recycled PET flake is repositioning virgin PX economics in packaging-grade polyester chains. Reliance Industries Limited leverages its Jamnagar refining complex to sustain captive PX-to-PTA integration. Sinopec anchors domestic supply across China's eastern seaboard through state-controlled catalytic reforming capacity. ExxonMobil Corporation competes via Singapore and Rotterdam hubs with merchant-grade PX exports to European textile makers.
Paraxylene is an aromatic hydrocarbon with formula C₈H₁₀, typically produced at 99.7% purity through catalytic reforming of naphtha feedstock to serve as the principal precursor for purified terephthalic acid. Purified Terephthalic Acid dominates product-type demand as bottle-grade and fiber-grade PTA plants absorb over ninety percent of global PX offtake. Polyester Fiber trails in volume but captures expanding share from Dimethyl Terephthalate as direct esterification routes displace older methanol-based processes. Films represents a mature outlet where optical-grade specifications command premium pricing over commodity packaging resin.
China's Ministry of Ecology and Environment enforces dual carbon emission caps that restrict new coal-to-chemical PX additions while favoring naphtha-route expansions. REACH registration in Europe and EPA fuel-aromatic standards in the United States shape cross-border trade flows and product certification requirements for PX derivatives. South Korea's Act on the Registration and Evaluation of Chemicals adds compliance layers for Korean exporters serving ASEAN textile markets. Stakeholders must track carbon-border adjustment mechanisms and feedstock-switching economics to align capacity decisions with regulatory trajectories.
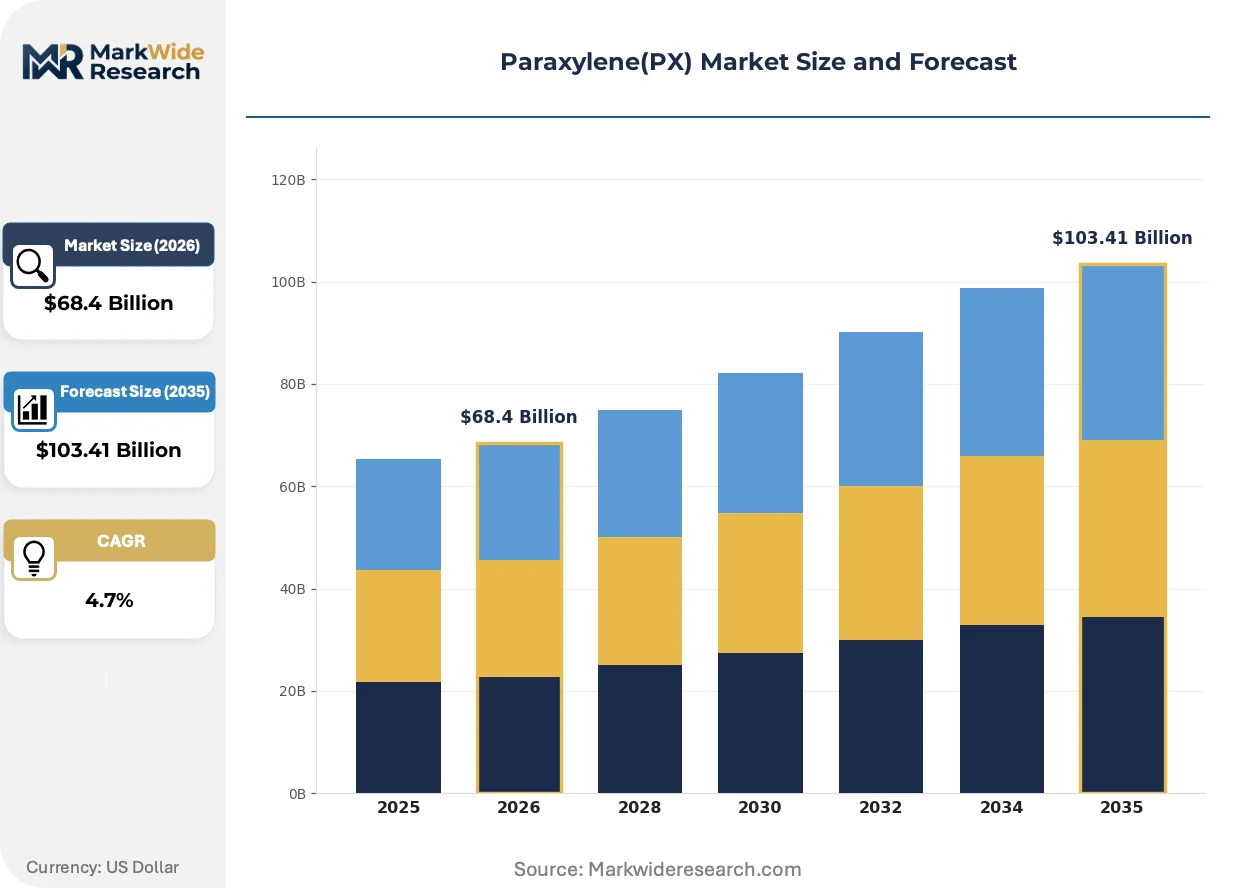
Market Dynamics
The Paraxylene(PX) Market pivots on feedstock-route bifurcation as China's dual carbon goals force naphtha-based reforming expansions while coal-to-chemical routes face emission caps. Refinery-petrochemical integration intensity determines cost competitiveness across coastal Asia-Pacific clusters.
Growth Catalysts
- Purified Terephthalic Acid capacity expansion:Bottle-grade and fiber-grade PTA plants absorb over ninety percent of global PX offtake, pulling feedstock demand through integrated complexes in China, South Korea, and India.
- REACH registration compliance:European textile makers source certified merchant-grade PX through Rotterdam and Singapore hubs, creating premium trade lanes for specification-grade material.
- Bio-based PX pilot advancement:China's Ministry of Ecology and Environment favors naphtha-route expansions under dual carbon targets, accelerating pilot projects for renewable feedstock substitution.
Market Restraints
- Naphtha price volatility:Crude-linked feedstock costs compress reforming margins unpredictably, exposing standalone aromatics producers to margin squeeze during oil price spikes.
- Coastal supply concentration:Over seventy percent of merchant PX capacity clusters in China's eastern seaboard and South Korea's Yeosu-Ulsan corridor, creating geographic vulnerability to port congestion or regional emission shutdowns.
- Dimethyl Terephthalate displacement:Direct esterification routes for PTA production eliminate methanol intermediate demand, eroding a historical PX outlet as older DMT plants retire.
Strategic Opportunities
- India's polyester fiber buildout:Reliance Industries Limited's Jamnagar complex expansion and downstream textile investments create captive PX-to-fabric demand absorption within a single refining-polymer chain.
- Singapore merchant hub positioning:ExxonMobil Corporation's Singapore aromatics complex serves European packaging-grade buyers seeking non-China supply diversification under carbon-border adjustment exposure.
- Optical-grade film specifications:Premium pricing for high-purity PX in display and electronics films outstrips commodity packaging resin margins, rewarding purity upgrade investments.
Industry Challenges
- Catalytic reforming catalyst regeneration cycles:Platinum-rhenium catalyst deactivation management requires specialized technical expertise scarce outside major integrated refiners, constraining new entrant viability.
- EPA fuel-aromatic standards alignment:US exporters face product certification complexity when redirecting reformate-derived PX to chemical versus fuel pools, comifying cross-border derivative trade documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraxylene(PX) Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Terephthalic Acid, Dimethyl Terephthalate, Polyester Fiber, Films End User: Textiles, Packaging, Automotive, Electronics Manufacturing Process: Fluid Catalytic Cracking, Toluene Disproportionation, Catalytic Reforming, Hydrodealkylation Application: Bottles, Fibers, Coatings, Resins |
| Companies Covered | Reliance Industries Limited, China National Petroleum Corporation, Sinopec, ExxonMobil Corporation, Saudi Aramco, BP PLC, JX Nippon Oil & Energy Corp, GS Caltex, S-Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraxylene(PX) Market Evolving Landscape
Bio-based feedstock substitution and carbon-accounting transparency are rewriting competitive positioning in aromatics supply chains. Technology convergence between refining optimization and polymer-grade purity requirements accelerates process innovation cycles.
Advanced bio-paraxylene production from cellulosic feedstocks is rewriting the feedstock hierarchy for premium polyester applications. European textile brands and Japanese apparel makers pilot bio-PX offtake agreements at small commercial scale. This technology is rewriting virgin PX premium structures as mass-balance certification creates price stratification between fossil and renewable-origin material.
China's dual carbon emission caps under MEE enforcement restrict new coal-to-chemical PX additions while accelerating naphtha-route permits. Refinery-petrochemical complexes in Zhejiang and Jiangsu provinces expand reforming capacity to capture PTA integration economics. Korean exporters to ASEAN textile markets face additional K-REACH compliance layers, reshaping documentation requirements for cross-border dimethyl terephthalate and purified terephthalic acid shipments.
Direct esterification process adoption by fiber-grade polyester manufacturers concentrates PX demand in single-step PTA plants. Methanol-based DMT routes lose share as Chinese and Indian textile makers prioritize capital efficiency and lower variable costs. This procurement pattern shift is most visible in South Korea's Yeosu cluster, where PTA producers now specify naphtha-origin PX with stricter impurity thresholds than legacy DMT-grade material.
Paraxylene(PX) Market Segmentation
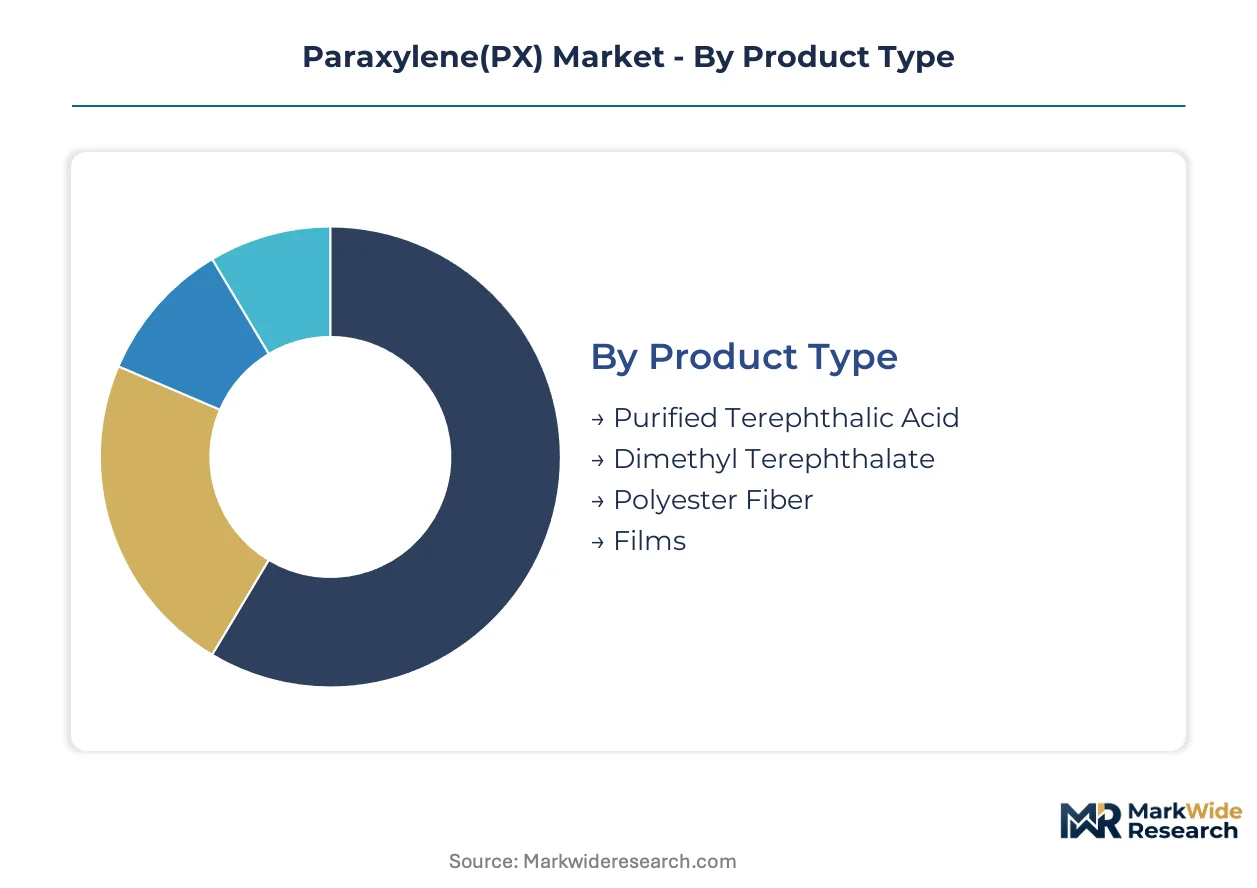
Paraxylene demand fractures across distinct technical specifications and end-use purity requirements. Buyers prioritize integration economics over standalone merchant supply, reshaping how segments compete for reforming capacity allocation.
Product Type:
Cost tier differentiation separates integrated PTA producers from merchant-grade spot buyers seeking specification flexibility.
- Purified Terephthalic Acid:Bottle-grade and fiber-grade specifications demand 99.7% minimum PX purity with strict control of ortho-xylene and meta-xylene impurities. Coastal China refiners in Zhejiang and Jiangsu provinces anchor captive demand through PTA integration, while South Korean exporters serve European packaging makers under REACH certification requirements.
- Polyester Fiber:Direct esterification routes now dominate fiber-grade production, concentrating PX offtake in single-step plants that bypass methanol intermediates. Indian textile clusters in Gujarat and Tamil Nadu absorb expanding volumes as Reliance Industries Limited scales downstream fabric integration.
- Dimethyl Terephthalate:Legacy methanol-based processes face displacement as Chinese and Indian producers retire older DMT lines for capital-efficient PTA alternatives.
- Films:Optical-grade specifications for display substrates command premium pricing over commodity packaging resin, rewarding purity upgrade investments.
Volume sits with Purified Terephthalic Acid; growth tilts toward Polyester Fiber as direct esterification expands.
End User:
Application maturity determines margin capture, with electronics and automotive segments pricing purity premiums above commodity textile absorption.
- Textiles:Asia-Pacific garment manufacturing absorbs the majority of fiber-grade PTA output, with Bangladesh and Vietnam weaving clusters pulling feedstock through integrated spinner-to-fabric chains.
- Packaging:Bottle-grade resin for carbonated soft drinks and water containers demands food-contact compliance certifications that constrain supplier qualification to major integrated refiners.
- Automotive:Engineering resin specifications for under-hood applications require thermal stability beyond standard fiber-grade material, creating specification-grade pricing tiers.
- Electronics:Optical film and display substrate applications represent the highest purity threshold segment, with Japanese and South Korean electronics makers sourcing through Singapore merchant hubs.
Textiles commands current volume; electronics exhibits the steepest expansion trajectory as display manufacturing concentrates in East Asian clusters.
Manufacturing Process:
Feedstock route selection now hinges on emission compliance rather than standalone yield optimization, advantaging naphtha-based methods under China's dual carbon enforcement.
- Catalytic Reforming:Platinum-rhenium catalyzed naphtha reforming produces C8 aromatic fractions at 99.7% PX purity through continuous catalyst regeneration cycles. China's Ministry of Ecology and Environment favors permit approvals for refinery-integrated reforming expansions over coal-to-chemical alternatives.
- Toluene Disproportionation:Transalkylation of toluene and C9 aromatics supplements reforming output where naphtha supply constraints limit conventional capacity expansion.
- Fluid Catalytic Cracking:FCC-derived light cycle oil yields lower PX concentration than dedicated reforming, limiting chemical-grade applications.
- Hydrodealkylation:Demethylation of heavier alkylbenzenes toluene and xylene streams sees niche application where mixed aromatic feedstocks predominate.
Catalytic Reforming dominates installed capacity; Toluene Disproportionation gains share where naphtha economics tighten.
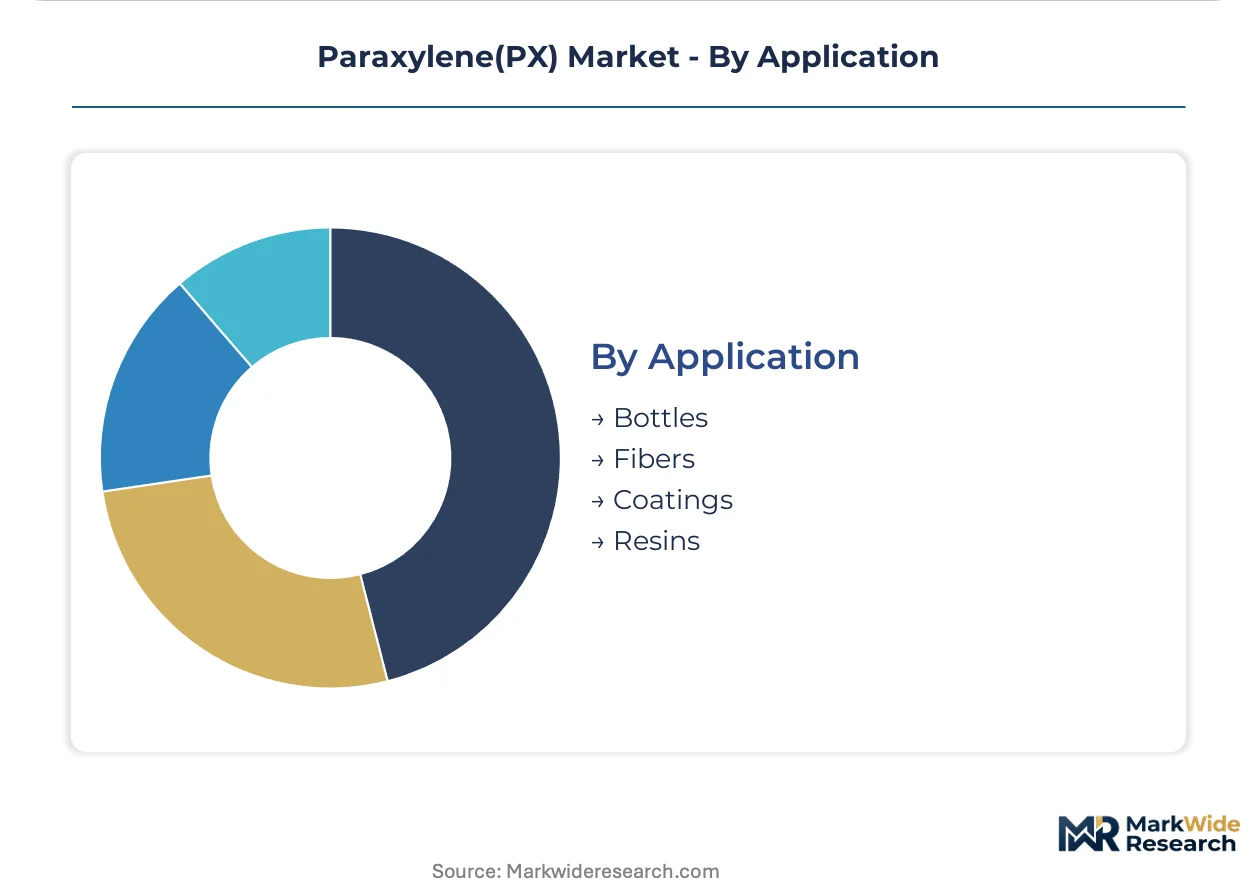
Application:
Customer scale separates bulk polymer absorption from specialty coating formulations requiring drum-quantity logistics.
- Bottles:PET container resin demands food-contact grade PTA with acetaldehyde content below 1 ppm, constraining qualified PX supply to major integrated producers with dedicated purification trains.
- Fibers:Staple and filament yarn production pulls the majority of merchant PX through direct esterification PTA plants, with Indian and Vietnamese textile clusters expanding absorption fastest.
- Coatings:Powder and liquid coating resin applications tolerate broader purity bands than bottle-grade specifications, opening merchant supply to smaller reforming operators.
- Resins:Unsaturated polyester and alkyd resin formulations consume PX derivatives in construction and marine applications with less stringent impurity thresholds than packaging grades.
Fibers anchors current offtake; bottles demonstrates the most rapid climb as refillable container mandates expand across European and Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant-grade paraxylene procurement concentrates in coastal refining corridors where PTA integration economics override standalone spot purchasing. China's eastern seaboard absorbs the majority of Asian offtake through state-controlled reforming complexes, while European packaging makers source certified material through Rotterdam and Singapore merchant hubs.
China
Zhejiang and Jiangsu province refiners expand catalytic reforming capacity to feed bottle-grade PTA plants serving domestic packaging demand. MEE dual carbon enforcement restricts new coal-to-chemical permits while accelerating naphtha-route approvals. The Ningbo-Zhoushan petrochemical cluster anchors captive PX-to-PTA integration for polyester fiber exports.
South Korea
Yeosu-Ulsan corridor exporters serve ASEAN textile markets under K-REACH compliance documentation requirements. Direct esterification adoption by fiber-grade producers concentrates PX demand in single-step PTA specifications. Busan port infrastructure handles merchant-grade aromatics transshipment to European REACH-certified buyers.
India
Gujarat's Jamnagar refining complex sustains captive PX-to-fabric demand absorption through downstream textile investments. Reliance Industries Limited scales PTA integration to serve domestic garment manufacturing clusters. Tamil Nadu weaving operations pull expanding feedstock volumes as direct esterification routes displace legacy DMT processes.
Singapore
Jurong Island aromatics complexes position as non-China supply diversification nodes under EU carbon-border adjustment exposure. ExxonMobil Corporation's merchant hub serves European packaging-grade buyers seeking specification-certified material. The port's storage and blending infrastructure supports spot market liquidity for Asian textile makers.
Germany
REACH registration requirements constrain qualified PX supply to major integrated refiners with dedicated purification trains. Ludwigshafen chemical corridor demand concentrates in optical-grade film specifications for display substrate applications. BASF SE and downstream polymer compounders source through Rotterdam merchant hubs with mass-balance certification documentation.
Paraxylene(PX) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical conglomerates commanding captive demand absorption while merchant-grade traders compete on specification flexibility and certification documentation. The vendor base concentrates around four strategic archetypes: state-controlled national oil companies with refinery-petrochemical integration, multinational energy majors with Singapore-Rotterdam merchant hub positioning, Korean and Japanese refiner-chemical hybrids with ASEAN export focus, and Indian conglomerates with downstream textile chain control. Dominant competitive moves include capacity expansion in coastal China under MEE permit approvals and strategic partnerships for bio-based PX pilot offtake agreements.
Within the state-controlled tier, China National Petroleum Corporation and Sinopec occupy positions as domestic supply anchors across China's eastern seaboard. Among multinational merchant-grade specialists, ExxonMobil Corporation exemplifies hub-based competition through Singapore and Rotterdam infrastructure. Reliance Industries Limited represents the vertically integrated archetype with Jamnagar complex captive demand absorption. These three entities illustrate how geographic positioning and integration depth determine competitive viability in specification-grade aromatics supply.
| Leading Market Players |
|---|
| Reliance Industries Limited |
| China National Petroleum Corporation |
| Sinopec |
| ExxonMobil Corporation |
| Saudi Aramco |
| BP PLC |
| JX Nippon Oil & Energy Corp |
| GS Caltex |
| S-Oil |
| Others |
Value Network & Pricing Analysis
Bottle-grade PTA procurement specifications from European packaging makers force naphtha-origin PX suppliers to absorb certification costs, compressing margins for merchant-grade exporters while rewarding integrated reforming complexes with captive purification trains. This demand-side quality premium widens the spread between spot market volatility and contract-based offtake stability.
Pricing Analysis
Volume capture dominates integrated PTA producers while margin protection drives merchant-grade spot trading. Three-tier pricing structure across optical-grade, bottle-grade, and fiber-grade specifications reflects purity thresholds and REACH certification documentation. Pricing pressure stems from naphtha cost volatility linked to crude benchmarks, squeezing standalone aromatics producers disproportionately. Merchant spot buyers exhibit highest price sensitivity; electronics-grade optical film purchasers show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Naphtha feedstock supply rests on Middle Eastern crude exporters and Asian refinery output from South Korea, China, and India. Platinum-rhenium catalyst regeneration cycles and specialized technical expertise constrain new entrant capacity additions. Single-source vulnerability concentrates in China's eastern seaboard reforming clusters where MEE emission enforcement triggers regional shutdowns. Distribution runs through Singapore and Rotterdam merchant hubs serving European REACH-certified buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paraxylene sector functions as a vertical-integration race where captive PTA absorption and downstream textile chain control determine competitive survival. Players pursue backward integration into naphtha supply and forward control over fabric manufacturing to defend margin structures.
For Market Incumbents: Deploy catalytic reforming capacity expansion in Zhejiang and Jiangsu provinces under MEE naphtha-route permit approvals. Secure long-term naphtha supply agreements with Middle Eastern crude exporters to buffer margin squeeze from oil price spikes. Invest in optical-grade purification train upgrades to capture premium pricing from Japanese and South Korean electronics makers.
For New Entrants and Emerging Players: The premium-to-economy price gap in merchant-grade fiber specifications offers entry traction for smaller reforming operators with flexible batch processing. Target Indian Gujarat and Tamil Nadu textile clusters where direct esterification adoption outpaces legacy DMT retirement. Pursue toll-manufacturing arrangements with established refiners lacking downstream PTA integration.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated refiner-textile conglomerates given carbon-border adjustment mechanism exposure shifting procurement toward non-China supply nodes. Long-term viability favors assets with captive naphtha supply and downstream fabric absorption within single ownership structures. Watch bio-based PX pilot offtake agreement announcements as inflection indicators for feedstock substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Zhejiang and Jiangsu province reforming additions under MEE permits anchor captive PTA integration economics. |
| Backward Integration | Jamnagar-style naphtha-to-fabric chain control buffers margin volatility from crude-linked feedstock costs. |
| Green Manufacturing Transition | Bio-based PX pilot projects under China's dual carbon goals create renewable feedstock certification premiums. |
| Long-term Supply Agreement | European packaging makers lock in REACH-certified merchant-grade volumes through Rotterdam hub contracts. |
| Joint Venture | Singapore aromatics complexes partner with ASEAN textile distributors to secure K-REACH documentation compliance. |
Research Methodology
Trade databases, SEC 10-K filings from integrated petrochemical conglomerates, and customs export records formed the secondary backbone for volume and flow calibration. Primary interviews with catalytic reforming plant managers, PTA procurement leads at polyester fiber manufacturers, and Singapore merchant hub traders validated capacity utilization assumptions. Bottom-up and top-down triangulation reconciled refinery output data with downstream polymer absorption estimates.
Bottom-up modeling built from individual reforming unit capacities and PTA plant offtake contracts, while top-down analysis cross-checked against regional petrochemical consumption patterns. Segmentation dimensions included product grade tier, end-use application, manufacturing process route, and coastal versus inland production hub clustering. CAGRs derived from trend extrapolation of naphtha-route expansion permits under MEE enforcement and bio-based substitution pilot scaling. Feedstock cost curves and carbon-border adjustment exposure shaped regional demand migration assumptions.
Inputs from Chinese Ministry of Ecology and Environment permit databases and Korean K-REACH compliance registries were available through the study window; gaps in proprietary catalyst regeneration cycle data introduce uncertainty bands around marginal cost estimates. Forecasts reflect documented assumptions about dual carbon policy continuity and direct esterification adoption rates. Naphtha price volatility, regional emission shutdowns, and bio-PX commercialization timelines constitute revision triggers. A small set of regulatory enforcement intensity and feedstock-switching economics indicators warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Global Capric Acid Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
North America Acetic Acid Market