
 Hydrochloric Acid Market | 2026-2036
Hydrochloric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrochloric Acid Market Analysis
Saudi Arabia's industrial city build-outs at Jubail and Yanbu are rewriting regional supply geography for merchant acid availability. Olin Corporation leverages integrated chlor-alkali networks across North American Gulf Coast corridors. BASF SE anchors European supply through Ludwigshafen hub operations. INEOS competes on captive chlorine integration across its UK and continental manufacturing footprint.
Hydrochloric acid is an aqueous solution of hydrogen chloride gas, typically produced at concentrations ranging from 32% to 38% by weight through direct synthesis or as a chlor-alkali by-product, serving primarily as a strong mineral acid for pH adjustment, metal surface treatment, and chemical synthesis. Industrial grade dominates volume flows into steel pickling and oilfield acidizing, while reagent grade commands premium positioning in analytical laboratories and electronics fabrication where trace-metal specifications determine usability. Food grade applications in corn syrup refining and protein processing represent a regulated margin pool with stringent FDA and EFSA purity thresholds.
EPA effluent guidelines under the Clean Water Act constrain US discharge concentrations from metal finishing facilities, pushing end-users toward closed-loop regeneration systems. REACH registration requirements in Europe mandate supply-chain documentation for downstream chemical manufacturing users of industrial grade material. China's MEE enforcement of GB standards on hydrochloric acid emissions from chlor-alkali plants is tightening merchant supply availability. Stakeholders must monitor how carbon-border adjustment mechanisms reshape the cost structure of chlorine-derived acid against alternative sulfuric acid substitution in steel processing.
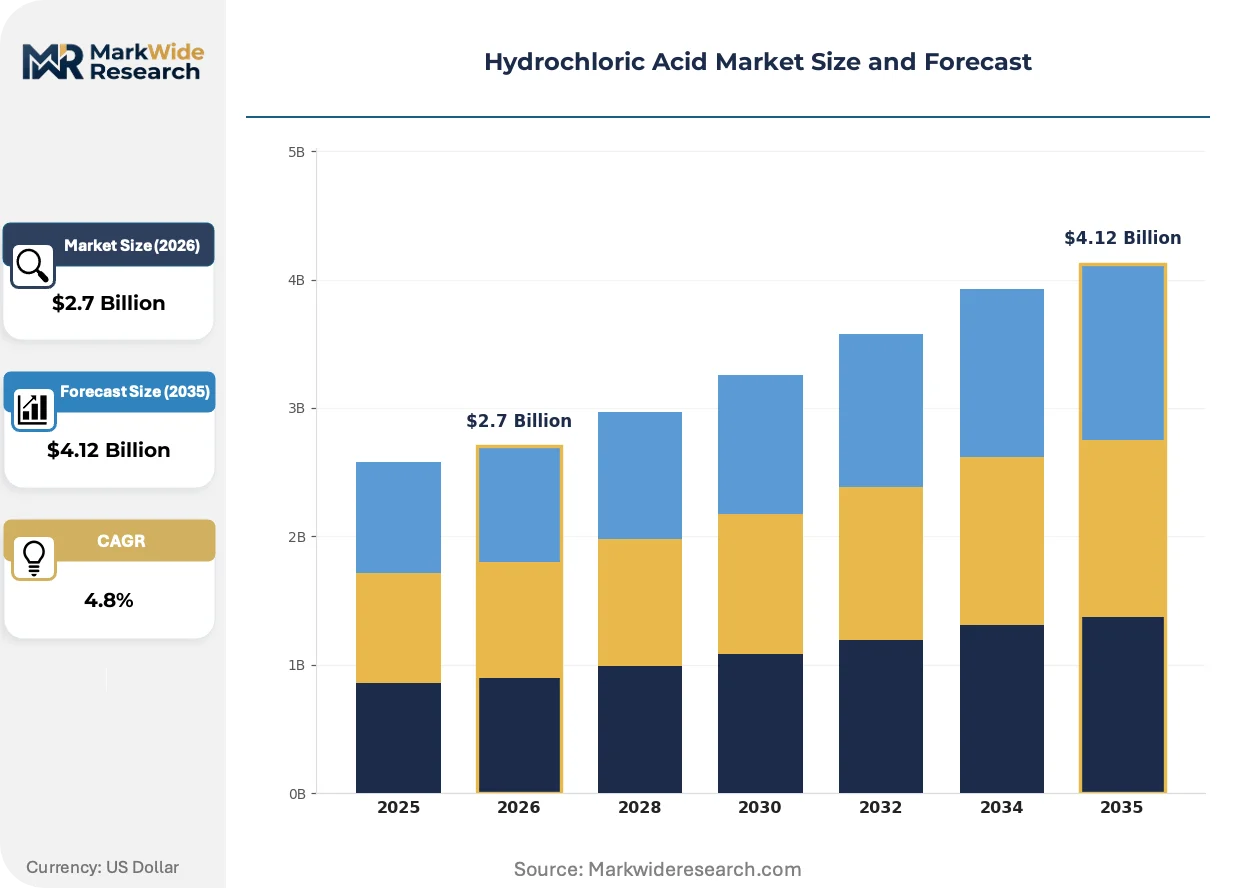
Market Dynamics
Chlor-alkali co-production economics are redirecting merchant acid flows as China's MEE enforcement tightens emission standards on integrated plants, forcing capacity reallocation toward compliance-grade output and reshaping spot-market availability across East Asian chemical manufacturing corridors.
Growth Catalysts
- Steel Pickling Intensity:Automotive lightweighting programs and construction sector expansion in Germany, Japan, and the United States are elevating consumption of industrial-grade material for surface preparation on high-strength alloys.
- REACH Registration Mandates:ECHA documentation requirements for downstream chemical manufacturing are consolidating supply relationships around registered producers with verified supply-chain transparency.
- Oilfield Acidizing Resurgence:Permian Basin and Vaca Muerta unconventional drilling operations are restoring demand for high-purity acid in carbonate reservoir stimulation.
Market Restraints
- Chlorine Feedstock Volatility:Electrolysis energy costs and caustic soda co-product pricing swings transmit directly into hydrochloric acid production economics.
- Merchant Supply Concentration:Chlor-alkali capacity clustering along the US Gulf Coast and China's Yangtze River Delta creates geographic vulnerability to weather and logistics disruptions.
- Sulfuric Acid Substitution:Steel processors in India and Brazil are evaluating alternative mineral acids for pickling operations where chloride stress corrosion presents technical constraints.
Strategic Opportunities
- Electronics-Grade Purification:Semiconductor fabrication in Taiwan and South Korea is generating premium demand for sub-ppb trace-metal specification acid.
- Closed-Loop Regeneration Systems:EPA effluent guidelines under the Clean Water Act are incentivizing spent acid recovery investments among metal finishing facilities.
- Food-Grade Certification Expansion:FDA and EFSA purity thresholds for corn syrup refining and protein processing represent margin-accretive niche positioning.
Industry Challenges
- Corrosion Engineering Expertise Gap:Facility operators lack qualified personnel for managing high-concentration acid storage and handling systems.
- Transportation Equipment Certification:Specialized tank car and ISO tank container approvals for hazardous material carriage extend procurement lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrochloric Acid Market |
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Reagent Grade, Anhydrous Delivery Mode: Bulk Supply, Drum Supply, Canister Supply, Tank Truck Application: Metal Cleaning, Food Processing, pH Control, Water Treatment End Use Industry: Chemical Manufacturing, Pharmaceuticals, Textile, Oil & Gas |
| Companies Covered | Olin Corporation, Westlake Chemical Corporation, BASF SE, Covestro AG, Occidental Petroleum Corporation, INEOS, INOVYN, Formosa Plastics Corporation, ERCO Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrochloric Acid Market Emerging Trajectories
Membrane electrolysis technology diffusion and digital process control integration are compressing production cost structures while tightening quality consistency, enabling producers to serve diverging specification requirements across industrial and electronic-grade segments without parallel asset bases.
Membrane cell technology is collapsing the cost gap between diaphragm and mercury-cell chlor-alkali processes. European and North American producers adopting membrane electrolysis are achieving 15-20% energy efficiency gains over legacy systems. This technology convergence is enabling single-plant flexibility to swing output between industrial and reagent-grade specifications.
China's MEE enforcement of GB standards on hydrogen chloride emissions is forcing chlor-alkali operators to retrofit absorption and scrubbing systems. Integrated plants in Shandong and Jiangsu provinces are redirecting acid output toward captive consumption rather than merchant sales. This regulatory compression is tightening spot-market availability and elevating regional price premiums.
Steel mills are consolidating acid procurement around long-term tolling arrangements with regeneration service providers. Metal processors in the US Midwest and Germany's Ruhr region are outsourcing spent acid recovery rather than maintaining on-site treatment infrastructure. This service-model transition is visible most acutely among mid-scale automotive stamping operations seeking to defray EPA compliance capital burdens.
Hydrochloric Acid Market Segmentation
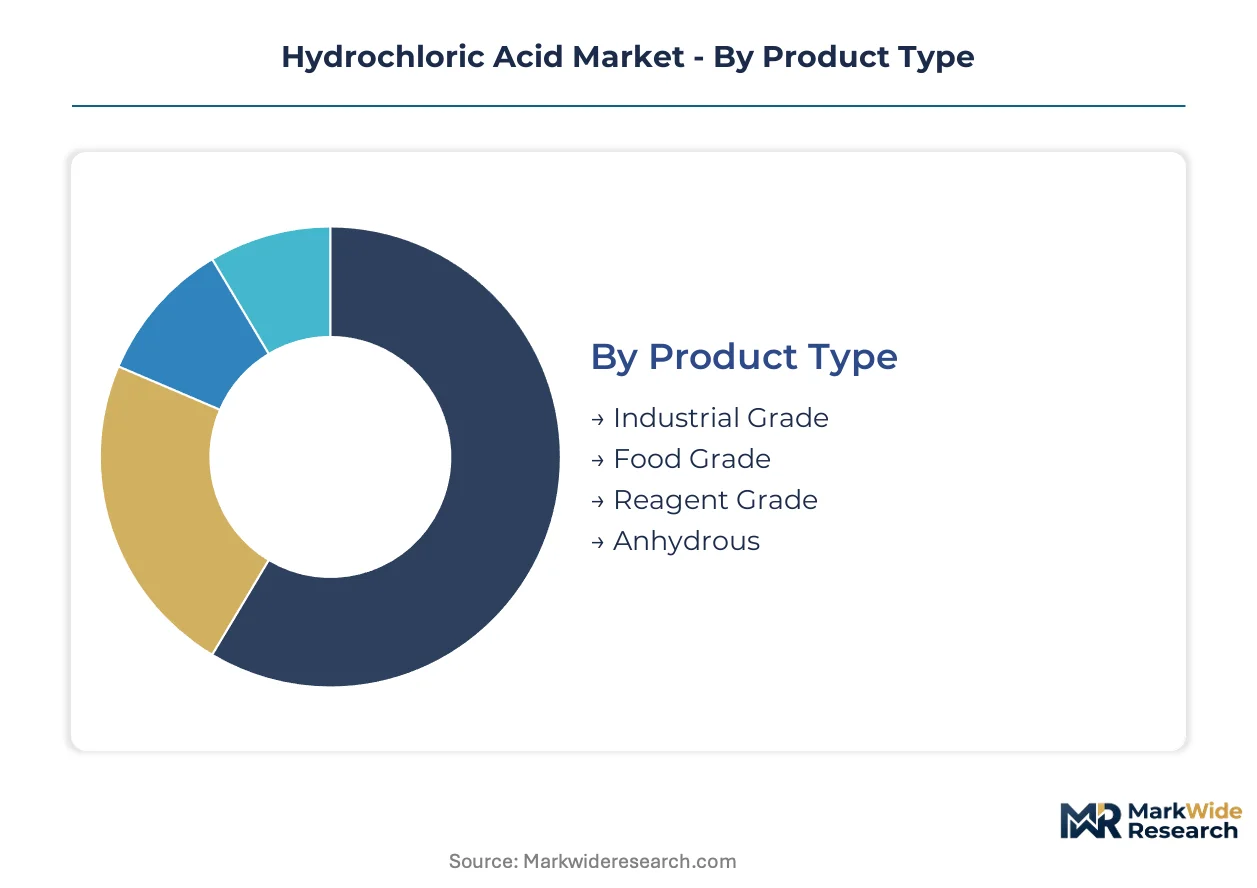
Segmentation in hydrochloric acid markets reflects diverging purity specifications and logistics requirements across steel processing, semiconductor fabrication, and regulated food applications. Producers configure membrane electrolysis assets to swing output between industrial and reagent grades without dedicated plant lines.
Product Type:
Mature industrial specifications dominate volume flows while emerging electronic-grade purity standards command premium positioning in semiconductor corridors.
- Industrial Grade:Aqueous solutions of 32-38% concentration serve steel pickling and oilfield acidizing where trace-metal tolerance is higher. Demand concentrates in automotive stamping operations across Germany, Japan, and the United States as lightweighting programs elevate high-strength alloy processing.
- Reagent Grade:Sub-ppb trace-metal specifications enable analytical laboratory and electronics fabrication applications. Taiwan and South Korean semiconductor foundries are driving premium demand as advanced node production tightens impurity thresholds.
- Food Grade:FDA and EFSA purity thresholds govern corn syrup refining and protein processing applications with stringent heavy-metal limits.
- Anhydrous:Hydrogen chloride gas form serves specialized chemical synthesis and pharmaceutical intermediate production requiring water-free conditions.
Industrial Grade retains volume leadership; Reagent Grade holds the steepest expansion curve.
Delivery Mode:
Cost tier differentiation separates high-volume pipeline and tank truck arrangements from packaged formats serving dispersed small-scale consumers.
- Bulk Supply:Pipeline and dedicated terminal deliveries anchor chlor-alkali integrated producers serving clustered chemical manufacturing corridors. The US Gulf Coast and China's Yangtze River Delta concentrate these flows around captive consumption networks.
- Tank Truck:Regional distribution of 5,000-8,000 gallon loads serves metal finishing and water treatment facilities without pipeline access. Midwest US automotive stamping clusters and Germany's Ruhr region depend on this modal flexibility.
- Drum Supply:55-gallon steel and composite containers reach mid-scale chemical processors and maintenance shops requiring intermittent replenishment.
- Canister Supply:Small-volume cylinders and pressurized containers support laboratory, pilot plant, and specialty chemical synthesis applications.
Bulk Supply commands the lowest per-unit logistics cost; Tank Truck delivery is climbing the fastest as regional processing clusters multiply.
Application:
Application segmentation tracks functional chemistry requirements from aggressive oxide removal to precise pH modulation in regulated environments.
- Metal Cleaning:Surface oxide and scale removal in steel pickling, aluminum etching, and metal finishing operations. German and US automotive supply chains are elevating consumption as high-strength alloy adoption intensifies.
- pH Control:Alkalinity neutralization in chemical synthesis, wastewater streams, and process water conditioning. China's tightening MEE discharge standards are redirecting chlor-alkali output toward compliance-grade material for industrial effluent treatment.
- Food Processing:Corn syrup refining, protein hydrolysis, and beverage acidification under FDA and EFSA oversight with strict heavy-metal documentation.
- Water Treatment:Municipal and industrial pH adjustment, ion exchange regeneration, and disinfection by-product control in potable and process water systems.
Metal Cleaning retains volume leadership; pH Control is gaining share fastest as environmental compliance tightens across East Asian manufacturing zones.
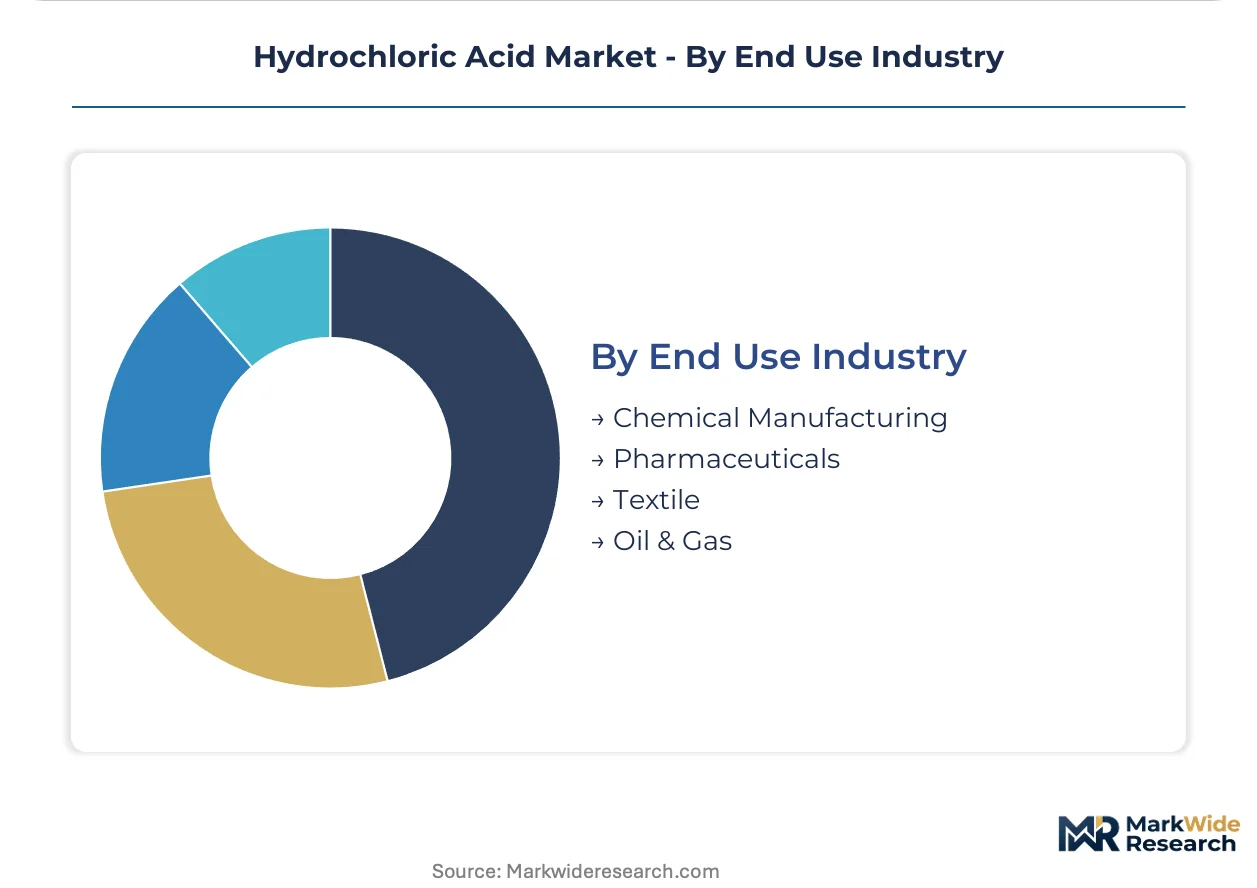
End Use Industry:
Customer type segmentation reveals diverging procurement patterns between commodity chemical consumers and specification-sensitive pharmaceutical and electronics sectors.
- Chemical Manufacturing:Chlorine derivative synthesis, catalyst preparation, and intermediate production consuming merchant acid at scale. Shandong and Jiangsu province chlor-alkali operators are redirecting output toward captive consumption as China's MEE enforcement tightens.
- Oil & Gas:Carbonate reservoir stimulation through acidizing operations in Permian Basin and Vaca Muerta unconventional drilling. High-purity requirements for downhole corrosion management distinguish this segment from industrial grade specifications.
- Pharmaceuticals:API synthesis, salt formation, and pH adjustment under GMP documentation requirements with batch-level traceability mandates.
- Textile:Fiber processing, dye bath pH control, and finishing chemical preparation consuming consistent-quality industrial grade material.
Chemical Manufacturing retains volume leadership; Oil & Gas shows the steepest expansion trajectory as unconventional drilling resurges in North and South American basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement in China is redirecting chlor-alkali co-production toward compliance-grade output, tightening merchant acid availability across East Asian manufacturing corridors and elevating regional price premiums.
China
Steel pickling operations in Shanghai and the Yangtze River Delta are absorbing industrial-grade volumes as automotive lightweighting accelerates. MEE oversight of GB emission standards is forcing Shandong and Jiangsu province operators to retrofit absorption systems. Merchant acid flows are contracting as integrated plants prioritize captive consumption over spot-market sales.
United States
Permian Basin unconventional drilling is restoring oilfield acidizing demand for high-purity material in carbonate reservoir stimulation. EPA effluent guidelines under the Clean Water Act are pushing metal finishers toward closed-loop regeneration investments. Gulf Coast chlor-alkali corridors concentrate bulk supply networks around Olin Corporation and Westlake Chemical integrated operations.
Germany
Automotive stamping clusters in the Ruhr region are elevating consumption for high-strength alloy surface preparation. REACH registration mandates from ECHA are consolidating supply relationships around registered producers with verified supply-chain documentation. BASF SE anchors European merchant availability through Ludwigshafen hub operations.
Saudi Arabia
Jubail and Yanbu industrial city build-outs are rewriting regional supply geography for merchant acid availability across Middle Eastern chemical manufacturing. SABIC-affiliated chlor-alkali expansions are capturing downstream derivative demand locally. Integrated petrochemical complexes are reducing import dependence for steel processing and water treatment applications.
Japan
Semiconductor fabrication in Kyushu and Kansai corridors is generating premium demand for sub-ppb trace-metal specification reagent-grade material. METI industrial policy is incentivizing domestic electronics chemical supply chain security. Osaka-based metal processors are outsourcing spent acid recovery to specialized regeneration service providers.
Hydrochloric Acid Market Vendor Landscape
Integrated chlor-alkali operators and merchant chemical distributors split the market between captive consumption networks and spot-market availability. The vendor base clusters around Gulf Coast and Yangtze River Delta production corridors, with membrane electrolysis technology compressing cost structures. Three archetypes dominate: chlor-alkali integrated majors, regional tolling specialists, and electronics-grade purification players. Competitive moves center on capacity reallocation toward compliance-grade output and long-term tolling arrangements with steel mill regeneration providers.
Among North American integrated operators, Olin Corporation and Westlake Chemical Corporation exemplify the chlor-alkari major archetype through Gulf Coast corridor positioning. BASF SE anchors European supply architecture from its Ludwigshafen hub. INEOS occupies a position within the UK and continental captive integration tier.
| Leading Market Players |
|---|
| Olin Corporation |
| Westlake Chemical Corporation |
| BASF SE |
| Covestro AG |
| Occidental Petroleum Corporation |
| INEOS |
| INOVYN |
| Formosa Plastics Corporation |
| ERCO Worldwide |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta chlor-alkali corridor concentrates membrane electrolysis capacity that feeds downstream pricing power to integrated producers serving Shanghai's chemical manufacturing clusters. China's MEE enforcement on GB emission standards is compressing merchant acid spot availability, elevating regional premiums as captive consumption displaces open-market sales.
Pricing Analysis
East Asian price spreads widen against Gulf Coast benchmarks as China's environmental compliance costs transmit into delivered costs. Pricing stratifies across reagent-grade electronics specifications, industrial-grade steel pickling tiers, and food-grade certification levels. Cost compression in industrial-grade material intensifies because sulfuric acid substitution threatens chloride-based pickling contracts. Chemical manufacturing procurement teams exhibit highest price sensitivity; semiconductor foundries demonstrate lowest sensitivity due to trace-metal specification rigidity.
Supply Chain Analysis
Extended payment terms from chlor-alkali majors to downstream distributors have tightened working capital requirements across merchant acid networks. Production draws from China, the United States, and Germany as the three dominant supply anchors. Raw material dependencies center on chlorine gas feedstock, electrolysis membrane components, and specialized corrosion-resistant storage alloys. Single-source vulnerability concentrates around Yangtze River Delta weather exposure and Gulf Coast hurricane disruption. Distribution runs through pipeline-terminal networks for bulk consumers, tank truck fleets for regional metal processors, and drum logistics for intermittent chemical synthesis users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
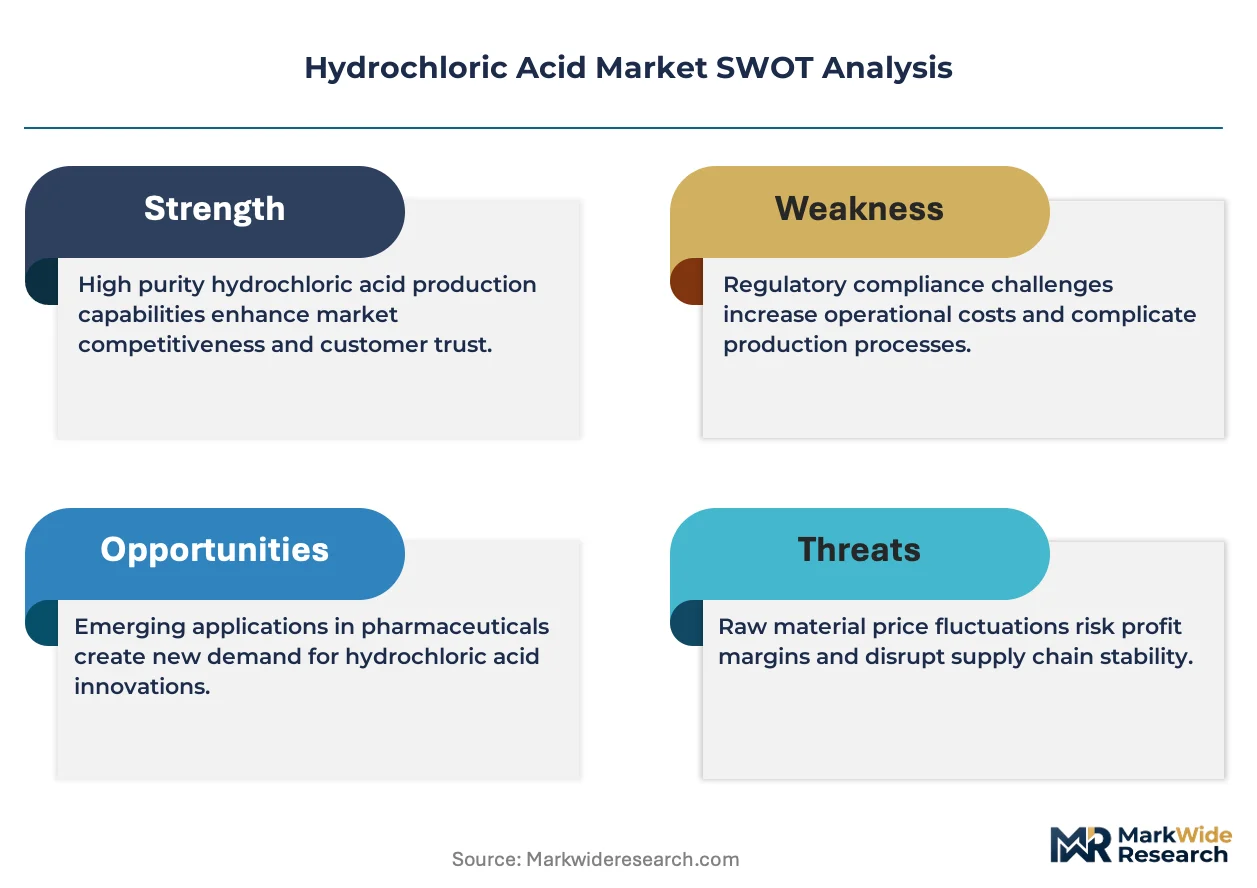
Sulfuric acid substitution in steel pickling operations poses a structural threat that incumbent hydrochloric acid producers must navigate through specification differentiation and regeneration service bundling.
For Market Incumbents: Insulate market position by deepening captive chlorine integration across chlor-alkali networks and accelerating closed-loop regeneration infrastructure investments with automotive stamping clusters. Sulfuric acid substitution in Indian and Brazilian steel mills demands defensive specification marketing around chloride stress corrosion performance. Backward integration into membrane electrolysis technology compresses production cost structures against merchant competitors. For New Entrants and Emerging Players: Establish a beachhead in electronics-grade purification serving Taiwan and South Korean semiconductor corridors where sub-ppb trace-metal specifications command sustainable premiums. Food-grade certification for corn syrup refining represents the most penetrable niche given FDA and EFSA barrier complexity that discourages commodity-grade crossover. Lead with tolling arrangements for spent acid recovery rather than greenfield production assets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because membrane electrolysis technology diffusion is compressing cost structures and squeezing sub-scale merchant operators toward exit. Target regional tolling specialists with established regeneration relationships in Germany's Ruhr region or the US Midwest automotive corridor. Watch MEE enforcement intensity in Shandong and Jiangsu provinces as the inflection signal for Chinese supply rationalization and export opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Membrane electrolysis additions in Saudi Arabia's Jubail corridor capture Middle Eastern derivative demand growth. |
| Backward Integration | Captive chlorine supply from chlor-alkali networks insulates against caustic soda co-product pricing volatility. |
| Long-term Supply Agreement | Tolling arrangements with automotive stamping operations defray EPA compliance capital burdens for metal finishers. |
| Green Manufacturing Transition | Closed-loop regeneration systems align with Clean Water Act effluent guidelines and MEE GB standards. |
| Joint Venture | Electronics-grade purification partnerships with Taiwan semiconductor foundries lock in sub-ppb specification supply. |
Methodological Framework
Cross-validation between primary interviews with chlor-alkali plant managers, downstream procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors anchors the qualitative findings against secondary validation from customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement disclosures. Bottom-up capacity modeling and top-down consumption estimation triangulate volume figures across the analysis window.
Calibration against historical chlor-alkali operating rates and steel pickling intensity indices validates the projection framework. Segmentation dimensions span grade tier, end-use industry, delivery mode, and regional production hub. CAGRs derive from trend extrapolation moderated by regulatory inflection points and technology substitution elasticity. Forecast inputs incorporate membrane electrolysis diffusion curves and MEE enforcement trajectory assumptions.
Stress conditions across chlorine feedstock volatility, sulfuric acid substitution elasticity, and logistics disruption severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aniline Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
2-Ethyl Hexanol Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
Ammonia Storage Tanks Market