
 Middle-East and Africa Carbon Black Market | 2026-2036
Middle-East and Africa Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Carbon Black Market Foresight
Product bundling around furnace black and reinforcing grades is consolidating procurement decisions for major tire producers across the Middle-East and Africa. Cabot Corporation leverages its technical service infrastructure to anchor long-term supply agreements with automotive OEMs in the region. Birla Carbon sustains cost competitiveness through backward integration into feedstock sourcing near Gulf petrochemical complexes. Orion S.A differentiates via specialty carbon black portfolios targeting coatings and plastics applications with stringent dispersion requirements.
Carbon black is a colloidal carbon material produced through incomplete combustion or thermal decomposition of hydrocarbons, typically with primary particle sizes ranging from 10 to 500 nanometers and surface areas between 20 and 250 square meters per gram; it functions primarily as a reinforcing filler in rubber compounds and as a pigmenting and conductivity agent in non-rubber applications. Specialty grades command premium positioning due to controlled particle morphology and surface chemistry requirements in high-performance coatings and conductive polymers. Furnace black dominates volume throughput across the region given its scalability and adaptability to varying feedstock qualities. Tire manufacturing absorbs the largest share of regional output, though plastics compounding for consumer goods represents the fastest-expanding application segment as polymer converters seek UV stabilization and color consistency.
Saudi Arabia's SFDA and South Africa's National Regulator for Compulsory Specifications enforce product safety standards that filter substandard imports from regional distribution channels. REACH-aligned chemical management protocols in Gulf Cooperation Council markets are elevating documentation burdens for specialty carbon black importers serving coatings and ink formulators. Stakeholders must monitor feedstock cost volatility linked to regional refinery output decisions and assess captive production investments before competitor lock-in accelerates across Jubail and Ras Laffan industrial zones.
Market Dynamics
Petrochemical integration around Saudi Arabia's Jubail Industrial City is consolidating carbon black supply chains, as tire manufacturers demand compound formulations that meet higher load-bearing specifications while local content rules in South Africa redirect procurement toward domestic suppliers.
Growth Catalysts
- REACH-aligned chemical management protocols:Gulf Cooperation Council markets are elevating documentation standards for specialty carbon black importers serving coatings and ink formulators, filtering substandard competitors from distribution channels.
- Tire manufacturing expansion:Compound formulators across the Middle-East and Africa are scaling furnace black consumption to meet reinforced rubber specifications for commercial vehicle OEMs.
- Jubail Industrial City concentration:Integrated production complexes adjacent to regional refineries are capturing feedstock cost advantages that independent processors cannot replicate.
Market Restraints
- Feedstock volatility:Regional refinery output decisions in Saudi Arabia and the UAE create input cost instability for non-integrated carbon black producers lacking captive naphtha or residual oil supplies.
- Import dependency concentration:Specialty grades for high-dispersion coatings applications remain concentrated among external suppliers, exposing formulators to shipping timeline risks through Red Sea corridor disruptions.
- Silica substitution in tire treads:Low-rolling-resistance compound requirements are displacing carbon black partial volumes in passenger tire segments, though truck and OTR tire specifications maintain filler demand.
Strategic Opportunities
- South Africa automotive localization:The Department of Trade, Industry and Competition's tightened local content requirements for automotive components are redirecting procurement toward domestic carbon black suppliers with SABS certification capabilities.
- Plastics compounding for consumer goods:Polymer converters across Nigeria and Kenya are adopting UV-stabilized masterbatches for durable goods packaging, opening specialty carbon black volumes beyond traditional rubber applications.
- Ras Laffan industrial zone expansion:Qatar's petrochemical corridor offers greenfield integration potential for producers seeking feedstock-adjacent furnace black capacity with Gulf export access.
Industry Challenges
- SFDA product safety compliance:Saudi Arabia's national regulator enforces stringent batch testing protocols that extend certification timelines for specialty grade importers unfamiliar with Gulf conformity assessment procedures.
- Process control engineering scarcity:Furnace black production requires combustion optimization expertise that remains concentrated among a limited pool of regional technical specialists, constraining operational scale-up for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Carbon Black Market |
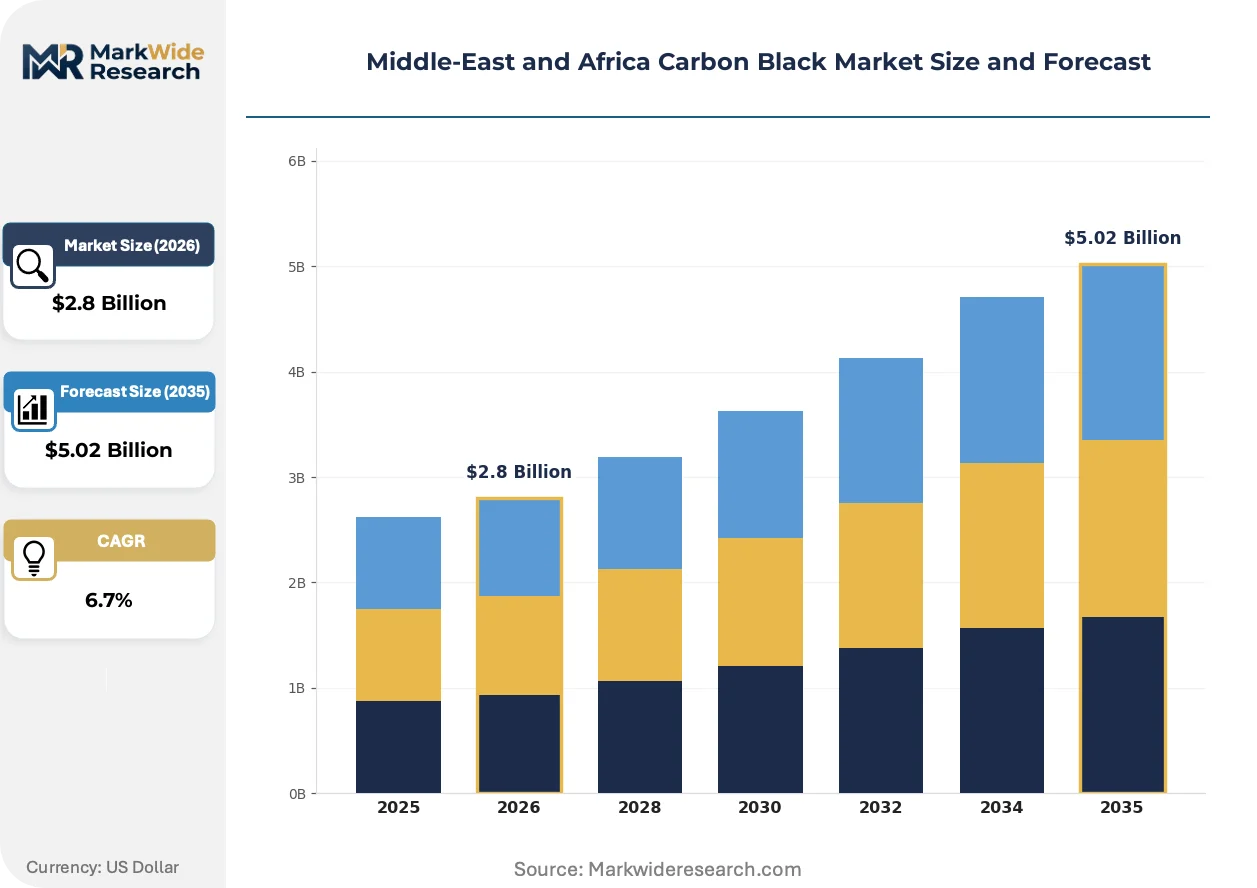
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Specialty, Reinforcing, Conductive Application: Tire Manufacturing, Coatings, Plastics, Inks End User: Aerospace, Automotive, Construction, Consumer Goods Production Process: Acetylene Black, Furnace Black, Thermal Black, Other |
| Companies Covered | Cabot Corporation, Birla Carbon, Continental Carbon Company, Orion S.A, SABIC, ADNOC, Phillips Carbon Black, Imerys, Tokai Carbon, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Carbon Black Market Shifts & Advancements
Technical service infrastructure and backward integration strategies are reshaping competitive positioning across the Middle-East and Africa, as producers compete on formulation support rather than commodity tonnage alone.
Furnace black production technology is consolidating procurement decisions for major tire producers across the region. Cabot Corporation anchors long-term supply agreements through embedded technical service teams co-located with automotive OEM compound development labs. This consolidation is compressing spot-market volumes as integrated producers lock in multi-year offtake commitments with volume-tiered pricing structures.
REACH-aligned chemical management protocols in Gulf Cooperation Council markets are elevating documentation burdens for specialty carbon black importers. The industrial consequence is a filtering effect that advantages established suppliers with pre-existing substance registration portfolios. Coatings and ink formulators in the UAE and Saudi Arabia are responding by consolidating vendor lists toward REACH-compliant distributors with Gulf-validated safety data sheets.
Buyer concentration among regional tire manufacturers is compressing negotiation cycles and unbundling technical service from base material supply. Major compounders in Jubail Industrial City now separate formulation consulting from carbon black procurement, engaging independent technical advisors while sourcing feedstock-adjacent furnace black through direct refinery partnerships. This pattern is most visible in Saudi Arabia, where petrochemical integration enables transparent cost-plus contracting that eliminates traditional distributor markups.
Middle-East and Africa Carbon Black Market Segmentation
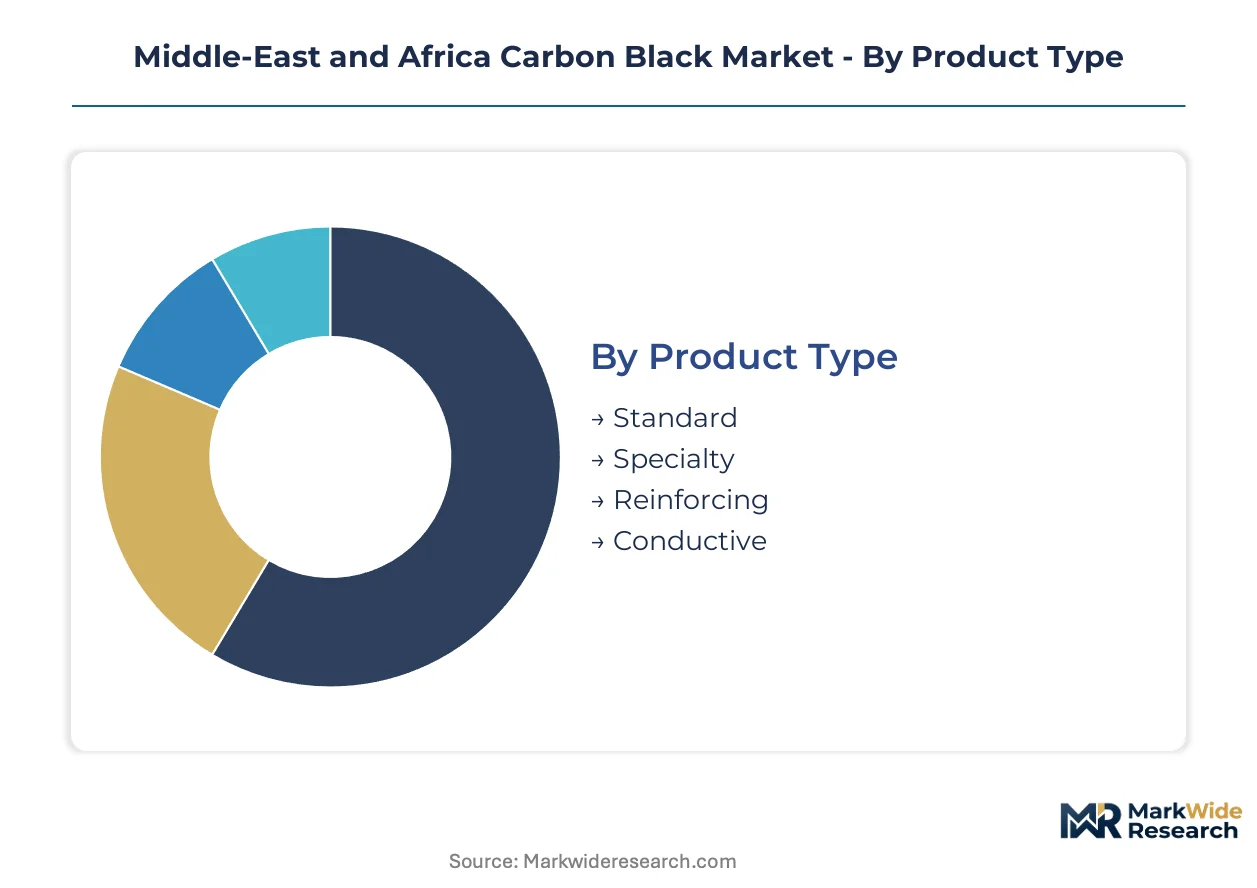
Carbon black segmentation across the Middle-East and Africa reflects divergent compliance burdens and feedstock access patterns. Tire manufacturers in Jubail Industrial City source furnace black under streamlined SFDA protocols, while coatings formulators face REACH-aligned documentation hurdles for specialty imports.
Product Type:
SFDA batch testing protocols apply differentially across grades, with specialty carbon black requiring extended Gulf conformity assessment timelines that filter smaller importers from distribution channels.
- Standard:Furnace-derived commodity grades with particle sizes between 20 and 100 nanometers absorb the majority of regional tire compound demand. Saudi Aramco's residual oil feedstock supplies integrated producers in Jubail with cost-plus contracting advantages that independent processors cannot match.
- Specialty:Controlled surface chemistry and morphology specifications serve high-dispersion coatings and conductive polymer applications. UAE-based ink formulators consolidate procurement toward REACH-compliant distributors with pre-validated safety data sheets to avoid Gulf customs delays.
- Reinforcing:High-structure grades engineered for load-bearing rubber compounds in commercial vehicle tires.
- Conductive:Precision-engineered particle networks enabling static dissipation in electronics packaging and industrial safety equipment.
Leading the category by volume: Standard. Growing fastest: Specialty.
Application:
Cost tier stratification separates commodity rubber reinforcement from premium pigment and conductivity functions, with feedstock-adjacent producers capturing the former and importers defending the latter.
- Tire Manufacturing:Furnace black consumption scales with commercial vehicle OEM specifications across Saudi Arabia and South Africa. SABS certification requirements in South Africa redirect procurement toward domestic suppliers as local content rules tighten under DTIC enforcement.
- Coatings:Specialty grades with stringent dispersion requirements command premium positioning in architectural and industrial finishes. Red Sea shipping corridor disruptions expose formulators to timeline risks when sourcing from external suppliers lacking regional inventory buffers.
- Plastics:UV-stabilized masterbatches for durable goods packaging represent the steepest expansion trajectory as Nigerian and Kenyan polymer converters adopt color consistency standards.
- Inks:Pigment-grade carbon black with controlled oil absorption serves publication and packaging print applications.
Highest margin concentration: Coatings. Steepest volume climb: Plastics.
End User:
Customer type maturity varies sharply, with automotive OEMs demanding embedded technical service while construction buyers prioritize transparent cost-plus contracting.
- Automotive:Compound development labs in Jubail Industrial City separate formulation consulting from feedstock procurement, engaging independent technical advisors while sourcing furnace black through direct refinery partnerships.
- Construction:Sealant and roofing membrane applications consume standard grades with less stringent batch documentation requirements.
- Aerospace:Specialty conductive and reinforcing grades meeting stringent flame-resistance and static-dissipation specifications.
- Consumer Goods:Plastics compounding for packaging drives specialty carbon black adoption as Kenyan and Nigerian converters scale UV-stabilized masterbatch production.
Deepest technical service integration: Automotive. Fastest demand acceleration: Consumer Goods.
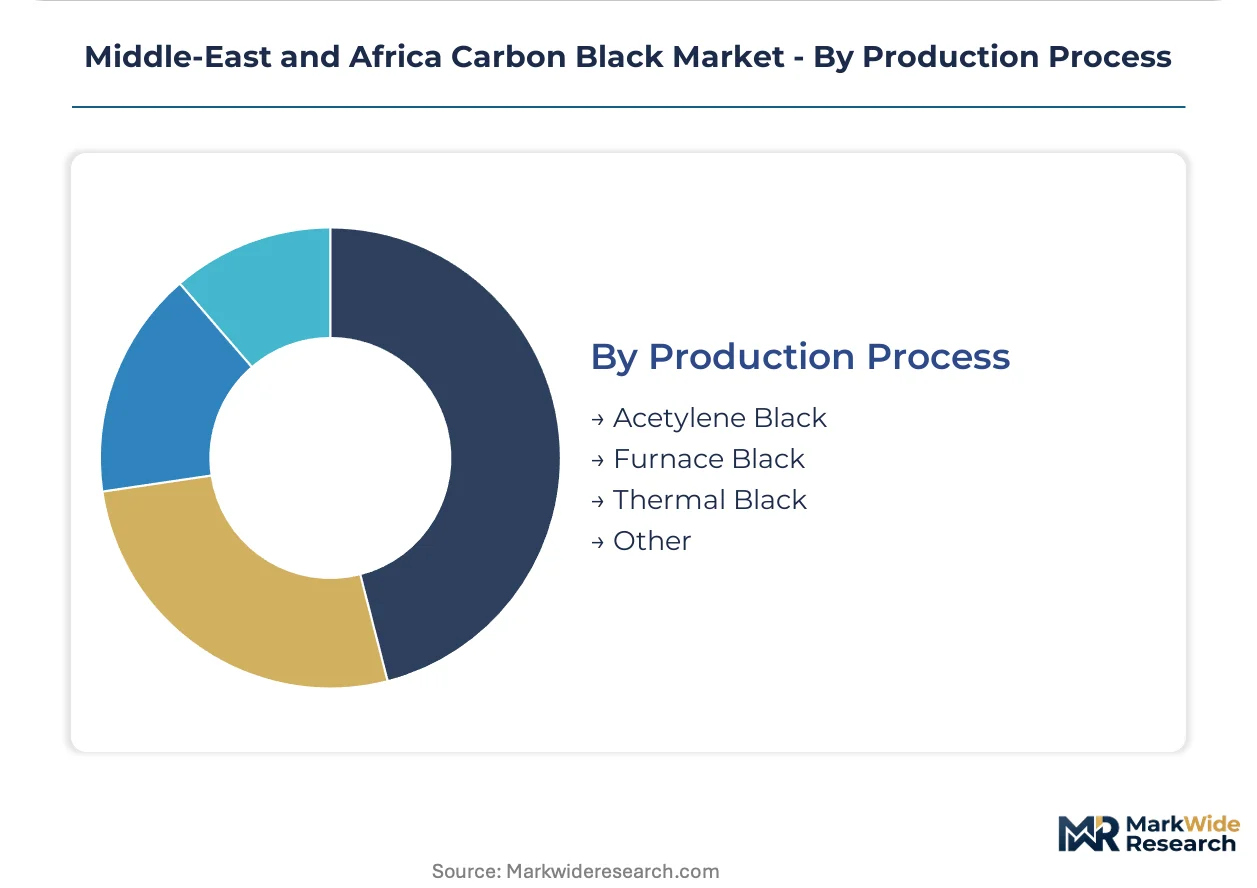
Production Process:
Supply concentration around Gulf petrochemical corridors advantages furnace black while process control engineering scarcity constrains acetylene and thermal black scale-up.
- Furnace Black:Scalable incomplete combustion of aromatic oils yields the dominant regional output, with Jubail and Ras Laffan integration capturing feedstock cost advantages.
- Thermal Black:Natural gas decomposition produces large-particle, low-structure grades for specialty rubber and insulation applications.
- Acetylene Black:High-purity conductive grades derived from acetylene decomposition serve battery and electronics applications with limited regional production.
- Other:Channel and lamp black processes retaining niche heritage pigment applications.
Widest production footprint: Furnace Black. Tightest technical specialist pool: Acetylene Black.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production concentrates in Saudi Arabia's petrochemical corridors while consumption spreads across tire manufacturing hubs in South Africa and the UAE. This geographic split shapes freight economics and procurement strategies for compounders lacking integrated supply.
Saudi Arabia
Jubail Industrial City hosts integrated carbon black facilities feeding adjacent tire plants with furnace black from refinery residual streams. SFDA enforces batch testing protocols that extend certification timelines for specialty grade importers. Ras Laffan industrial zone offers greenfield expansion potential for feedstock-adjacent capacity with Gulf export positioning.
South Africa
Domestic tire manufacturers absorb reinforcing grades under tightened DTIC local content rules redirecting procurement toward SABS-certified suppliers. The Department of Trade, Industry and Competition enforces automotive component localization thresholds that filter non-compliant imports. Port Elizabeth and Durban industrial corridors concentrate rubber goods production requiring high-structure carbon black specifications.
United Arab Emirates
Coatings and ink formulators in Jebel Ali Free Zone source specialty grades with stringent dispersion requirements for architectural finishes. MOHAP-aligned chemical management protocols elevate documentation burdens for REACH-compliant distributors serving the emirates. Dubai and Sharjah logistics hubs buffer inventory against Red Sea shipping corridor disruptions.
Qatar
Ras Laffan petrochemical integration supports furnace black production scaling with regional refinery output decisions. The country's national industrial regulator maintains conformity assessment procedures for chemical imports serving downstream manufacturing. Mesaieed industrial city anchors polymer conversion capacity consuming UV-stabilized masterbatches for packaging applications.
Nigeria
Lagos and Port Harcourt polymer converters adopt specialty carbon black for durable goods packaging requiring color consistency standards. The country's national standards organization enforces product safety documentation for imported chemical additives. Aba and Onitsha manufacturing clusters drive plastics compounding demand beyond traditional rubber applications.
Middle-East and Africa Carbon Black Market Competitive Landscape
The competitive structure tilts toward petrochemical-integrated producers capturing feedstock cost advantages that independent processors cannot replicate. Market concentration remains moderate with tiered differentiation between commodity furnace black suppliers and specialty grade importers. Two strategic archetypes dominate: backward-integrated Gulf producers leveraging refinery adjacency, and technical service-focused multinationals anchoring long-term automotive supply agreements. Dominant competitive moves include capacity expansion around Jubail and Ras Laffan industrial zones, plus portfolio diversification into conductive and UV-stabilized grades for plastics applications.
Within the integrated producer archetype, SABIC and ADNOC exemplify feedstock-advantaged positioning through captive supply of residual oils and naphtha streams. Among technical service-focused multinationals, Cabot Corporation occupies a position emphasizing embedded formulation support co-located with automotive OEM compound development labs. Birla Carbon sits within the cost-competitive tier, representing backward integration strategies near Gulf petrochemical complexes.
| Leading Market Players |
|---|
| Cabot Corporation |
| Birla Carbon |
| Continental Carbon Company |
| Orion S.A |
| SABIC |
| ADNOC |
| Phillips Carbon Black |
| Imerys |
| Tokai Carbon |
| Others |
Supply & Pricing Matrix
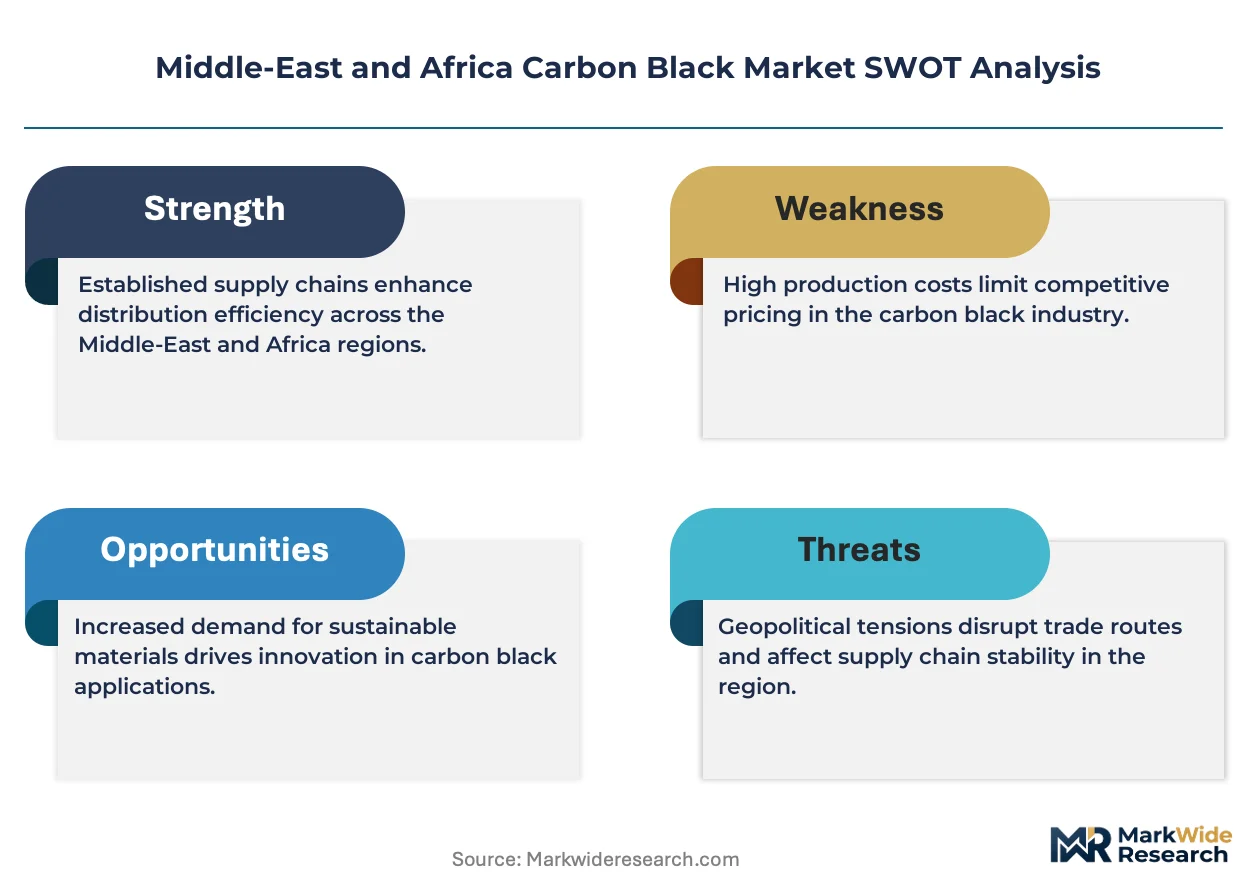
Tire manufacturer consolidation around Jubail Industrial City is forcing furnace black suppliers toward transparent cost-plus contracting that eliminates distributor markups and compresses spot-market premiums. This procurement shift rewards feedstock-adjacent producers with captive refinery supply while squeezing independent processors lacking residual oil access.
Pricing Analysis
Margin tightening in specialty grades reflects REACH-aligned documentation burdens that filter smaller importers from Gulf distribution channels. Contract-based long-term offtake dominates volume procurement, with price differentiation resting on SABS certification tier and volume scale rather than brand premium. Cost-down pressure on standard furnace black accelerates because petrochemical-integrated producers capture feedstock cost advantages that independents cannot match. Automotive OEM compounders exhibit lowest price sensitivity due to embedded technical service requirements, while construction sealant buyers prioritize transparent cost-plus sourcing.
Supply Chain Analysis
SFDA batch testing protocols and Gulf conformity assessment procedures gate specialty carbon black imports, extending certification timelines for coatings formulators. Supply concentrates in Saudi Arabia, South Africa, and the United Arab Emirates, with production drawing from residual oil feedstocks, natural gas streams, and imported aromatic oils. Single-source vulnerability persists around Red Sea shipping corridor disruptions that expose UAE-based ink formulators to timeline risks. Distribution runs through direct refinery partnerships for tire manufacturers and REACH-compliant distributor networks for coatings applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa carbon black market sits in a technology-transition phase as silica substitution displaces partial volumes in passenger tire treads while conductive and UV-stabilized specialty grades capture premium positioning in plastics and electronics applications.
For Market Incumbents: To counter silica substitution in low-rolling-resistance tire segments, deepen formulation support capabilities co-located with automotive OEM compound development labs and anchor long-term supply agreements through embedded technical service teams. Counter feedstock volatility by securing captive residual oil supply through refinery integration in Jubail and Ras Laffan industrial zones. For New Entrants and Emerging Players: Begin with plastics compounding for consumer goods in Nigeria and Kenya, where UV-stabilized masterbatch demand outpaces established supply and SABS certification requirements have not yet consolidated vendor lists. Target coatings formulators in Jebel Ali Free Zone seeking REACH-compliant distributors with pre-validated safety data sheets to avoid Gulf customs delays. For Investors and Strategic Acquirers: The window for entry favors technical service-focused multinationals with existing substance registration portfolios and backward-integrated Gulf producers with feedstock-adjacent furnace black capacity. Monitor silica substitution rates in passenger tire OEM specifications as the inflection indicator for long-term carbon black demand trajectory across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captures residual oil cost advantages from Saudi Aramco refinery streams that independent processors cannot replicate. |
| Long-term Supply Agreement with Automotive OEMs | Locks in multi-year offtake commitments with volume-tiered pricing structures that compress spot-market exposure. |
| Specialty Grade Portfolio Diversification | Targets conductive and UV-stabilized grades for Nigerian and Kenyan polymer converters adopting color consistency standards. |
| Technical Service Infrastructure Expansion | Embeds formulation support teams co-located with Jubail Industrial City compound development labs. |
| Greenfield Capacity in Ras Laffan Industrial Zone | Positions feedstock-adjacent furnace black production with Gulf export access and transparent cost-plus contracting. |
Research Methodology
Trade statistics from customs authorities, petrochemical industry association reports, and SEC filings from listed carbon black producers formed the secondary backbone of this analysis. Primary interviews with tire compound development executives, coatings formulators, polymer converter procurement leads, and SFDA regulatory affairs specialists provided demand-side validation. Bottom-up and top-down triangulation cross-checked volume estimates against refinery output data and downstream consumption patterns.
Bottom-up modeling built from grade-specific consumption rates by end-use industry, while top-down analysis anchored aggregate market size to petrochemical production indices and automotive OEM tire procurement disclosures. Segmentation dimensions included product type tier, application function, end-user industry maturity, and regional production hub concentration. CAGRs were derived from fitted growth curves applied to normalized baseline consumption, with feedstock cost volatility and silica substitution penetration treated as scenario variables across the projection horizon.
Underlying measurement precision varies by segment; furnace black volumes in tire manufacturing carry tighter precision than specialty grade estimates in coatings applications due to consolidated buyer disclosure. Forecasts reflect assumptions about SFDA enforcement intensity, DTIC local content rule implementation, and Red Sea shipping corridor stability. A model refresh is warranted upon material change in silica substitution rates or Gulf petrochemical integration investment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Carbamide Market