
 Cyclomethicone Market | 2026-2036
Cyclomethicone Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclomethicone Market Analysis
Buyer concentration in the personal care sector is rebalancing as multinational cosmetic houses consolidate supplier rosters while indie beauty brands fragment procurement across specialty distributors. Dow Inc. leverages backward integration into siloxane feedstocks to secure cost stability. Wacker Chemie AG anchors its position through pharmaceutical-grade purification capabilities that serve regulated dermal applications. Shin-Etsu Chemical Co., Ltd. dominates Asian supply chains with captive methyl chloride and silicon metal operations.
Cyclomethicone denotes volatile cyclic siloxanes—primarily D4, D5, and D6 oligomers—characterized by low surface tension, rapid evaporation rates below 250°C, and water-insoluble yet oil-compatible solubility profiles that enable transient skin feel without residue. These properties drive formulation utility across cosmetic emollients, industrial release coatings, and electronics-grade dielectric fluids. Cyclopentasiloxane leads product type demand due to its favorable volatility balance in antiperspirant and hair conditioning applications, while cyclohexasiloxane captures margin pools in longer-wear skin care where slower evaporation extends product residence. Spray formulations outpace creams and gels in growth velocity, reflecting consumer preference for dry-mist sun care and dry shampoo delivery systems that minimize tactile residue.
REACH D4 restriction proposals under ECHA evaluation and FDA oversight of cosmetic ingredient safety through the Voluntary Cosmetic Registration Program shape formulation migration toward D5 and D6 alternatives in European and North American markets. China's NMPA cosmetic ingredient filing requirements and GB standards for silicone content in personal care products create divergent compliance pathways that fragment global product portfolios. Stakeholders must monitor regulatory threshold adjustments for cyclic siloxane classifications while calibrating regional formulation strategies against divergent permissible exposure limits.
Market Dynamics
REACH D4 restriction proposals are forcing personal care formulators toward D5 and D6 alternatives, fragmenting global product portfolios as regional compliance pathways diverge. This regulatory pressure sits at the center of current market restructuring, reshaping R&D priorities and supplier relationships across cosmetic and industrial applications.
Growth Catalysts
- Lightweight formulation demand:Personal care brands are expanding cyclomethicone use in dry-mist sun care and dry shampoo delivery systems where rapid evaporation minimizes tactile residue.
- REACH regulatory migration:ECHA evaluation of D4 restrictions is accelerating reformulation investment toward compliant D5 and D6 alternatives in European cosmetic applications.
- China capacity expansion:Domestic silicone production growth and local cosmetic brand development are pulling volume eastward, concentrating demand in Shanghai and Guangdong manufacturing clusters.
Market Restraints
- Methyl chloride feedstock volatility:Silicon metal and methyl chloride price swings compress margins for non-integrated producers lacking captive chlorosilane supply.
- Asian supply concentration:Shin-Etsu's captive silicon metal operations and Dow's siloxane integration create oligopolistic conditions in high-purity grades.
- Natural oil substitution:Squalane and hemisqualane are displacing cyclomethicone in clean-label facial moisturizers targeting ingredient-conscious consumers.
Strategic Opportunities
- Pharmaceutical-grade purification:Wacker Chemie's dermal application capabilities demonstrate margin pools in regulated medical device coatings and transdermal delivery systems.
- Electronics dielectric fluids:Thermal management applications in data center immersion cooling represent underpenetrated volume outside traditional cosmetic markets.
- India PLI scheme alignment:Specialty chemical manufacturing incentives under India's production-linked incentive framework attract investment for regional supply base development.
Industry Challenges
- Cross-regional formulation complexity:China's NMPA filing requirements and GB standards demand separate product portfolios from EU REACH-compliant lines, multiplying SKU management overhead.
- Volatile organic compound testing capacity:Third-party analytical verification for D4/D5/D6 content classification faces bottlenecks as reformulation timelines compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclomethicone Market |
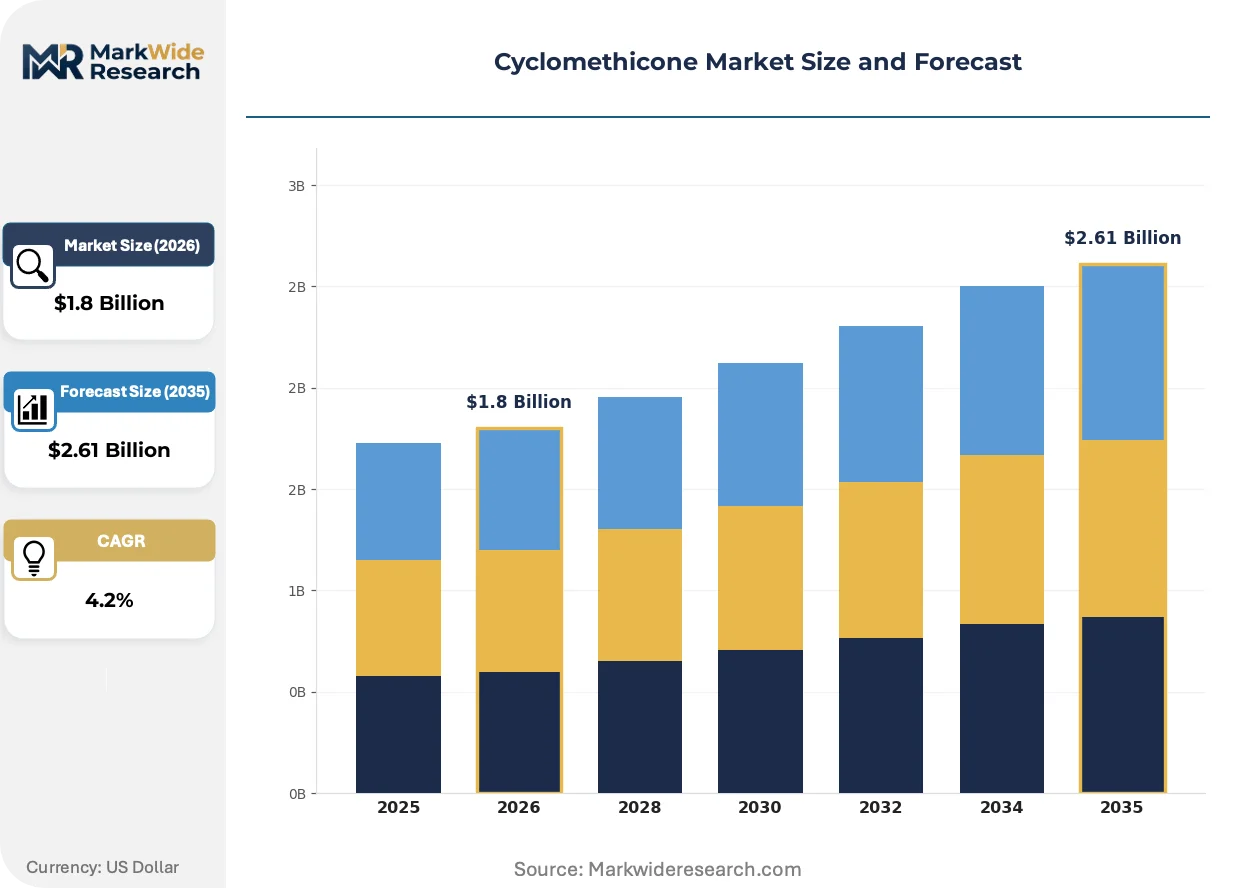
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclotetrasiloxane, Cyclopentasiloxane, Cyclohexasiloxane, Cycloheptasiloxane End User: Personal Care, Automotive, Electronics, Home Care Application: Silicone Coatings, Moisturizers, Hair Products, Emulsifiers Formulation: Sprays, Creams, Gels, Lotions |
| Companies Covered | Dow Inc., Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Evonik Industries AG, KCC Corporation, Elkem ASA, AkzoNobel N.V., Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclomethicone Market Emerging Trajectories
Continuous purification technology is automating quality consistency in cyclomethicone production, reducing batch-to-batch variation that previously required manual intervention. This automation wave is compressing the competitive gap between commodity and pharmaceutical-grade suppliers.
Membrane filtration and molecular distillation systems are automating the removal of linear siloxane contaminants from cyclic oligomer streams. Cosmetic contract manufacturers in Germany and the United States are adopting these systems to meet pharmaceutical-grade specifications without multi-year purification cycles. The technology is automating compliance with tightening purity thresholds while reducing solvent waste volumes.
ECHA's restriction proposal on D4 under REACH evaluation is forcing reformulation roadmaps toward D5 and D6 alternatives by 2026. Cosmetic houses with European manufacturing footprints are accelerating alternative qualification timelines to avoid supply disruption. Hair conditioning and antiperspirant segments face the steepest substitution curves given D4's historical dominance in volatility-balanced formulations.
Indie beauty brands are fragmenting procurement across specialty distributors rather than consolidating with multinational chemical suppliers. This pattern concentrates in North American and Western European markets where direct-to-consumer cosmetic launches proliferate. Specialty distributors capture margin by offering smaller minimum order quantities and technical formulation support that commodity suppliers decline.
Cyclomethicone Market Segmentation
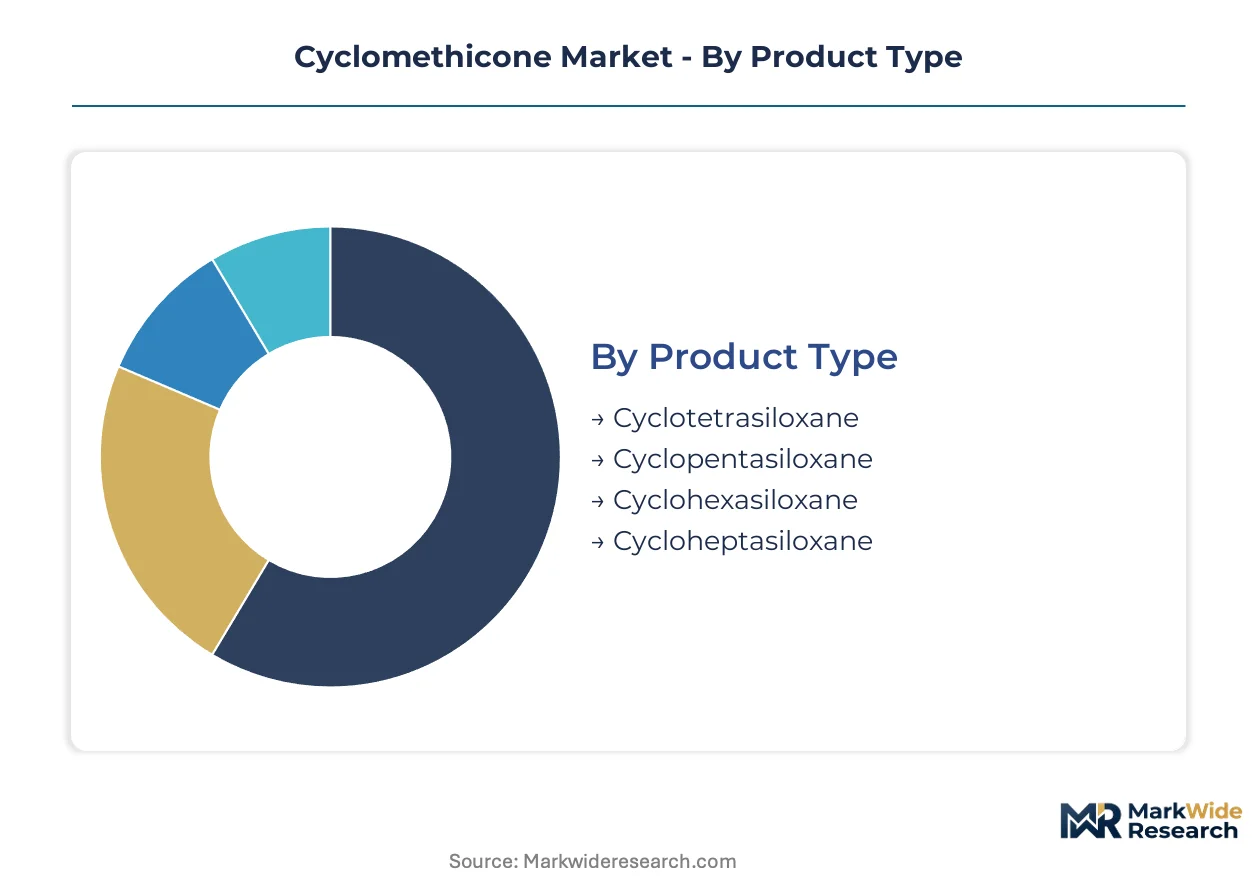
Cyclomethicone segmentation reveals distinct performance profiles across molecular weights and delivery formats. Formulators select oligomer grades based on evaporation kinetics, while end-use diversification spreads risk across cosmetic and industrial demand pools.
Product Type:
Integration depth varies sharply: cyclopentasiloxane dominates standalone cosmetic formulations, while cyclotetrasiloxane increasingly serves as embedded intermediates in silicone polymer synthesis.
- Cyclotetrasiloxane:The D4 oligomer exhibits the fastest evaporation profile among commercial grades, making it historically central to antiperspirant dry sprays. REACH restriction proposals in Europe are compressing its use in leave-on cosmetic applications, pushing volume toward industrial sealant and adhesive formulations where volatility accelerates cure rates.
- Cyclopentasiloxane:D5 strikes the volatility balance that cosmetic formulators prize for transient skin feel without residue accumulation. Demand concentrates in Shanghai and Guangdong manufacturing clusters serving domestic Chinese cosmetic brands, where NMPA filing requirements for silicone content create distinct compliance pathways from European standards.
- Cyclohexasiloxane:Slower evaporation extends product residence in longer-wear skin care applications. The D6 grade captures reformulation volume migrating from restricted D4 lines in EU markets.
- Cycloheptasiloxane:Specialty grade serving niche pharmaceutical and medical device coating applications requiring extended surface residence.
Cyclopentasiloxane leads volumes today; cyclohexasiloxane is gaining share fastest.
End User:
Cost tier stratification separates premium cosmetic procurement from commodity industrial purchasing, with pharmaceutical-grade purification commanding multiples over technical grades.
- Personal Care:Antiperspirants, hair conditioners, and facial moisturizers represent the core demand anchor. ECHA's D4 evaluation is fragmenting European product portfolios toward D5 and D6 alternatives, while Chinese domestic brand growth pulls volume toward local manufacturing.
- Automotive:Interior trim coatings and gasket sealants exploit cyclomethicone's thermal stability and release properties. Demand tracks vehicle production cycles with lower formulation switching frequency than cosmetics.
- Electronics:Dielectric fluids for thermal management in data center immersion cooling represent underpenetrated volume outside traditional markets.
- Home Care:Furniture polish and surface treatment applications favor faster-evaporating grades for streak-free finishes.
Personal care commands the premium tier; electronics is climbing the fastest as thermal management applications proliferate.
Application:
Customer type divergence separates mass-market cosmetic houses from specialty pharmaceutical contractors, with procurement scale and technical support requirements driving supplier selection.
- Silicone Coatings:Industrial release coatings for bakeware and manufacturing equipment exploit low surface tension and thermal stability. Automotive and electronics manufacturing clusters in Germany and Japan anchor technical-grade demand.
- Moisturizers:Facial and body care formulations leverage rapid evaporation for dry-touch aesthetics. Clean-label substitution pressure from squalane and hemisqualane is displacing cyclomethicone in premium natural-positioned lines.
- Hair Products:Serums and conditioning treatments balance spreadability with non-greasy finish. Dry-mist delivery systems are expanding faster than traditional cream formats.
- Emulsifiers:Silicone-in-water and water-in-silicone systems for sophisticated cosmetic textures. Pharmaceutical-grade specifications for transdermal delivery systems command margin premiums.
Moisturizers anchor current revenue; silicone coatings for electronics thermal management show the steepest expansion trajectory.
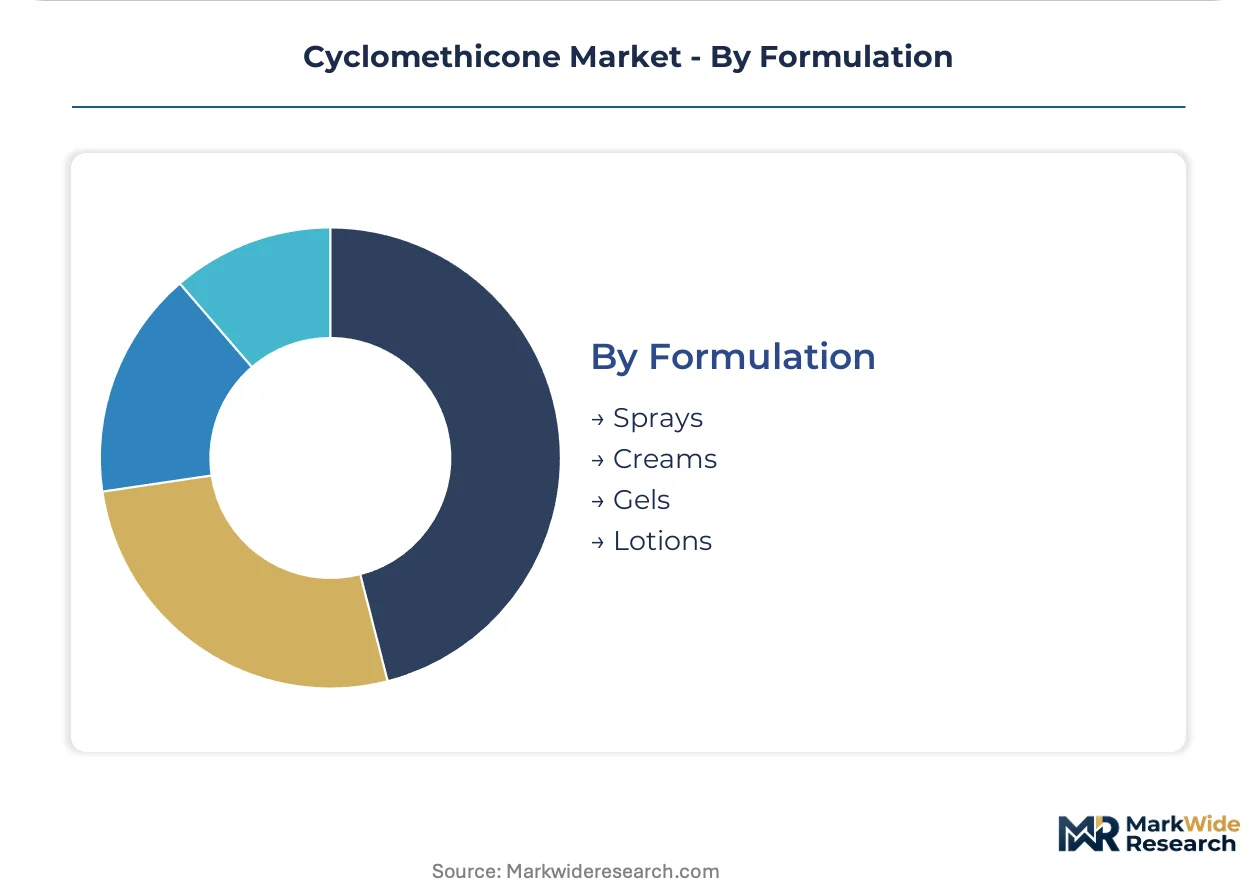
Formulation:
Supply concentration in spray propellant systems and packaging equipment creates barriers for new entrants in dry-mist formats.
- Sprays:Dry-mist sun care and dry shampoo delivery systems are expanding most quickly, reflecting consumer preference for residue-minimizing application. Propellant compatibility and VOC testing capacity constrain supplier options.
- Creams:Traditional emulsion vehicles for facial and body moisturizers. Slower growth reflects consumer migration toward lighter textures.
- Gels:Clear formulations for men's grooming and targeted treatment products. Silicone gel networks provide distinctive skin feel.
- Lotions:Pump-dispersed fluid emulsions balancing spreadability with absorption speed. Mass-market volume anchor with stable but slower growth.
Sprays dominate growth velocity; lotions retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic silicone production capacity pulls volume eastward while Germany's pharmaceutical-grade purification capabilities anchor European supply for regulated dermal applications. These two markets illustrate how regional specialization fragments global cyclomethicone procurement.
China
Domestic cosmetic brand growth and captive methyl chloride operations concentrate demand in Shanghai and Guangdong manufacturing clusters. NMPA filing requirements for silicone content create compliance pathways distinct from European standards. Local producers expand capacity to serve indie beauty brands fragmenting procurement across specialty distributors.
Germany
Pharmaceutical-grade purification capabilities serve regulated medical device coatings and transdermal delivery systems. ECHA's REACH D4 restriction proposals accelerate reformulation timelines toward D5 and D6 alternatives. Cosmetic contract manufacturers in Germany adopt membrane filtration systems to meet tightening purity thresholds without multi-year cycles.
United States
FDA oversight through the Voluntary Cosmetic Registration Program shapes formulation migration toward compliant alternatives in North American markets. Spray formulation demand for dry-mist sun care and dry shampoo delivery systems outpaces traditional cream formats. Third-party analytical verification capacity faces bottlenecks as reformulation timelines compress.
Japan
Electronics-grade dielectric fluids for thermal management in data center immersion cooling represent underpenetrated volume outside traditional cosmetic markets. METI standards and JIS specifications govern silicone content in industrial applications. Captive silicon metal operations in Chubu and Kansai regions support high-purity grade production.
India
Specialty chemical manufacturing incentives under the PLI scheme attract investment for regional supply base development. BIS standards for silicone content in personal care products create divergent compliance pathways from EU and North American requirements. Maharashtra and Gujarat industrial corridors concentrate formulation and packaging operations for domestic cosmetic brands.
Cyclomethicone Market Vendor Landscape
Asian producers anchor the scale-driven tier; European specialists hold the pharmaceutical-grade premium segment. The vendor base splits between consolidated multinational chemical houses with backward integration into siloxane feedstocks and fragmented specialty distributors serving indie beauty brands. Three archetypes dominate: integrated feedstock owners, purification specialists, and regional distribution intermediaries. Competitive moves center on capacity expansion in China and technology licensing for continuous purification systems.
Within the integrated feedstock tier, Dow Inc. and Shin-Etsu Chemical Co., Ltd. occupy positions defined by captive supply chain control. Wacker Chemie AG exemplifies the purification specialist archetype serving regulated applications. These three anchors demonstrate how geographic origin and corporate structure map to strategic positioning without requiring identical competitive moves.
| Leading Market Players |
|---|
| Dow Inc. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Evonik Industries AG |
| KCC Corporation |
| Elkem ASA |
| AkzoNobel N.V. |
| Solvay SA |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade purification capabilities command substantial premiums over technical-grade cyclomethicone, with this certification ladder determining both contract structures and supplier selection criteria across cosmetic and industrial procurement. ECHA's REACH D4 restriction timeline and China's NMPA filing requirements fragment pricing power by geography, forcing buyers to maintain separate inventory pools for compliant formulations.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade cyclopentasiloxane as domestic methyl chloride integration improves. Contract-based long-term offtake dominates procurement for multinational cosmetic houses, while spot purchasing serves indie beauty brands through specialty distributors. Price differentiation hinges on certification grade—pharmaceutical specifications versus technical—and volume scale, with largest buyers extracting freight and handling concessions. Cost compression in standard grades is intensifying because Shin-Etsu's captive silicon metal operations and Dow's siloxane integration create oligopolistic supply conditions. Indie beauty brands exhibit highest price sensitivity due to fragmented order sizes, while pharmaceutical contractors accept premiums for dermal-grade purity.
Supply Chain Analysis
Freight cost volatility from Shanghai and Guangdong manufacturing clusters to European and North American formulation sites erodes margins for non-integrated distributors. Supply concentrates in China, Germany, and Japan, with domestic silicone production growth in China pulling volume eastward. Raw material dependencies center on silicon metal, methyl chloride, and chlorosilane intermediates. Single-source vulnerability from Shin-Etsu's captive operations in Chubu and Kansai regions creates concentration risk for high-purity electronics grades. Distribution runs through specialty chemical distributors serving indie brands and direct contracts with multinational cosmetic houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclomethicone demand functions as a regulatory compounder, with ECHA's REACH D4 restriction proposals forcing accelerated reformulation investment across European cosmetic applications.
For Market Incumbents: Lock in backward integration into siloxane feedstocks to secure margin stability against methyl chloride price swings. Prioritize pharmaceutical-grade certification investment to capture premium pools in transdermal delivery systems and medical device coatings, defending against Wacker Chemie's established purification capabilities. Capacity expansion in China's Guangdong cluster captures volume from domestic cosmetic brand growth. For New Entrants and Emerging Players: Direct-to-specialty-distributor channels offer the most penetrable route for regional supply base development, particularly serving North American indie beauty brands fragmenting procurement away from multinational chemical houses. Target electronics-grade dielectric fluids for data center thermal management as the fastest-climbing application outside saturated cosmetic markets. Technical formulation support and smaller minimum order quantities differentiate against commodity suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where purification technology gaps separate pharmaceutical-grade specialists from commodity producers. Five-to-ten-year viability favors acquisition targets with continuous purification systems automating quality consistency without multi-year cycles. Membrane filtration and molecular distillation capabilities signal investable technical moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Dow's captive supply model demonstrates cost stability against methyl chloride volatility. |
| Pharmaceutical-Grade Purification Investment | Wacker Chemie's dermal capabilities command margin multiples in regulated medical applications. |
| Continuous Purification Technology Licensing | Automation of quality consistency compresses competitive gaps between grade tiers. |
| Regional Capacity Expansion in China | Shanghai and Guangdong clusters capture demand from domestic cosmetic brand proliferation. |
| Electronics Dielectric Fluid Qualification | Data center immersion cooling represents underpenetrated volume outside traditional cosmetic markets. |
Methodological Framework
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each regional cluster. Primary interviews with silicone plant managers, cosmetic procurement leads at multinational houses, specialty distribution channel partners, and pharmaceutical R&D directors combined with secondary validation from customs and trade data, SEC 10-K filings, ECHA regulatory submissions, and NMPA filing records. Bottom-up production capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition across molecular weight grades, end-use industries, formulation formats, and regional regulatory clusters structures the analytical framework. CAGRs derive from segment-level growth rate blending weighted by current volume shares. Forecast inputs incorporate REACH D4 restriction implementation timelines, China domestic capacity expansion curves, and substitution elasticity from squalane and hemisqualane in clean-label facial moisturizers.
Regulatory threshold adjustments, feedstock price volatility, and clean-label substitution acceleration are the dominant revision risks to modeled demand. Forecasts reflect assumptions about compliance timeline adherence and reformulation cost pass-through rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Explosives and Pyrotechnics Market