
 Global Photoacid Generators Market | 2026-2036
Global Photoacid Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photoacid Generators Market Intelligence
Buyer concentration among leading foundries and memory manufacturers is recalibrating procurement leverage across the supply base. Shin-Etsu Chemical sustains its position through captive silane chemistry and backward integration into organosilicon feedstocks. Tokyo Ohka Kogyo dominates photoresist-formulation partnerships with Asian foundries. Merck KGaA leverages its European regulatory expertise to navigate REACH compliance for halogenated PAG chemistries.
Photoacid generators are ionic or non-ionic compounds that produce strong acids upon exposure to ultraviolet or electron-beam radiation, typically containing sulfonium, iodonium, or diazomethane moieties with hexafluoroantimonate or hexafluorophosphate counterions, and they function as latent catalysts that enable selective deprotection of polymer resists in nanoscale lithography. Onium salt formulations, particularly sulfonium and iodonium variants, anchor current revenue pools due to their established performance at 193 nm and 248 nm wavelengths. Extreme UV technology represents the fastest-expanding segment as foundries transition below 7 nm nodes, though deep UV maintains volume leadership across mature node production. Electron beam PAGs occupy a specialized niche in photomask fabrication where direct-write precision outweighs throughput constraints.
REACH registration requirements in Europe, EPA toxic substance controls in the United States, and Japan's Chemical Substances Control Law collectively restrict perfluorinated acid generators and drive substitution toward non-ionic alternatives. Korea's Ministry of Environment and Taiwan's EPA are tightening volatile organic compound limits in cleanroom chemistries, compelling reformulation of standard PAG products. Stakeholders must monitor regulatory divergence across these jurisdictions while calibrating R&D portfolios between established onium chemistries and emerging non-sulfonated architectures.
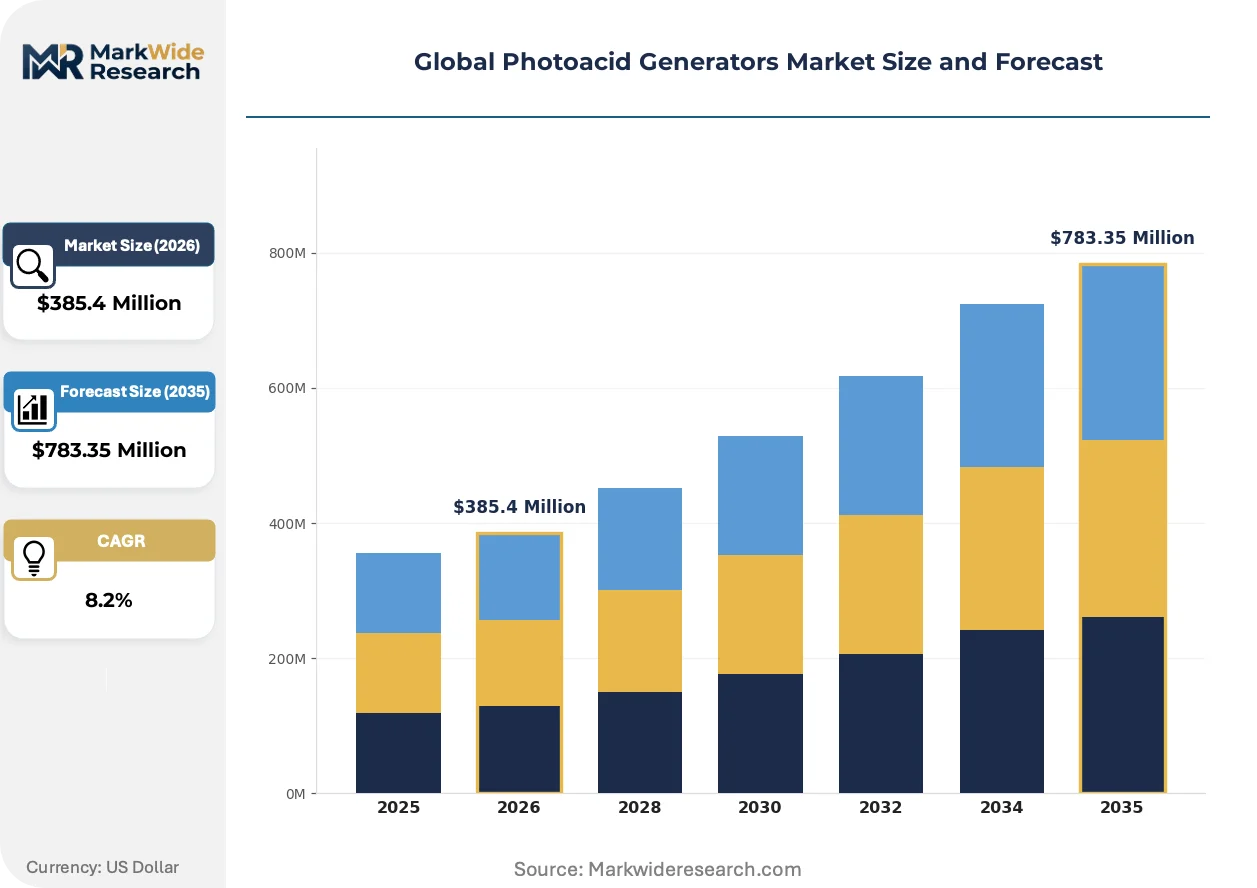
Market Dynamics
Extreme ultraviolet lithography is compressing node geometries below 7 nanometers across Taiwan and South Korea, forcing PAG suppliers to reformulate acid generators for shorter wavelengths and tighter spectral sensitivity windows.
Growth Catalysts
- Advanced node expansion:Foundries in Hsinchu and Pyeongtaek are commissioning EUV-capable fabs, creating immediate demand for high-purity sulfonium salts calibrated to 13.5 nm exposure systems.
- REACH compliance substitution:ECHA restrictions on perfluorinated compounds are accelerating qualification of non-ionic PAG architectures across German and French resist formulators.
- Photomask direct-write:Electron-beam lithography for multi-patterning masks requires specialized diazomethane PAGs with precise acid diffusion control.
Market Restraints
- Organosilicon feedstock concentration:Captive silane production in Japan limits independent PAG manufacturers' access to critical sulfonium precursors.
- PFAS regulatory friction:EPA toxic substance controls and state-level prohibitions in Minnesota and Maine are forcing reformulation of hexafluoroantimonate counterion chemistries.
- Technical limitation at sub-3 nm:Acid blur from conventional onium salts exceeds critical dimension tolerance budgets, constraining resolution scaling.
Strategic Opportunities
- Indian semiconductor manufacturing:Dholera and Gujarat fab clusters under the PLI scheme will require localized PAG supply chains absent domestic production.
- Non-sulfonated architectures:Imide-based and oxime sulfonate PAGs bypass perfluorinated acid concerns while maintaining quantum yield performance.
- EU Green Deal alignment:CSRD reporting requirements favor PAG suppliers with verified carbon footprints in their organofluorine synthesis pathways.
Industry Challenges
- Cleanroom chemistry talent:Formulation chemists with expertise in acid diffusion modeling and polymer compatibility are concentrated in Japan and Korea.
- EUV infrastructure capex:Qualification of PAGs for ASML exposure systems requires multi-million dollar metrology investments beyond mid-tier suppliers.
- Dual-use export controls:US Bureau of Industry and Security restrictions on advanced lithography materials complicate cross-border formulation transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photoacid Generators Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $783.35 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onium Salt, Non-Onym Salt, Sulfonium Salt, Iodonium Salt, Others Technology: Deep UV, i-Line, Electron Beam, Extreme UV, Laser Lithography Application: Semiconductor, Flat Panel Display, Micro-Optics, Printing Circuit Board, Optical Storage End User: Wafer Fabricators, Foundries, Packaging Companies, Fabless Companies |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Sumitomo Chemical Co., Ltd., Tokyo Ohka Kogyo Co., Ltd., The Dow Chemical Company, Toyo Gosei Co., Ltd., Heraeus Holding, FUJIFILM Corporation, Merck KGaA, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photoacid Generators Market Strategic Shifts & Innovations
EUV wavelength migration is compressing development cycles for photoacid generators while regulatory fragmentation across jurisdictions forces parallel qualification tracks for the same chemistries.
Multicomponent PAG systems is unifying acid amplification control with line-edge roughness reduction in chemically amplified resists. Memory manufacturers in Icheon are adopting these formulations for 3D NAND stack patterning. This convergence is unifying previously separate specification requirements from logic and memory foundries into single product platforms.
Japan's Chemical Substances Control Law amendments are tightening notification thresholds for fluorinated PAG intermediates. Formulators must now submit full toxicity dossiers for sulfonium salts previously exempt under polymer exemptions. Korean resist manufacturers are responding by accelerating non-fluorinated counterion development with domestic PAG suppliers.
Direct long-term supply agreements are displacing spot purchasing among leading foundries. TSMC and Samsung have consolidated their PAG procurement through three-year qualification contracts with volume guarantees. Taiwan's EPA volatile organic compound enforcement is reinforcing this concentration by raising compliance costs for secondary suppliers.
Global Photoacid Generators Market Segmentation
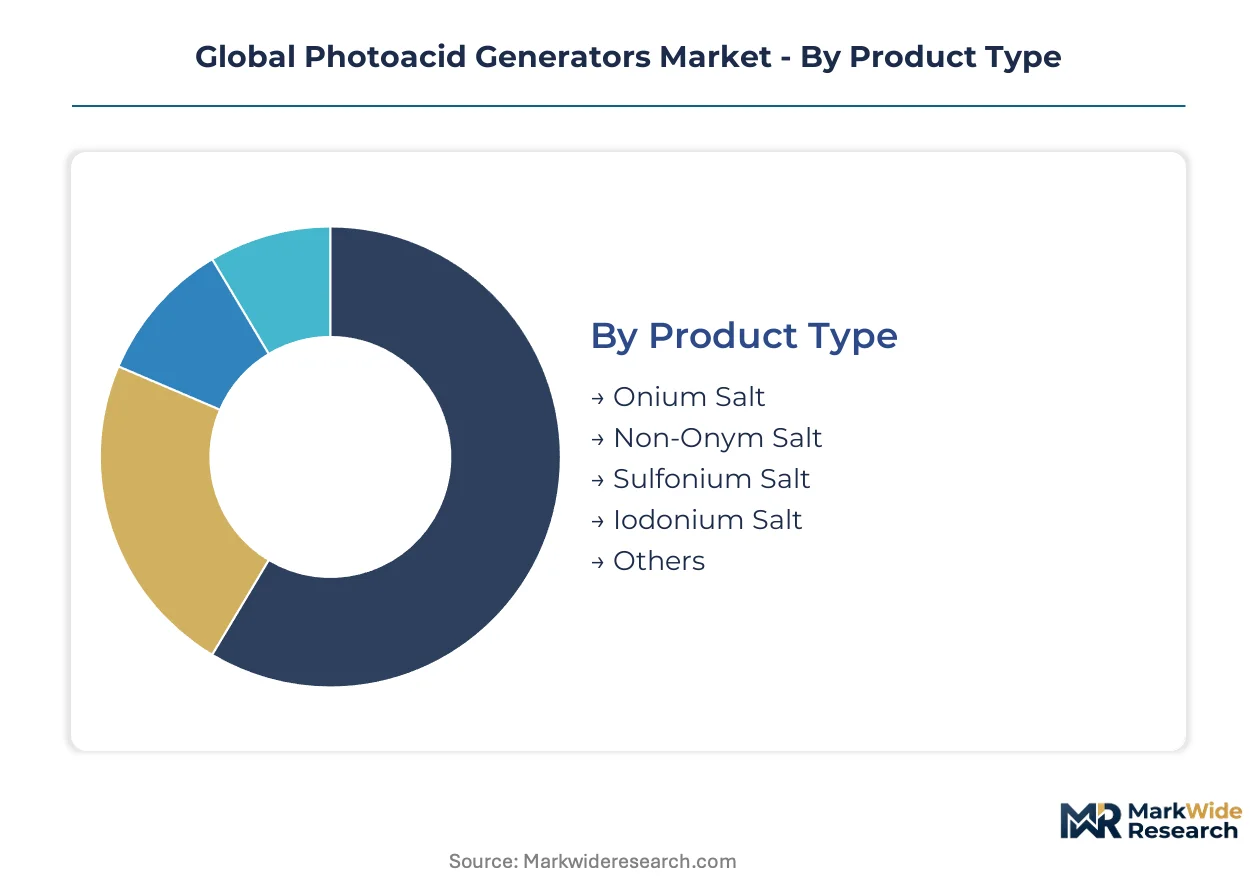
Segmentation in photoacid generators reveals how formulation chemistry, exposure wavelength, and fabrication node complexity create distinct procurement specifications across semiconductor supply chains. Each dimension carries different margin profiles, qualification barriers, and regulatory exposure that reshape supplier positioning.
Product Type:
Customization intensity spans from commodity counterion exchanges to proprietary molecular architectures requiring dedicated synthesis pathways.
- Onium Salt:Sulfonium and iodonium cations paired with hexafluoroantimonate or hexafluorophosphate anions dominate 193 nm and 248 nm lithography. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify these for high-volume logic production at mature nodes.
- Non-Onium Salt:Imide-based and oxime sulfonate architectures bypass perfluorinated acid concerns while maintaining quantum yield. German and French resist formulators are accelerating qualification under ECHA restrictions on PFAS compounds.
- Sulfonium Salt:Triarylsulfonium derivatives anchor EUV resist platforms with optimized acid diffusion lengths for sub-7 nm patterning.
- Iodonium Salt:Diaryliodonium formulations offer alternative acid strength profiles for specialized polymer deprotection kinetics.
- Others:Diazomethane and non-ionic latent acid generators serve photomask direct-write and niche metrology applications.
Leading the category by volume: Onium Salt. Growing fastest: Non-Onium Salt.
Technology:
Capital equipment lock-in at foundries creates technology-specific PAG procurement channels with decade-long qualification cycles.
- Extreme UV:13.5 nm wavelength exposure demands sulfonium salts with sub-nanometer acid blur and precise spectral sensitivity windows. ASML's NXE platform deployment across Hsinchu and Pyeongtaek fabs is compressing development cycles for qualified chemistries.
- Deep UV:248 nm and 193 nm systems maintain volume leadership across mature node production where capital depreciation favors extended tool utilization. Korean memory manufacturers in Icheon consume these formulations for 3D NAND stack patterning.
- i-Line:365 nm mercury line exposure persists in power semiconductor and analog device fabrication.
- Electron Beam:Direct-write systems require diazomethane PAGs with precise acid diffusion control for photomask fabrication.
- Laser Lithography:Maskless and stepper-based laser systems occupy specialized prototyping and research applications.
Highest procurement concentration: Deep UV. Steepest expansion trajectory: Extreme UV.
Application:
Pattern density requirements and substrate material properties fragment PAG specifications across downstream manufacturing steps.
- Semiconductor:Logic and memory fabrication at sub-7 nm nodes requires EUV-calibrated sulfonium salts with line-edge roughness below 2 nm. Taiwan and South Korea foundries specify multi-component PAG systems for chemically amplified resists.
- Flat Panel Display:Large-area photolithography for OLED and LCD backplanes uses modified i-line and deep UV formulations with adjusted viscosity for spin-coating uniformity.
- Micro-Optics:Diffractive optical element fabrication demands precise sidewall angle control through acid diffusion management.
- Printed Circuit Board:Dry film and liquid photoresist applications for PCB patterning use cost-optimized onium salt grades.
- Optical Storage:Mastering and replication processes for Blu-ray and archival media require specialized sensitivity profiles.
Dominant revenue share: Semiconductor. Gaining share fastest: Flat Panel Display.
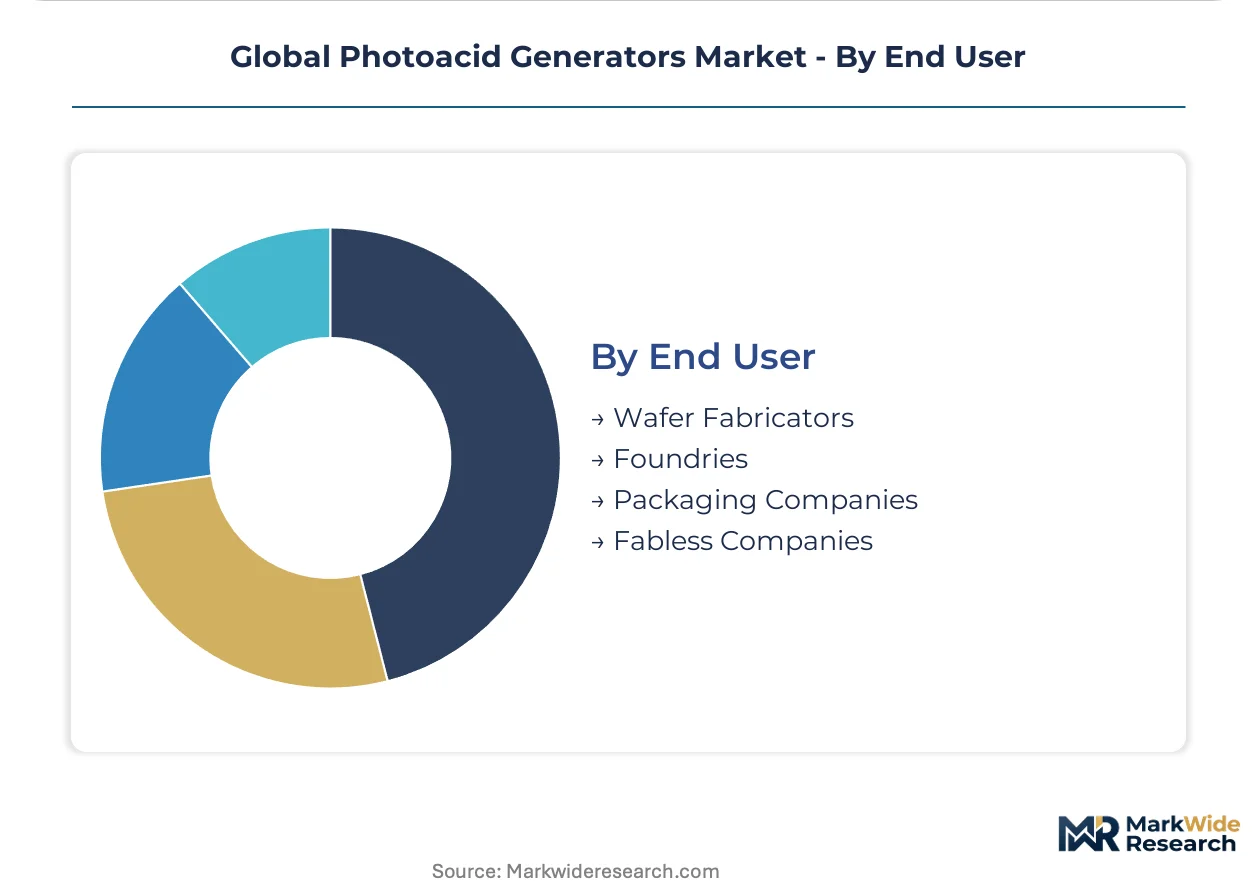
End User:
Procurement scale and technical integration depth separate captive formulation development from merchant PAG purchasing.
- Wafer Fabricators:Integrated device manufacturers with in-house resist formulation capabilities, such as Intel and Texas Instruments, specify PAG purity grades and counterion compositions directly.
- Foundries:Pure-play manufacturers including TSMC, Samsung Foundry, and GlobalFoundries consolidate procurement through three-year qualification contracts with volume guarantees.
- Packaging Companies:Advanced packaging lithography for fan-out wafer-level packaging uses reformulated PAGs adapted from front-end specifications.
- Fabless Companies:Design houses without fabrication assets rely on foundry-specified PAG chemistries through indirect supply chain relationships.
Controlling procurement volume: Foundries. Expanding specification influence: Packaging Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organosilicon feedstock production in Japan and advanced lithography clusters in Taiwan and South Korea anchor the geographic distribution of photoacid generator demand. Manufacturing concentration follows semiconductor foundry placement, with regulatory divergence across jurisdictions reshaping local formulation requirements.
Taiwan
Hsinchu Science Park hosts TSMC's EUV-capable fabs driving sulfonium salt procurement for sub-7 nm nodes. Taiwan's EPA volatile organic compound enforcement is raising compliance costs for secondary PAG suppliers. The Southern Taiwan Science Park expansion in Tainan is absorbing multi-component PAG systems for 3D NAND stack patterning.
South Korea
Samsung Foundry and SK Hynix in Pyeongtaek and Icheon anchor deep UV and EUV PAG consumption for memory and logic production. Korea's Ministry of Environment is tightening VOC limits in cleanroom chemistries, compelling reformulation of standard products. The Yongin semiconductor cluster is emerging as a qualification hub for non-fluorinated counterion alternatives.
Japan
Shin-Etsu Chemical's captive silane production in Niigata and Tokyo Ohka Kogyo's photoresist partnerships concentrate supply-side leverage. Japan's Chemical Substances Control Law amendments are tightening notification thresholds for fluorinated PAG intermediates. The Kumamoto and Hiroshima fab corridors are sustaining mature node demand for 193 nm and 248 nm formulations.
United States
Intel's integrated device manufacturing in Arizona and Oregon specifies PAG purity grades directly for in-house resist formulation. EPA toxic substance controls and state-level PFAS prohibitions in Minnesota and Maine are forcing hexafluoroantimonate counterion substitutions. The Albany Nanotech Complex in New York is serving as a pilot line for EUV PAG qualification with ASML exposure systems.
Germany
Merck KGaA leverages European regulatory expertise to navigate REACH compliance for halogenated PAG chemistries across German resist formulators. ECHA restrictions on perfluorinated compounds are accelerating qualification of non-ionic PAG architectures. The Dresden semiconductor cluster, anchored by GlobalFoundries, is consolidating procurement through multi-year qualification contracts.
Global Photoacid Generators Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue non-sulfonated architectures and regional supply localization. The market exhibits consolidated supply-side concentration among Japanese and European incumbents with captive feedstock positions. Three archetypes dominate: integrated chemical conglomerates with backward organosilicon control, specialized photoresist formulators with foundry-locked partnerships, and diversified materials suppliers leveraging regulatory navigation expertise. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with qualification contracts extending to three-year terms.
Within the integrated chemical tier, Shin-Etsu Chemical Co., Ltd. exemplifies backward integration into organosilicon feedstocks, while Tokyo Ohka Kogyo Co., Ltd. occupies a position anchored in photoresist-formulation partnerships with Asian foundries. Merck KGaA represents the regulatory-navigation archetype, leveraging European REACH expertise to service halogenated chemistry demand. These three entities collectively illustrate how feedstock control, customer integration, and compliance capability define sustainable positioning.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Tokyo Ohka Kogyo Co., Ltd. |
| The Dow Chemical Company |
| Toyo Gosei Co., Ltd. |
| Heraeus Holding |
| FUJIFILM Corporation |
| Merck KGaA |
| JSR Corporation |
| Others |
Cost & Logistics Intelligence
Foundry procurement consolidation through three-year qualification contracts anchors pricing power among suppliers with ASML exposure system certifications. Contract structures favor volume-guaranteed offtake over spot purchasing, compressing margins for secondary suppliers lacking metrology infrastructure.
Pricing Analysis
Volume-mature deep UV formulations trade at compressed margins while EUV-calibrated sulfonium salts command premium positioning. Pricing stratifies across EUV-grade, DUV-production, and legacy-node tiers, with differentiation driven by purity certification and acid diffusion precision. Cost compression in legacy onium salts intensifies as Korean memory manufacturers consolidate procurement. Merchant PAG suppliers exhibit highest price sensitivity; captive formulators at integrated device manufacturers absorb cost fluctuations through in-house synthesis.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are reshaping sourcing patterns for Dholera and Gujarat fab clusters. Organosilicon feedstock concentrates in Japan, with sulfonium precursors drawing from Niigata-based silane production. Hexafluoroantimonate counterions rest on fluorochemical supply chains concentrated in Germany and China. Single-source vulnerability pervades sulfonium salt intermediates. Distribution runs through resist formulator partnerships rather than direct foundry sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around qualification-capable suppliers as EUV infrastructure capex barriers eliminate mid-tier competitors. REACH compliance substitution and PFAS regulatory friction accelerate exits among non-compliant producers.
For Market Incumbents: Extend qualification contract durations to lock out emerging entrants before Indian fab clusters commission. Deepen backward integration into organosilicon feedstocks to neutralize Shin-Etsu's captive supply advantage. Defend against non-sulfonated architecture substitutes by accelerating imide-based PAG co-development with Tokyo Ohka Kogyo. For New Entrants and Emerging Players: The premium-to-economy pricing gap in legacy DUV formulations offers white-space entry below EUV qualification barriers. Target packaging lithography applications where fan-out wafer-level patterning specifications remain less stringent. Pursue joint development agreements with Indian resist formulators under PLI localization mandates. For Investors and Strategic Acquirers: The window for entry favors regulatory-navigation specialists with REACH dossier capabilities. Long-term viability hinges on carbon footprint verification for EU Green Deal alignment. Watch ECHA PFAS restriction timelines as inflection signals for non-ionic PAG valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Feedstocks | Shin-Etsu's Niigata silane production eliminates sulfonium precursor supply risk for qualified suppliers. |
| Long-term Supply Agreement with Foundry Partners | TSMC and Samsung three-year contracts lock volume guarantees and raise barriers for secondary entrants. |
| Green Manufacturing Transition | CSRD reporting requirements favor suppliers with verified carbon footprints in fluorinated synthesis pathways. |
| Joint Venture for Indian Localization | Dholera fab clusters under PLI scheme require domestic PAG supply chains absent current production. |
| Capacity Expansion for EUV-grade Sulfonium Salts | ASML NXE platform deployment across Hsinchu and Pyeongtaek compresses qualified chemistry development cycles. |
Research Approach
Document review covered SEC 10-K filings, ECHA REACH registration databases, and customs trade data, complemented by interviews with resist formulation directors, foundry procurement managers, and organosilicon plant engineers. Secondary validation drew from semiconductor equipment capex disclosures, EPA toxic substance control filings, and Japan Chemical Substances Control Law amendments. Bottom-up volume modeling triangulated against top-down foundry capacity expansion announcements.
Historical shipment patterns cross-referenced against expert panel input on EUV migration timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry architecture, exposure wavelength technology, fabrication node complexity, and regional regulatory cluster. CAGRs derived from supply-demand balance projections incorporating ASML tool installation schedules and resist formulator qualification pipelines.
Underlying measurement precision varies by segment; EUV-grade sulfonium salts carry tighter precision than legacy i-line formulations due to concentrated foundry disclosure. Forecasts reflect assumptions on node migration speed and REACH restriction implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Biocides for Leather Market