
 Calcium D-Pantothenate Market | 2026-2036
Calcium D-Pantothenate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium D-Pantothenate Market Outlook
Chinese bulk pharmaceutical chemical production is hardening its grip on calcium D-pantothenate feedstock supply. Zhenjiang Gaopeng Pharmaceutical leverages captive fermentation capacity to dominate powder-grade output for nutraceutical buyers. DSM anchors European demand through backward integration into pharmaceutical-grade pantothenate, while BASF competes on cosmetic-grade formulations with specialized liquid concentrates for skin-care manufacturers.
Calcium D-pantothenate, the calcium salt of vitamin B5, typically assays at 98-102% purity with a specific rotation of +24.0° to +28.5° and serves primarily as an essential cofactor precursor in coenzyme A synthesis for metabolic function across human and animal nutrition. The powder segment sustains the largest volume base through direct compression into tablet and capsule formulations, while liquid concentrates are displacing solid forms in cosmetic emulsions where solubility drives formulation efficiency. Pharmaceutical-grade specifications command premium positioning due to USP and EP certification requirements that granule and tablet formats must meet for finished-dose compliance.
FDA dietary supplement cGMP rules, China's SAMR food additive GB standards, and the EU's EFSA novel food evaluations collectively constrain market access to certified producers meeting purity and traceability thresholds. These frameworks elevate compliance costs for non-integrated manufacturers while rewarding firms with in-house analytical and quality systems. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs, as divergence in assay methods and impurity profiles threatens to fragment specification requirements across export destinations.
Market Dynamics
Chinese fermentation capacity concentration now dictates calcium D-pantothenate availability and pricing benchmarks for downstream nutraceutical, pharmaceutical, and cosmetic formulators worldwide.
Growth Catalysts
- Preventive health prioritization:Consumers across East Asia and North America are expanding daily supplement regimens with B-complex formulations containing calcium D-pantothenate as a coenzyme A precursor for metabolic support.
- GB standards harmonization:China's SAMR food additive purity benchmarks are elevating export-grade specifications, enabling certified producers to access premium pharmaceutical and nutraceutical channels in regulated markets.
- Cosmetic emulsion demand:Skin-care manufacturers in South Korea and Germany are accelerating liquid concentrate adoption for enhanced solubility in topical formulations.
Market Restraints
- Fermentation feedstock volatility:Corn-derived dextrose and nitrogen source costs fluctuate with agricultural commodity cycles, compressing margins for non-integrated pantothenate producers.
- Zhenjiang cluster concentration:Overreliance on single-region Chinese bulk pharmaceutical chemical output creates supply vulnerability from environmental compliance shutdowns or logistics disruptions.
- Pharmacopeial divergence:Misalignment between USP, EP, and ChP monograph assay methods forces manufacturers to maintain parallel analytical protocols, raising quality system overhead.
Strategic Opportunities
- Indian nutraceutical manufacturing:CDSCO and FSSAI regulatory maturation is attracting contract manufacturers seeking alternative B-vitamin sourcing outside Chinese supply chains.
- EFSA novel food pathways:Synthetic biology-derived pantothenate production methods may qualify for streamlined safety evaluations, opening differentiated positioning for fermentation innovators.
- Direct-to-practitioner channels:Functional medicine clinicians in the United States are prescribing therapeutic-dose B5 protocols, bypassing traditional retail supplement distribution.
Industry Challenges
- Analytical chemistry talent scarcity:USP and EP certification requirements demand specialized chromatography and spectroscopy expertise that contract laboratories struggle to staff.
- Multi-pharmacopeial compliance timelines:Parallel validation studies for ChP, USP, and EP release specifications extend product registration cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium D-Pantothenate Market |
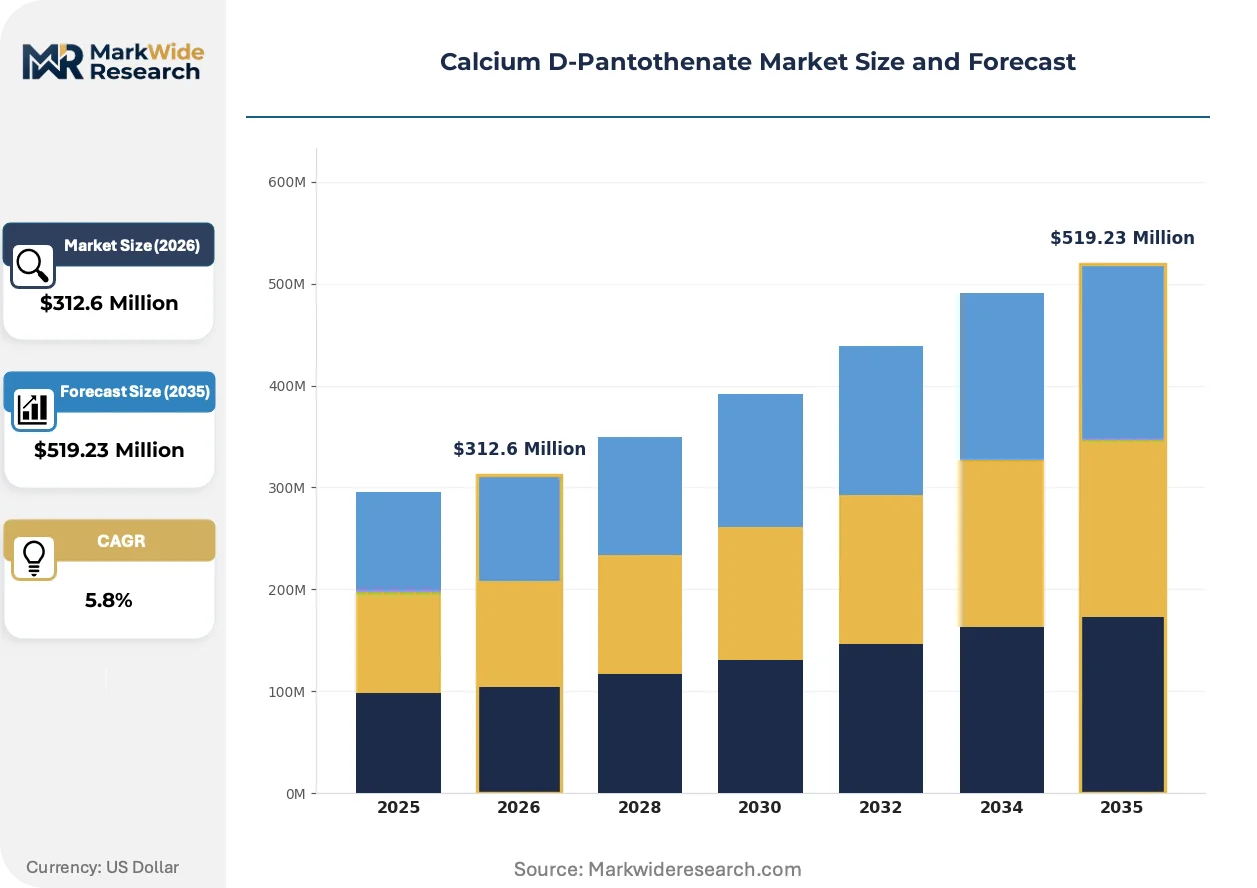
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Liquid, Tablet Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Food Additives End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Dietary Supplements Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Zhenjiang Gaopeng Pharmaceutical Co. Ltd., Yifan Pharmaceutical, Shandong Hwatson Biochem, Shandong Xinfa Pharmaceutical, DSM, BASF, Shandong Xinhua Pharmaceutical Co. Ltd., Anhui Huaheng Biotechnology Co., Ltd., DKS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium D-Pantothenate Market Strategic Shifts
Continuous fermentation monitoring and real-time release testing are compressing batch cycle times while pharmacopeial harmonization efforts attempt to unify quality specifications across export destinations.
Continuous bioprocessing technology is integrating PAT (Process Analytical Technology) sensors for real-time titer measurement during calcium D-pantothenate fermentation. Large-scale Chinese manufacturers are adopting these systems to reduce offline testing delays. This integration is enabling same-day release decisions that compress working capital cycles and reduce quarantine inventory.
REACH registration requirements for vitamin B5 intermediates are tightening substance volume tracking and safety data documentation obligations for EU importers. The European Chemicals Agency is expanding dossier evaluation scope for fermentation-derived substances. Cosmetic-grade pantothenate suppliers are responding by segregating EU-dedicated production lines to isolate regulatory exposure.
Long-term offtake agreements are replacing spot market purchasing among North American nutraceutical contract manufacturers. Buyers are committing to annual volumes with indexed pricing to secure supply continuity from Chinese fermentation specialists. This behavioral shift is most visible among tablet and capsule formulators in California and New Jersey seeking cGMP-compliant raw material traceability.
Calcium D-Pantothenate Market Segmentation
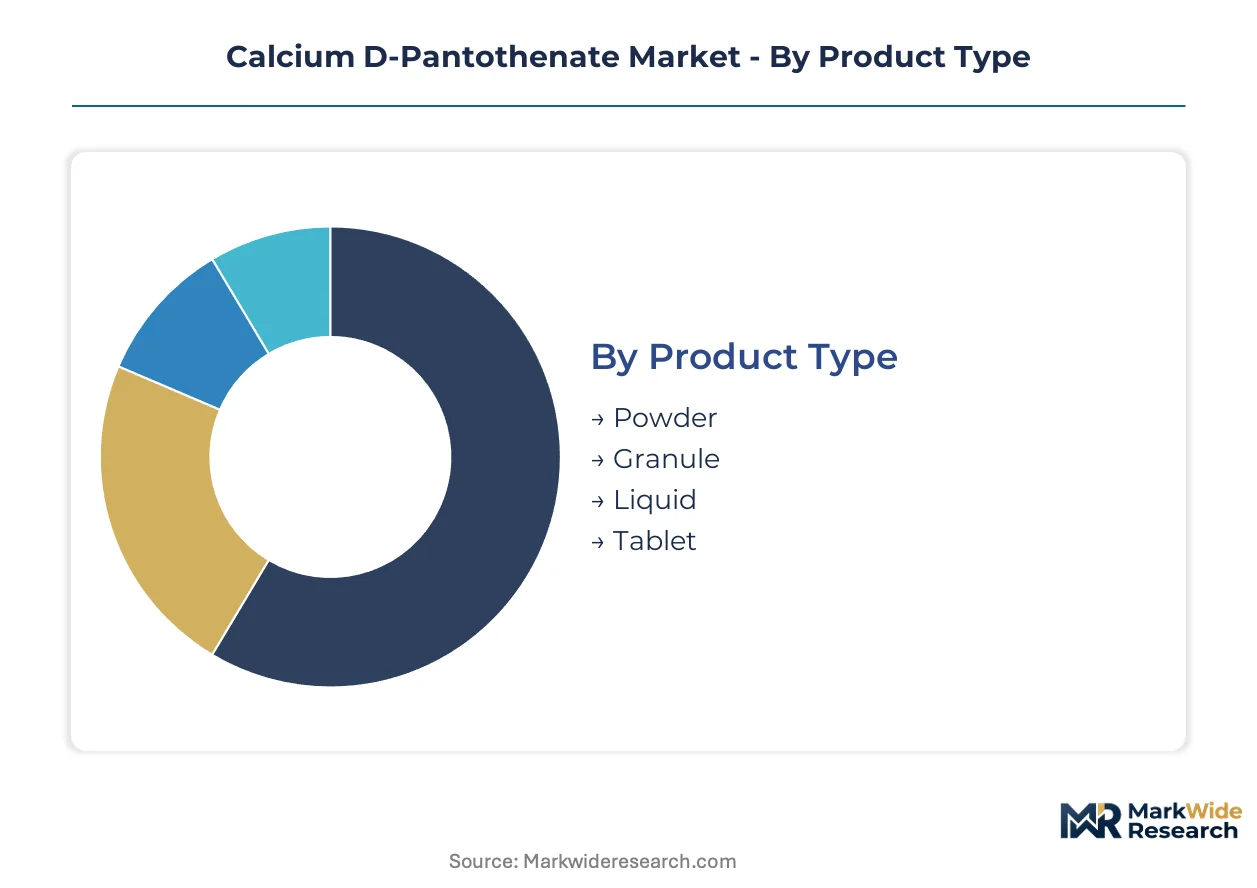
Calcium D-pantothenate formulation requirements diverge sharply across end-use applications, with pharmaceutical and nutraceutical buyers demanding USP-certified powder grades while cosmetic formulators prioritize liquid solubility profiles. Understanding these segment-specific technical specifications enables suppliers to align fermentation output with downstream certification and formulation requirements.
Product Type:
Customization intensity spans from commodity powder grades to specialized liquid concentrates engineered for specific formulation compatibility.
- Powder:Direct-compression grade material assays at 98-102% purity with specified particle size distribution for tablet and capsule manufacturing. Food manufacturers in China and pharmaceutical firms in Germany concentrate procurement here due to handling efficiency and storage stability advantages.
- Liquid:Aqueous concentrates deliver enhanced bioavailability in cosmetic emulsions and liquid dietary supplements. South Korean skin-care manufacturers and U.S. functional beverage formulators drive specification development for solubility-optimized variants.
- Granule:Intermediate particle size enables controlled dissolution profiles for sustained-release pharmaceutical applications.
- Tablet:Pre-formulated finished dosage forms serve direct-to-consumer nutraceutical channels and practitioner-directed therapeutic protocols.
Leading the category by volume: Powder. Expanding most quickly: Liquid.
Application:
Margin structures stratify across regulatory intensity tiers, with pharmaceutical certification commanding premium positioning over food-grade commodity supply.
- Nutraceuticals:B-complex and standalone B5 supplements targeting metabolic support and stress adaptation. U.S. dietary supplement manufacturers and Chinese health product exporters dominate procurement, with FDA cGMP compliance and SAMR registration requirements shaping supplier qualification.
- Pharmaceuticals:Active pharmaceutical ingredient supply for coenzyme A precursor applications in metabolic disorder therapeutics. European Union EMA and U.S. FDA inspection protocols enforce USP and EP monograph adherence.
- Cosmetics:Topical formulations leveraging pantothenate humectant and skin-barrier properties. German and South Korean formulators specify liquid concentrates for emulsion compatibility.
- Food Additives:Fortification applications in cereals, beverages, and functional foods governed by China's GB standards and Codex Alimentarius frameworks.
Dominant by revenue contribution: Nutraceuticals. Steepest expansion trajectory: Cosmetics.
End User:
Procurement sophistication varies from multinational pharmaceutical quality systems to regional food processor commodity purchasing.
- Pharmaceutical Firms:Integrated quality agreements, audit rights, and pharmacopeial certification requirements define supplier relationships. DSM and BASF backward-integrated operations serve this tier exclusively.
- Dietary Supplements:Contract manufacturers and branded marketers in California, New Jersey, and India source through annual offtake agreements with indexed pricing.
- Food Manufacturers:Industrial-scale fortification buyers prioritize unit cost and supply continuity over certification depth.
- Cosmetic Companies:Formulation houses in Germany, France, and South Korea specify cosmetic-grade liquid concentrates with solubility guarantees.
Highest specification barriers: Pharmaceutical Firms. Fastest procurement growth: Dietary Supplements.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and regulatory documentation needs across buyer segments.
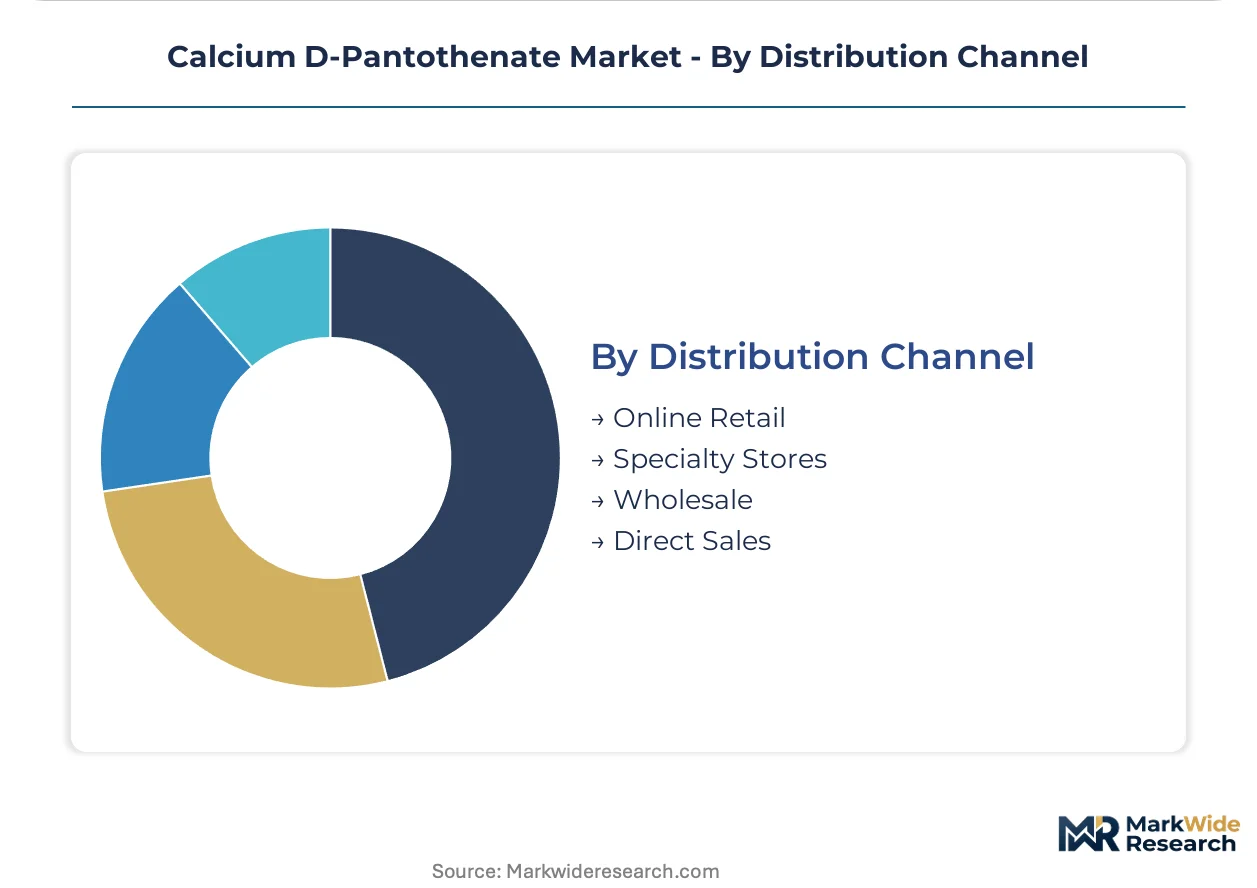
- Direct Sales:Long-term supply agreements link Chinese fermentation specialists with multinational pharmaceutical and nutraceutical manufacturers. Zhenjiang Gaopeng Pharmaceutical leverages captive capacity through direct relationships.
- Wholesale:Industrial distributors aggregate powder-grade volumes for mid-tier food and supplement manufacturers seeking reduced minimum order quantities.
- Online Retail:E-commerce platforms serve small-scale cosmetic formulators and specialty nutraceutical startups requiring rapid sample access and technical documentation.
- Specialty Stores:Regional chemical distributors provide localized inventory and regulatory support for qualified buyers in regulated markets.
Primary volume channel: Direct Sales. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhenjiang's fermentation corridor anchors calcium D-pantothenate supply chains. The city processes corn-derived dextrose feedstock into vitamin B5 intermediates that reach nutraceutical and pharmaceutical formulators across three continents.
China
Jiangsu province's chemical parks concentrate powder-grade fermentation capacity serving global nutraceutical contract manufacturers. SAMR's GB 1903.40-2021 food additive purity standards now govern export-grade specifications. Zhenjiang Gaopeng Pharmaceutical operates captive upstream dextrose refining alongside downstream pantothenate crystallization.
Germany
Ludwigshafen and surrounding Rhineland chemical clusters drive cosmetic-grade liquid concentrate demand for skin-care emulsion formulators. ECHA's REACH registration requirements enforce substance volume tracking for vitamin B5 intermediates. BASF's backward integration into pharmaceutical-grade pantothenate serves EMA-inspected finished-dose manufacturers.
United States
New Jersey and California dietary supplement contract manufacturers source through annual offtake agreements with indexed pricing. FDA cGMP rules mandate lot-level traceability from fermentation through tablet compression. DSM's North American distribution anchors pharmaceutical-grade supply for USP-certified drug applications.
India
Maharashtra and Gujarat nutraceutical manufacturing zones attract contract manufacturers seeking B-vitamin sourcing alternatives. CDSCO's Active Pharmaceutical Ingredient registration pathways and FSSAI's food safety standards are maturing regulatory infrastructure. Hyderabad-based analytical laboratories now offer USP and EP certification support for import substitution.
South Korea
Seoul Capital Area cosmetic formulators specify solubility-optimized liquid pantothenate for K-beauty emulsion products. MFDS cosmetic ingredient safety evaluations drive documentation requirements for humectant applications. Busan-Ulsan chemical processing districts handle intermediate purification for regional skin-care manufacturers.
Calcium D-Pantothenate Market Competitive Environment
Global majors compete with regional champions across certification depth and vertical integration intensity. The vendor base stratifies into three tiers: multinational chemical conglomerates with pharmacopeial certification, Chinese fermentation specialists with captive feedstock supply, and regional distributors serving commodity food-grade buyers. Two strategic archetypes dominate: backward-integrated pharmaceutical-grade producers and scale-driven powder-grade fermentation houses. Competitive moves center on pharmacopeial certification expansion and long-term offtake contracting with indexed pricing mechanisms.
Among Chinese fermentation specialists, Zhenjiang Gaopeng Pharmaceutical Co. Ltd. and Shandong Hwatson Biochem occupy positions exemplifying the captive feedstock archetype. DSM and BASF represent the multinational certification tier. Yifan Pharmaceutical sits within the regional scale-driven segment serving domestic nutraceutical channels.
| Leading Market Players |
|---|
| Zhenjiang Gaopeng Pharmaceutical Co. Ltd. |
| Yifan Pharmaceutical |
| Shandong Hwatson Biochem |
| Shandong Xinfa Pharmaceutical |
| DSM |
| BASF |
| Shandong Xinhua Pharmaceutical Co. Ltd. |
| Anhui Huaheng Biotechnology Co., Ltd. |
| DKS |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity in Zhenjiang anchors both supply security and pricing power for Chinese producers serving global nutraceutical and pharmaceutical formulators. DSM and BASF counter with backward-integrated pharmaceutical-grade positioning, creating a bifurcated structure where certification depth determines margin capture.
Pricing Analysis
Service bundling separates contract-grade supply from commodity spot transactions, with annual offtake agreements now including lot-level traceability documentation and indexed pricing adjustments. Pharmaceutical-grade USP and EP certification commands premium positioning over food-grade powder, while cosmetic liquid concentrates price on solubility guarantees rather than purity alone. Cost compression in standard-grade powder runs through corn-derived dextrose feedstock volatility, squeezing non-integrated fermentation houses. Food manufacturers exhibit highest price sensitivity, prioritizing unit cost over certification depth.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and New Jersey warehouse inventory for just-in-time delivery to pharmaceutical and nutraceutical formulators. Production gravity centers on China, with Zhenjiang's chemical parks supplying downstream tablet and capsule manufacturers worldwide. Corn-derived dextrose, nitrogen sources, and crystallization solvents constitute critical input dependencies. Single-source vulnerability from Jiangsu province concentration creates exposure to environmental compliance shutdowns. Distribution feeds from direct sales relationships into wholesale channels serving mid-tier supplement manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chinese fermentation capacity concentration props pricing by constraining spot market liquidity, forcing buyers into long-term contracting. This supply-constrained structure rewards certified producers while marginalizing commodity traders.
For Market Incumbents: Deploy pharmacopeial certification expansion to defend positioning against Indian contract manufacturing alternatives. DSM and BASF should deepen EMA and FDA inspection readiness, while Chinese specialists must secure SAMR export-grade registrations to access premium channels. Synthetic biology-derived production methods threaten traditional fermentation economics.
For New Entrants and Emerging Players: Continuous bioprocessing technology with PAT sensor integration offers entry into quality-sensitive segments without matching Zhenjiang's scale. Target South Korean cosmetic formulators seeking solubility-optimized liquid concentrates outside established supply relationships. Direct-to-practitioner distribution in the United States bypasses entrenched retail supplement channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational chemical conglomerates seeking fermentation capacity. Long-term viability hinges on regulatory certification depth rather than commodity scale. Watch for EFSA novel food approvals for synthetic biology methods as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dextrose Refining | Zhenjiang Gaopeng Pharmaceutical's captive feedstock supply insulates margin from agricultural commodity cycles. |
| Pharmacopeial Certification Expansion | USP and EP dual registration opens EMA-inspected finished-dose channels for API-grade pantothenate supply. |
| Continuous Fermentation Technology Deployment | PAT sensor integration enables real-time titer measurement and same-day release decisions. |
| Long-term Supply Agreement Structuring | Annual offtake contracts with indexed pricing secure working capital cycles for Chinese fermentation specialists. |
| EU-dedicated Production Line Segregation | REACH registration compliance isolates regulatory exposure for cosmetic-grade pantothenate exporters. |
Study Parameters
Document review covered FDA cGMP guidance documents, SAMR GB standards, EMA inspection protocols, and USP monograph revisions, complemented by interviews with fermentation plant managers, nutraceutical procurement leads at California contract manufacturers, pharmaceutical quality assurance directors, and cosmetic formulation chemists in Seoul. Secondary validation drew from customs trade data, SEC filings of listed chemical producers, and pharmacopeial harmonization working papers. Bottom-up capacity modeling triangulated against top-down demand segmentation across nutraceutical, pharmaceutical, cosmetic, and food additive applications.
Segment-level outputs across powder, liquid, granule, and tablet formats were projected over the analysis window, with nutraceutical, pharmaceutical, cosmetic, and food additive end-use shares modeled separately. CAGRs were derived from regression analysis of historical volume trajectories and capacity expansion announcements. Fermentation yield improvements and pharmacopeial certification timelines served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under feedstock price spikes or sudden environmental compliance shutdowns in Jiangsu province. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Sandarac Market