
 Glucono Delta Lactone Market | 2026-2036
Glucono Delta Lactone Market Size, Share, and Industry Trends Forecast 2026-2036
Glucono Delta Lactone Market Foresight
Asset-light toll manufacturing is narrowing the capital barrier for mid-tier entrants in glucono delta lactone supply. Jungbunzlauer Suisse AG leverages its Swiss fermentation infrastructure to dominate pharmaceutical-grade output. Corbion N.V. sustains backward integration into dextrose feedstock, anchoring margin control across European dairy supply chains. BASF SE competes through industrial-grade scale, occupying bulk chemical channels with standardized specifications.
Glucono delta lactone is a cyclic ester of gluconic acid (C6H10O6, MW 178.14 g/mol) produced via microbial fermentation of glucose, subsequently crystallized and purified to specific mesh sizes for controlled acid release in aqueous systems. Its primary commercial function centers on pH reduction without direct acid taste, enabling precise coagulation in dairy processing and delayed leavening in baking formulations. Food Grade material leads volume throughput, though Pharmaceutical Grade commands superior unit economics through CDMO qualification requirements and USP-NF certification overhead. Cosmetic Grade represents the fastest-expanding demand pool, as formulators substitute GDL for traditional alpha-hydroxy acids in exfoliating products seeking milder epidermal interaction profiles.
FDA food additive regulations under 21 CFR 184.1318 govern GDL purity thresholds and labeling requirements for US market access, while EFSA evaluates novel application extensions through the EU food additive reauthorization cycle. China's SAMR enforces GB 1886.174 standards for fermentation-derived acidity regulators, creating compliance divergence that shapes regional sourcing strategies. Stakeholders must monitor regulatory divergence between pharmacopeial grades and food-grade specifications, as tightening purity definitions in one jurisdiction typically cascade into supplier qualification upgrades across all served segments.
Market Dynamics
Clean-label dairy processors are forcing fermentation-derived acidifiers into formulation pipelines faster than suppliers can expand pharmaceutical-grade capacity, tightening grade-specific availability and reshaping contract structures.
Growth Catalysts
- FSSAI clean-label mandates:India's food safety regulator is accelerating natural acidity regulator adoption in processed dairy, pulling GDL into curd and paneer manufacturing lines previously dependent on synthetic alternatives.
- Dual carbon goals:China's MIIT incentives for bio-based chemical production are redirecting glucose fermentation capacity toward food-grade acidifiers, expanding domestic supply bases for East Asian dairy clusters.
- Enzymatic crystallization:Novel biocatalytic purification methods are reducing pharmaceutical-grade production cycles, enabling faster CDMO qualification timelines for injectable formulation clients.
Market Restraints
- Glucose feedstock volatility:Corn-derived dextrose pricing swings directly compress fermentation margins, particularly for non-integrated producers lacking captive starch processing.
- East Asian supply concentration:Fermentation technology clusters in Shandong and Jiangsu provinces dominate crystallization-grade output, creating geographic single-source vulnerability for European formulators.
- Citric acid substitution:Lower-cost acidulants with comparable pH reduction profiles are displacing GDL in industrial cleaning applications and some mass-market baking segments.
Strategic Opportunities
- Saudi dairy expansion:SFDA modernization of food additive standards is opening formulation trials for GDL in extended-shelf-life laban and cheese analog production.
- Cosmetic acid replacement:Korean formulators are substituting GDL for glycolic acid in sensitive-skin exfoliants, creating pharmaceutical-grade demand outside traditional food channels.
- Precision fermentation convergence:Integration of AI-driven strain optimization with continuous crystallization is compressing batch-to-batch variability for high-purity pharmaceutical contracts.
Industry Challenges
- USP-NF certification timelines:Pharmaceutical-grade validation cycles now extend eighteen to twenty-four months, freezing supplier switching options for injectable drug manufacturers.
- Legacy ERP integration:Batch record digitization for FDA 21 CFR Part 11 compliance is forcing mid-tier fermenters into costly MES upgrades without guaranteed contract volume recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucono Delta Lactone Market |
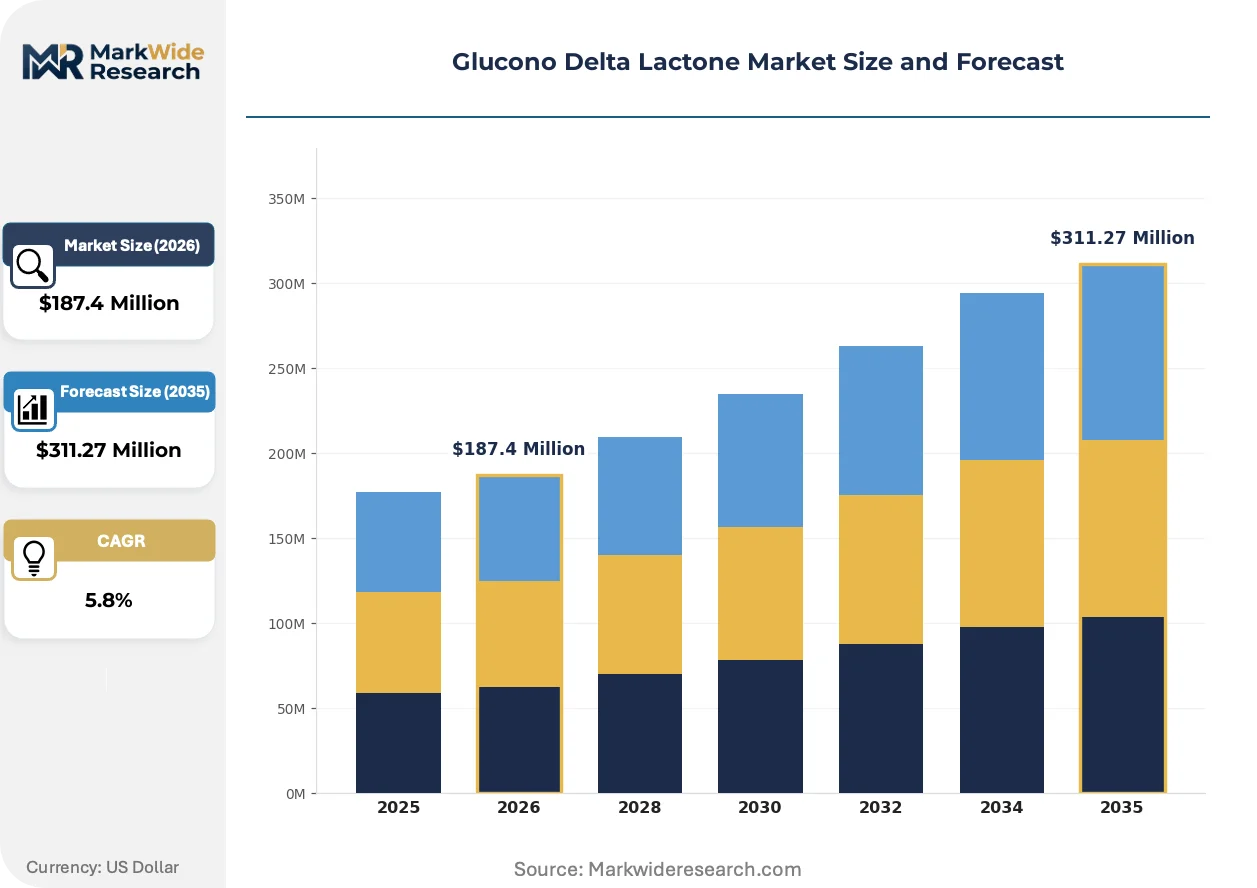
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Dairy Processing, Meat Curing, Baking, Beverage Acidification, Cosmetic Formulations End User: Dairy Manufacturers, Meat Processors, Bakeries, Beverage Companies, Cosmetic Producers Packaging Type: Bulk Bags, Drums, Sachets, Cartons, Tins |
| Companies Covered | BASF SE, Anhui SS Biochemical Technology Co., Ltd, Corbion N.V., Kanto Chemical Co., Inc., Hefei TNJ Chemical Industry Co., Ltd, Jungbunzlauer Suisse AG, Archer Daniels Midland Company, Millipore Sigma, Fufeng Group Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucono Delta Lactone Market Shifts & Advancements
Digital traceability infrastructure is penetrating fermentation supply chains, compressing batch authentication cycles and enabling real-time purity verification across multi-grade production lines.
Inline Raman spectroscopy for crystallization endpoint detection is digitizing quality assurance workflows in pharmaceutical-grade GDL manufacturing. CDMOs serving sterile injectable formulators are deploying these systems to eliminate offline HPLC sampling delays. The technology is digitizing release-to-ship timelines from days to hours, compressing working capital requirements for high-value batches.
EFSA's food additive reauthorization cycle is tightening purity thresholds for fermentation-derived acidity regulators ahead of 2025 evaluations. The regulatory friction is forcing European suppliers into redundant testing protocols against both pharmacopeial and food-grade specifications. Dairy processors in Germany and France are responding by consolidating purchasing around dual-certified suppliers, reducing qualified vendor pools.
Formulator procurement is consolidating around suppliers offering integrated regulatory dossier support. Mid-sized dairy processors are abandoning spot-market purchasing for multi-year toll manufacturing agreements with embedded compliance documentation. The shift is most visible in Netherlands and Belgium, where clean-label marketing claims require auditable additive provenance from glucose source through final crystallization.
Glucono Delta Lactone Market Segmentation
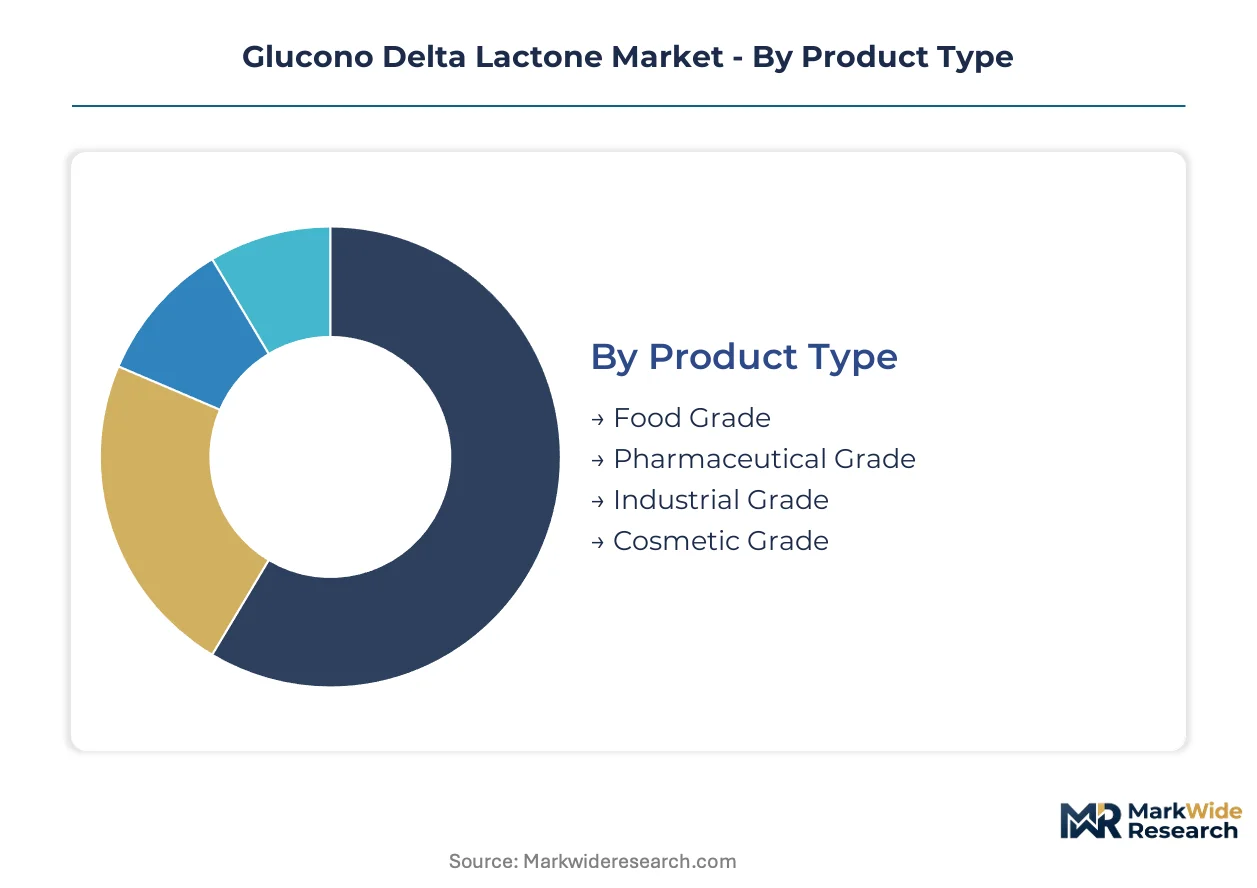
Glucono delta lactone markets fragment sharply across purity grades and end-use specifications, with regulatory thresholds determining supplier qualification and pricing stratification. Each segmentation dimension carries distinct margin profiles and certification burdens that reshape procurement patterns across food, pharmaceutical, and cosmetic channels.
Product Type:
Cost tier differentiation separates commodity fermentation outputs from specialized grades commanding pharmacopeial premiums and CDMO validation overhead.
- Food Grade:Standardized crystallization to specific mesh sizes enables controlled acid release in aqueous dairy systems. Demand concentrates in East Asian fermentation clusters serving clean-label dairy processors in China and Japan, with FSSAI mandates in India accelerating natural acidifier substitution.
- Pharmaceutical Grade:USP-NF certified material undergoes eighteen-to-twenty-four-month validation cycles for injectable formulation qualification. CDMO contracts in Switzerland and Germany anchor premium pricing through sterile manufacturing documentation and batch-specific CoA protocols.
- Industrial Grade:Bulk chemical specifications serve non-food pH adjustment applications with standardized purity thresholds.
- Cosmetic Grade:Korean formulators are substituting this material for glycolic acid in sensitive-skin exfoliants, creating demand outside traditional food channels.
Food Grade commands the established base. The steepest expansion runs through Cosmetic Grade.
Application:
Functional performance requirements in pH control and coagulation timing determine formulation adoption across protein processing and leavening systems.
- Dairy Processing:Precise coagulation control in tofu and fresh cheese production without direct acid taste drives formulation loyalty. German and French processors are consolidating purchasing around dual-certified suppliers to satisfy EFSA reauthorization purity thresholds.
- Cosmetic Formulations:Milder epidermal interaction profiles compared to traditional alpha-hydroxy acids are pulling GDL into Korean and Japanese skincare lines targeting barrier-sensitive demographics.
- Meat Curing:pH reduction accelerates color fixation and shelf-life extension in processed protein systems.
- Baking:Delayed leavening action enables controlled rise in refrigerated dough applications.
- Beverage Acidification:Neutral taste profile supports clean-label positioning in functional drink categories.
Dairy Processing anchors volume throughput. Cosmetic Formulations is gaining share fastest.
End User:
Customer type segmentation reflects divergent procurement sophistication, from spot-market commodity purchasing to multi-year toll agreements with embedded compliance documentation.
- Dairy Manufacturers:Netherlands and Belgium processors are abandoning spot-market purchasing for multi-year toll manufacturing agreements requiring auditable additive provenance from glucose source through final crystallization.
- Cosmetic Producers:Korean formulators are driving pharmaceutical-grade demand through sensitive-skin product lines, with procurement teams requiring integrated regulatory dossier support for marketing claim substantiation.
- Meat Processors:Standardized acidification requirements support volume purchasing through established distribution channels.
- Bakeries:Industrial and artisanal segments split between bulk commodity supply and specialty ingredient sourcing.
- Beverage Companies:Clean-label positioning drives natural acidifier specification in functional and premium categories.
Dairy Manufacturers represent the anchored revenue base. Cosmetic Producers shows the steepest upward trajectory.
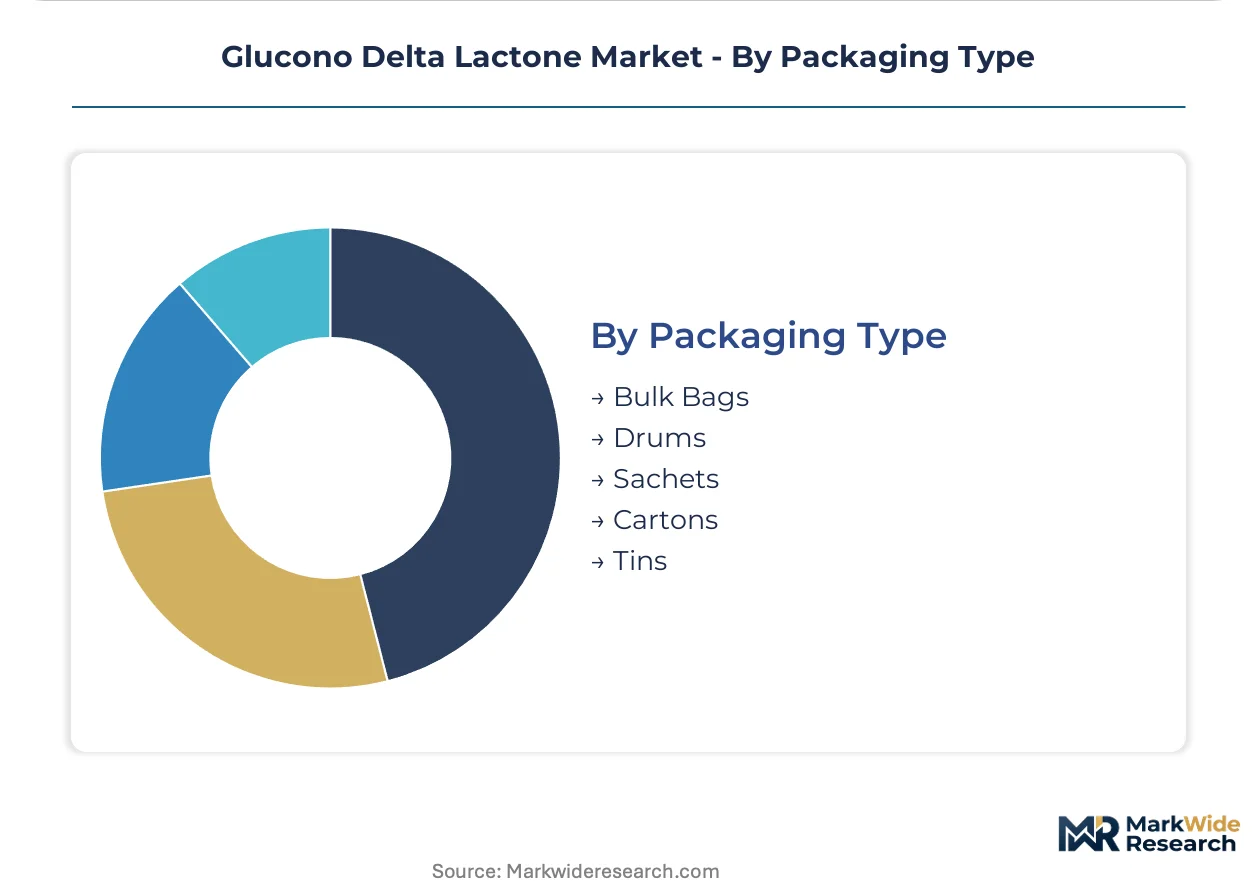
Packaging Type:
Volume scale and handling infrastructure determine packaging selection, with regulatory documentation requirements varying by shipment size and destination market.
- Bulk Bags:Food-grade dairy processors in Germany and France utilize FIBC formats for high-volume crystallization-grade material, with inline Raman spectroscopy enabling batch authentication before discharge.
- Drums:Pharmaceutical-grade shipments to CDMOs require sealed steel containment with tamper-evident closure systems and chain-of-custody documentation.
- Sachets:Retail and artisanal bakery channels favor pre-measured unit dosing for formulation consistency.
- Cartons:Secondary packaging for multi-unit pharmaceutical and cosmetic shipments.
- Tins:Premium cosmetic and specialty food positioning with moisture-barrier properties.
Bulk Bags dominate food-grade logistics. Drums capture the pharmaceutical premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy manufacturers in Germany, China, and Japan concentrate procurement power for pharmaceutical-grade material, while cosmetic formulators in South Korea and the Netherlands are expanding addressable demand beyond traditional food channels.
China
Fermentation capacity expansion in Shandong and Jiangsu provinces serves domestic dairy processors shifting to clean-label acidifiers. SAMR enforces GB 1886.174 standards for fermentation-derived additives, tightening purity thresholds that reshape supplier qualification. MIIT dual carbon incentives redirect glucose fermentation capacity toward food-grade acidifiers, expanding supply bases for East Asian dairy clusters.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia consolidate purchasing around dual-certified suppliers to satisfy EFSA reauthorization purity thresholds. EFSA food additive evaluations tighten specifications for fermentation-derived acidity regulators ahead of 2025 cycles. Cologne-based formulators are embedding multi-year toll manufacturing agreements with auditable additive provenance requirements.
United States
Pharmaceutical-grade demand from sterile injectable CDMOs concentrates in New Jersey and Massachusetts manufacturing corridors. FDA 21 CFR 184.1318 governs GDL purity thresholds and labeling requirements for food additive market access. Chicago-area dairy processors are accelerating natural acidifier substitution in extended-shelf-life cheese production.
South Korea
Cosmetic formulators in Seoul and Gyeonggi-do substitute GDL for glycolic acid in sensitive-skin exfoliants, creating pharmaceutical-grade demand outside food channels. MFDS cosmetic safety standards shape ingredient qualification timelines for barrier-sensitive product lines. Busan-based procurement teams require integrated regulatory dossier support for marketing claim substantiation.
Netherlands
Dairy manufacturers in Randstad and Brabant abandon spot-market purchasing for multi-year toll agreements with embedded compliance documentation. EFSA reauthorization cycles force redundant testing protocols against pharmacopeial and food-grade specifications. Eindhoven-region processors demand auditable additive provenance from glucose source through final crystallization.
Glucono Delta Lactone Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Swiss and German fermentation specialists anchor pharmaceutical-grade supply through CDMO qualification infrastructure. Chinese and Dutch chemical conglomerates dominate food-grade volume through backward integration into dextrose feedstock. The competitive arena splits between premium pharmacopeial certification, mid-tier toll manufacturing scale, and commodity bulk chemical channels. Capacity expansion and regulatory dossier integration constitute the dominant competitive moves reshaping supplier-customer contracting.
Within the fermentation-specialist tier, Jungbunzlauer Suisse AG represents Swiss pharmaceutical-grade infrastructure, while Corbion N.V. exemplifies Dutch backward integration into feedstock supply. BASF SE anchors German industrial-grade scale. These three occupy positions across distinct certification tiers without overlapping customer segments.
| Leading Market Players |
|---|
| BASF SE |
| Anhui SS Biochemical Technology Co., Ltd |
| Corbion N.V. |
| Kanto Chemical Co., Inc. |
| Hefei TNJ Chemical Industry Co., Ltd |
| Jungbunzlauer Suisse AG |
| Archer Daniels Midland Company |
| Millipore Sigma |
| Fufeng Group Co., Ltd |
| Others |
Supply & Pricing Matrix
Shandong and Jiangsu fermentation clusters anchor crystallization-grade output, concentrating margin capture downstream with European dairy processors and sterile injectable CDMOs who face eighteen-to-twenty-four-month supplier qualification timelines. This geographic supply concentration amplifies pricing power for integrated producers while forcing non-integrated buyers into long-term toll agreements with embedded compliance premiums.
Pricing Analysis
Certification level creates the primary spread across pharmaceutical, food, and industrial tiers. Three-tier pricing structure across USP-NF certified, FSSAI-compliant, and bulk chemical specifications reflects eighteen-to-twenty-four-month validation overhead versus spot-market commodity availability. Cost compression in food-grade material is intensifying because citric acid substitution erodes GDL's position in mass-market baking. Industrial cleaning applications show the highest price sensitivity, while sterile injectable CDMOs accept substantial premiums for batch-specific CoA protocols and chain-of-custody documentation.
Supply Chain Analysis
Corn-derived dextrose feedstock draws from North American grain belts and Chinese starch processing corridors, with glucose pricing volatility transmitting directly into fermentation margins. Crystallization-grade output concentrates in China, Switzerland, and the Netherlands, while pharmaceutical purification capacity clusters around Swissmedic-regulated facilities and German EMA-aligned infrastructure. Single-source vulnerability runs through Shandong fermentation complexes for European formulators lacking dual-qualified suppliers. Distribution runs through toll manufacturing agreements with embedded regulatory dossier support rather than spot-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
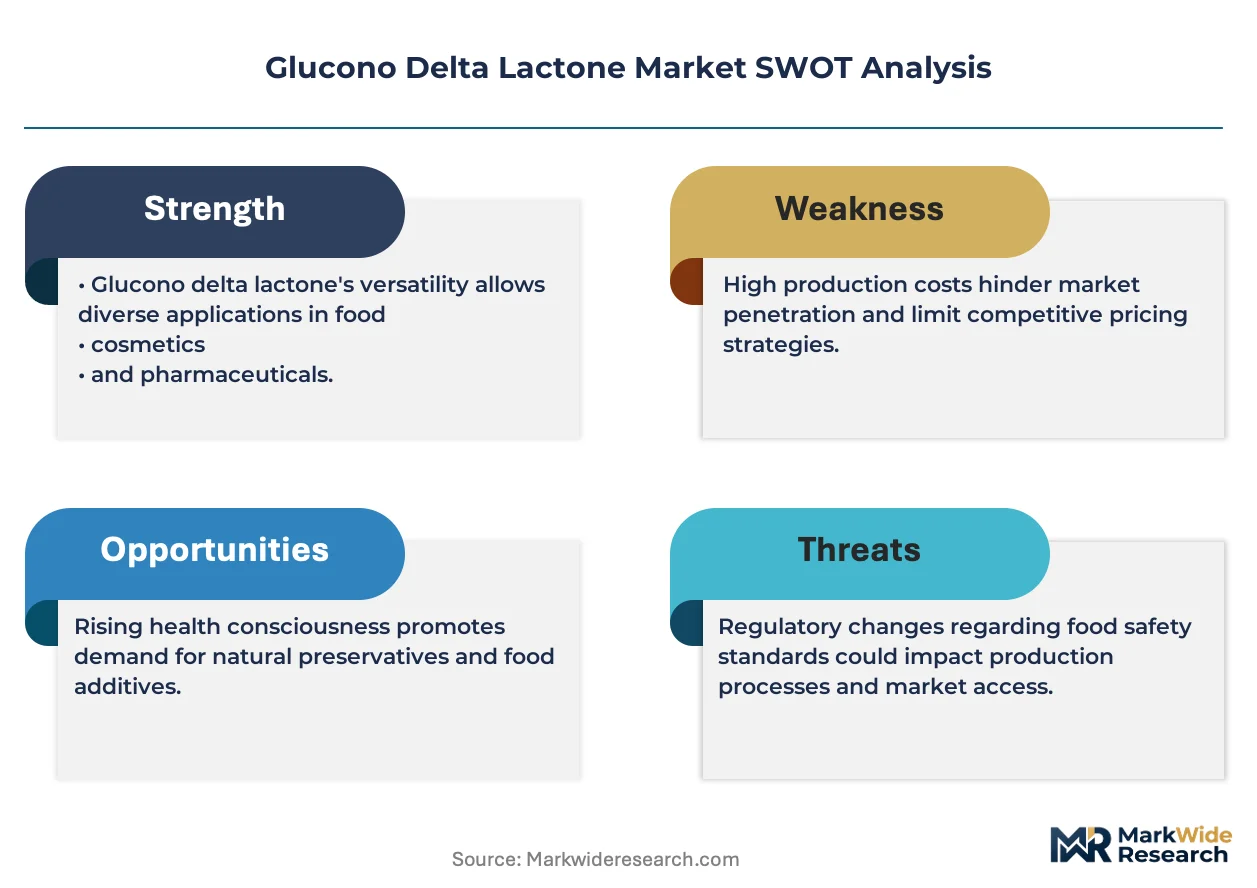
This market rewards regulatory entrenchment as the dominant defensive moat, with USP-NF and EFSA dual-certification timelines creating switching costs that freeze buyer-supplier relationships for multi-year contract horizons.
For Market Incumbents: Build certification moats through simultaneous USP-NF, EFSA, and FSSAI dossier maintenance to capture dairy processor consolidation around dual-qualified suppliers. Add sterile manufacturing documentation capacity in Switzerland or Germany to serve CDMO qualification pipelines. Citric acid substitution in industrial cleaning threatens commodity-tier margins, demanding upstream integration into dextrose feedstock to defend cost position. For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade pharmaceutical material for Korean sensitive-skin exfoliant formulators, where MFDS safety standards create qualification barriers lower than sterile injectable tiers. Target Saudi dairy expansion as SFDA modernization opens formulation trials for extended-shelf-life laban production. Precision fermentation convergence with AI-driven strain optimization offers a go-to-market angle for compressed batch-to-batch variability contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation specialists holding captive dextrose supply and partial EFSA certification progress toward full dual-grade qualification. Five-to-ten-year viability hinges on regulatory dossier depth rather than capacity scale alone. Monitor EFSA food additive reauthorization cycle outcomes as the inflection signal for European supplier consolidation velocity and redundant testing protocol burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dextrose Feedstock | Corbion N.V.'s margin control model anchors European dairy supply chain competitiveness against glucose volatility. |
| Dual Certification Investment | Simultaneous USP-NF and EFSA qualification expands addressable buyer pools across pharmaceutical and premium food channels. |
| Precision Fermentation Convergence | AI-driven strain optimization with continuous crystallization compresses batch variability for high-purity pharmaceutical contracts. |
| Cosmetic Grade Capacity Expansion | Korean MFDS-aligned output captures sensitive-skin exfoliant substitution demand outside traditional food applications. |
| Toll Manufacturing Agreement Structuring | Multi-year embedded compliance contracts replace spot purchasing for Netherlands and Belgium clean-label dairy processors. |
Research Methodology
Desk research of FDA 21 CFR filings, EFSA food additive reauthorization documentation, SAMR GB standard publications, and customs trade flow databases preceded structured interviews with fermentation plant managers, dairy processor procurement leads, CDMO regulatory affairs directors, and cosmetic formulator R&D heads. Bottom-up capacity modeling triangulated against top-down demand segmentation across grade tiers and end-use applications.
Fixed assumptions held regulatory timeline standards and dual carbon incentive structures constant across the projection horizon, while glucose feedstock pricing and citric acid substitution elasticity were varied under stress scenarios. Segmentation dimensions modeled included purity grade tier, end-use industry channel, packaging format, and regional regulatory cluster. CAGRs were derived from volume-throughput trajectories calibrated to FSSAI mandate implementation pace and EFSA reauthorization cycle outcomes.
Stress conditions across glucose price volatility bands, certification timeline extensions, and East Asian supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory divergence between pharmacopeial and food-grade specifications. Cross-checking against SAMR enforcement action frequencies and EFSA additive evaluation calendars is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Multichannel Reagent Reservoir Market