
 Europe Sugarcane Wax Market | 2026-2036
Europe Sugarcane Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sugarcane Wax Market Insights
A capital-intensity divergence between integrated refiners and specialty compounders is unwinding competitive stability in European sugarcane wax supply. Clariant AG leverages its Swiss-based botanical extraction infrastructure to secure raw material continuity. BASF SE anchors its position through backward integration into fatty acid derivative streams. KahlWax GmbH & Co. KG specializes in small-batch cosmetic-grade refining, occupying a defensible niche against volume leaders.
Europe sugarcane wax comprises long-chain aliphatic esters, alcohols, and acids derived from Saccharum officinarum leaf filtrates, with melting points typically ranging from 78°C to 82°C and saponification values between 75 and 95; manufacturers refine this material for surface coating, binding, and rheology modification across food, cosmetic, and industrial applications. Cosmetic Grade commands premium positioning due to stringent impurity thresholds and certification overhead, while Food Grade volume expands through confectionery and fruit coating substitution for shellac. Pharmaceutical Grade remains a margin-rich segment constrained by European Medicines Agency validation requirements and limited qualified refining capacity.
REACH registration obligations and the EU Green Deal's bio-based content targets shape product formulation roadmaps and import qualification protocols for non-European suppliers. EFSA food contact material approvals determine access to packaging and coating applications across member states. Croda International plc navigates these frameworks through dedicated regulatory affairs teams in the United Kingdom and Netherlands. Stakeholders must monitor evolving ECHA substance evaluation timelines and national transpositions of the Packaging and Packaging Waste Regulation to anticipate qualification bottlenecks.
Market Dynamics
REACH registration obligations and the EU Green Deal's bio-based content mandates are compressing formulation timelines for European cosmetic and food packaging manufacturers. These regulatory pressures are forcing substitution away from petroleum-derived waxes toward Saccharum officinarum-derived alternatives, with qualified refining capacity emerging as the binding constraint on supply expansion.
Growth Catalysts
- EU Green Deal bio-based targets:Packaging and Packaging Waste Regulation transpositions across member states mandate minimum renewable content thresholds. Food coating and cosmetic formulators accelerate qualification of sugarcane wax to meet 2030 interim targets.
- Cosmetic clean-label pivot:Personal care brands reformulate away from synthetic emollients. Leaf-derived esters command preference in skin-conditioning applications where petroleum alternatives face consumer rejection.
- Shellac substitution momentum:Confectionery manufacturers in Germany and France replace insect-derived coatings. EFSA food contact approvals for sugarcane wax enable direct substitution in fruit and candy surface treatments.
Market Restraints
- Raw material geographic concentration:Saccharum officinarum cultivation for wax extraction concentrates in tropical zones outside Europe. European refiners face freight cost volatility and currency exposure on Brazilian and Indian feedstock.
- EMA validation bottlenecks:Pharmaceutical-grade qualification requires multi-year stability documentation. Limited European refining capacity holds EMA-certified output below demand from topical drug formulators.
- Carnauba wax price competition:Palm-derived alternatives from Northeast Brazil undercut sugarcane wax in high-gloss coating applications. Copernicia prunifera supply expansion limits pricing power in industrial segments.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Greenfield personal care production clusters in Central Europe lack qualified local wax suppliers. Early-mover refiners can anchor supply contracts with relocating formulators.
- CSRD supply-chain disclosure requirements:Corporate Sustainability Reporting Directive mandates Scope 3 emissions transparency. Sugarcane wax offers documented bio-based carbon credentials that synthetic alternatives cannot match.
- Supercritical CO2 extraction convergence:Botanical extraction technology from European hemp and hop processing adapts to sugarcane leaf processing. Equipment repurposing lowers capital barriers for specialty-grade entrants.
Industry Challenges
- Analytical chemist scarcity:ECHA substance evaluation protocols require specialized chromatography expertise for impurity profiling. Refiners compete with pharmaceutical and agrochemical sectors for limited European analytical talent pools.
- Multi-grade certification overlap:Cosmetic, food, and pharmaceutical grades demand non-intersecting equipment trains. Small-batch specialists face capital inefficiency when serving multiple certification tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sugarcane Wax Market |
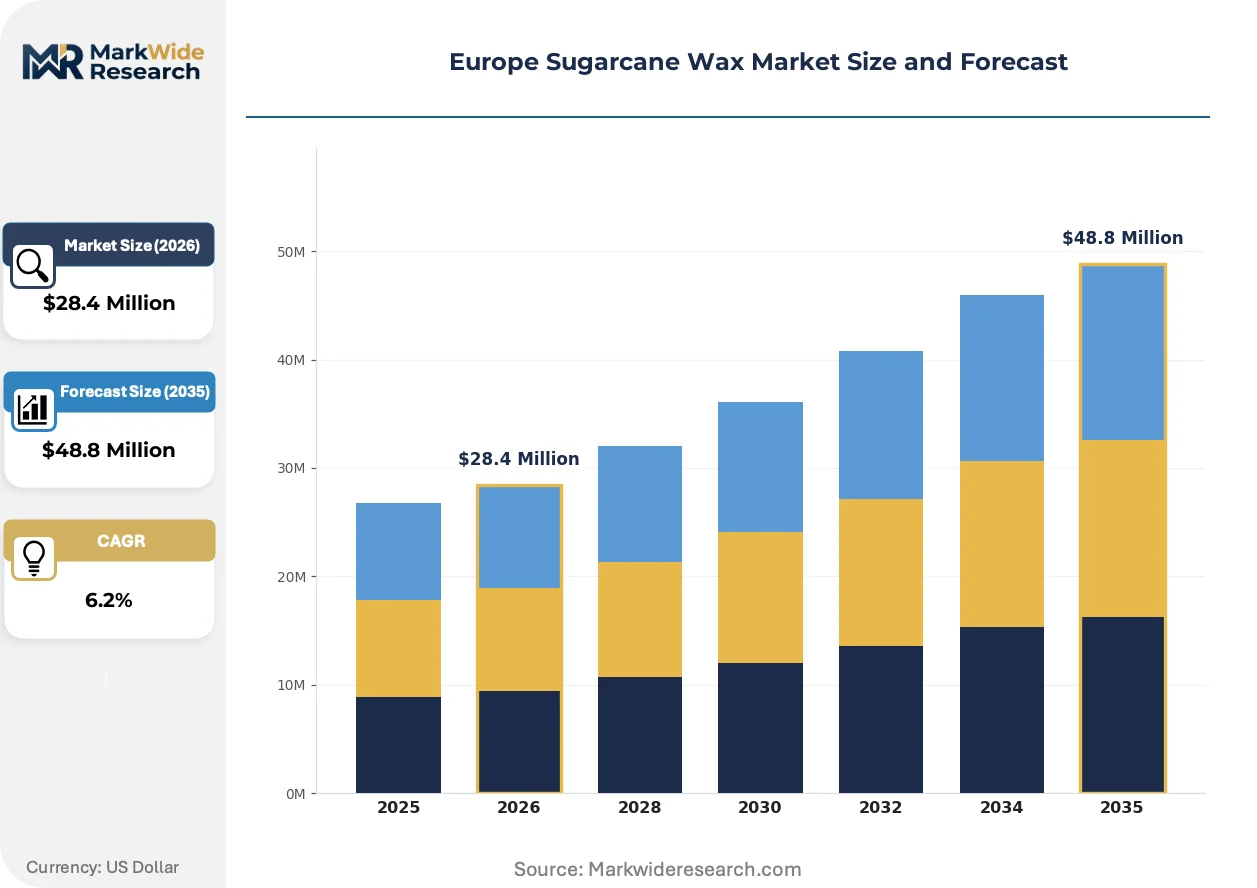
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $48.8 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candles, Cosmetics, Packaging, Food Coatings Application: Personal Care, Pharmaceuticals, Food Industry, Industrial Uses Grade: Food Grade, Cosmetic Grade, Industrial Grade, Pharmaceutical Grade Packaging Type: Bottles, Jars, Pouches, Bulk Packaging |
| Companies Covered | Clariant AG, Strahl & Pitsch, Inc., BASF SE, Th. Goldschmidt AG, KahlWax GmbH & Co. KG, Croda International plc, Lonza Group AG, Eastman Chemical Company, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sugarcane Wax Market Trends and Innovations
Formulation science and regulatory disclosure requirements are compressing the acceptable specification window for plant-derived waxes. Refiners invest in precision fractionation to serve divergent purity requirements across end-use verticals without cross-contamination risk.
Supercritical fluid extraction technology is bifurcating the European refining landscape. High-pressure CO2 systems from Swiss and German equipment manufacturers enable solvent-free processing that meets cosmetic-grade residual limits. Large-scale hexane-based refiners in the Netherlands face stranded asset risk as formulators specify supercritical-derived inputs for premium positioning. The technology is compressing batch sizes while expanding SKU diversity, forcing capital reallocation across the supply base.
REACH authorization timelines are extending qualification horizons for new market entrants. ECHA's 2024-2026 substance evaluation work program prioritizes long-chain aliphatic esters for hazard reclassification. Existing registrants with dossier completeness hold competitive moats against importers facing data gap accusations. Cosmetic-grade suppliers with early registration timestamps capture formulation lock-in ahead of potential restriction scenarios.
Brand procurement teams are consolidating supplier panels around vertically integrated refiners with captive analytical capabilities. Direct contracting with extraction-to-delivery operators replaces distributor-mediated purchasing for volume cosmetic accounts. This pattern concentrates most visibly in German and French personal care manufacturing clusters where sustainability audit requirements favor single-source traceability over multi-vendor flexibility.
Europe Sugarcane Wax Market Segmentation
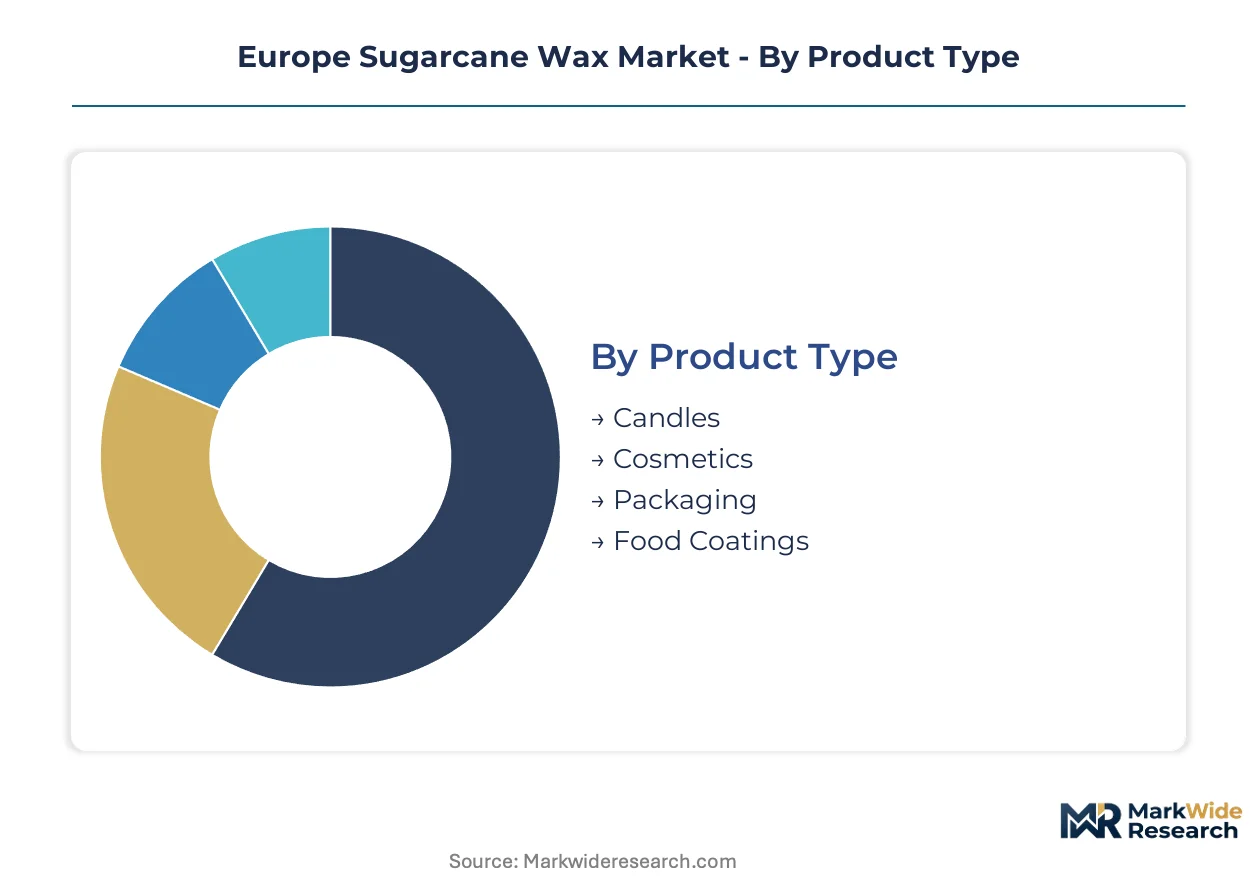
European sugarcane wax demand fragments across certification tiers and end-use specifications that impose incompatible purity thresholds. Refiners must dedicate discrete equipment trains to each grade, fragmenting capacity utilization and forcing strategic specialization choices.
Product Type:
Cosmetics and food coatings face the most acute substitution pressure from carnauba wax and synthetic alternatives, driving qualification investments to defend positioning.
- Candles:Long-chain aliphatic esters provide clean-burning properties with minimal soot residue. Demand concentrates in artisanal and premium home fragrance segments across Germany and France where petroleum paraffin faces consumer rejection.
- Cosmetics:Refined ester fractions serve as plant-derived emollients and texture modifiers in skin-conditioning formulations. German and French personal care manufacturers prioritize Saccharum officinarum-derived inputs for clean-label positioning against petroleum alternatives.
- Packaging:Surface coating applications leverage wax hydrophobicity for moisture barrier properties in paper and board substrates.
- Food Coatings:EFSA-approved grades replace shellac in confectionery and fruit surface treatments across German and French processing facilities.
Candles retains volume leadership; Cosmetics holds the steepest expansion curve.
Application:
Personal care applications command the widest specification spreads, with pharmaceutical qualification imposing the tightest purity constraints.
- Personal Care:Leaf-derived esters function as occlusive agents and viscosity modifiers in skin and hair formulations. French and German cosmetic compounders specify supercritical CO2-extracted grades for premium product lines.
- Pharmaceuticals:EMA-validated grades require multi-year stability documentation and dedicated manufacturing suites. Limited qualified European refining capacity constrains supply to topical drug formulators in Switzerland and Germany.
- Food Industry:Confectionery and fresh produce coating applications demand EFSA food contact material approvals.
- Industrial Uses:Lubricant and mold release applications tolerate broader specification windows than consumer-facing segments.
Personal Care dominates revenue contribution; Pharmaceuticals maintains the steepest margin premium.
Grade:
Certification tier directly determines addressable end-use markets and capital requirements for dedicated processing infrastructure.
- Food Grade:EFSA-compliant refining achieves impurity thresholds suitable for direct food contact and coating applications. Volume expansion accelerates in German confectionery and French fruit processing clusters replacing shellac.
- Cosmetic Grade:Stringent residual solvent limits and microbiological specifications command premium positioning. Swiss and German refiners invest in supercritical CO2 extraction to meet cosmetic formulator qualification protocols.
- Industrial Grade:Broader specification tolerances serve lubricant, adhesive, and surface coating applications with lower purity requirements.
- Pharmaceutical Grade:EMA validation requirements restrict supply to refiners with dedicated equipment trains and documented stability programs.
Food Grade captures the widest volume base; Cosmetic Grade delivers the fastest share gains.
Packaging Type:
Packaging configuration aligns with customer scale and regulatory documentation requirements rather than functional performance differentiation.
- Bottles:Liquid or molten wax delivery serves small-batch cosmetic compounders and pharmaceutical formulators requiring precise dosing control.
- Jars:Solid block or pellet formats accommodate artisanal candle makers and specialty food processors with lower throughput requirements.
- Pouches:Flexible packaging reduces freight costs for mid-volume personal care and food coating manufacturers.
- Bulk Packaging:Tanker or drum shipments serve high-volume industrial users and large cosmetic manufacturing clusters in Germany and France.
Bulk Packaging anchors industrial segment economics; Bottles sustains the most rapid format expansion in cosmetic-grade distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German refiners with captive supercritical extraction infrastructure, while Italian and Spanish compounders absorb freight premiums on Brazilian feedstock. This asymmetry shapes capacity investment patterns across the continent.
Germany
Cosmetic formulators in Hamburg and Düsseldorf drive demand for ECHA-registered cosmetic-grade wax. The EU Green Deal's bio-based packaging mandates accelerate shellac substitution in confectionery clusters around Cologne. BASF SE anchors supply security through backward integration into fatty acid streams.
France
Personal care manufacturers in Île-de-France specify supercritical CO2-extracted grades for premium skin-conditioning lines. ANSM cosmetic ingredient oversight tightens impurity documentation requirements. L'Oréal-adjacent compounders in Clichy consolidate supplier panels around single-source traceability.
Switzerland
Pharmaceutical-grade qualification dominates Geneva and Basel refining economics. Swissmedic validation requirements restrict EMA-certified output below topical drug formulator demand. Clariant AG leverages botanical extraction infrastructure for raw material continuity.
Italy
Artisanal candle makers in Tuscany and Lombardy favor long-chain aliphatic esters for clean-burning positioning. REACH registration costs disadvantage smaller importers against established refiners. Milan-based cosmetic compounders pivot from petroleum emollients to Saccharum officinarum-derived alternatives.
Netherlands
Rotterdam logistics hubs buffer feedstock volatility for hexane-based refiners serving industrial coating segments. EFSA food contact approvals enable fruit coating substitution in agribusiness clusters around Wageningen. Large-scale refiners face stranded asset risk as supercritical specifications penetrate premium tiers.
Europe Sugarcane Wax Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive stability across the European supply base. Integrated chemical conglomerates with captive raw material streams occupy volume positions, while specialty refiners command premium tiers through certification depth. Three archetypes dominate: backward-integrated multinationals, supercritical extraction specialists, and regional compounders with flexible batch capacity. Competitive moves concentrate on M&A for regulatory dossier accumulation and greenfield supercritical capacity deployment.
Among Swiss and German-based operators, Clariant AG, BASF SE, and KahlWax GmbH & Co. KG exemplify the tripartite structure. Clariant AG represents the technology-forward archetype with dedicated botanical infrastructure. BASF SE anchors the integrated multinational tier through upstream control over derivative streams. KahlWax GmbH & Co. KG occupies the specialist position, serving small-batch cosmetic qualification requirements that volume leaders cannot address profitably.
| Leading Market Players |
|---|
| Clariant AG |
| Strahl & Pitsch, Inc. |
| BASF SE |
| Th. Goldschmidt AG |
| KahlWax GmbH & Co. KG |
| Croda International plc |
| Lonza Group AG |
| Eastman Chemical Company |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization asymmetries between hexane-based volume refiners and supercritical CO2 specialists create divergent cost floors across the European supply base. Swiss and German operators with captive extraction infrastructure capture margin premiums on cosmetic-grade output, while Rotterdam-based industrial processors absorb freight volatility on Brazilian Saccharum officinarum feedstock.
Pricing Analysis
Configured-to-order pricing for pharmaceutical and cosmetic grades commands substantial premiums over standard industrial-tier quotations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth rather than volume scale alone. Price differentiation rests on EMA validation status and supercritical-derived residual specifications. Cost compression in industrial-grade segments is intensifying because Brazilian carnauba wax alternatives undercut sugarcane wax in high-gloss coating applications. Food-grade buyers in German confectionery clusters exhibit the highest price sensitivity, while Swiss pharmaceutical formulators accept premium positioning for documented stability programs.
Supply Chain Analysis
Port congestion at Santos and currency volatility on the Brazil-Europe trade lane compress refining margins for feedstock-dependent operators. Raw material extraction concentrates in Brazil and India, with Saccharum officinarum leaf filtrates feeding European refiners through Rotterdam and Hamburg entry points. The supply chain draws from tropical cultivation zones outside the continent, exposing processors to freight cost fluctuations and import qualification protocols under REACH. Single-source vulnerability on Brazilian feedstock represents the dominant structural risk. Distribution runs through integrated refiner-direct contracts for volume cosmetic accounts, with distributor-mediated channels serving artisanal candle makers and small-batch compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ECHA registration timestamps and dossier completeness create switching costs that lock out unqualified importers.
For Market Incumbents: Shield formulation lock-in by accelerating EMA validation investments ahead of potential ECHA substance evaluation restrictions. Expand supercritical CO2 capacity in Swiss and German manufacturing clusters to capture premium-tier demand from L'Oréal-adjacent compounders. Carnauba wax price competition in industrial coatings threatens volume-tier margins. For New Entrants and Emerging Players: Lead with supercritical extraction technology repurposed from European hemp and hop processing infrastructure. Target Poland and Czech Republic personal care manufacturing clusters relocating from Western Europe, where qualified local wax suppliers remain scarce. Position on CSRD-compliant Scope 3 emissions documentation as the go-to-market angle for sustainability-audit-driven procurement teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors supercritical extraction specialists with regulatory dossier accumulation over hexane-based volume refiners facing stranded asset risk. Long-term viability hinges on ECHA registration completeness and EMA-certified equipment train separation. The acquisition target archetype combines botanical extraction infrastructure with dedicated analytical capabilities. Watch ECHA substance evaluation timelines for long-chain aliphatic esters as the inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables solvent-free processing that meets ANSM cosmetic-grade residual limits. |
| EMA Validation Investment | Secures multi-year stability documentation required by Swissmedic for pharmaceutical-tier supply. |
| Backward Integration into Feedstock | Reduces currency exposure on Brazilian Saccharum officinarum leaf filtrate imports. |
| CSRD Supply Chain Disclosure Program | Documents bio-based carbon credentials that synthetic wax alternatives cannot match. |
| Central European Greenfield Deployment | Anchors supply contracts with personal care formulators relocating to Poland and Czech Republic. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, EFSA food contact material approvals, and EU Green Deal policy documentation. Primary interviews engaged refinery operations directors, cosmetic formulation chemists at German and French personal care manufacturers, procurement leads at confectionery processors, and regulatory affairs specialists navigating REACH obligations. Secondary validation drew from SEC filings of listed chemical conglomerates, Cefic sector reports, and customs trade data on Saccharum officinarum-derived imports. Bottom-up capacity assessments triangulated against top-down demand modeling across certification tiers.
Segmentation dimensions modeled include grade tier (cosmetic, food, pharmaceutical, industrial), end-use application (personal care, pharmaceuticals, food coatings, candles, industrial uses), extraction technology (supercritical CO2 versus hexane-based), and regional production cluster (Germany, France, Switzerland, Italy, Netherlands). CAGRs were derived from regression analysis of historical qualification timelines and projected substitution rates across the analysis window. Industry-specific forecast inputs incorporated EMA validation queue lengths and EFSA approval trajectories for sugarcane wax in direct food contact.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal bio-based mandates or ECHA registration continuity would require recalibration. Forecasts reflect assumptions on REACH authorization timelines and carnauba wax supply expansion from Northeast Brazil. Regulatory restriction scenarios, feedstock crop failures in tropical cultivation zones, or breakthrough synthetic bio-wax technologies could materially revise trajectory projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Vulcanization Accelerators Market