
 Europe Residential Heat Pump Market | 2026-2036
Europe Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Heat Pump Market Insights
Multi-source component procurement is expanding across European heat pump supply chains as manufacturers buffer against semiconductor and compressor bottlenecks. Daikin Industries leverages its in-house inverter production to sustain margin control amid volatile electronics markets. Vaillant Group anchors its competitiveness through captive sheet-metal fabrication and regional distribution hubs in Germany and the Netherlands. NIBE Industrier specializes in modular hydronic interfaces that simplify installer integration across Nordic and Continental European climates.
A residential heat pump is a vapor-compression or thermodynamic device that extracts thermal energy from ambient air, ground, or water sources and transfers it indoors via a refrigerant cycle operating at coefficient-of-performance ratios typically between three and five. Its primary commercial purpose is to displace fossil-fuel combustion for space heating and domestic hot water in dwellings. Air source systems dominate unit volumes across Southern and Central Europe due to lower installed cost and minimal site disruption, while ground source configurations command premium positioning in new construction segments where borehole access is practical. Hybrid installations pairing heat pumps with existing boilers are gaining structural traction in renovation projects where building envelopes limit full electrification feasibility.
The EU Green Deal, F-Gas Regulation, and Ecodesign requirements collectively mandate minimum seasonal performance factors and phasedown of high-global-warming-potential refrigerants, directly conditioning product certification and market access across member states. EMA-aligned national regulators in France, Germany, and Italy enforce these standards through building permit linkages and subsidy eligibility gates. Stakeholders must monitor refrigerant platform transitions and installer certification gaps as decisive variables for competitive positioning in the next product cycle.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant platform timelines across European heat pump manufacturing, forcing R-410A phaseout commitments before 2027 and redirecting R&D investment toward lower-GWP alternatives. This regulatory pressure is consolidating supplier power around compressor and refrigerant technology leaders while reshaping certification requirements for installers across Germany, France, and Italy.
Growth Catalysts
- Building renovation subsidies:Germany's BEG federal funding program and France's MaPrimeRénov scheme now tie grant eligibility to heat pump installation, pulling forward replacement cycles for oil and gas boilers in single-family housing stock.
- District heating displacement:Municipal utilities in Poland and the Czech Republic are accelerating heat pump adoption as legacy coal-fired district networks face EU emissions compliance deadlines and carbon pricing exposure.
- Refrigerant transition mandates:The F-Gas Regulation's phasedown schedule is compressing product development cycles and creating first-mover advantages for manufacturers with R-290 and R-32 platforms already certified.
Market Restraints
- Copper and rare-earth volatility:Compressor manufacturing depends on neodymium magnet supply concentrated in Chinese processing facilities, exposing European assemblers to input cost swings and export restriction risk.
- Installer capacity constraints:Certified heat pump technician density in Southern Europe remains below deployment targets set by national building renovation plans, extending project timelines and inflating labor premiums.
- Building envelope limitations:Pre-1990 housing stock across Belgium and the Netherlands often lacks insulation depth for monobloc air-source systems at design temperatures, forcing hybrid configurations that dilute electrification benefits.
Strategic Opportunities
- Hybrid system penetration:Renovation projects in Austria and Switzerland are creating demand for bivalent heat pump-boiler combinations that optimize running costs across temperature bands while minimizing upfront envelope investment.
- Installer certification platforms:Digital training and remote commissioning tools are reducing time-to-certification for HVAC technicians, expanding addressable labor pools in underpenetrated Spanish and Portuguese markets.
- EU Green Deal alignment:Member state Recovery and Resilience Facility disbursements are channeling capital toward residential electrification, with Italy and Poland directing substantial allocations toward heat pump voucher programs.
Industry Challenges
- Refrigerant handling certification:The transition to flammable A3-class refrigerants requires updated safety training and equipment investment across the installer base, creating bottlenecks in markets where technician turnover is elevated.
- Grid integration complexity:Distribution network operators in rural Germany and France are imposing connection studies and upgrade cost allocations that extend project timelines and erode consumer economics for larger-capacity units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Heat Pump Market |
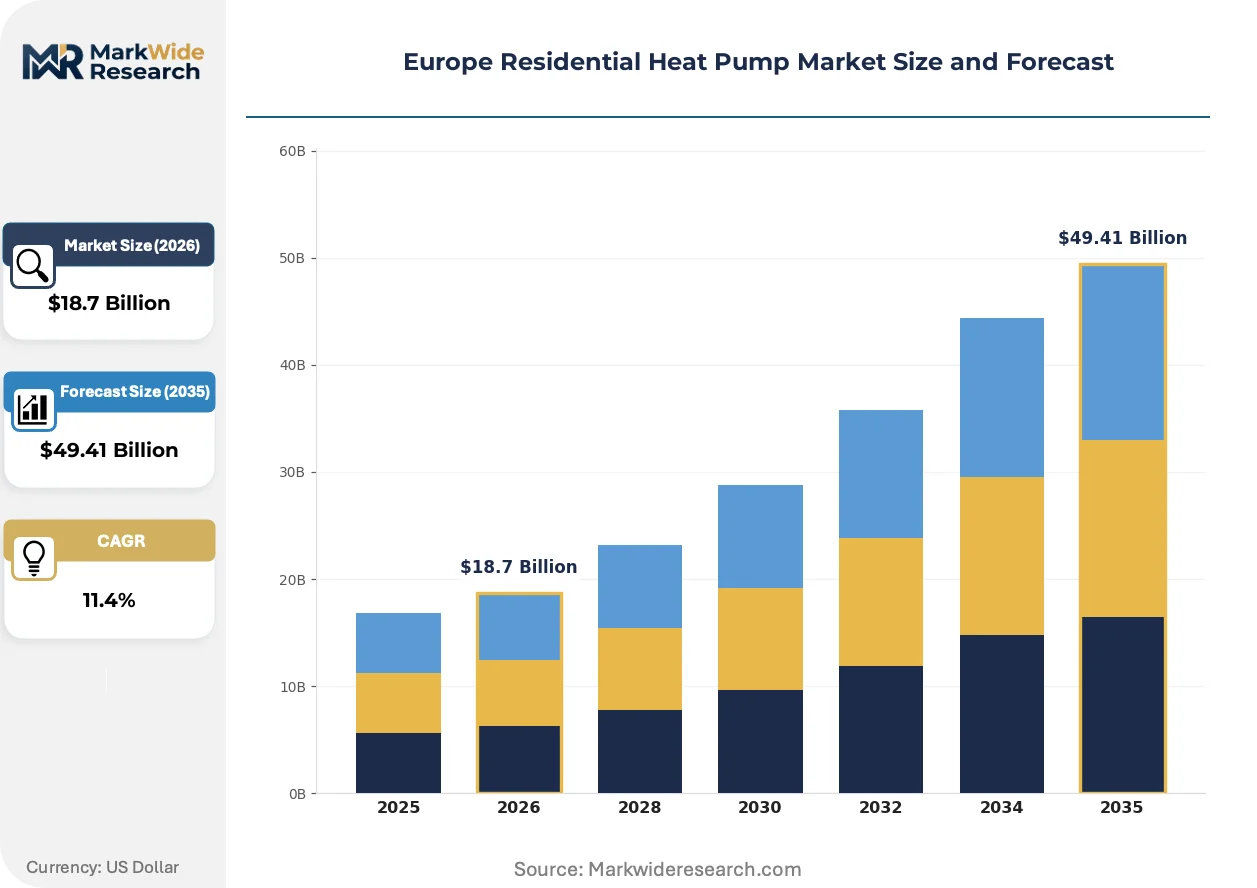
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Water Source, Hybrid Technology: Variable Refrigerant Flow, Thermoelectric, Heat Recovery, Scroll Compressor End User: Single-Family Homes, Multi-Family Units, Renovation Projects, New Constructions Installation: DIY, Professional, Retrofit, New Build |
| Companies Covered | Daikin Industries, Vaillant Group, NIBE Industrier, Viessmann Group, Mitsubishi Electric, Stiebel Eltron, Carrier Global Corporation, Johnson Controls International, The Danfoss Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Heat Pump Market Trends and Innovations
Refrigerant chemistry, control system architecture, and service delivery models are undergoing simultaneous transformation as manufacturers and utilities position for post-2027 regulatory compliance and demand-side flexibility monetization.
R-290 propane refrigerant is consolidating as the dominant platform for new residential heat pump development, offering GWP below 3 and thermodynamic performance superior to transitional R-32 blends. Nordic and German manufacturers are adopting R-290 for monobloc outdoor units ahead of 2027 F-Gas quota restrictions, compressing the competitive window for R-410A-dependent product lines and forcing smaller assemblers toward licensed compressor supply agreements.
The EU Ecodesign and Energy Labelling regulations are tightening minimum seasonal coefficient of performance requirements for space heating appliances sold in member states. These standards are eliminating entry-level fixed-speed compressor configurations from legal sale, redirecting volume toward variable-speed inverter platforms that command manufacturing complexity premiums but deliver operating cost advantages to end-users in high-utilization climates.
Aggregators and energy retailers are bundling heat pump installation with demand-response enrollment and dynamic electricity tariffs, displacing traditional equipment-only sales through installer networks. This model is concentrating volume in Germany and the Netherlands where regulatory frameworks enable grid flexibility compensation, shifting margin capture toward utilities and away from pure-play equipment distributors.
Europe Residential Heat Pump Market Segmentation
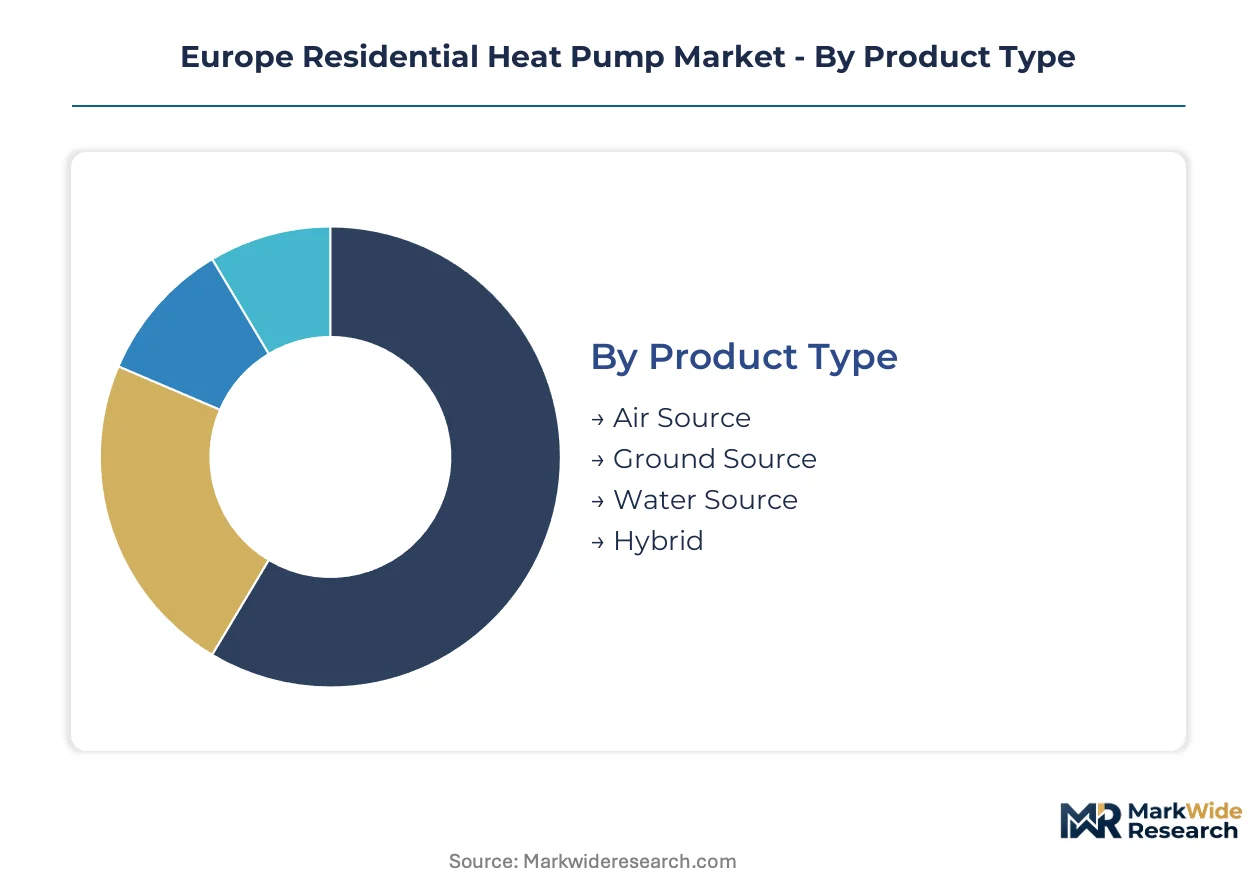
Segmentation in the Europe Residential Heat Pump Market reveals how technology choices, building types, and installation contexts shape procurement patterns. Distinct product configurations align with specific renovation subsidies and building envelope conditions across Germany, France, and Italy.
Product Type:
Standalone outdoor units dominate retrofit applications, while embedded ground-loop systems require deeper building integration during construction phases.
- Air Source:Monobloc and split configurations extract thermal energy from ambient air through finned evaporator coils. Demand concentrates in Southern and Central European renovation projects where drilling access is restricted and the EU Green Deal subsidies reduce payback periods for gas boiler replacements.
- Ground Source:Closed-loop borehole or horizontal collector systems leverage stable subsoil temperatures for superior seasonal performance factors. Installations cluster in new construction segments across Germany and the Netherlands where foundation work permits simultaneous ground-loop deployment.
- Water Source:Lake and river-based configurations utilize direct water-to-refrigerant heat exchange. Deployments track proximity to suitable water bodies in Alpine regions and Nordic countries.
- Hybrid:Bivalent systems combine heat pumps with retained fossil-fuel boilers for peak-load coverage. Adoption accelerates in Belgian and Dutch pre-1990 housing stock where envelope limitations prevent full electrification.
Volume placements concentrate in Air Source; the faster expansion belongs to Hybrid.
Technology:
Cost tier stratification separates premium inverter platforms from entry-level fixed-speed alternatives now restricted by Ecodesign minimums.
- Variable Refrigerant Flow:Inverter-driven compressor modulation matches output to dynamic heat loads across partial-load conditions. German and Italian manufacturers prioritize VRF architectures for their R-290 refrigerant compatibility and demand-response integration capabilities.
- Thermoelectric:Solid-state Peltier modules enable compact, refrigerant-free thermal transfer for niche low-capacity applications. Interest concentrates in auxiliary hot water preheating segments where simplicity outweighs efficiency penalties.
- Heat Recovery:Simultaneous heating and cooling circuits capture rejected thermal energy for domestic hot water or pool heating. Multi-family installations in France exploit this capability to improve project economics through energy cost allocation.
- Scroll Compressor:Orbiting scroll mechanisms deliver reliable compression across residential capacity ranges. Asian suppliers dominate scroll manufacturing, exposing European assemblers to rare-earth magnet supply chain exposure.
Scroll Compressor platforms retain the largest installed base; VRF architectures are climbing the fastest.
End User:
Customer type determines system sizing, financing mechanisms, and subsidy access pathways across national renovation programs.
- Single-Family Homes:Detached dwellings with individual heating circuits represent the core addressable market. Germany's BEG program and France's MaPrimeRénov scheme target this segment with grant structures tied to oil and gas boiler decommissioning.
- Multi-Family Units:Shared thermal distribution systems require centralized or cascaded heat pump configurations. Deployment faces hurdles in split-incentive arrangements between landlords and tenants across Belgian and Austrian rental markets.
- Renovation Projects:Retrofit installations must accommodate existing emitter temperatures and hydraulic interfaces. Polish and Czech district heating displacement creates substantial pull as coal network phaseouts accelerate.
- New Constructions:Greenfield builds integrate heat pumps from design stage with optimized low-temperature emitters. Nordic building codes mandate near-zero energy standards that favor ground-source and air-source integration.
Renovation Projects absorb the highest unit volumes; New Constructions show the steepest expansion trajectory.
Installation:
Professional certification requirements and grid connection procedures create divergent margin structures across execution modes.
- Professional:Certified HVAC technicians execute full design, commissioning, and warranty coverage. Labor capacity constraints in Southern Europe extend project timelines and inflate installation premiums.
- Retrofit:Adaptation of existing hydronic systems to heat pump operating characteristics. Building envelope limitations in Belgian and Dutch housing stock force hybrid configurations.
- DIY:Self-installation of monobloc units by technically competent homeowners. Regulatory frameworks in Germany and France restrict warranty eligibility and subsidy access for non-certified work.
- New Build:Coordinated installation during construction phase with integrated controls and metering. Netherlands and Denmark lead penetration where building regulations synchronize heat pump mandates with grid flexibility requirements.
Professional installation dominates current placements; New Build is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-family renovation subsidies concentrate demand in Germany, France, and Italy, while district heating displacement accelerates uptake across Central European coal-phaseout zones. National building codes and EU Green Deal disbursements create divergent deployment timelines across member states.
Germany
Oil and gas boiler replacement cycles dominate residential procurement, with BEG federal funding tying grant eligibility directly to heat pump installation. The Federal Office for Economic Affairs and Export Control enforces subsidy compliance through energy efficiency audits. Manufacturing clusters in North Rhine-Westphalia and Bavaria host compressor assembly and refrigerant platform development facilities serving renovation contractors.
France
MaPrimeRénov scheme structures grant access around household income tiers and building performance thresholds, channeling volume toward air-source retrofits in peri-urban single-family stock. The Directorate General for Energy and Climate coordinates regional prefecture implementation of EU Ecodesign standards. Industrial concentration around Lyon and Grenoble supports heat pump production for Alpine climate specifications.
Italy
Superbonus tax credits drive multi-family and single-family renovation pipelines simultaneously, though administrative complexity extends project timelines. The National Agency for Energy Services certifies installer competence under EU F-Gas handling requirements. Northern manufacturing corridors in Lombardy and Veneto supply hydronic interface components for Mediterranean climate adaptations.
Poland
Municipal coal-fired district network phaseouts create structural demand for individual building electrification in urban residential zones. The Energy Regulatory Office imposes connection standards that align with EU Green Deal building renovation targets. Warsaw and Krakow metropolitan areas concentrate installer training programs and equipment distribution networks.
Netherlands
Pre-1990 housing stock limitations force hybrid heat pump-boiler configurations that optimize running costs across temperature bands. The Netherlands Enterprise Agency administers ISDE subsidy schemes linking grant levels to seasonal performance factor thresholds. Rotterdam-The Hague corridor hosts testing facilities for low-temperature emitter compatibility with air-source systems.
Europe Residential Heat Pump Market Competitive Landscape
Refrigerant platform transitions dominate the current landscape as manufacturers compress R-410A phaseout timelines ahead of 2027 F-Gas quota restrictions. The vendor base stratifies across three tiers: integrated HVAC conglomerates with captive compressor supply, regional heating specialists with installer network control, and modular component assemblers dependent on licensed technology. Two competitive moves define positioning: backward integration into inverter electronics and refrigerant handling certification platforms that lock installer loyalty.
Among Japanese and European integrated manufacturers, Daikin Industries and Mitsubishi Electric exemplify the conglomerate archetype with in-house production spanning compressors and control systems. Vaillant Group and NIBE Industrier occupy the regional specialist tier, anchoring competitiveness through captive fabrication and Nordic climate engineering expertise. These four entities represent divergent responses to supply chain volatility—electronics integration versus manufacturing proximity.
| Leading Market Players |
|---|
| Daikin Industries |
| Vaillant Group |
| NIBE Industrier |
| Viessmann Group |
| Mitsubishi Electric |
| Stiebel Eltron |
| Carrier Global Corporation |
| Johnson Controls International |
| The Danfoss Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap manufacturers across Germany and Italy anchor supply discipline through conservative balance-sheet management and selective capacity expansion. Their financing patterns limit aggressive price competition while concentrating procurement power around captive sheet-metal fabrication and regional distribution hubs. The EU Green Deal subsidy pipelines prop end-user demand, yet compressor and semiconductor bottlenecks compress margin recovery timelines for assemblers without in-house inverter production.
Pricing Analysis
Volume placements concentrate in economy-tier air-source configurations while margin capture clusters in premium inverter platforms and hybrid bivalent systems. Price differentiation hinges on seasonal performance factor certification tiers and after-sales service bundling through authorized installer networks. Pricing pressure stems from rare-earth magnet cost volatility in Chinese processing facilities, eroding assembler margins on scroll compressor platforms. Single-family renovation contractors in France and Germany exhibit highest price sensitivity, whereas multi-family project developers in Italy prioritize performance guarantees over upfront equipment costs.
Supply Chain Analysis
Reverse-logistics flows for refrigerant recovery and compressor refurbishment remain underdeveloped across European heat pump markets, creating stranded asset risk as R-410A phaseout accelerates. Manufacturing concentration centers on Germany, Italy, and China, with Asian suppliers dominating scroll compressor and inverter electronics production. Supply chains rest on neodymium magnet feedstock from Chinese processing facilities, copper coil stock from German mills, and R-290 refrigerant from regional European chemical plants. Single-source vulnerability in rare-earth processing exposes assemblers to export restriction risk. Distribution runs through authorized HVAC wholesaler networks and direct-to-installer channels controlled by regional heating specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer capacity constraints across Southern Europe prop pricing power for certified technicians, creating a supply-constrained growth environment where equipment availability and labor certification gates determine deployment velocity.
For Market Incumbents: Deepen captive inverter electronics production to buffer against semiconductor lead-time volatility and sustain margin control. Anchor installer loyalty through refrigerant handling certification platforms that lock technician networks ahead of R-290 transition deadlines. Defend position against modular component assemblers by accelerating R-290 platform certification and regional distribution hub density in Poland and Czech Republic renovation corridors. For New Entrants and Emerging Players: Digital direct-installer marketplaces offer the lowest-friction route to bypass incumbent wholesaler control and capture price-transparent procurement flows. Target underpenetrated Spanish and Portuguese markets where certified technician density lags national building renovation targets. Pursue white-label manufacturing partnerships with Asian compressor suppliers to compress product development cycles for R-32 and R-290 platforms. For Investors and Strategic Acquirers: F-Gas quota allocation announcements from the European Commission are the leading indicator that refrigerant platform transitions will consolidate supplier power around certified manufacturers. The five-to-ten year viability window favors acquisition targets with captive hydronic interface engineering and established installer certification programs. Monitor EU Recovery and Resilience Facility disbursement schedules for member states directing capital toward heat pump voucher programs as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| R-290 Refrigerant Platform Certification | First-mover certification under EU F-Gas Regulation secures quota-constrained market access ahead of 2027 deadlines. |
| Installer Certification Platform Investment | Digital training and remote commissioning tools expand addressable labor pools in Spanish and Portuguese markets. |
| Backward Integration into Inverter Electronics | In-house semiconductor procurement buffers margin erosion from volatile electronics spot markets and Chinese export restrictions. |
| Hybrid System Portfolio Expansion | Bivalent heat pump-boiler combinations capture Belgian and Dutch renovation demand where envelope limitations prevent full electrification. |
| Regional Distribution Hub Density | Proximity to Poland and Czech Republic district heating displacement corridors reduces logistics premiums and installation timeline risk. |
Research Methodology
Trade association filings, EU regulatory databases, and national customs records formed the secondary backbone for volume and value estimation. Primary interviews with heat pump manufacturing executives, HVAC installer network managers, and building renovation subsidy administrators validated procurement patterns and pricing dynamics. The analysis triangulated bottom-up equipment shipment data with top-down energy transition spending allocations across member state Recovery and Resilience Facility frameworks.
Bottom-up modeling aggregated unit placements by product type, technology tier, and installation mode across Germany, France, Italy, Poland, and Netherlands. Top-down validation cross-referenced national building renovation plan targets with EU Green Deal disbursement schedules. Segmentation dimensions spanned air-source, ground-source, water-source, and hybrid configurations; variable refrigerant flow, thermoelectric, heat recovery, and scroll compressor technologies; and single-family, multi-family, renovation, and new construction end-use contexts. CAGRs were derived from subsidy pipeline visibility, refrigerant platform transition timelines, and installer capacity expansion trajectories.
The model holds under sustained EU Green Deal funding and F-Gas Regulation enforcement; deviation in rare-earth export restrictions or grid connection upgrade cost allocations would shift deployment timelines. Forecasts reflect assumptions regarding subsidy continuity, refrigerant handling certification velocity, and distribution network operator connection study procedures. Practitioners should monitor European Commission F-Gas quota announcements and member state Recovery and Resilience Facility disbursement schedules for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Thermostatic Faucet Market