
 Global Tunnel and Metro Ventilation Market | 2026-2036
Global Tunnel and Metro Ventilation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tunnel and Metro Ventilation Market Outlook
European fan manufacturing capacity is hardening as producers scale output for transalpine rail projects. TLT-Turbo GmbH leverages its axial fan engineering heritage to anchor contracts across Central European tunnel corridors. Howden Group sustains long-term positions in high-pressure ventilation through backward integration into impeller casting. Systemair AB competes on modular platform designs that reduce installation complexity for metro operators.
Tunnel and metro ventilation encompasses engineered airflow systems designed to maintain air quality, control temperature, and enable smoke evacuation in enclosed underground transport infrastructure, typically achieving air exchange rates of 100–150 cubic meters per second in main tunnel bores. These installations serve the critical commercial purpose of protecting passenger safety and ensuring continuous operations during fire events or equipment failures. Mechanical system configurations lead installed value across metro tunnel applications where natural airflow proves insufficient, while jet fan technology represents the fastest-growing segment as operators retrofit aging road tunnels with longitudinal ventilation schemes. Pressure relief and hybrid designs command margin premiums in deep-bore railway stations where space constraints limit traditional ducting.
Regulatory frameworks from the EU F-Gas Regulation, US OSHA tunnel safety standards, and China's GB standards for urban rail transit collectively mandate minimum airflow velocities and smoke extraction capacities, directly shaping equipment specifications and procurement criteria. Japan's METI energy efficiency guidelines for building services equipment extend to metro ventilation, pushing suppliers toward variable-speed drives and demand-controlled operation. Stakeholders must monitor divergence between regional fire safety certification requirements as project specifications increasingly bar equipment not qualified under multiple national standards.
Market Dynamics
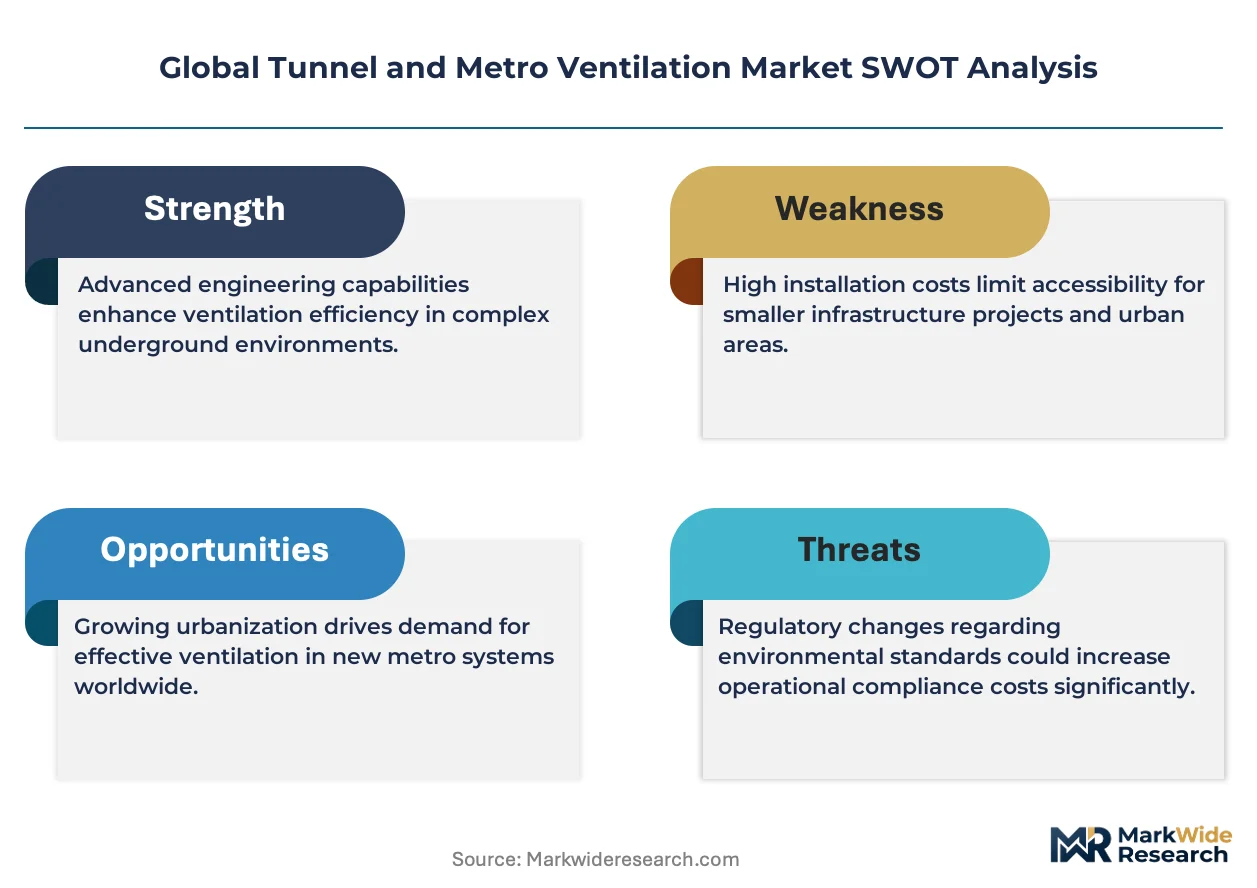
Jet fan retrofits in aging road tunnels are compressing replacement cycles as operators face simultaneous mandates for fire safety upgrades and energy efficiency compliance. This dual-pressure environment is restructuring procurement priorities toward modular, digitally-integrated ventilation architectures.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant-based cooling restrictions in underground stations accelerate demand for purely mechanical ventilation and heat rejection systems. Equipment suppliers report specification changes across German and Austrian rail projects.
- China's GB 50157 urban rail standards:Updated smoke extraction velocity mandates require higher-capacity axial fans in new metro lines. Beijing and Shanghai transit authorities are tendering for upgraded ventilation packages.
- Longitudinal ventilation schemes:Road tunnel operators in Italy and Norway favor jet fan arrays over traditional transverse ducting for bore lengths under three kilometers. Installation cost advantages drive specification shifts.
Market Restraints
- Specialized impeller casting capacity:High-pressure aluminum alloy foundry output concentrates in Germany and Japan. Lead times for large-diameter backward-curved impellers now exceed fourteen months.
- Copper winding cost volatility:Electric motor raw material exposure creates margin pressure for fan OEMs. Variable-speed drive integration partially offsets efficiency losses but adds component complexity.
- Deep-bore railway station constraints:Physical space limitations in Swiss and Japanese alpine tunnels restrict ducting geometry options. Hybrid ventilation designs command engineering premiums that compress addressable volume.
Strategic Opportunities
- India's urban rail expansion:Delhi Metro Rail Corporation and Bangalore Metro are specifying fire-rated ventilation for Phase IV extensions. Domestic manufacturing incentives under PLI schemes attract component localization.
- Digital twin integration:Computational fluid dynamics modeling converges with real-time sensor networks. Operators in Singapore and Dubai pilot predictive airflow optimization for energy arbitrage.
- US OSHA tunnel safety standard updates:Proposed particulate monitoring enhancements would mandate continuous air quality verification. This creates specification pull for sensor-integrated ventilation management platforms.
Industry Challenges
- Computational fluid dynamics expertise scarcity:Tunnel-specific thermal and smoke movement modeling requires specialized simulation talent. Engineering consultancies in France and Switzerland report recruitment bottlenecks for qualified analysts.
- Multi-standard certification complexity:Equipment qualified under China's GB standards requires separate fire safety testing for EU transalpine projects. Dual-qualification timelines extend bid-to-award cycles by eight to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tunnel and Metro Ventilation Market |
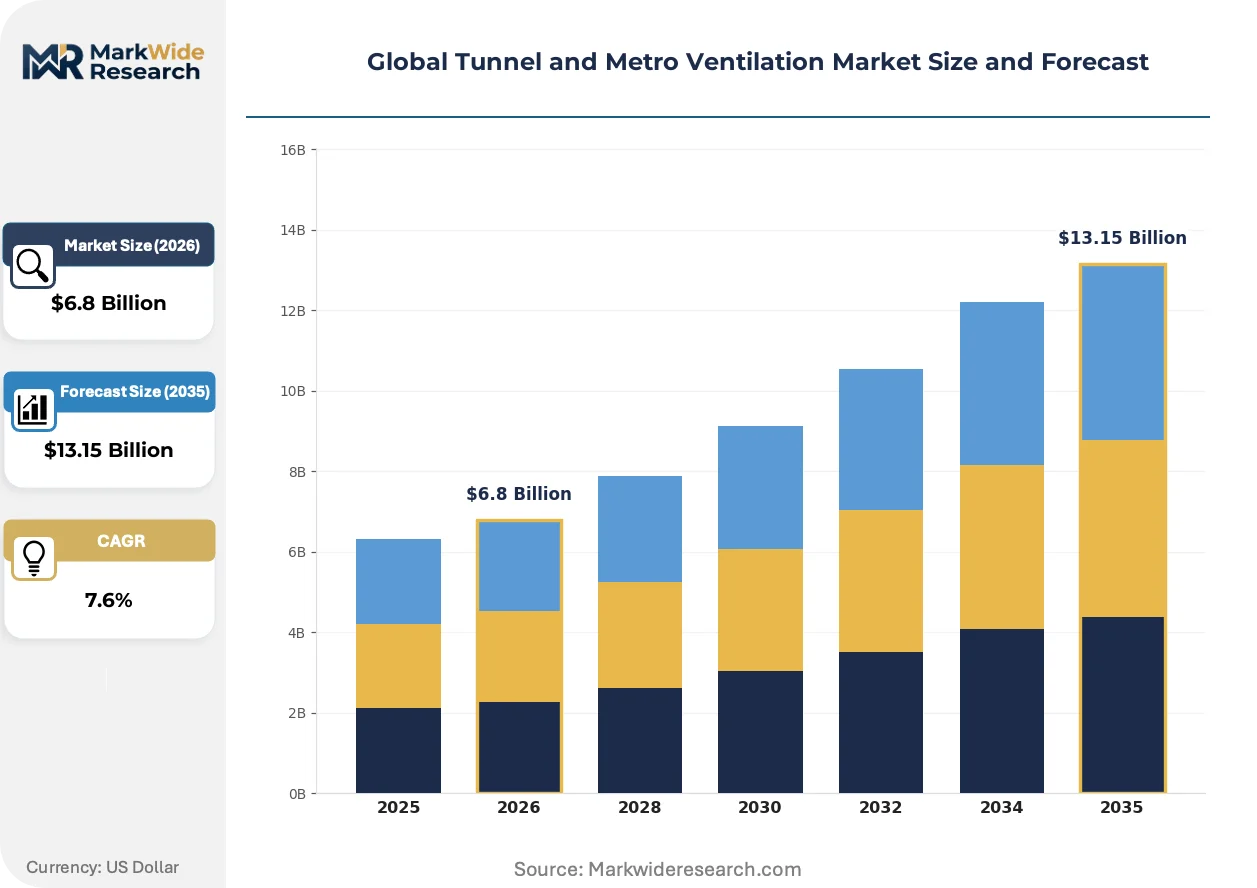
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Mechanical, Natural, Hybrid, Pressure Relief Application: Metro Tunnels, Road Tunnels, Underground Parking, Railway Stations Technology: Axial Fans, Centrifugal Fans, Jet Fans, Smoke Control Systems End User: Government, Transportation Authorities, Construction Firms, Private Operators |
| Companies Covered | Systemair AB, TLT-Turbo GmbH, Howden Group, Zitron SA, Epiroc AB, FläktGroup, ABB Ltd., Siemens AG, TROX GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tunnel and Metro Ventilation Market Strategic Shifts
Active airflow management is migrating from fixed-speed mechanical systems toward adaptive, sensor-driven architectures that respond to real-time traffic density and thermal loads. This shift redefines value capture from hardware supply toward operational optimization services.
Computational fluid dynamics software is converging with edge computing hardware to enable localized smoke path prediction without centralized data center dependency. Metro operators in Seoul and London are piloting these distributed architectures for sub-second emergency response coordination. The technology is converging with legacy building management systems through standardized BACnet protocols, reducing integration friction for brownfield station upgrades.
Japan's METI energy efficiency guidelines for building services equipment now explicitly cover metro ventilation load profiles. The framework mandates variable-speed drive deployment and demand-controlled ventilation based on passenger counting sensors. Deep-bore stations in Osaka and Nagoya are retrofitting fixed-speed fan arrays to comply with fiscal year reporting requirements.
Lifecycle service contracting is displacing traditional equipment procurement in Nordic tunnel projects. Norwegian and Finnish road authorities now specify availability-based payment structures where ventilation system performance guarantees determine contractor compensation. This model concentrates risk with integrators capable of predictive maintenance analytics and remote diagnostics capability.
Global Tunnel and Metro Ventilation Market Segmentation
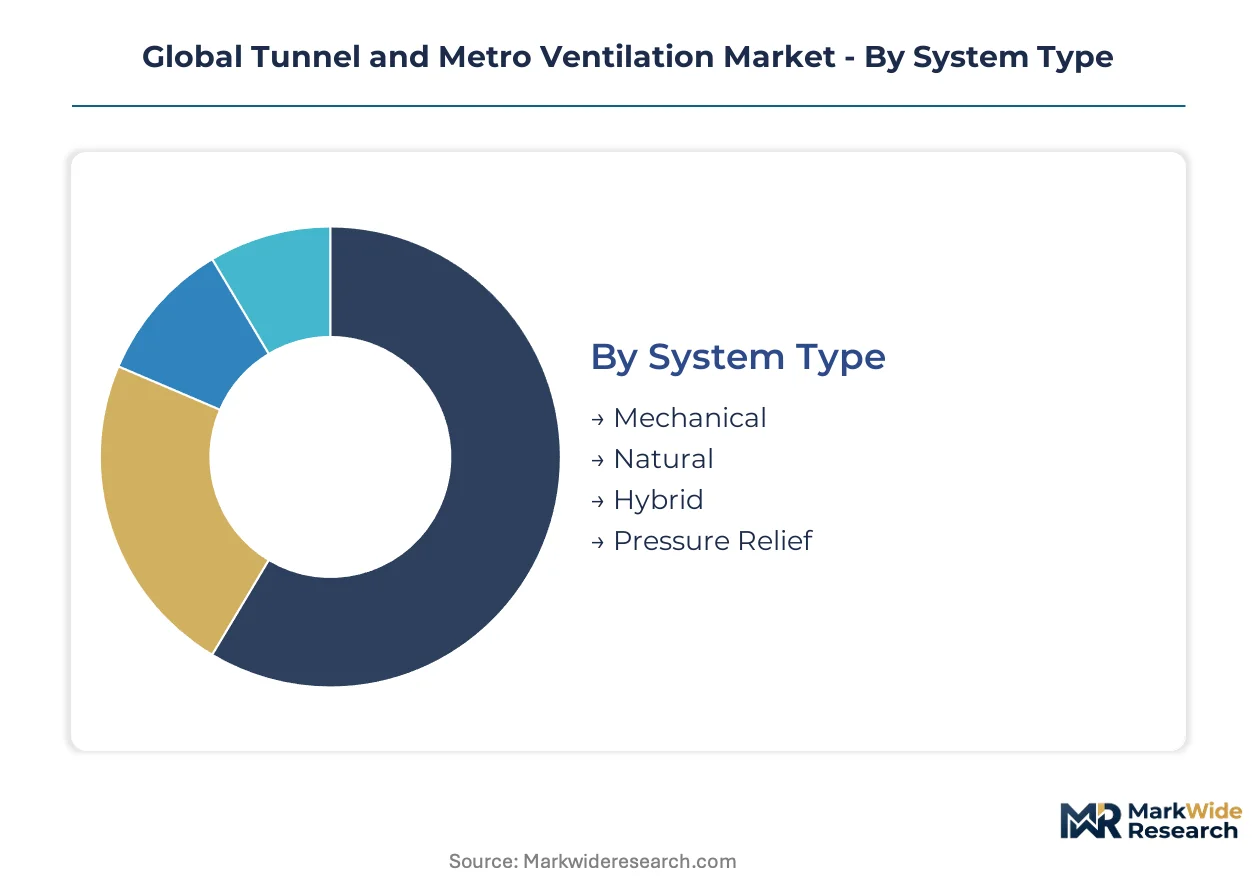
Tunnel and metro ventilation procurement decisions hinge on bore geometry, regulatory fire safety mandates, and lifecycle cost models. Segmentation reveals how specification choices diverge between new rail infrastructure and aging road tunnel retrofits.
System Type:
Capital intensity and space constraints drive buyer selection between fixed mechanical plant and passive architectural solutions.
- Mechanical:Engineered fan arrays and ducting networks deliver controlled airflow rates of 100–150 cubic meters per second in main tunnel bores. Beijing and Shanghai metro authorities specify mechanical systems for deep-bore stations where natural ventilation proves inadequate.
- Natural:Buoyancy-driven airflow through shaft arrays and portal geometry eliminates energy consumption but requires extended tunnel gradients. Norwegian road tunnel operators favor natural systems for bore lengths under 800 meters with favorable topography.
- Hybrid:Combined mechanical-natural architectures balance operational flexibility with energy efficiency compliance. Swiss alpine railway stations deploy hybrid designs where space constraints limit full mechanical plant installation.
- Pressure Relief:Dedicated pressure-equalization chambers and relief dampers manage piston effects from high-speed train passage. Japanese Shinkansen extension projects specify pressure relief for tunnels exceeding 10 kilometers in length.
Volume sits with Mechanical systems; growth tilts toward Hybrid configurations.
Application:
End-use environment dictates smoke extraction velocity requirements and equipment redundancy levels.
- Metro Tunnels:Continuous passenger occupancy mandates redundant ventilation trains and emergency smoke extraction capacity. Delhi Metro Rail Corporation Phase IV extensions specify fire-rated ventilation packages with 90-minute survival ratings.
- Road Tunnels:Intermittent vehicle traffic enables simpler longitudinal ventilation schemes with jet fan arrays. Italian Autostrade tenders favor jet fan retrofits for twin-bore highway tunnels under three kilometers.
- Underground Parking:Carbon monoxide monitoring drives demand-controlled ventilation with variable-speed fan operation. Dubai commercial developments integrate parking ventilation with district cooling plant heat rejection.
- Railway Stations:Deep-bore station platforms require platform screen door integration and piston wind management. London Crossrail stations deploy pressure-stabilized ventilation for 24 trains per hour throughput.
Metro Tunnels command the largest installed base; Road Tunnel retrofits are expanding most quickly.
Technology:
Impeller aerodynamics and motor efficiency differentiate equipment performance in high-duty-cycle applications.
- Axial Fans:Direct airflow parallel to shaft axis achieves high volume flow rates at moderate pressure rise. China's GB 50157 updated standards drive specification of higher-capacity axial fans in new metro lines.
- Centrifugal Fans:Radial impeller configurations generate elevated static pressure for ducted distribution networks. German transalpine rail projects specify backward-curved centrifugal designs for station HVAC integration.
- Jet Fans:Thrust-based longitudinal ventilation eliminates ducting infrastructure in constrained bores. Norwegian and Finnish road authorities specify jet fan arrays for availability-based maintenance contracts.
- Smoke Control Systems:Dedicated extraction trains and dampers interface with fire detection networks for emergency response. Singapore MRT pilots predictive smoke path modeling through distributed edge computing architectures.
Axial Fans retain volume leadership; Jet Fans gain share fastest among retrofit applications.
End User:
Procurement authority determines specification stringency, qualification requirements, and contract structure preferences.
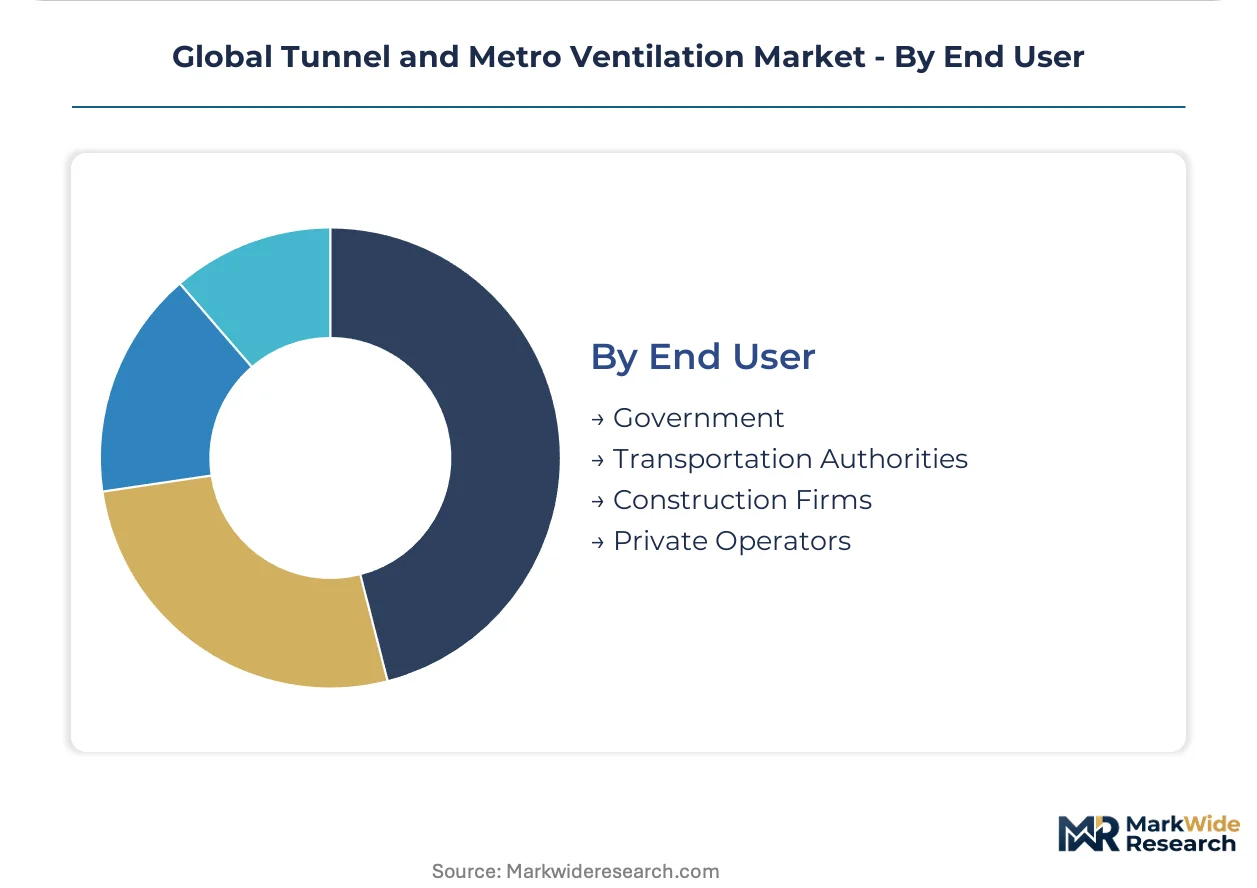
- Government:National infrastructure ministries mandate multi-standard equipment qualification and extended warranty terms. EU transalpine projects require simultaneous GB and CE fire safety certification.
- Transportation Authorities:Operating agencies prioritize lifecycle cost optimization and predictive maintenance integration. Seoul Metro deploys sensor-integrated ventilation management for real-time energy arbitrage.
- Construction Firms:EPC contractors favor modular platform designs that reduce installation complexity and site labor exposure. Bangalore Metro Phase IV specifications emphasize plug-and-play fan array deployment.
- Private Operators:Concession holders specify availability-based payment structures linking contractor compensation to system performance guarantees. Nordic tunnel projects concentrate risk with integrators capable of remote diagnostics.
Transportation Authorities dominate current procurement volume; Private Operators are climbing the fastest as concession models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-pressure aluminum alloy foundry output concentrates in Germany and Japan. Lead times for large-diameter backward-curved impellers now exceed fourteen months. This supply-side constraint shapes procurement timelines across tunnel corridors worldwide.
China
Beijing and Shanghai transit authorities are tendering for upgraded ventilation packages under GB 50157 urban rail standards. Updated smoke extraction velocity mandates require higher-capacity axial fans in new metro lines. The Yangtze River Delta corridor anchors manufacturing capacity for impeller casting and motor winding components serving domestic and export demand.
Germany
TLT-Turbo GmbH leverages axial fan engineering heritage to anchor contracts across Central European tunnel corridors. The EU F-Gas Regulation phase-down accelerates demand for purely mechanical ventilation systems across German and Austrian rail projects. Bavaria and Baden-Württemberg host specialized foundry clusters supplying high-pressure impellers for transalpine applications.
United States
Proposed OSHA tunnel safety standard updates would mandate continuous air quality verification through particulate monitoring enhancements. This creates specification pull for sensor-integrated ventilation management platforms. The Northeast Corridor and California transit authorities pilot predictive airflow optimization for energy arbitrage in brownfield station upgrades.
India
Delhi Metro Rail Corporation and Bangalore Metro specify fire-rated ventilation for Phase IV extensions. Domestic manufacturing incentives under PLI schemes attract component localization for motor winding and control systems. The Delhi-NCR and Karnataka clusters concentrate EPC contractor activity for modular fan array deployment.
Japan
METI energy efficiency guidelines for building services equipment now explicitly cover metro ventilation load profiles. Deep-bore stations in Osaka and Nagoya retrofit fixed-speed fan arrays to comply with fiscal year reporting requirements. The Kansai and Chubu regions concentrate CFD modeling expertise for tunnel-specific thermal and smoke movement simulation.
Global Tunnel and Metro Ventilation Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital integration and lifecycle service contracting. The vendor base spans European engineering heritage firms, Nordic modular platform specialists, and diversified industrial conglomerates with ventilation divisions. Two strategic archetypes dominate: axial fan engineering specialists leveraging casting integration, and building automation integrators converging HVAC with fire safety systems. Competitive moves concentrate on backward integration into impeller foundry capacity and predictive maintenance analytics capability.
Within the European engineering tier, TLT-Turbo GmbH and Systemair AB exemplify divergent positioning strategies. Howden Group anchors the high-pressure ventilation segment through captive supply of precision-cast impellers. Zitron SA and FläktGroup occupy positions bridging equipment fabrication with system integration. ABB Ltd. and Siemens AG represent the automation convergence archetype, embedding ventilation control within broader building management architectures. TROX GmbH sits within the ducting and air distribution specialist tier serving premium specification segments.
| Leading Market Players |
|---|
| Systemair AB |
| TLT-Turbo GmbH |
| Howden Group |
| Zitron SA |
| Epiroc AB |
| FläktGroup |
| ABB Ltd. |
| Siemens AG |
| TROX GmbH |
| Others |
Value Chain & Pricing Dynamics
Transit authority mandates for multi-standard fire safety certification are compressing supplier qualification timelines and forcing foundry investments that reshape cost structures across equipment tiers. Buyers now bundle extended warranty terms with predictive maintenance clauses, unbundling pure hardware procurement from lifecycle service obligations.
Pricing Analysis
Extended warranty and remote diagnostics bundling now separates premium ventilation integrators from standard equipment vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification breadth—dual GB and CE qualification commands 15-20% premiums over single-standard equipment. Cost compression in mid-tier axial fan arrays is intensifying because copper winding volatility and foundry capacity constraints squeeze OEM margins. Transportation authorities in Nordic markets exhibit lowest price sensitivity due to availability-based contracting models, while construction firms in India's Phase IV metro extensions remain most cost-conscious.
Supply Chain Analysis
Dual-sourcing requirements for critical impeller castings now mandate German and Japanese foundry qualification for transalpine and Shinkansen projects alike. High-pressure aluminum alloy production concentrates in Bavaria, Baden-Württemberg, and the Chubu region, with copper windings drawing from Chinese and Chilean concentrate flows. Single-source vulnerability in large-diameter backward-curved impellers extends procurement timelines when demand surges across simultaneous rail corridors. Distribution runs through EPC contractor networks for greenfield metro deployments, while aftermarket service flows direct to transportation authority technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in tunnel ventilation is becoming a race to secure captive foundry capacity and embedded digital service platforms. Players lacking upstream impeller casting integration or downstream predictive analytics capability face margin compression as procurement shifts toward lifecycle contracting.
For Market Incumbents: Hedge against modular platform specialists by securing long-term offtake agreements with German and Japanese foundry clusters. Accelerate backward integration into aluminum alloy casting capacity before copper volatility and lead time extensions erode margin position in high-pressure centrifugal fan segments. Lock in dual GB-CE certification pipelines to defend against Chinese OEMs expanding into EU transalpine tenders. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down in Germany and Austria opens a window for purely mechanical ventilation specialists without refrigerant-based cooling exposure. Target India's PLI-backed component localization for motor winding and control system manufacturing as the most penetrable geography. Pursue digital twin integration partnerships with Singapore and Dubai metro operators as the primary go-to-market angle, bypassing hardware-only procurement channels. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive foundry capacity and CFD modeling talent. Long-term viability across the 5-10 year horizon rests on securing impeller casting assets in Germany or Japan rather than pure-play software or service layer acquisitions. Watch for OSHA tunnel safety standard finalization as the inflection signal—particulate monitoring mandates would accelerate sensor-integrated platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive aluminum alloy casting in Bavaria secures impeller supply for transalpine rail contracts. |
| Digital Twin Platform Development | CFD-edge computing convergence enables real-time smoke path prediction for Seoul Metro pilots. |
| Multi-Standard Certification Investment | Simultaneous GB and CE qualification compresses bid-to-award cycles for EU-China corridor projects. |
| Lifecycle Service Contracting Pivot | Availability-based payment structures align contractor compensation with Nordic tunnel authority performance metrics. |
| Predictive Maintenance Analytics Buildout | Remote diagnostics capability concentrates risk with integrators in Norwegian road authority concession models. |
Study Parameters
Multi-period observation of tender award patterns, foundry capacity utilization, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with ventilation system procurement managers at transportation authorities, EPC contractor technical directors, foundry operations leads, and fire safety engineering consultants. Secondary validation drew from EU F-Gas Regulation implementation reports, China's GB 50157 standard revision documents, Japan METI energy efficiency filings, and OSHA tunnel safety docket records. Bottom-up equipment shipment tracking and top-down infrastructure investment pipeline analysis were triangulated to cross-verify volume estimates.
Input-output matrices mapped fan system specifications to metro line construction schedules and road tunnel retrofit programs across the projection horizon. Segmentation modeling incorporated system type, application environment, impeller technology, and end-user procurement authority dimensions. CAGRs were derived from equipment replacement cycle compression rates and infrastructure investment trajectories rather than extrapolated trend lines. Industry-specific forecast inputs included aluminum alloy foundry lead time surveys and copper LME forward curve integration.
The model assumes a particular technology adoption path; alternative pathways for distributed edge computing smoke detection would alter the outlook if latency requirements shift toward centralized architectures. Forecasts reflect documented assumptions regarding regulatory implementation pacing and foundry capacity expansion schedules. Deviation in OSHA standard finalization timing or EU F-Gas phase-down acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Roof Vents Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Marine HVAC Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Aeration System Market
HVAC Systems
South Korea Commercial HVAC Market