
 Saudi Arabia Patient Monitoring Market | 2026-2036
Saudi Arabia Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Patient Monitoring Market Analytics
Market Context
Saudi Arabia is narrowing the gap between installed monitoring capacity and bed expansion targets across its Ministry of Health facilities. Philips Healthcare leverages deep channel relationships with Saudi hospital groups to sustain equipment refresh cycles. GE Healthcare anchors its position through localized service infrastructure and training academies in Riyadh. Siemens Healthineers differentiates via advanced hemodynamic monitoring suites tailored for cardiac catheterization labs in King Faisal Specialist Hospital and similar tier-one institutions.
Technical Definition and Segment Structure
Patient monitoring encompasses integrated systems that acquire, process, display, and alarm on physiological parameters including ECG, SpO2, invasive blood pressure, and respiratory rate through multi-parameter bedside units and distributed telemetry networks. These systems serve primarily to detect clinical deterioration, guide therapeutic intervention, and reduce preventable adverse events in acute and post-acute care settings. Bedside monitors occupy the largest revenue pool given mandatory deployment in ICU and step-down units, while remote patient monitors represent the fastest-expanding category as SFDA clears more cloud-connected devices for home deployment. Wearable devices command premium pricing where continuous ambulatory ECG and arrhythmia detection integrate with hospital electronic medical record systems.
Regulatory Framework and Outlook
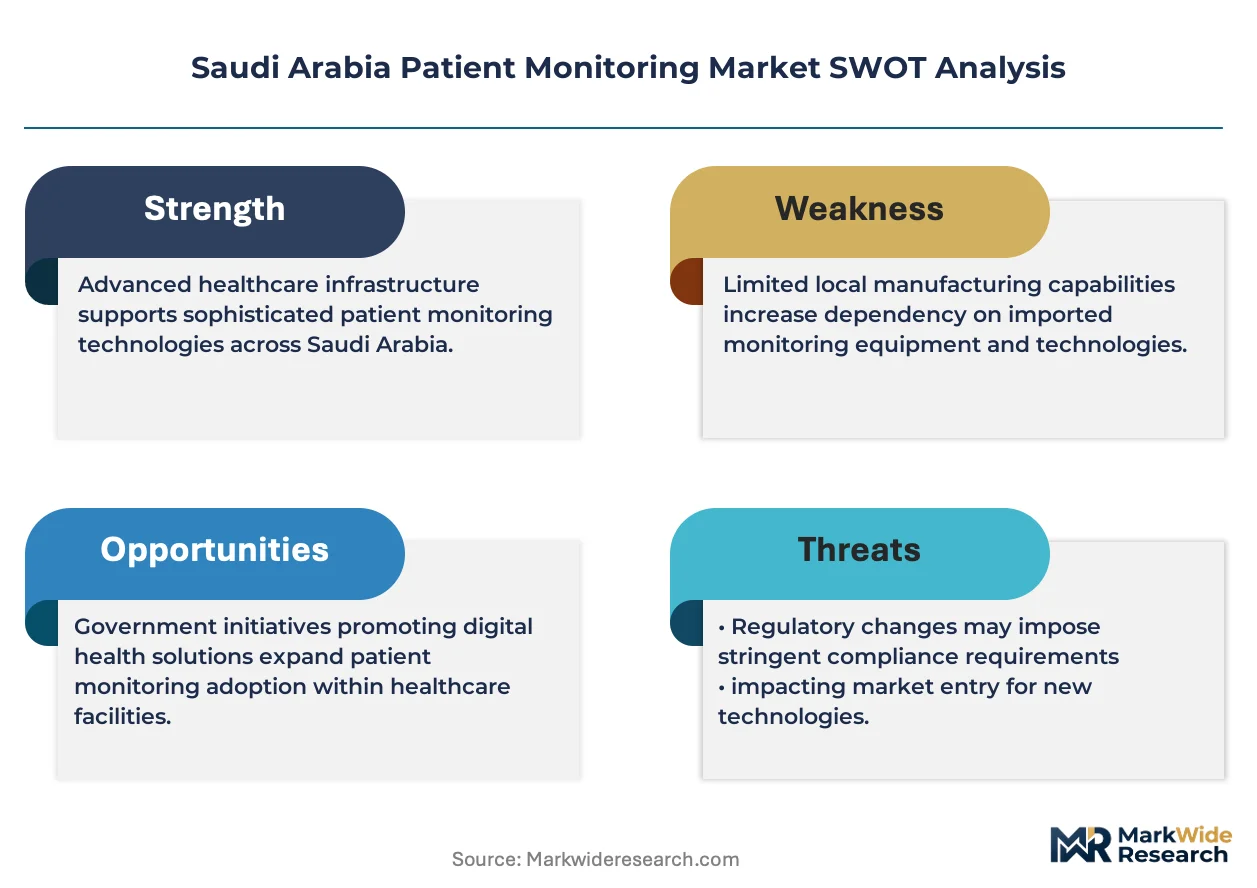
SFDA medical device registration requirements, MOHAP technical standards for connected health equipment, and NPHIES interoperability mandates collectively shape product design and market access timelines for manufacturers. The Health Sector Transformation Program's push toward privatization and public-private partnerships redirects procurement toward outcome-based service contracts rather than capital equipment purchases. Stakeholders must monitor how SFDA adapts its cybersecurity guidance for cloud-based patient data streams as hospital networks decentralize monitoring beyond traditional walls.
Market Dynamics
The Health Sector Transformation Program is redirecting Saudi hospital procurement from capital equipment purchases toward integrated service contracts, compressing vendor margins while expanding telemetry network footprints across Ministry of Health facilities.
Growth Catalysts
- SFDA registration pathways:Streamlined medical device approvals for cloud-connected monitoring equipment accelerate product launch timelines for manufacturers targeting Saudi tertiary care centers.
- Cardiac catheterization labs:Expansion of hemodynamic monitoring suites in King Faisal Specialist Hospital and comparable tier-one institutions drives demand for multi-parameter bedside units.
- Remote patient monitoring:SFDA clearance protocols for home-deployable devices open ambulatory care channels beyond traditional hospital walls.
Market Restraints
- Service infrastructure concentration:Localized technical support and training capabilities cluster in Riyadh and Jeddah, limiting equipment refresh cycles in peripheral regions.
- Interoperability mandates:NPHIES technical standards for connected health equipment impose compliance costs and extend product development timelines.
- Substitution pressure:Wearable devices with continuous ambulatory ECG capabilities compete with traditional telemetry for post-acute monitoring applications.
Strategic Opportunities
- Eastern Province expansion:Underpenetrated hospital networks in Dammam and Khobar present whitespace for telemetry infrastructure deployment under privatization initiatives.
- AI-enabled arrhythmia detection:Convergence of machine learning algorithms with continuous monitoring hardware creates premium pricing tiers for integrated cardiac care pathways.
- Public-private partnerships:Outcome-based service contract models under the Health Sector Transformation Program shift revenue streams toward recurring managed services.
Industry Challenges
- Cybersecurity skill scarcity:Hospital IT departments face capability gaps in securing cloud-based patient data streams as monitoring decentralizes beyond facility perimeters.
- Legacy EMR integration:Multi-parameter bedside units require complex interfacing with existing electronic medical record architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Patient Monitoring Market |
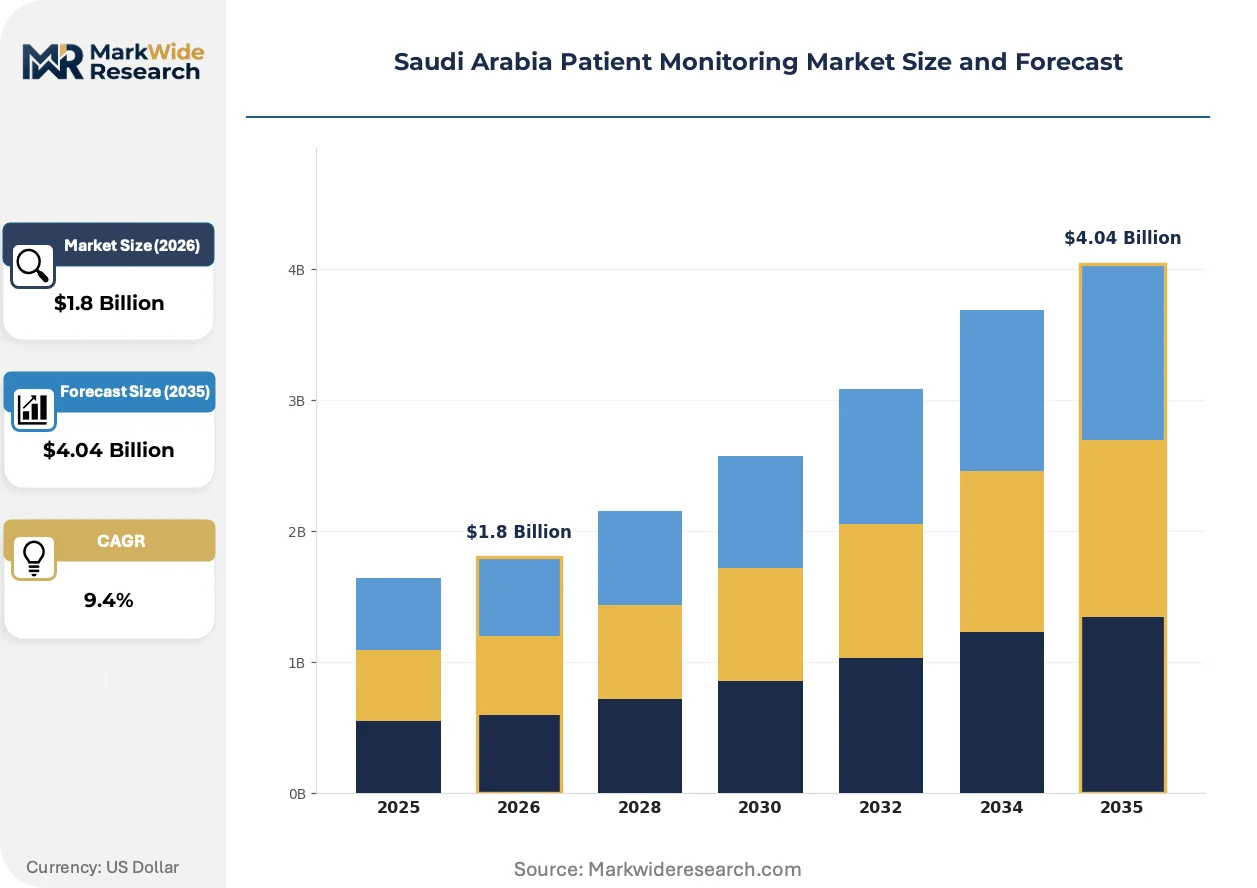
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Remote Patient Monitors, Portable Monitors Technology: Wireless Technology, Cloud-Based Solutions, Bluetooth Monitoring, Telehealth Platforms End User: Hospitals, Home Healthcare, Ambulatory Surgical Centers, Nursing Homes Application: Cardiac Monitoring, Respiratory Monitoring, Neurological Monitoring, Chronic Disease Management |
| Companies Covered | Philips Healthcare, GE Healthcare, Siemens Healthineers, Mindray Medical International Limited, Nihon Kohden Corporation, Drägerwerk AG & Co. KGaA, Masimo Corporation, Medtronic plc, Schiller AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Patient Monitoring Market Evolving Landscape
Telemetry infrastructure is evolving from bedside-centric architectures toward distributed monitoring ecosystems that span hospital, ambulatory, and home environments simultaneously.
Artificial intelligence is migrating from retrospective analytics to real-time clinical decision support embedded directly within monitoring hardware. Cardiac care units in Riyadh's tier-one hospitals are adopting these systems fastest, compressing alarm response windows from minutes to seconds while reducing false-positive rates that plague traditional threshold-based alerting.
SFDA cybersecurity guidance for cloud-connected medical devices is tightening data governance requirements for patient monitoring systems. Manufacturers must now demonstrate end-to-end encryption and breach response protocols before registration approval, with remote patient monitoring categories facing the most stringent review timelines as home deployment expands.
Hospital procurement teams are bundling equipment purchases with multi-year service and training contracts rather than acquiring hardware outright. Ministry of Health facilities lead this transition, replacing capital expenditure approvals with operational budgets that cover installation, maintenance, and clinician education through single-vendor relationships.
Saudi Arabia Patient Monitoring Market Segmentation
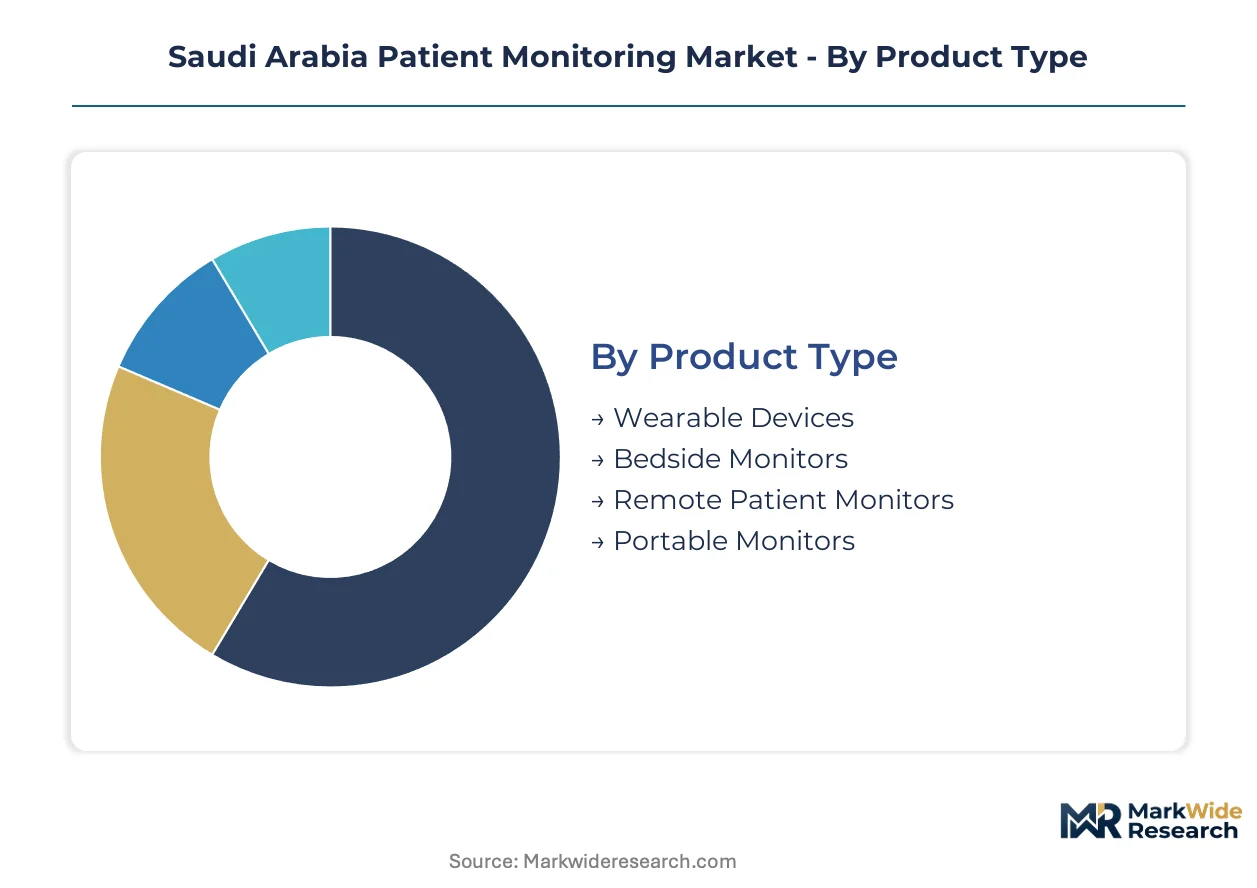
Saudi Arabia's patient monitoring market fragments across hardware form factors, connectivity architectures, care settings, and clinical applications. Each segment carries distinct service requirements, regulatory pathways, and procurement dynamics under the Health Sector Transformation Program.
Product Type:
After-sales service intensity varies sharply across product categories, with bedside monitors demanding 24/7 technical support contracts while wearable devices shift liability toward patient self-management.
- Bedside Monitors:Multi-parameter units integrate ECG, SpO2, invasive blood pressure, and respiratory rate acquisition through modular chassis designs. Ministry of Health tertiary care centers in Riyadh and Jeddah drive replacement cycles as ICU bed expansion targets accelerate under privatization initiatives.
- Wearable Devices:Continuous ambulatory ECG patches and arrhythmia detection bands command premium pricing where cloud connectivity integrates with hospital EMR systems. King Faisal Specialist Hospital and comparable tier-one institutions pilot these for post-discharge cardiac surveillance.
- Remote Patient Monitors:SFDA-cleared home-deployable kits enable telemetry beyond facility walls.
- Portable Monitors:Battery-powered compact units serve emergency transport and step-down unit applications.
Bedside monitors hold the largest share; momentum sits with wearable devices.
Technology:
Technology selection determines cybersecurity compliance burdens, with cloud-connected architectures facing extended SFDA review timelines compared to localized wireless deployments.
- Cloud-Based Solutions:Centralized data aggregation platforms enable real-time physician dashboards and predictive analytics for deterioration detection. SFDA tightened encryption and breach response protocols for these systems as home deployment expands patient data beyond hospital firewalls.
- Wireless Technology:Distributed telemetry networks eliminate bedside tethering through IEEE 802.11 standards and proprietary radio frequency protocols. Cardiac catheterization labs in tier-one Riyadh facilities prioritize these for hemodynamic monitoring suite upgrades.
- Bluetooth Monitoring:Short-range connectivity bridges consumer-grade wearables with clinical validation requirements.
- Telehealth Platforms:Integrated video consultation layers overlay physiological data streams for remote physician oversight.
Wireless technology dominates current installations; cloud-based solutions are climbing the fastest.
End User:
End-user concentration shapes pricing power, with hospital networks extracting multi-year service bundling while home healthcare procurement fragments across individual patient referrals.
- Hospitals:Ministry of Health facilities and privatized hospital groups anchor demand through centralized capital budgets and outcome-based service contracts. The Health Sector Transformation Program redirects procurement from equipment purchases toward integrated managed services spanning installation, maintenance, and clinician training.
- Home Healthcare:Post-acute monitoring demand surges as SFDA clears ambulatory devices and NPHIES interoperability mandates enable EMR integration. Peripheral regions beyond Riyadh and Jeddah present whitespace where technical support infrastructure remains thin.
- Ambulatory Surgical Centers:Same-day procedure volumes drive compact monitoring requirements.
- Nursing Homes:Long-term care facilities adopt simplified parameter tracking for chronic condition surveillance.
Hospitals command the dominant revenue pool; home healthcare shows the steepest expansion trajectory.
Application:
Application focus determines algorithm development priorities, with cardiac monitoring attracting AI-enabled arrhythmia detection investment while respiratory applications lag in predictive analytics maturity.
- Cardiac Monitoring:Continuous ECG, hemodynamic pressure, and ST-segment analysis systems target catheterization labs and coronary care units. Machine learning integration compresses alarm response windows while reducing false-positive rates that plague threshold-based alerting in Riyadh's tier-one hospitals.
- Chronic Disease Management:Multi-parameter longitudinal tracking supports diabetes, hypertension, and heart failure population health initiatives. The Health Sector Transformation Program's privatization push creates demand for remote monitoring infrastructure in Eastern Province expansion zones.
- Respiratory Monitoring:Capnography and pulse oximetry systems address ventilation and sleep disorder applications.
- Neurological Monitoring:EEG and intracranial pressure systems serve neurosurgical and stroke unit requirements.
Cardiac monitoring generates the largest revenue; chronic disease management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA registration protocols and Health Sector Transformation Program procurement reforms anchor Saudi Arabia's patient monitoring infrastructure buildout across Ministry of Health facilities and privatized hospital networks.
Riyadh
King Faisal Specialist Hospital and Ministry of Health tertiary centers drive multi-parameter bedside monitor replacement cycles as ICU bed expansion targets accelerate. SFDA cybersecurity guidance for cloud-connected devices imposes encryption and breach response protocols on manufacturers seeking registration approval. King Saud Medical City and specialized cardiac catheterization labs in the capital pilot AI-enabled arrhythmia detection systems.
Eastern Province
Dammam and Khobar hospital networks present whitespace for telemetry infrastructure deployment where technical support capabilities remain thinner than in Riyadh. Privatization initiatives under the Health Sector Transformation Program redirect procurement toward outcome-based service contracts rather than capital equipment purchases. King Fahd Hospital of the University anchors hemodynamic monitoring suite upgrades in the region's tier-one institutions.
Western Region
Jeddah's hospital groups leverage deep channel relationships with multinational equipment suppliers to sustain equipment refresh cycles in Ministry of Health facilities. MOHAP technical standards for connected health equipment impose interoperability compliance costs on product development timelines. King Abdulaziz University Hospital and Jeddah National Hospital concentrate demand for remote patient monitoring integration with electronic medical record systems.
NEOM Northwest
The giga-project's healthcare infrastructure planning incorporates distributed monitoring ecosystems spanning hospital, ambulatory, and home environments from initial design phases. NPHIES interoperability mandates enable cloud-based patient data streams to integrate with centralized health information exchange architectures. NEOM's greenfield development bypasses legacy EMR integration challenges that extend deployment timelines in established facilities elsewhere.
Saudi Arabia Patient Monitoring Market Competitive Landscape
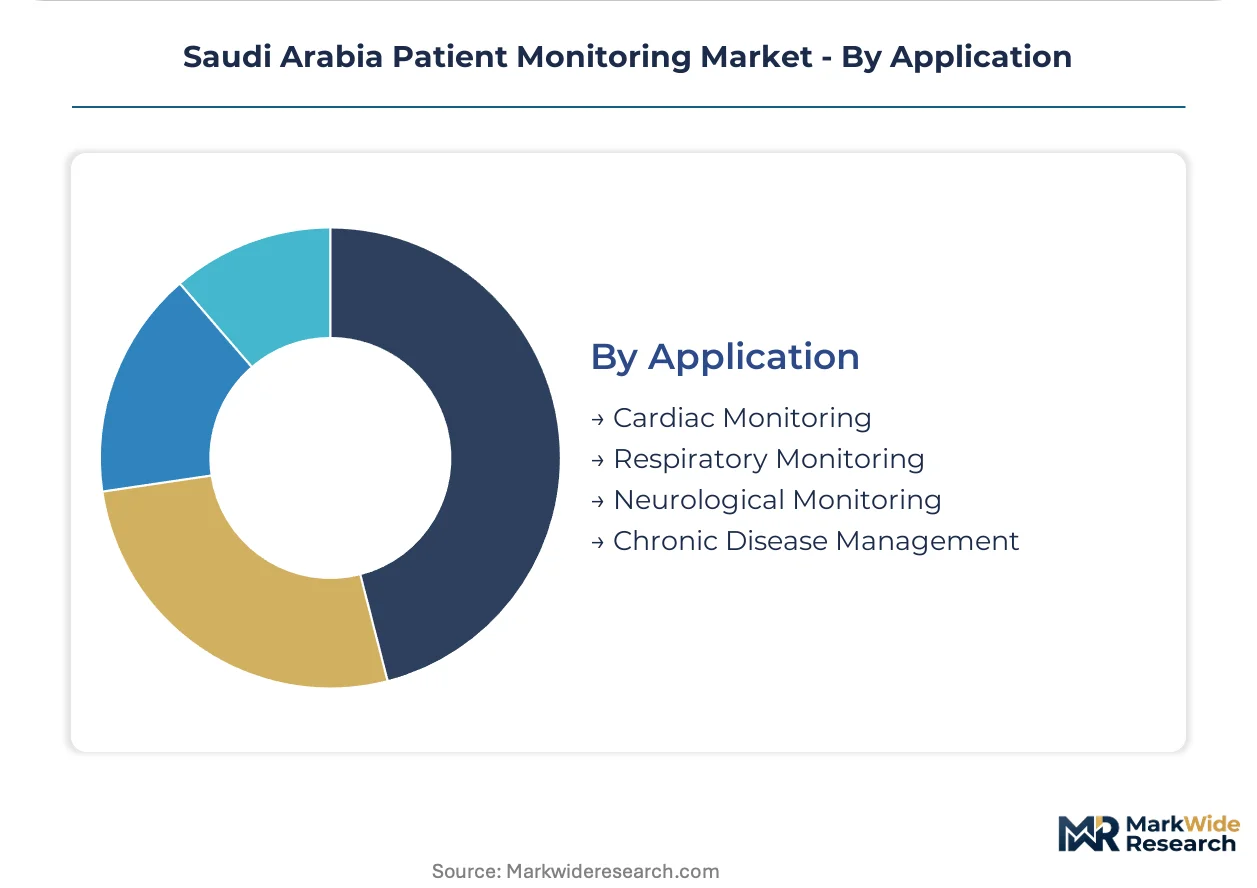
Capability concentration sits with multinational equipment suppliers possessing localized service infrastructure; scale advantage sits with diversified health technology conglomerates leveraging global manufacturing footprints. The vendor base stratifies across three tiers: integrated diagnostic imaging and monitoring platforms, specialized hemodynamic and cardiac monitoring suites, and emerging wearable device manufacturers seeking SFDA clearance for home deployment. Strategic moves center on multi-year service contract bundling and AI-enabled algorithm integration into hardware platforms.
Among European-domiciled health technology suppliers, Siemens Healthineers AG and Drägerwerk AG & Co. KGaA exemplify the premium-tier specialist archetype through advanced monitoring suite configurations. Philips Healthcare occupies a position bridging integrated platform scale with deep channel relationships in Saudi hospital procurement. These three anchors illustrate how regulatory compliance capability and localized technical support infrastructure determine competitive positioning under SFDA and Health Sector Transformation Program requirements.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| Mindray Medical International Limited |
| Nihon Kohden Corporation |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Medtronic plc |
| Schiller AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in Eastern Province telemetry infrastructure creates pricing leverage for manufacturers with localized service teams, compressing margins for vendors dependent on fly-in technical support while rewarding those with Riyadh-based training academies.
Pricing Analysis
Riyadh-Jeddah price spreads of 15-20% reflect differential service infrastructure density, with bedside monitors commanding premium-mid-economy pricing differentiation based on after-sales bundling intensity. SFDA cybersecurity certification tiers separate cloud-connected architectures from localized wireless systems, with the former extracting 25-30% uplifts where NPHIES interoperability is pre-validated. Cost compression in wearable device tiers is intensifying as consumer-grade manufacturers seek clinical validation pathways. Ministry of Health hospital networks exhibit lowest price sensitivity due to outcome-based contract mandates, while ambulatory surgical centers negotiate hardest on capital equipment line items.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia dominates component cost volatility for multi-parameter bedside monitors, with semiconductor sensors and display modules drawing from concentrated East Asian manufacturing hubs. Printed circuit assemblies and lithium-ion power systems rest on Chinese and South Korean supplier bases, while specialized ECG electrodes and SpO2 sensors feed from Japanese and German component specialists. Single-source vulnerability sits with AI-enabled arrhythmia detection chipsets sourced from Taiwan. Distribution runs through authorized distributor networks anchored in Riyadh and Jeddah, with direct hospital contracts emerging for tier-one institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from multi-year technical support and clinician training contracts is expanding faster than hardware sales as the Health Sector Transformation Program redirects procurement toward integrated managed services.
For Market Incumbents: Entrench position through backward integration into cloud infrastructure and localized AI algorithm development, countering substitution pressure from wearable device manufacturers seeking SFDA clearance. Deepen channel control by embedding biomedical engineers within King Faisal Specialist Hospital and comparable tier-one institutions to compress response times below competitor reach. For New Entrants and Emerging Players: Pursue whitespace in Eastern Province home healthcare deployment where technical support infrastructure remains thin and NPHIES interoperability mandates create entry barriers for undifferentiated hardware vendors. Target chronic disease management applications with Bluetooth-enabled ambulatory kits that bridge consumer usability with clinical validation requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among monitoring-as-a-service providers with outcome-based Ministry of Health contracts spanning installation through clinician education. Long-term viability hinges on cybersecurity compliance capability as SFDA tightens cloud-connected device governance. Acquisition target archetype: regional service specialists with established training academies and GPO relationships. The signal to watch is Health Sector Transformation Program privatization velocity in Dammam and Khobar hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cybersecurity Pre-Certification | Accelerates registration timelines for cloud-connected architectures targeting home deployment expansion. |
| Hospital System Partnership | King Faisal Specialist Hospital relationships anchor hemodynamic monitoring suite upgrade cycles. |
| AI Algorithm Integration | Machine learning-enabled arrhythmia detection commands pricing premiums in Riyadh cardiac units. |
| Service Contract Bundling | Multi-year managed services align with Health Sector Transformation Program procurement reforms. |
| NPHIES Interoperability Validation | Pre-integrated EMR connectivity reduces deployment friction in Ministry of Health facilities. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, GPO contracts managers, and SFDA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork with Ministry of Health procurement directors and tier-one hospital administrators combined with secondary validation against hospital procurement databases, GPO contract disclosures, and SFDA medical device registration filings. Bottom-up demand modeling across bedside, wearable, and remote monitoring form factors triangulated with top-down expenditure tracking from Health Sector Transformation Program budget allocations.
Demand-supply balance framing anchored the projection methodology, with capacity utilization across Riyadh and Jeddah service infrastructure informing pricing elasticity assumptions over the projection horizon. Segmentation dimensions spanned product type, connectivity architecture, care setting, and clinical application, with cardiac versus chronic disease management split validated against catheterization lab expansion pipelines. CAGRs derived from equipment replacement cycle analysis and privatization initiative timelines, incorporating NPHIES interoperability compliance cost trajectories and AI-enabled feature penetration curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese wearable manufacturers pursuing SFDA clearance or accelerated Eastern Province privatization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Lung Monitoring Devices Market