
 Patient Monitoring Devices Market | 2026-2036
Patient Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Monitoring Devices Market Analysis
The gap between premium multi-parameter systems and single-purpose commodity monitors is repositioning procurement criteria across health systems. Philips Healthcare leverages its software-integrated monitoring ecosystems to sustain premium pricing in critical care installations. Medtronic anchors its portfolio through implantable cardiac monitors that feed longitudinal data into provider dashboards. Masimo competes on proprietary pulse oximetry algorithms that differentiate performance in low-perfusion scenarios.
Patient monitoring devices encompass electronic systems that acquire, process, display, and transmit physiological data such as electrocardiogram waveforms, blood oxygen saturation, respiratory rate, and invasive pressure readings with sampling frequencies typically exceeding 250 Hz for cardiac applications. These systems serve primarily to enable early detection of clinical deterioration, reduce response times to adverse events, and support decentralized care models outside traditional hospital wards. Wearable monitors and remote patient monitoring technologies are capturing the fastest expansion as health systems seek to extend surveillance beyond physical bed capacity, while bedside monitors retain the largest installed base and associated service revenue pools. Implantable devices command the highest per-unit margins due to regulatory complexity and long-term data subscription models.
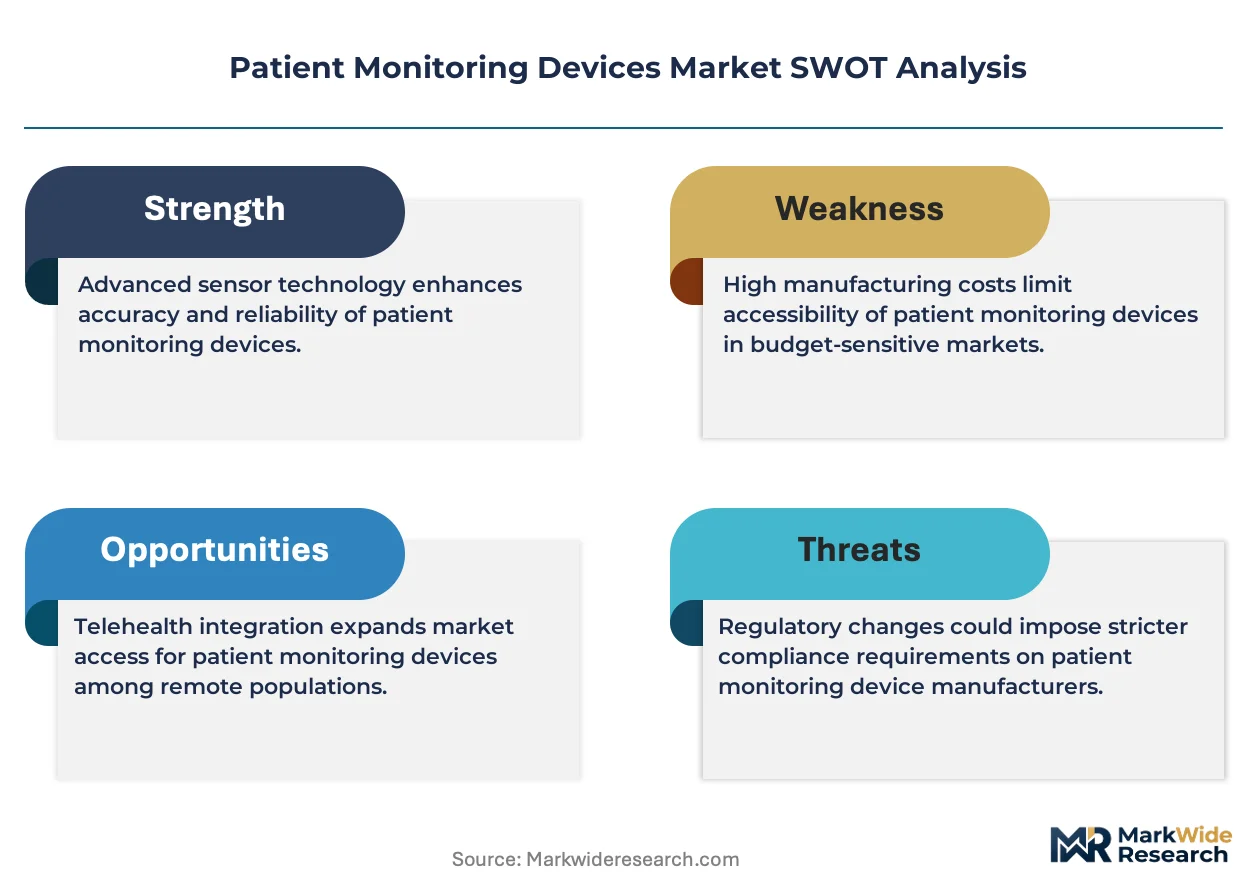
The FDA enforces Class II and Class III device controls that mandate clinical validation for algorithms generating diagnostic alarms, directly shaping R&D timelines and submission costs for manufacturers seeking US market access. EMA's Medical Device Regulation requires notified body oversight of software-as-a-medical-device components, tightening conformity pathways for European deployments. Stakeholders must track evolving cybersecurity guidance from both regulators as connected device portfolios expand attack surfaces and liability exposure.
Market Dynamics
Hospital systems are consolidating procurement around cloud-native monitoring platforms that collapse capital expenditure into per-patient subscription economics, compressing traditional hardware refresh cycles and vendor lock-in periods.
Growth Catalysts
- CMS Readmission Penalties:US hospital systems deploy remote patient monitoring to avoid reimbursement cuts tied to 30-day readmission rates, accelerating telemetry expansion into post-acute settings.
- Wireless Telemetry:Bedside-to-cloud data streaming eliminates wired infrastructure costs and enables continuous monitoring during patient transport and ambulation.
- Aging Population Protocols:Germany and Japan mandate longitudinal vital sign tracking for chronic disease cohorts, creating institutional demand for wearable ECG and pulse oximetry systems.
Market Restraints
- Semiconductor Supply Concentration:Analog front-end chips and low-power Bluetooth SoCs concentrate in Taiwanese and South Korean fabrication facilities, exposing lead time volatility.
- FDA Algorithm Validation:Class II device controls require clinical studies for diagnostic alarm algorithms, extending development timelines by 18-24 months for US market entry.
- Disposable Sensor Costs:Single-use pulse oximetry probes and ECG electrodes constitute 40-60% of lifetime ownership cost, squeezing margin on hardware-only contracts.
Strategic Opportunities
- Home-Based Acute Care:Hospital-at-home programs in the United States reimburse remote monitoring at parity with inpatient observation, opening ambulatory telemetry deployment.
- AI-Assisted Alarm Management:Machine learning classifiers reduce false positive rates in critical care, differentiating premium system tiers and justifying software subscription pricing.
- EU MDR Software Pathways:EMA's Medical Device Regulation creates first-mover advantage for manufacturers with notified body-approved software-as-a-medical-device architectures.
Industry Challenges
- Cybersecurity Workforce Gap:Connected device portfolios require embedded security engineers and clinical risk managers that medical device manufacturers struggle to recruit at scale.
- Legacy System Integration:Proprietary data protocols from installed bedside monitors obstruct seamless cloud aggregation, forcing expensive middleware development or rip-and-replace decisions.
- Interoperability Certification:HL7 FHIR and IEEE 11073 conformance testing delays product launches as health systems demand verified EHR connectivity before procurement approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Monitoring Devices Market |
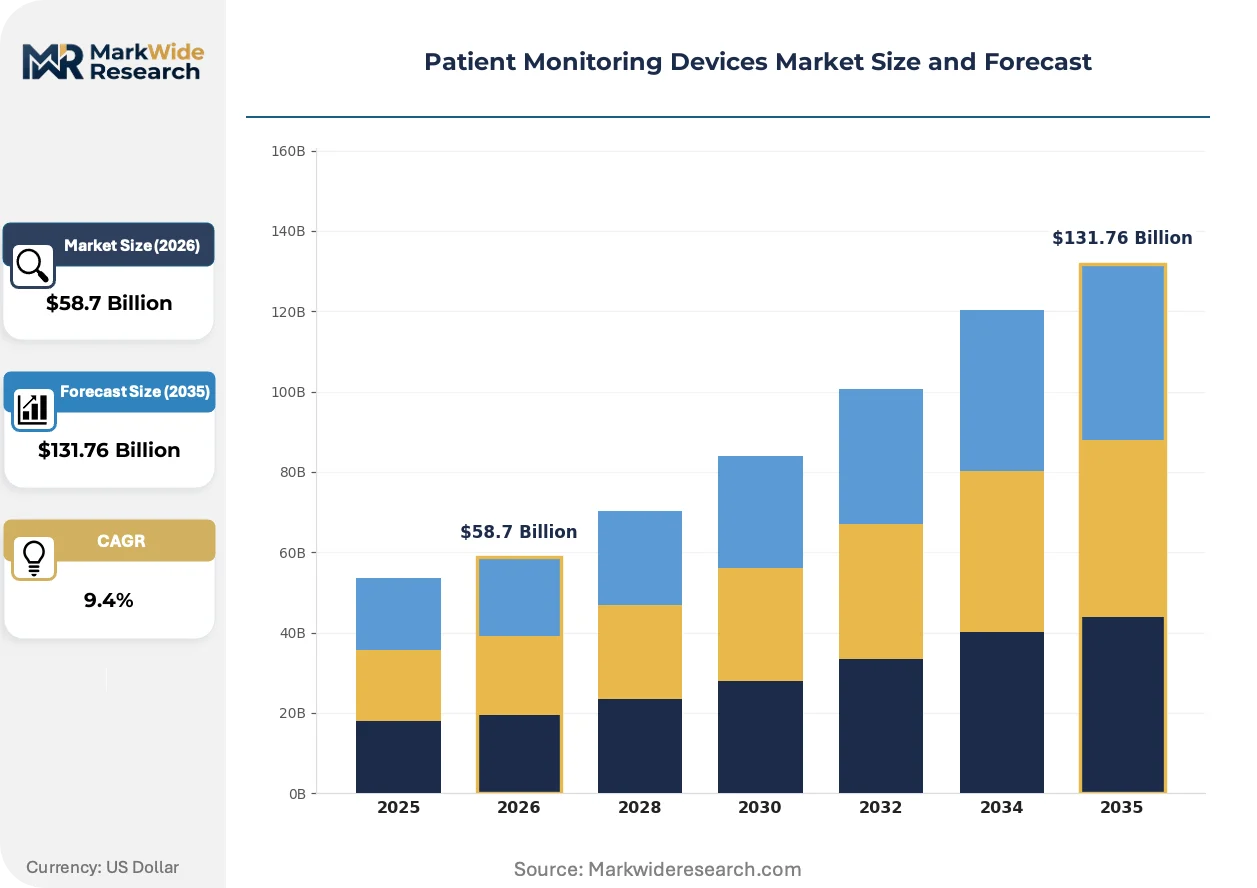
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Bedside Monitors, Implantable Devices, Handheld Monitors Technology: Telehealth Solutions, Remote Patient Monitoring, Wireless Systems, Automated Alerts End User: Hospitals, Home Care Settings, Clinics, Long-term Care Facilities Application: Cardiac Monitoring, Respiratory Monitoring, Neurological Monitoring, Fetal Monitoring |
| Companies Covered | Philips Healthcare, Medtronic, GE Healthcare, Abbott Laboratories, Masimo, Mindray Medical, Nihon Kohden Corporation, Omron Healthcare, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Monitoring Devices Market Emerging Trajectories
Algorithmic interpretation of physiological waveforms is displacing threshold-based alarm systems, while regulatory frameworks accelerate software validation requirements and procurement models shift toward integrated platform contracts over discrete device sales.
Edge computing architectures embedded in wearable monitors are automating real-time arrhythmia detection and respiratory pattern analysis without cloud dependency. Cardiology departments in US academic medical centers are piloting these systems for ambulatory patient surveillance. This distributed processing is automating clinical decision support at the point of data acquisition, reducing latency and network bandwidth requirements.
EMA's Medical Device Regulation tightens notified body oversight of software-as-a-medical-device components, including machine learning algorithms that adapt based on patient-specific data. Manufacturers must demonstrate continuous validation across algorithm updates, increasing regulatory affairs headcount and documentation burden. European health systems are responding by consolidating procurement around vendors with established MDR conformity pathways, favoring incumbents over emerging competitors.
Health system procurement departments are unbundling hardware ownership from clinical service contracts, favoring per-patient-per-day pricing that aligns vendor revenue with actual monitoring utilization. This consumption-based model displaces capital purchase orders and multi-year service agreements. The shift is most visible in US integrated delivery networks seeking operational flexibility amid bed capacity volatility and value-based reimbursement pressure.
Patient Monitoring Devices Market Segmentation
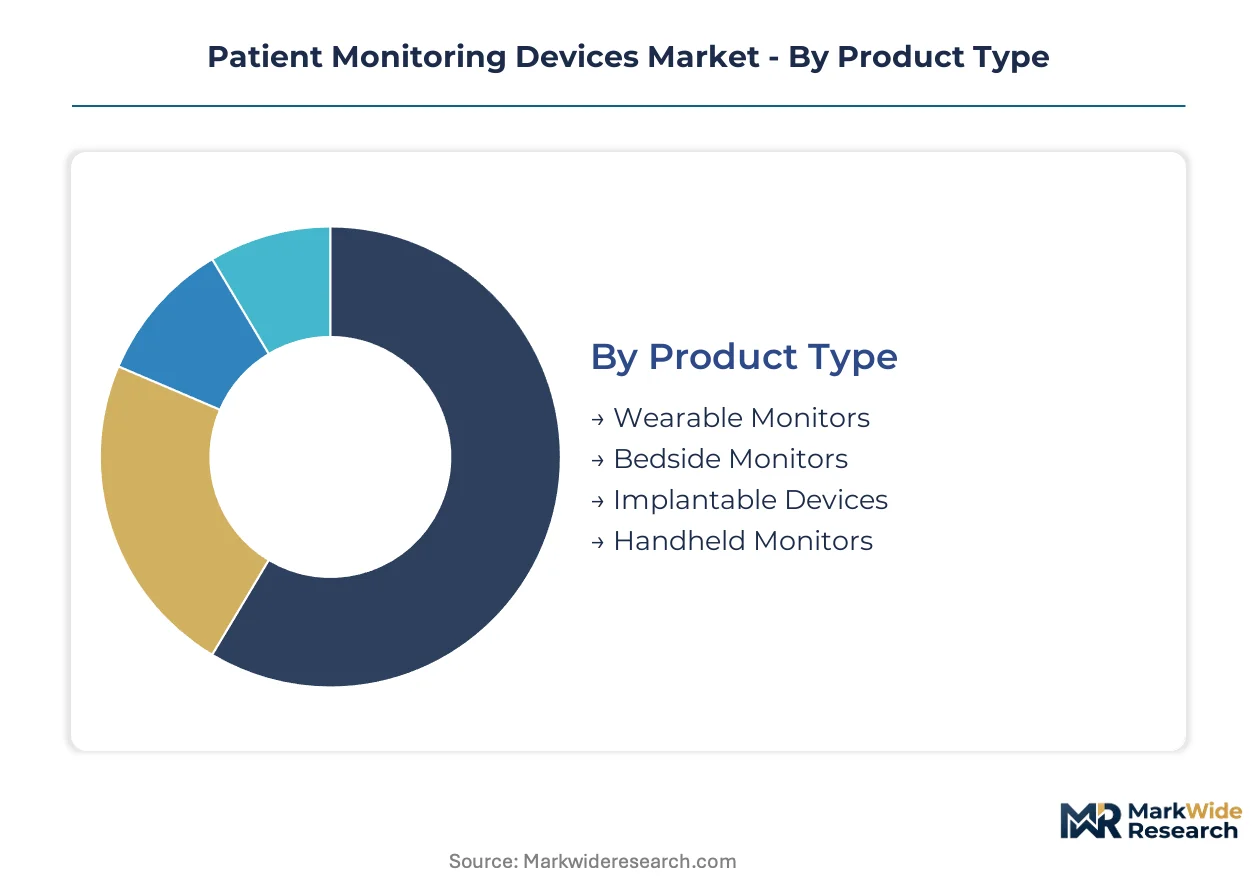
Procurement criteria across health systems diverge sharply by care setting and reimbursement model, forcing manufacturers to architect distinct value propositions for acute versus ambulatory deployment. Segmentation reveals where hardware margins concentrate versus where subscription economics dominate.
Product Type:
Buyers in this category separate by capital availability and clinical risk tolerance, with premium multi-parameter systems commanding extended service contracts.
- Wearable Monitors:These devices integrate photoplethysmography, accelerometry, and single-lead ECG into patch or wrist-worn form factors sampling at 100-500 Hz. Hospital-at-home programs in the United States and Germany are standardizing on these systems for post-discharge surveillance, driven by CMS reimbursement parity with inpatient observation.
- Bedside Monitors:Multi-parameter systems acquire ECG, SpO2, invasive pressures, and respiratory waveforms through modular rack configurations with 250+ Hz cardiac sampling. These retain the largest installed base across US academic medical centers and Japanese tertiary hospitals, where 24/7 critical care coverage mandates wired reliability.
- Implantable Devices:Leadless cardiac monitors and implantable loop recorders transmit longitudinal arrhythmia data via cellular networks.
- Handheld Monitors:Spot-check devices for pulse oximetry and non-invasive blood pressure serve rapid assessment workflows in clinics and emergency departments.
Bedside monitors lead volumes today; wearable monitors are gaining share fastest.
Technology:
Technology selection tracks infrastructure maturity, with cloud-native platforms displacing on-premise architectures in systems with advanced IT capabilities.
- Telehealth Solutions:Integrated video consultation platforms with synchronous vital sign streaming enable virtual rounding and specialist consultation. US integrated delivery networks deploy these most intensively, motivated by workforce shortages in rural service areas.
- Remote Patient Monitoring:Asynchronous data transmission from patient homes to clinical dashboards supports chronic disease management at scale. Germany's national digital health infrastructure and Japan's aging-population protocols are institutionalizing these deployments for heart failure and COPD cohorts.
- Wireless Systems:Bluetooth Low Energy and proprietary radio protocols eliminate bedside tethering during transport and ambulation.
- Automated Alerts:Machine learning classifiers processing waveform data reduce false positive alarm rates in critical care environments.
Remote patient monitoring shows the steepest expansion trajectory; wireless systems anchor near-term revenue.
End User:
End-user economics range from capital-intensive enterprise sales to per-patient subscription models, reshaping vendor go-to-market structures.
- Hospitals:Acute care systems purchase capital equipment with 7-10 year depreciation schedules and attached multi-year service agreements. These buyers dominate procurement volume in the United States, Germany, and Japan, where reimbursement complexity favors integrated platform vendors.
- Home Care Settings:Post-acute and chronic care monitoring operates on per-patient-per-day pricing aligned with actual utilization. US hospital-at-home waivers and German home nursing subsidies are accelerating vendor investment in lightweight, patient-operated devices.
- Clinics:Outpatient facilities prioritize spot-check devices and limited-parameter monitoring for pre-operative assessment.
- Long-term Care Facilities:Skilled nursing and assisted living environments deploy fall detection and basic vital sign surveillance for resident safety.
Hospitals dominate current revenue; home care settings are climbing the fastest.
Application:
Application segmentation reflects physiological complexity and regulatory validation burden, with cardiac applications commanding the most rigorous FDA and EMA scrutiny.
- Cardiac Monitoring:Systems acquire and interpret ECG waveforms, heart rate variability, and implantable device transmissions for arrhythmia detection. US academic medical centers and German cardiology departments are piloting edge-computing wearables for ambulatory surveillance, driven by catheterization lab capacity constraints.
- Respiratory Monitoring:Capnography, pulse oximetry, and respiratory rate detection support mechanical ventilation and sleep apnea management. Japanese respiratory therapy protocols and US post-acute COVID monitoring programs are expanding demand for continuous SpO2 tracking.
- Neurological Monitoring:EEG and intracranial pressure systems serve epilepsy, stroke, and trauma intensive care.
- Fetal Monitoring:Ultrasound and tocodynamometer systems track uterine contractions and fetal heart rate during labor and delivery.
Cardiac monitoring leads volumes today; respiratory monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical engineering talent clusters in Boston, Munich, and Tokyo anchor the highest-density monitoring device deployment corridors. These metropolitan concentrations feed directly into health system procurement decisions and regulatory approval pathways.
United States
Hospital-at-home waivers and CMS reimbursement parity for remote monitoring accelerate telemetry deployment into post-acute settings. FDA Class II device controls mandate clinical validation for diagnostic alarm algorithms, extending development timelines for domestic market entry. The Boston-Cambridge corridor concentrates academic medical centers piloting edge-computing wearables for ambulatory cardiac surveillance.
Germany
National digital health infrastructure mandates longitudinal vital sign tracking for chronic disease cohorts, institutionalizing wearable ECG and pulse oximetry demand. EMA's Medical Device Regulation tightens notified body oversight of software-as-a-medical-device components, favoring vendors with established conformity pathways. Bavaria's medical technology cluster around Erlangen and Munich hosts health system pilot programs for hospital-at-home telemetry.
Japan
Aging-population protocols require continuous monitoring for heart failure and COPD patients, expanding institutional demand for lightweight wearable systems. PMDA oversight aligns with international harmonization initiatives while maintaining distinct local clinical evidence requirements. The Kanto region around Tokyo concentrates tertiary hospital procurement and domestic manufacturer headquarters.
United Kingdom
NHS workforce shortages drive virtual rounding and remote specialist consultation platforms into standard care pathways. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR while establishing independent conformity assessment routes. The Oxford-Cambridge-London arc concentrates health tech procurement decision-making and digital health infrastructure investment.
China
Hospital tier classification systems concentrate multi-parameter monitoring procurement in Class 3A facilities across provincial capitals. NMPA medical device registration requirements prioritize domestic clinical evidence for algorithm-based diagnostic features. The Yangtze River Delta around Shanghai hosts the largest concentration of manufacturing capacity and health system pilot deployments for cloud-native monitoring platforms.
Patient Monitoring Devices Market Vendor Landscape
Top-tier vendors anchor critical care installations through integrated software-hardware ecosystems, while mid-tier specialists compete on discrete parameter excellence and regional service density. The vendor base stratifies across three archetypes: diversified conglomerates with full-stack monitoring portfolios, cardiac-focused specialists leveraging implantable device data streams, and emerging challengers attacking specific workflow pain points with cloud-native architectures. Competitive dynamics center on M&A activity consolidating telemetry data platforms and strategic partnerships embedding monitoring capabilities into electronic health record workflows.
Within the diversified conglomerate tier, Philips Healthcare and GE Healthcare occupy positions exemplifying platform-centric competition through software-integrated ecosystems and modular hardware architectures. Medtronic anchors the cardiac-specialist vector, representing the implantable device-to-dashboard data continuity model that commands premium subscription economics. These three entities collectively illustrate how vendor positioning diverges between capital equipment ownership models and recurring revenue service architectures.
| Leading Market Players |
|---|
| Philips Healthcare |
| Medtronic |
| GE Healthcare |
| Abbott Laboratories |
| Masimo |
| Mindray Medical |
| Nihon Kohden Corporation |
| Omron Healthcare |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
EMA's Medical Device Regulation gates qualified supply and premium-tier pricing access by mandating notified body oversight of software-as-a-medical-device components, forcing health systems to consolidate procurement around vendors with established conformity pathways and compressing margin for uncertified competitors.
Pricing Analysis
The bundled-vs-unbundled service split is collapsing capital expenditure into per-patient subscription economics across US integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated critical care platforms from modular bedside systems and commodity spot-check devices. Cost compression in the standard tier is intensifying because health systems unbundle hardware ownership from clinical service contracts. Home care settings exhibit the highest price sensitivity due to reimbursement uncertainty, while academic medical centers absorb premium pricing for FDA-validated diagnostic algorithms.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise-scale procurement for multi-parameter systems, while distributor networks serve clinic and long-term care segments. Analog front-end chips and low-power Bluetooth SoCs concentrate in Taiwanese and South Korean fabrication facilities, exposing lead time volatility. Single-source vulnerability in semiconductor supply creates procurement risk for wearable monitor manufacturers scaling hospital-at-home deployments. Distribution runs through group purchasing organizations in the United States and regional medical device distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as health systems prioritize FDA-validated AI alarm management over threshold-based systems, filtering procurement toward vendors with demonstrated clinical evidence packages.
For Market Incumbents: Acquire cloud-native telemetry platforms to defend installed base erosion from software-first challengers. Philips Healthcare and GE Healthcare should deepen backward integration into sensor manufacturing to offset disposable probe cost inflation. Anchor premium pricing through exclusive EHR integration partnerships that raise switching costs for hospital customers.
For New Entrants and Emerging Players: Edge-computing arrhythmia detection offers a technology-first wedge into US academic medical center pilot programs seeking catheterization lab capacity relief. Target German home nursing subsidies as the most penetrable reimbursement pathway for lightweight wearable ECG systems. Pursue notified body pre-submission pathways under EU MDR before commercial launch to compress time-to-revenue.
For Investors and Strategic Acquirers: Roll-up economics work for cardiac monitoring specialists because longitudinal data subscription models command recurring revenue multiples absent from hardware-only vendors. Platform consolidation across telemetry data streams offers 5-10 year viability as health systems demand unified dashboards. Watch CMS hospital-at-home waiver permanence as the signal to watch for ambulatory telemetry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Class II device controls mandate clinical validation for diagnostic alarm algorithms in US market entry. |
| CE Marking Pathway | EMA MDR notified body approval accelerates procurement consolidation by European health systems. |
| Hospital System Partnership | Integrated delivery network contracts embed monitoring platforms into EHR workflows at scale. |
| Software Companion Development | AI-assisted alarm classifiers differentiate premium tiers and justify subscription pricing models. |
| Reimbursement Strategy | CMS hospital-at-home parity and German digital health infrastructure institutionalize demand. |
Methodological Framework
Direct dialogue with hospital procurement committees, biomedical engineers, GPO contracts managers, and regulatory affairs directors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract disclosures. Bottom-up and top-down triangulation reconciled unit shipment estimates with health system capital expenditure patterns.
Segment-level outputs across product type, technology architecture, end-user setting, and clinical application dimension were stress-tested against reimbursement trajectory assumptions. CAGRs were derived from logistic diffusion curves fitted to historical adoption rates in remote patient monitoring and cloud-native platform deployment. Forecast inputs incorporated semiconductor supply lead time volatility and regulatory validation timeline distributions.
The model holds under stable reimbursement parity and MDR conformity pathway continuity; deviation in CMS waiver permanence or notified body capacity constraints would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Respiration Monitor Belt Market