
 MR Vital Sign Monitors Market | 2026-2036
MR Vital Sign Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
MR Vital Sign Monitors Market Analytics
Aftermarket service revenue is fragmenting across hardware calibration, software updates, and remote telemetry support. GE Healthcare leverages its installed base of MRI systems to bundle vital sign monitoring contracts. Koninklijke Philips N.V. sustains R&D intensity in optical sensing architectures that function within high-field magnetic environments. IRadimed Corp. specializes in wireless, battery-powered designs that dominate niche ambulatory MRI segments.
MR vital sign monitors are instruments engineered to track physiological parameters—heart rate, blood oxygen saturation, blood pressure, and respiration—without electromagnetic interference in static magnetic fields ranging from 1.5 to 7 Tesla, utilizing fiber-optic or pneumatic transduction to eliminate RF noise. Their primary purpose is to ensure patient safety during diagnostic imaging or interventional procedures where conventional electronic sensors fail. Portable monitors lead product type segmentation due to flexibility across hybrid operating rooms and mobile MRI suites, while multi-parameter units capture expanding margin pools as hospitals consolidate device procurement. Electronic technology anchors the installed base, though hybrid optical-electronic architectures represent the fastest-growing category as manufacturers balance accuracy with MRI compatibility.
The FDA enforces 510(k) premarket notification and IEC 60601-1-2 electromagnetic compatibility standards for MRI-compatible medical electrical equipment, directly shaping design validation timelines and market access costs. The EU Medical Device Regulation and ISO 13485 quality management requirements impose additional conformity burdens on manufacturers seeking European hospital procurement channels. Stakeholders must monitor evolving FDA guidance on computational vital sign algorithms and predicate device equivalence determinations.
Market Dynamics
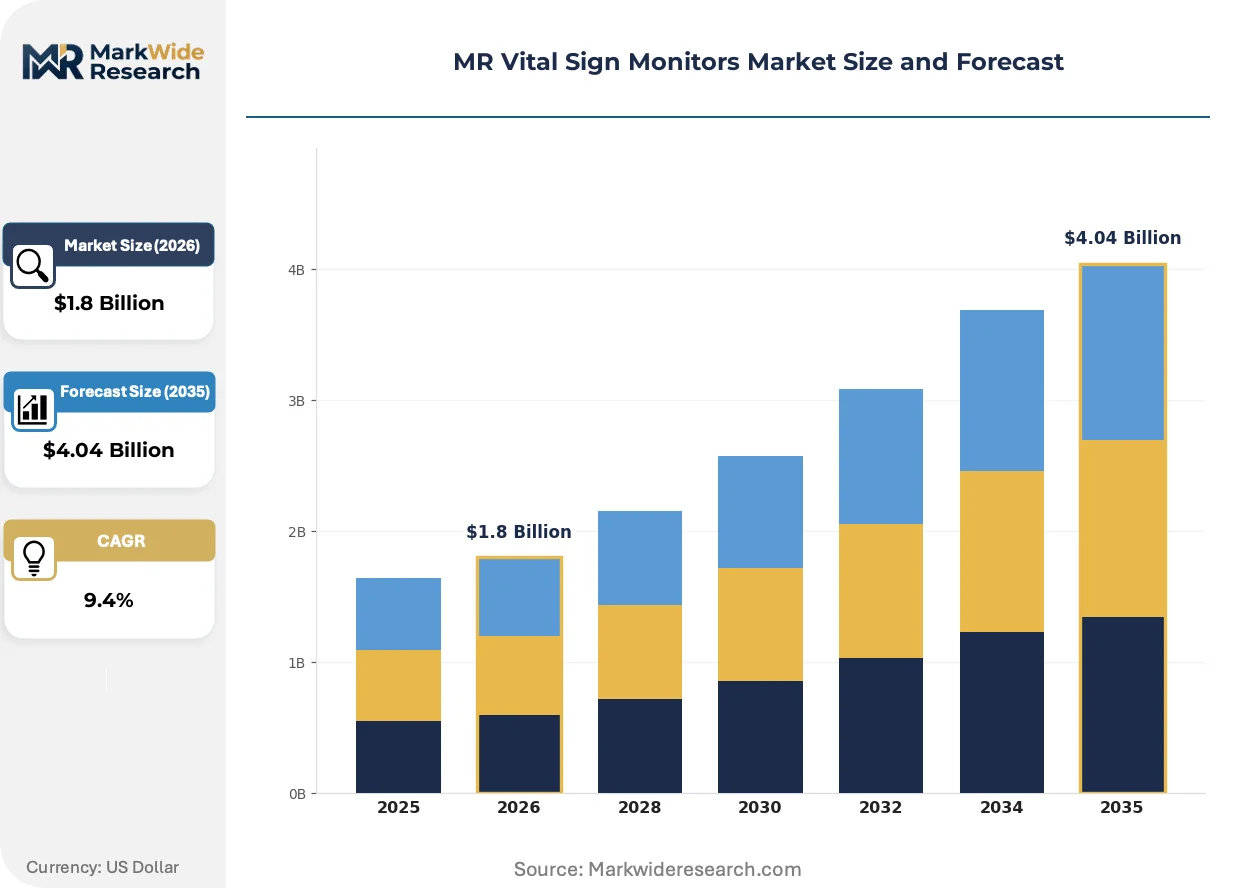
The FDA's 510(k) clearance pathway compresses product development timelines while IEC 60601-1-2 electromagnetic compatibility standards force manufacturers toward fiber-optic and pneumatic transduction architectures that eliminate RF noise in high-field magnetic environments.
Growth Catalysts
- Hospital Radiology Department Expansion:Rising installed MRI base in tertiary care centers creates consistent replacement and upgrade cycles for compatible monitoring equipment.
- EU Medical Device Regulation:MDR conformity requirements accelerate hospital procurement of certified devices from validated suppliers, consolidating demand around compliant manufacturers.
- Hybrid Operating Room Construction:Surgical suites combining MRI guidance with real-time physiological monitoring require portable, multi-parameter units that function across static magnetic fields from 1.5 to 7 Tesla.
Market Restraints
- Fiber-Optic Component Supply Concentration:Specialized optical transducers and cables for high-field environments source from limited qualified suppliers, creating input cost volatility and lead time risk.
- 510(k) Predicate Device Equivalence:FDA determinations requiring substantial equivalence to existing cleared devices slow novel sensor architecture introductions and extend validation costs.
- Pneumatic System Calibration Complexity:Blood pressure modules using pneumatic cuffs demand frequent recalibration services that fragment aftermarket revenue and elevate total cost of ownership.
Strategic Opportunities
- Ambulatory MRI Suite Penetration:Mobile imaging services and standalone diagnostic centers in underserved United States markets present white space for wireless, battery-powered monitor deployment.
- Computational Algorithm Clearance:Evolving FDA guidance on AI-driven vital sign interpretation creates pathway for software-enabled feature differentiation and recurring revenue models.
- Optical-Electronic Hybrid Convergence:Integration of fiber-optic sensing with miniaturized electronic signal processing enables single-unit multi-parameter monitoring that reduces procurement complexity.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialists capable of designing electromagnetic interference shielding for 7 Tesla environments command premium compensation and extend R&D timelines.
- Legacy MRI System Integration:Backward compatibility requirements with installed 1.5 Tesla suites constrain hardware architecture choices and complicate firmware update pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MR Vital Sign Monitors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Stationary Monitors, Multi-parameter Monitors, Wearable Devices Technology: Electronic, Optical, Hybrid, Mechanical End User: Hospitals, Homecare, Nursing Facilities, Emergency Services Application: Cardiac Monitoring, Respiratory Monitoring, Temperature Monitoring, Blood Pressure Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., IRadimed Corp., Dragerwerk AG, Schiller AG, Spacelabs Healthcare, Mindray Medical International Limited, Nihon Kohden Corporation, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MR Vital Sign Monitors Market Evolving Landscape
Sensor architecture evolution, regulatory algorithm guidance, and procurement consolidation are actively restructuring how hospitals evaluate and deploy physiological monitoring during magnetic resonance procedures.
Fiber-optic pulse oximetry and blood pressure sensing is hybridizing with pneumatic backup systems to create redundant measurement pathways that satisfy both accuracy requirements and MRI compatibility mandates. Academic medical centers with 7 Tesla research magnets are piloting these dual-transduction designs to eliminate signal dropout during extended scanning protocols. The convergence is compressing demand for pure pneumatic systems while elevating R&D intensity among component suppliers.
The FDA's evolving guidance on computational vital sign algorithms is reshaping predicate device equivalence determinations for software-enabled monitors. Manufacturers must now document clinical validation datasets for machine learning-derived heart rate and respiration metrics, extending 510(k) preparation timelines. Cardiac MRI segments face the steepest compliance burden as arrhythmia detection algorithms attract heightened scrutiny.
Hospital procurement departments are consolidating device categories into multi-year enterprise agreements that bundle vital sign monitors with MRI system service contracts. Radiology department buyers in the United States are displacing standalone monitor purchases with integrated vendor relationships that span hardware, calibration, and remote telemetry support. This concentration shifts negotiating leverage toward manufacturers with installed base scale and comprehensive service networks.
MR Vital Sign Monitors Market Segmentation
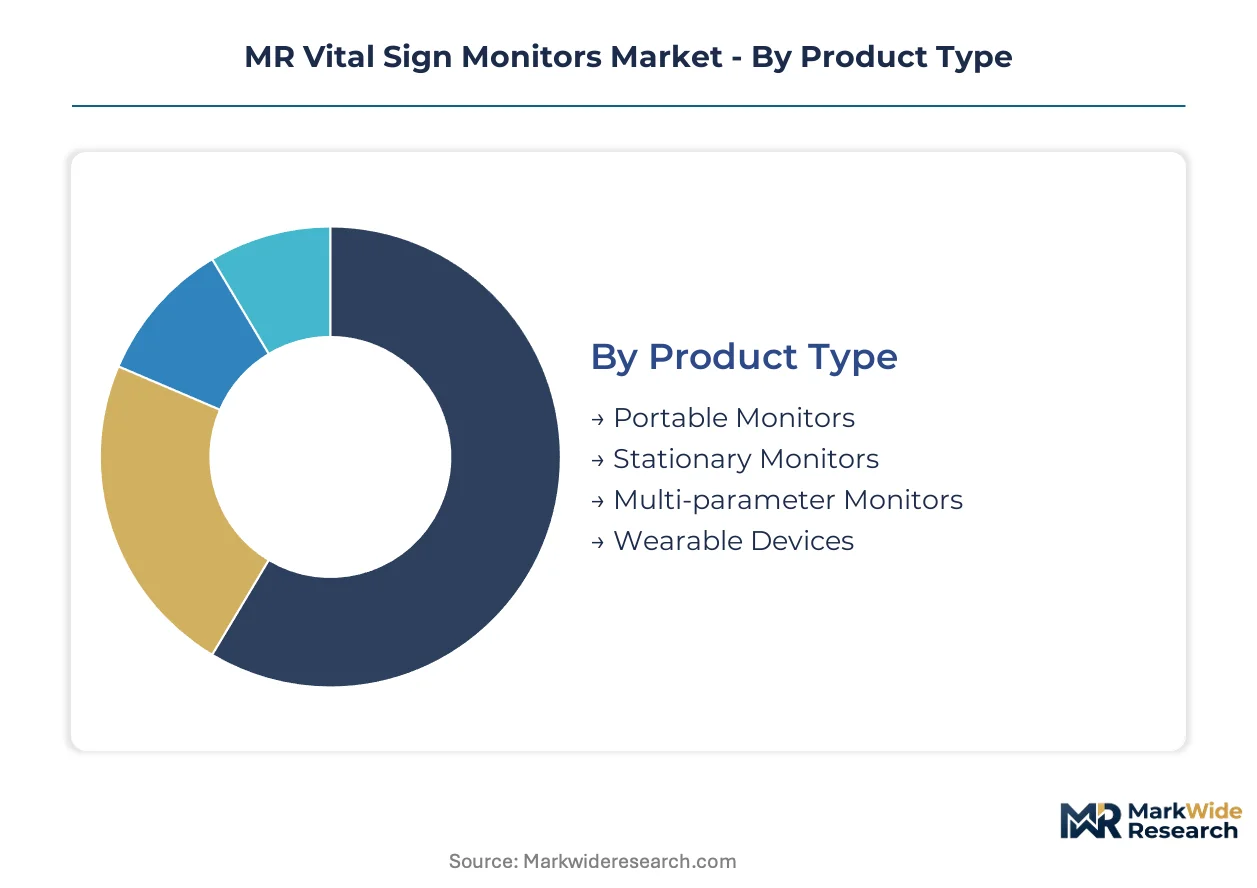
Segmentation in the MR vital sign monitors market reveals how procurement decisions split between imaging workflow integration and point-of-care flexibility. Hospital buyers weigh magnetic compatibility specifications against total cost of ownership across stationary installations and mobile deployments.
Product Type:
Use-case spectrum spans fixed radiology suite installations to ambulatory services requiring battery-powered mobility.
- Portable Monitors:Battery-powered units with fiber-optic transduction enable deployment across hybrid operating rooms and mobile MRI suites. Demand concentrates in United States tertiary care centers expanding interventional MRI capabilities.
- Multi-parameter Monitors:Integrated platforms consolidate pulse oximetry, blood pressure, and respiratory tracking within single electromagnetic-shielded enclosures. Academic medical centers in Germany and Japan prioritize these units for 7 Tesla research environments.
- Stationary Monitors:Fixed-installation systems anchor dedicated MRI suite infrastructure with pneumatic backup architectures.
- Wearable Devices:Wireless, battery-powered designs target niche ambulatory segments and extended monitoring protocols.
The dominant share belongs to Portable Monitors, while Multi-parameter Monitors are closing the gap fastest.
Technology:
Cost tier differentiation separates legacy electronic architectures from premium fiber-optic and hybrid systems.
- Electronic:Conventional transduction dominates installed base despite RF susceptibility limitations. Replacement cycles in United States community hospitals sustain procurement volume for backward-compatible systems.
- Hybrid:Optical-electronic convergence balances measurement accuracy with magnetic field immunity. Siemens Healthineers and Philips accelerate R&D in this category for 3 Tesla clinical installations.
- Optical:Pure fiber-optic sensing eliminates electromagnetic interference in ultra-high-field research magnets.
- Mechanical:Pneumatic transduction provides redundant backup for critical blood pressure measurement.
Electronic technology retains the largest installed footprint, though Hybrid architectures are expanding most quickly.
End User:
Customer type determines specification requirements from enterprise procurement to decentralized care delivery.
- Hospitals:Radiology departments and hybrid surgical suites drive specification standards for electromagnetic compatibility. United States health systems bundle monitor procurement with MRI service contracts.
- Emergency Services:Pre-hospital and intra-hospital transport applications demand ruggedized, battery-powered designs. European ambulance services in France and Germany pilot wireless monitoring for stroke imaging protocols.
- Homecare:Limited penetration due to magnetic field safety requirements and calibration complexity.
- Nursing Facilities:Minimal adoption constrained by capital equipment budgets and technical training gaps.
Hospitals command the dominant procurement volume, while Emergency Services are gaining share fastest.
Application:
Clinical workflow integration shapes how monitoring parameters align with specific imaging protocols.
- Cardiac Monitoring:ECG-gated imaging and arrhythmia detection during stress MRI require specialized fiber-optic pulse detection. FDA scrutiny of computational heart rate algorithms elevates validation costs for this segment.
- Blood Pressure Monitoring:Non-invasive pneumatic cuffs with optical backup serve interventional procedures and sedation monitoring. Anesthesia departments in Japanese university hospitals prioritize redundant measurement pathways.
- Respiratory Monitoring:Capnography and impedance pneumography support breath-hold coaching and sedation safety.
- Temperature Monitoring:Core temperature tracking prevents thermal injury during extended scanning protocols.
Cardiac Monitoring holds the dominant clinical priority, while Blood Pressure Monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber-optic component suppliers cluster in Germany, Switzerland, and Japan, creating regional dependencies for manufacturers sourcing MRI-compatible transducers. This concentration shapes procurement strategies across hospital radiology departments in North America, Europe, and Asia-Pacific.
United States
Hospital radiology departments drive consistent replacement cycles for portable monitors compatible with 1.5 to 7 Tesla MRI systems. FDA 510(k) clearance requirements compress product development timelines while elevating validation costs for domestic manufacturers. The Boston-Cambridge medical device corridor hosts development centers where hybrid optical-electronic architectures undergo preclinical testing for next-generation cardiac monitoring applications.
Germany
Academic medical centers in Heidelberg and Munich prioritize multi-parameter monitors for ultra-high-field 7 Tesla research environments. EU Medical Device Regulation conformity requirements accelerate procurement consolidation around validated suppliers with notified body certifications. The Baden-Württemberg precision optics cluster supplies fiber-optic pulse oximetry components to monitor manufacturers serving European hospital networks.
Japan
University hospitals in Tokyo and Osaka deploy redundant blood pressure monitoring systems for sedation protocols during extended cardiac MRI procedures. PMDA regulatory alignment with IEC 60601-1-2 electromagnetic compatibility standards streamlines market access for domestic and imported devices. The Nagoya medical electronics manufacturing base produces pneumatic transduction modules for integration into hybrid monitor architectures.
China
Tertiary care centers in Beijing and Shanghai expand installed MRI bases, creating procurement volume for backward-compatible monitoring equipment. NMPA registration requirements for Class II medical devices extend validation timelines for foreign manufacturers seeking hospital procurement channels. The Yangtze River Delta medical device manufacturing zone assembles electronic monitor components for domestic distribution and regional export.
Switzerland
Swissmedic certification requirements for MRI-compatible devices attract specialized manufacturers seeking premium European market positioning. The Basel-Zurich medtech corridor hosts engineering talent for electromagnetic interference shielding design in high-field magnetic environments. Swiss university hospitals collaborate with component suppliers on optical sensing validation for next-generation hybrid monitor platforms.
MR Vital Sign Monitors Market Competitive Landscape
Diversified imaging system manufacturers and specialized vital sign monitor producers split the market across bundled service contracts and standalone device procurement. The vendor base organizes into three strategic archetypes: integrated imaging equipment suppliers leveraging installed MRI bases, dedicated monitor specialists with fiber-optic sensing expertise, and diversified medical device conglomerates with multi-parameter platform portfolios. Competitive positioning depends on backward compatibility breadth, calibration service network density, and regulatory submission velocity. M&A activity concentrates on optical transducer technology acquisitions and regional service network expansion.
Within the integrated imaging equipment tier, GE Healthcare and Koninklijke Philips N.V. represent archetypes of vendors bundling monitor procurement with MRI system service contracts. Among specialized monitor developers, IRadimed Corp. occupies a position exemplifying wireless, battery-powered design focus for ambulatory MRI segments. These three companies anchor the competitive structure, with diversified medical device conglomerates and regional specialists filling procurement gaps in price-sensitive hospital segments and emerging market installations.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| IRadimed Corp. |
| Dragerwerk AG |
| Schiller AG |
| Spacelabs Healthcare |
| Mindray Medical International Limited |
| Nihon Kohden Corporation |
| Bayer |
| Others |
Value Network & Pricing Analysis
Fiber-optic component supply concentration in Germany, Switzerland, and Japan determines both pricing tier spreads and supply chain shape for MR vital sign monitors. Single-source dependencies on specialized optical transducers force manufacturers to absorb input cost volatility while passing premium positioning downstream to hospital buyers seeking 7 Tesla compatibility.
Pricing Analysis
FDA 510(k) clearance requirements dictate the pricing tier structure across the MR vital sign monitors landscape. Three-tier pricing structure across premium, standard, and economy levels separates fiber-optic hybrid systems from legacy electronic architectures and entry-level pneumatic backups. Certification grade and after-sales service bundling drive price differentiation, with premium tiers capturing calibration contract value. Cost compression in standard electronic segments is intensifying because of backward-compatible replacement demand in United States community hospitals. Emergency services buyers exhibit the highest price sensitivity, while academic medical centers with 7 Tesla research magnets demonstrate the least.
Supply Chain Analysis
Contract manufacturing for fiber-optic transduction modules concentrates with specialized EMS providers in the Nagoya medical electronics cluster and select Swiss precision optics foundries. Component sourcing draws from Germany, Japan, and Switzerland for optical sensing elements, with pneumatic module assembly anchored in China. Raw material dependencies include specialty optical fibers, electromagnetic shielding alloys, and high-precision pressure sensors. Single-source vulnerability around qualified fiber-optic cable suppliers creates lead time risk during demand surges. Distribution runs through direct hospital procurement channels and imaging equipment OEM bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from computational vital sign algorithms that could displace hardware-centric monitoring architectures. Defense requires pre-emptive software-enabled feature differentiation and regulatory capture of AI-driven predicate device pathways.
For Market Incumbents: Pre-empt algorithmic substitution by securing FDA computational validation datasets for machine learning-derived cardiac metrics before software-native entrants achieve clearance. Deepen backward integration into fiber-optic transducer production to reduce exposure to German and Swiss component supply volatility. Bundle remote telemetry support with hardware procurement to lock hospital radiology departments into multi-year service relationships that resist disintermediation. For New Entrants and Emerging Players: Underserved United States ambulatory MRI markets present white-space opportunity for wireless, battery-powered monitor deployment targeting mobile imaging services and standalone diagnostic centers. Target hybrid operating room construction pipelines in tertiary care expansion projects where procurement specifications remain fluid and vendor relationships unconsolidated. Pursue GPO contract penetration as the fastest go-to-market angle, leveraging price positioning against bundled incumbent offerings. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors optical sensing technology specialists with notified body certifications and established hospital procurement channels. Long-term viability rests on regulatory submission velocity and service network density rather than manufacturing scale alone. Monitor FDA guidance publication timelines on computational vital sign algorithms as the critical inflection signal for software-enabled valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines capture replacement cycle demand before competitor predicate devices lock hospital procurement. |
| CE Marking Pathway Investment | EU MDR conformity positions manufacturers for German academic medical center 7 Tesla research magnet installations. |
| Hospital System Partnership | Enterprise agreements with United States health systems displace standalone monitor purchases through integrated vendor relationships. |
| Software Companion Development | AI-driven vital sign interpretation creates recurring revenue models and differentiation against hardware-only competitors. |
| Reimbursement Strategy | CPT code alignment for cardiac MRI monitoring secures favorable hospital budget allocation and procurement priority. |
Research Methodology
Operator-level perspectives from hospital biomedical engineers, radiology department purchasing committees, GPO contracts managers, and imaging equipment service technicians anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, hospital procurement records, and IEC electromagnetic compatibility filings. Bottom-up unit demand modeling triangulated against top-down imaging equipment installation data.
Scenario-bracketing framed analytical projections across the analysis window, with volume and value outputs reflecting segmented modeling by product type, technology architecture, end-user category, and application. CAGRs derived from replacement cycle timing, MRI base expansion rates, and technology transition curves. Forecast inputs incorporated regulatory submission velocity assumptions and fiber-optic component supply lead time distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-native entrants or imaging equipment OEMs expanding monitoring capabilities would shift outcomes. Quarterly review of FDA computational algorithm guidance publication, 510(k) clearance backlogs, and fiber-optic supplier order book indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Neuro-Monitoring System Market