
 Disposable Medical Gowns Market | 2026-2036
Disposable Medical Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Medical Gowns Market Outlook
Market Dynamics and Strategic Positioning
China's expanded nonwoven fabric capacity is reshaping raw material availability for disposable medical gown producers worldwide. Cardinal Health leverages its domestic distribution network to sustain contract volume with integrated delivery networks across the United States. Medline Industries anchors its competitive stance through direct sales channels that bypass traditional distributor markups for large hospital systems. Owens & Minor competes on logistics density, positioning its warehouse footprint to guarantee next-day fulfillment to rural acute-care facilities.
Product Architecture and Segment Structure
Disposable medical gowns are single-use protective garments engineered from spunbond-meltblown-spunbond (SMS) laminates, polyethylene films, or polypropylene nonwovens, designed to achieve AAMI PB70 liquid barrier ratings Level 1 through Level 4 for isolation, surgical, and contamination-control applications. Surgical gowns command premium pricing due to stringent sterility assurance and reinforced critical zones, while isolation gowns dominate volume throughput in emergency departments and long-term care settings. Polypropylene and SMS fabric categories capture the majority of material demand as hospitals phase out reusable linen programs to reduce cross-contamination risk and laundry logistics overhead.
Regulatory Environment and Forward Outlook
The FDA enforces AAMI PB70 and ASTM F2407 standards for liquid barrier classification, while the EU Medical Device Regulation (MDR) mandates clinical evaluation and post-market surveillance for gowns sold in European member states. India's CDSCO has aligned with ISO 16603 and ISO 16604 blood and viral penetration testing protocols, tightening market entry for imported protective apparel. Stakeholders must monitor evolving biocompatibility requirements and track regulatory divergence between major markets to avoid certificate gaps that could block tender participation or trigger supply chain requalification costs.
Market Dynamics
China's nonwoven fabric capacity expansion is compressing raw material costs for disposable medical gown manufacturers while simultaneously creating supply concentration risks that reshape procurement strategies across the value chain.
Growth Catalysts
- AAMI PB70 Level 4 Adoption:The FDA's updated liquid barrier guidance is accelerating hospital procurement of higher-grade SMS surgical gowns to meet sterility assurance requirements in critical care settings.
- Tier-2 and Tier-3 India Hospital Expansion:India's CDSCO alignment with ISO 16603 viral penetration standards is modernizing protective apparel procurement as hospital infrastructure spreads beyond metropolitan centers.
- Spunbond-meltblown-spunbond Fabric Innovation:Advanced SMS laminate constructions are displacing polyethylene films in isolation gown applications due to superior breathability-barrier balance.
Market Restraints
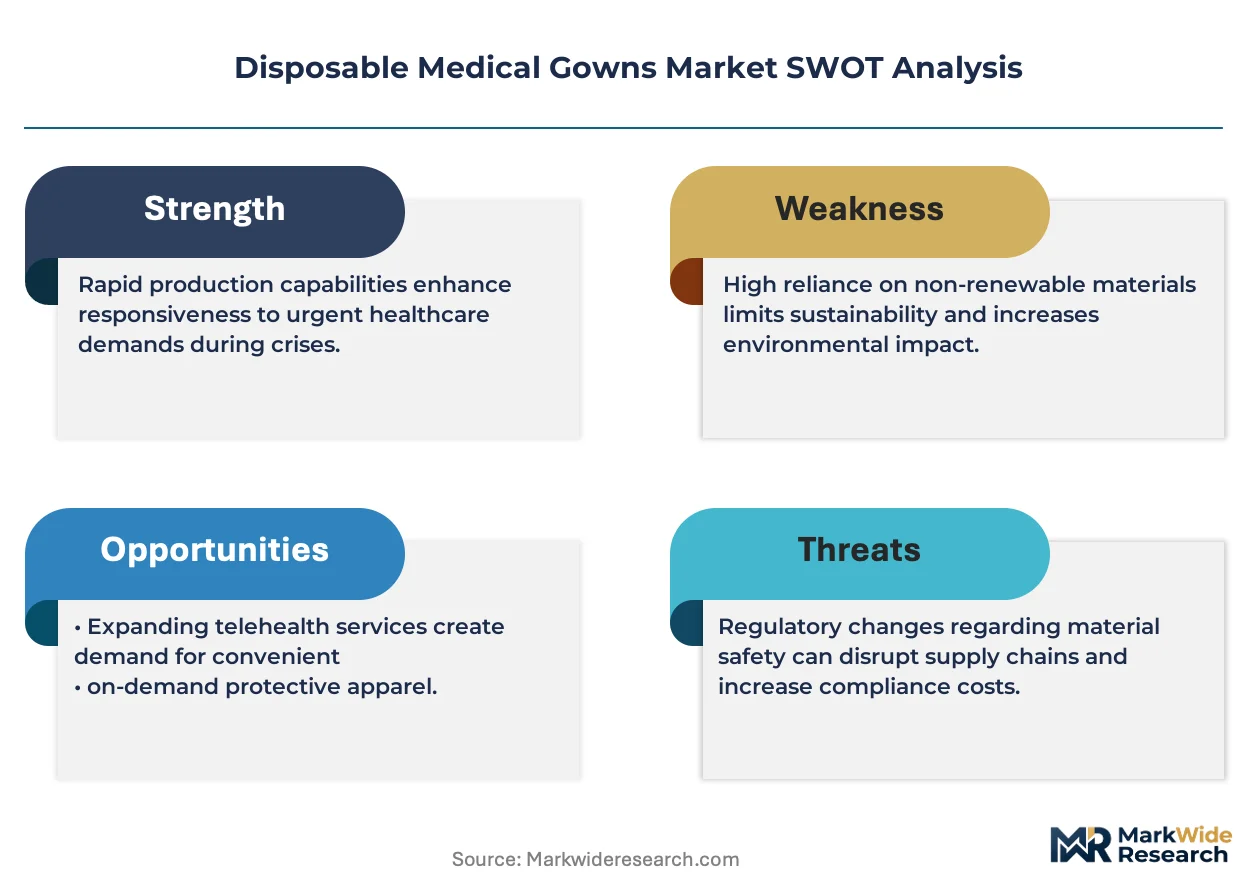
- Polypropylene Feedstock Volatility:Crude oil price fluctuations directly compress margins for nonwoven fabric converters dependent on petrochemical-derived raw materials.
- China Supply Concentration:Overreliance on Zhejiang and Jiangsu province nonwoven producers creates vulnerability to regional logistics disruptions and export control shifts.
- Reusable Linen Program Persistence:European healthcare systems with established industrial laundry infrastructure resist full conversion to single-use alternatives despite cross-contamination evidence.
Strategic Opportunities
- EU MDR Certification Arbitrage:Manufacturers achieving CE marking under the Medical Device Regulation's clinical evaluation requirements gain preferential access to tender pools in Germany, France, and Benelux markets.
- Ambulatory Surgical Center Channel:Outpatient procedure volume growth in United States freestanding surgical facilities creates demand for procedure-matched gown SKUs bypassing traditional hospital procurement.
- Biodegradable Nonwoven Convergence:PLA-cellulose fiber blends meeting ASTM F3352 biodegradability standards are opening sustainability-premium positioning in Nordic and North American institutional buyers.
Industry Challenges
- AAMI PB70 Testing Bottleneck:Limited third-party laboratory capacity for liquid barrier certification extends product launch timelines and strains R&D budgets for mid-tier manufacturers.
- Legacy ERP Integration Friction:Hospital systems migrating to cloud-based procurement platforms require SKU rationalization that conflicts with gown manufacturers' broad product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Medical Gowns Market |
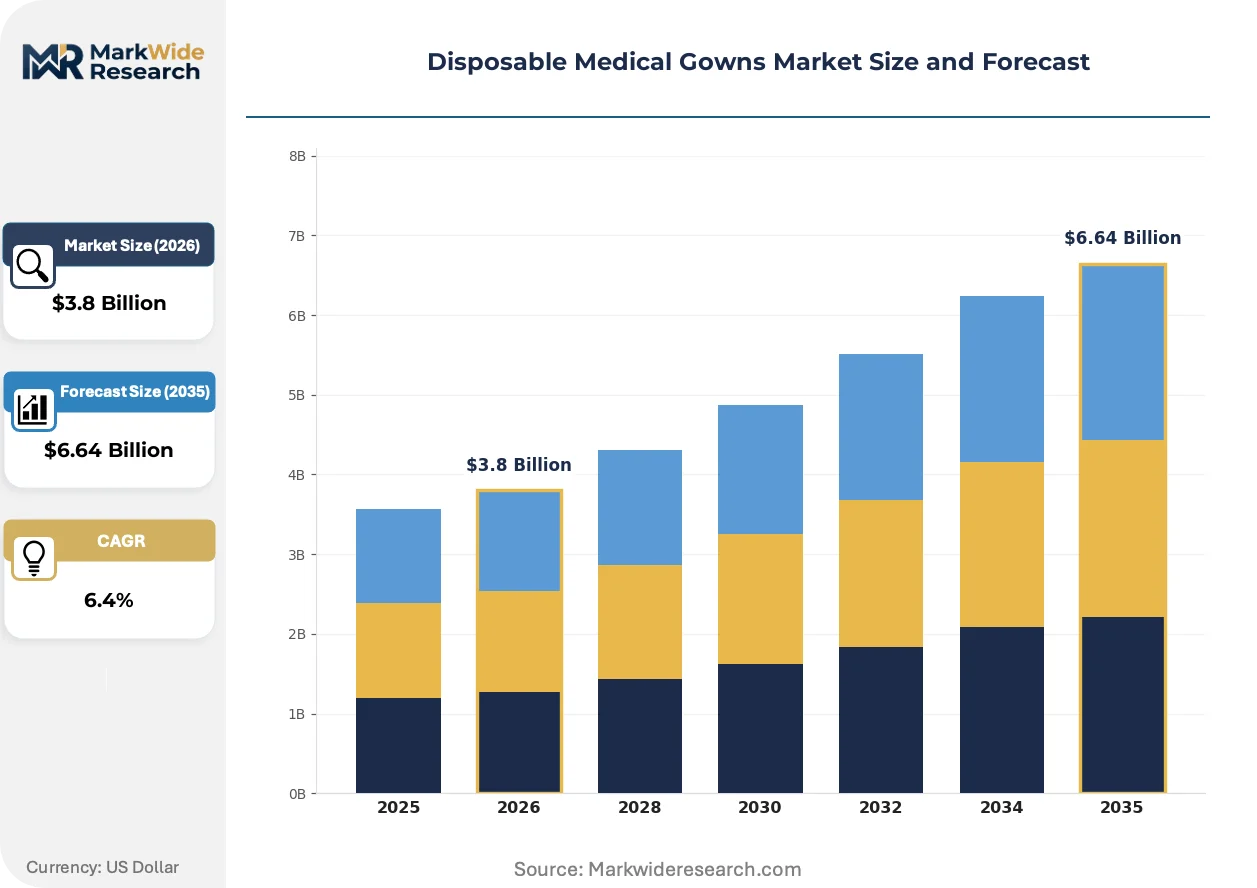
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Surgical Gowns, Surgical Gowns, Isolation Gowns, Coveralls Material: Polyethylene, Polypropylene, SMS Fabric, PVC End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Wholesalers |
| Companies Covered | Cardinal Health, 3M, Medline Industries, Standard Textile, Angelica, Owens & Minor, Mölnlycke Health Care, Ahlstrom-Munksjö, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Medical Gowns Market Strategic Shifts
Digital manufacturing and regulatory digitization are converging to compress product development cycles while sustainability pressures force material science breakthroughs in barrier performance without petrochemical dependence.
Spunbond-meltblown-spunbond laminates with nanofiber interlayers are achieving AAMI Level 4 protection at reduced basis weights. Academic medical centers in the United States are piloting these constructions for extended-duration surgical procedures. The technology is virtualizing traditional multi-layer polyethylene alternatives by consolidating barrier and comfort functions into single-substrate solutions.
The EU Medical Device Regulation's post-market surveillance database is mandating traceable lot-level performance documentation for gowns sold in European member states. Manufacturers must now maintain clinical evaluation reports that track real-world barrier failure incidents. Surgical gown suppliers with integrated quality management systems are capturing disproportionate tender share in France and Germany where notified body scrutiny is most intensive.
Integrated delivery networks in the United States are consolidating vendor lists through master service agreements that bundle gowns with gloves, drapes, and sterilization wraps. Independent ambulatory surgery centers face exclusion from these contracts and are responding by forming purchasing cooperatives that aggregate volume for direct manufacturer negotiation. This channel restructuring is most visible in Texas and Florida where ASC construction permits have accelerated post-pandemic.
Disposable Medical Gowns Market Segmentation
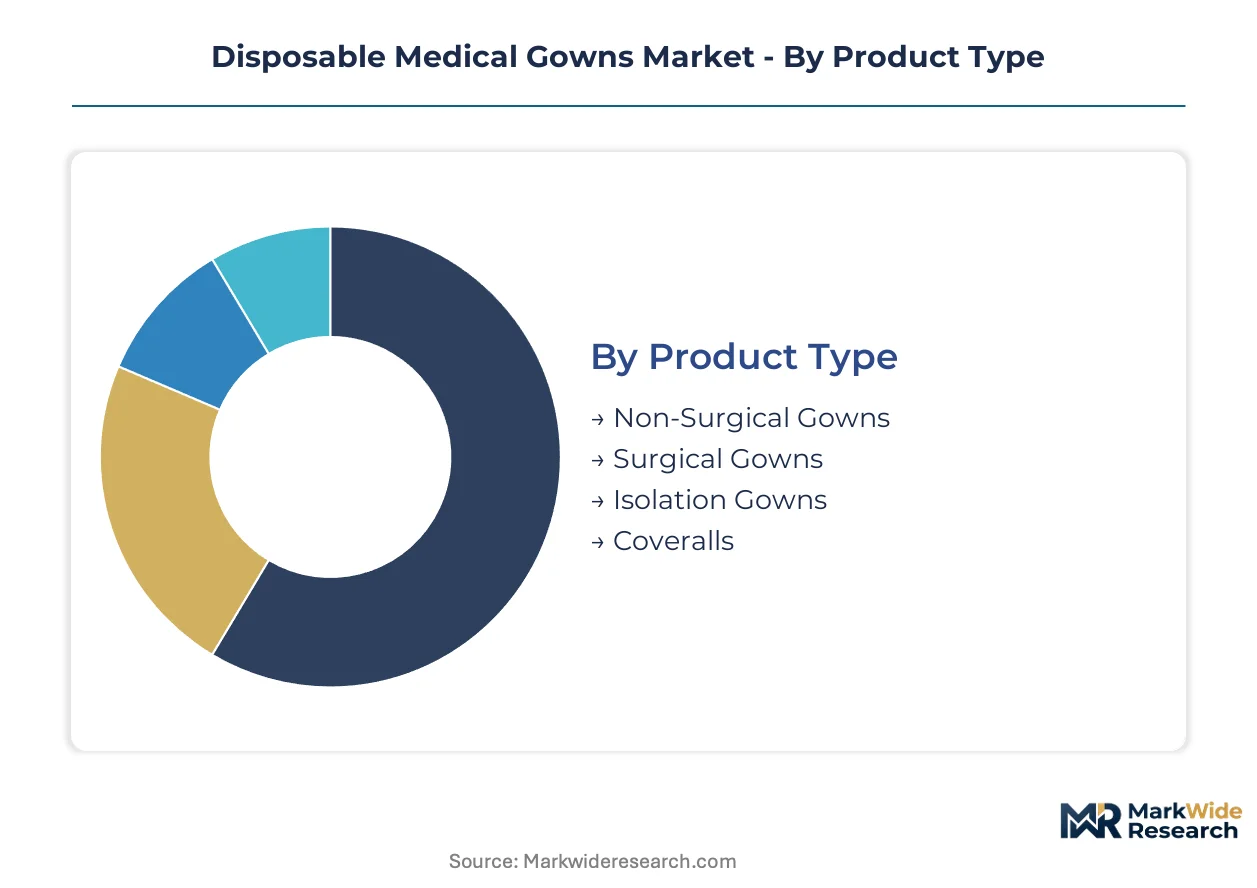
Disposable medical gown segmentation reveals distinct consumption velocities across product tiers, with surgical applications demanding extended wear cycles while isolation protocols drive rapid turnover. Material specifications and distribution pathways further stratify procurement patterns, creating parallel supply chains optimized for either bulk throughput or premium sterility assurance.
Product Type:
Cycle times vary dramatically across gown categories, with surgical procedures requiring extended-duration barrier integrity while emergency isolation protocols consume garments at accelerated rates.
- Surgical Gowns:Engineered with reinforced critical zones and AAMI PB70 Level 3-4 barrier ratings, these garments withstand multi-hour operative procedures. Demand concentrates in academic medical centers and tertiary hospitals performing complex cardiothoracic and orthopedic interventions, where sterility breach carries catastrophic liability exposure.
- Isolation Gowns:Standard AAMI Level 1-2 constructions designed for single-patient contact duration in emergency departments and infectious disease wards. These garments rotate fastest in high-throughput settings, with some facilities consuming multiple units per patient encounter during outbreak protocols.
- Non-Surgical Gowns:Basic protective apparel for visitor screening and administrative contamination control in hospital entryways.
- Coveralls:Full-body protective systems deployed in biocontainment units and hazardous material response scenarios.
Isolation gowns anchor the volume base while surgical gowns gain share at the steepest rate as procedure complexity escalates across developed healthcare systems.
Material:
Cost tiers separate commodity-grade solutions from engineered laminates, with raw material selection directly determining barrier performance certification and end-market access.
- SMS Fabric:Spunbond-meltblown-spunbond laminates deliver the optimal breathability-barrier balance for extended surgical wear. These constructions dominate procurement in Germany, France, and the United States where AAMI PB70 Level 3-4 compliance is mandatory for operative settings.
- Polypropylene:Spunbond nonwovens provide economical isolation protection for short-duration applications. Demand concentrates in India's tier-2 and tier-3 hospital expansion, where CDSCO-aligned ISO 16603 testing is modernizing procurement standards without requiring premium laminate costs.
- Polyethylene:Film-based impermeable barriers for high-fluid-exposure procedures in labor and delivery suites.
- PVC:Heavy-duty chemical-resistant constructions for industrial hygiene and specialized decontamination operations.
Polypropylene materials anchor the volume base while SMS fabric gains share at the steepest rate as regulatory pressure elevates minimum barrier standards.
End User:
Customer scale determines procurement sophistication, with integrated delivery networks negotiating master service agreements while independent operators purchase through fragmented channels.
- Hospitals:Multi-thousand-bed systems with dedicated supply chain functions and vendor consolidation programs. These institutions drive specification-grade demand for AAMI PB70 Level 3-4 surgical gowns, particularly in the United States where integrated delivery networks bundle protective apparel across dozens of facilities.
- Clinics:Outpatient diagnostic and minor procedure centers with limited storage capacity and just-in-time inventory requirements. Demand clusters in ambulatory surgical centers across Texas and Florida, where purchasing cooperatives aggregate volume for direct manufacturer negotiation.
- Long-term Care Facilities:Extended-stay institutions with standardized isolation protocols and high staff-to-patient ratios driving consistent gown throughput.
- Home Healthcare:Dispersed delivery models requiring retail-packaged solutions and direct-to-consumer logistics infrastructure.
Hospital procurement anchors the volume base while clinic channels gain share at the steepest rate as outpatient procedure migration accelerates.
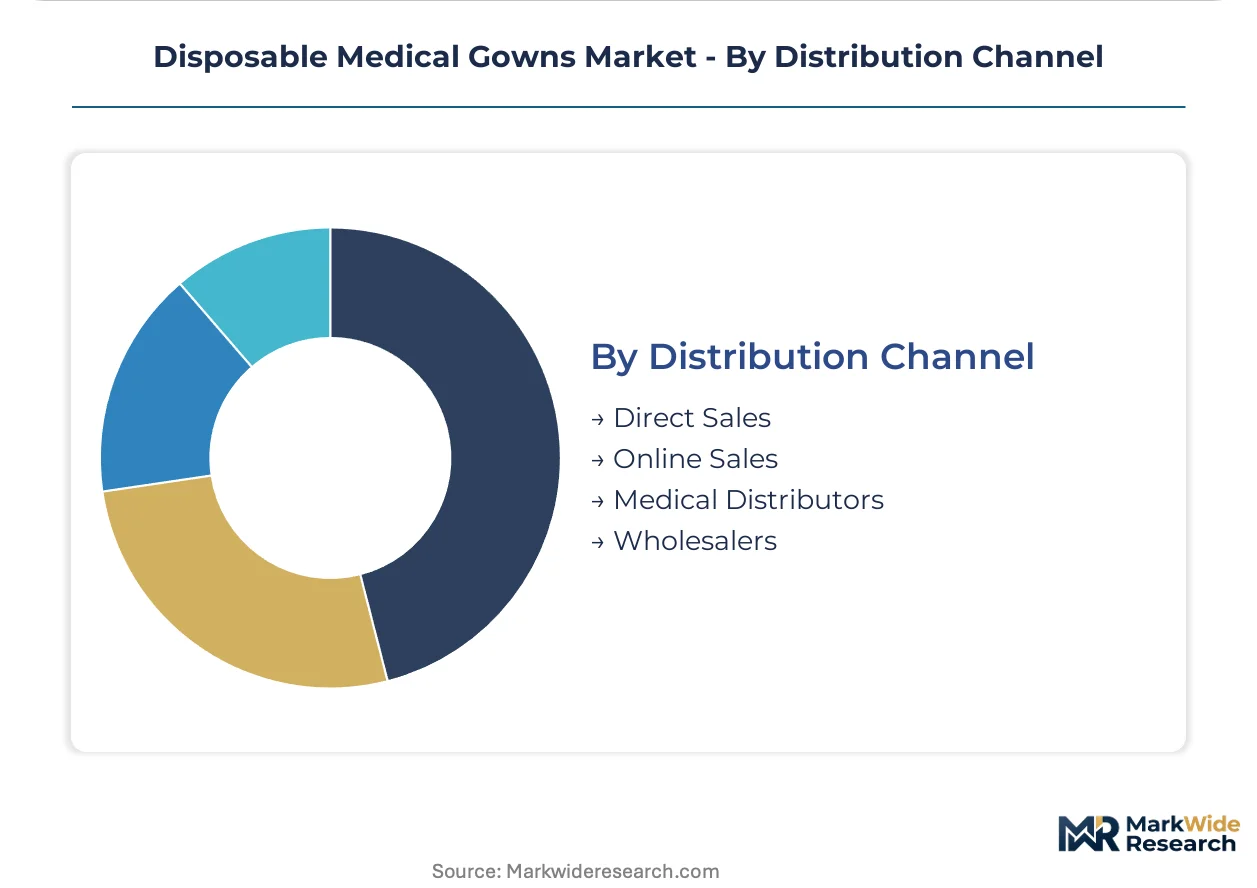
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with complex gown specifications demanding direct manufacturer relationships.
- Direct Sales:Manufacturer-to-institution relationships for large hospital systems with dedicated account management and custom SKU requirements. These channels bypass distributor markups and enable lot-level traceability compliance with EU MDR post-market surveillance mandates.
- Medical Distributors:Regional and national intermediaries maintaining local inventory positions for same-day fulfillment to mid-sized acute care facilities. Owens & Minor competes aggressively through warehouse density guaranteeing next-day delivery to rural hospitals.
- Online Sales:E-commerce platforms serving small clinics and individual practitioners with standardized product configurations and credit-card purchasing.
- Wholesalers:Bulk aggregators supplying group purchasing organizations and international trading companies with container-load quantities.
Medical distributors anchor the volume base while direct sales channels gain share at the steepest rate as vendor consolidation programs concentrate purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material fabrication clusters in Zhejiang and Jiangsu provinces supply nonwoven substrates to converters worldwide, creating interdependence between Asian supply nodes and Western healthcare procurement systems. Hospital infrastructure buildouts in emerging economies and sterility assurance mandates in developed markets generate divergent demand profiles across geographies.
United States
Ambulatory surgical centers in Texas and Florida are expanding single-use protective apparel procurement as outpatient procedure volumes rise. The FDA enforces AAMI PB70 liquid barrier ratings that push integrated delivery networks toward Level 3-4 SMS surgical gowns. Owens & Minor leverages warehouse density across the Southeast to guarantee next-day fulfillment to rural acute-care facilities.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive specification-grade demand for extended-duration surgical gowns with reinforced critical zones. The EU Medical Device Regulation mandates clinical evaluation reports and post-market surveillance databases for barrier performance documentation. Notified body scrutiny concentrates in Frankfurt and Munich, favoring suppliers with integrated quality management systems.
India
Hospital infrastructure modernization accelerates across tier-2 and tier-3 cities in Maharashtra and Gujarat, concentrating procurement authority in state-level tender pools. The CDSCO aligns with ISO 16603 and ISO 16604 blood and viral penetration testing protocols, tightening market entry for imported protective apparel. Domestic nonwoven converters in Ahmedabad and Pune are scaling capacity to meet public hospital demand.
China
Zhejiang and Jiangsu province fabricators expanded spunbond-meltblown-spunbond laminate capacity throughout 2023-2024, compressing raw material costs for global gown manufacturers. The NMPA enforces GB standards for medical protective equipment while provincial export controls create intermittent supply uncertainty. Shanghai-based trading companies aggregate container-load volumes for re-export to Southeast Asian hospital systems.
Brazil
Hospital networks in São Paulo and Minas Gerais are converting from reusable linen programs to single-use alternatives despite established industrial laundry infrastructure. ANVISA regulates liquid barrier performance for imported surgical apparel, creating certificate gaps that delay tender participation. Regional distributors in Rio de Janeiro maintain inventory positions for same-day fulfillment to mid-sized private hospitals.
Disposable Medical Gowns Market Competitive Environment
Integrated distributors and direct-sales manufacturers split the market between logistics-density positioning and vendor consolidation bypass. The vendor base concentrates around three strategic archetypes: diversified healthcare conglomerates with broad protective apparel portfolios, specialized nonwoven converters with captive fabric supply, and regional distributors competing on warehouse footprint and fulfillment velocity. M&A activity targets vertical integration into SMS laminate production, while strategic partnerships between converters and sterilization wrap manufacturers bundle gown procurement across hospital system contracts.
Among diversified healthcare conglomerates, Cardinal Health and Medline Industries exemplify contrasting channel strategies. Cardinal leverages domestic distribution infrastructure to sustain contract volume with integrated delivery networks, while Medline anchors its position through direct sales relationships that bypass traditional distributor markups for large hospital systems. Owens & Minor occupies a logistics-specialist position, competing on warehouse density to guarantee next-day fulfillment to rural acute-care facilities across the United States.
| Leading Market Players |
|---|
| Cardinal Health |
| 3M |
| Medline Industries |
| Standard Textile |
| Angelica |
| Owens & Minor |
| Mölnlycke Health Care |
| Ahlstrom-Munksjö |
| McKesson Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Zhejiang and Jiangsu province nonwoven fabricators determines both the pricing tier spreads between SMS surgical gowns and polypropylene isolation garments and the supply chain shape favoring consolidated procurement through integrated delivery networks or direct manufacturer relationships.
Pricing Analysis
AAMI PB70 liquid barrier certification dictates the pricing tier structure across the disposable medical gowns market, separating premium Level 3-4 SMS surgical constructions from standard Level 1-2 polypropylene isolation alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with academic medical centers least price-sensitive due to liability exposure and tier-2 Indian hospitals most sensitive amid infrastructure modernization budgets. Pricing pressure stems from polypropylene feedstock volatility tied to crude oil fluctuations, compressing margins for nonwoven converters without captive resin supply.
Supply Chain Analysis
Extended payment terms from large hospital systems and supply-chain finance facilities anchored in Shanghai trading companies lubricate working capital flows for mid-tier converters lacking balance sheet depth. Raw material fabrication concentrates in China, India, and the United States, with spunbond-meltblown-spunbond laminates, polypropylene resin, and polyethylene films serving as critical inputs. Single-source vulnerability to Zhejiang province export controls creates intermittent supply uncertainty. Distribution runs through medical distributors maintaining regional warehouse density for same-day fulfillment to mid-sized acute care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable medical gowns market is entering a cyclical recovery phase as hospital capital expenditure budgets normalize following pandemic-era stockpiling depletion and outpatient procedure volumes rebound across developed healthcare systems.
For Market Incumbents: Harden supply chain resilience through backward integration into SMS laminate production or captive nonwoven fabric supply in India to offset China concentration risk. Deepen hospital system partnerships by embedding lot-level traceability systems that satisfy EU MDR post-market surveillance mandates, converting compliance burden into contract stickiness against emerging entrants lacking integrated quality management infrastructure.
For New Entrants and Emerging Players: Ambulatory surgical center purchasing cooperatives in Texas and Florida represent the most penetrable entry point, bypassing integrated delivery network vendor consolidation walls through aggregated volume negotiation. CDSCO-aligned ISO 16603 certification for India's tier-2 and tier-3 hospital expansion offers a regulatory-compliant beachhead without AAMI PB70 Level 4 investment. Direct sales channel establishment targeting freestanding surgical facilities enables margin capture unavailable through traditional distributor relationships.
For Investors and Strategic Acquirers: EU MDR notified body scrutiny intensification reshapes the acquisition landscape toward converters with existing CE marking and clinical evaluation report infrastructure. Long-term viability centers on five-to-ten year vendor consolidation tailwinds in United States healthcare procurement. Acquisition target archetype: mid-cap SMS laminate specialists with EU quality management integration and underutilized capacity in India or Southeast Asia. Monitor FDA liquid barrier guidance revision timing as inflection indicator for surgical gown premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements favor early movers in notified body relationships. |
| Backward Integration into SMS Fabric | Captive nonwoven supply insulates margin compression from polypropylene resin volatility. |
| Hospital System Partnership | Integrated delivery network master service agreements bundle gowns across multi-facility contracts. |
| CDSCO Certification Investment | ISO 16603 alignment unlocks India's tier-2 and tier-3 public hospital tender participation. |
| Ambulatory Surgical Center Channel Development | Texas and Florida ASC cooperatives aggregate volume for direct manufacturer negotiation bypassing distributors. |
Study Parameters
A standing panel of hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and nonwoven converter operations executives provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, CDSCO import registration databases, EU MDR notified body certificates, and hospital procurement contract repositories. Bottom-up facility-level demand modeling and top-down healthcare expenditure allocation triangulated volume estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying hospital capital expenditure recovery assumptions. Segmentation dimensions included product type tier, material specification, end-user scale, and distribution channel structure. CAGRs derived from procedure volume elasticity analysis, regulatory compliance cost pass-through coefficients, and raw material cost curve projections. Industry-specific forecast inputs incorporated AAMI PB70 adoption curve timing and ambulatory surgical center construction permit velocity in key United States markets.
Practitioners should monitor polypropylene feedstock price volatility, FDA barrier guidance revision timing, and China export control policy shifts for early signals of forecast deviation. Forecasts reflect assumptions regarding hospital infrastructure modernization pacing and regulatory harmonization trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Disposables Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Suture Wire Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Global Lancets Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Microcarrier Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Syringes and Cannulas Market