
 Plasma Collection Containers Market | 2026-2036
Plasma Collection Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Collection Containers Market Analytics
Multi-source procurement of polymer resins is expanding across the plasma container supply base. Grifols leverages captive plasma collection networks to secure downstream container demand. Becton Dickinson and Company anchors North American hospital supply chains through integrated distribution. Terumo BCT differentiates in automated apheresis systems that specify proprietary container interfaces.
Plasma collection containers are sterile, single-use vessels engineered from medical-grade plastics or glass, designed to maintain anticoagulant stability and prevent hemolysis during centrifugation and frozen storage. These containers must meet biocompatibility standards for extended plasma preservation at negative temperatures while enabling sterile docking and transfer to fractionation equipment. Bag systems dominate current procurement volumes due to their flexibility in high-throughput apheresis procedures, while pre-filled containers represent the fastest-expanding category as hospitals seek to reduce compounding errors and streamline therapeutic plasma exchange workflows. Polypropylene is displacing PVC in premium container lines because regulators in Germany and France are scrutinizing plasticizer leachables under REACH and MDR frameworks.
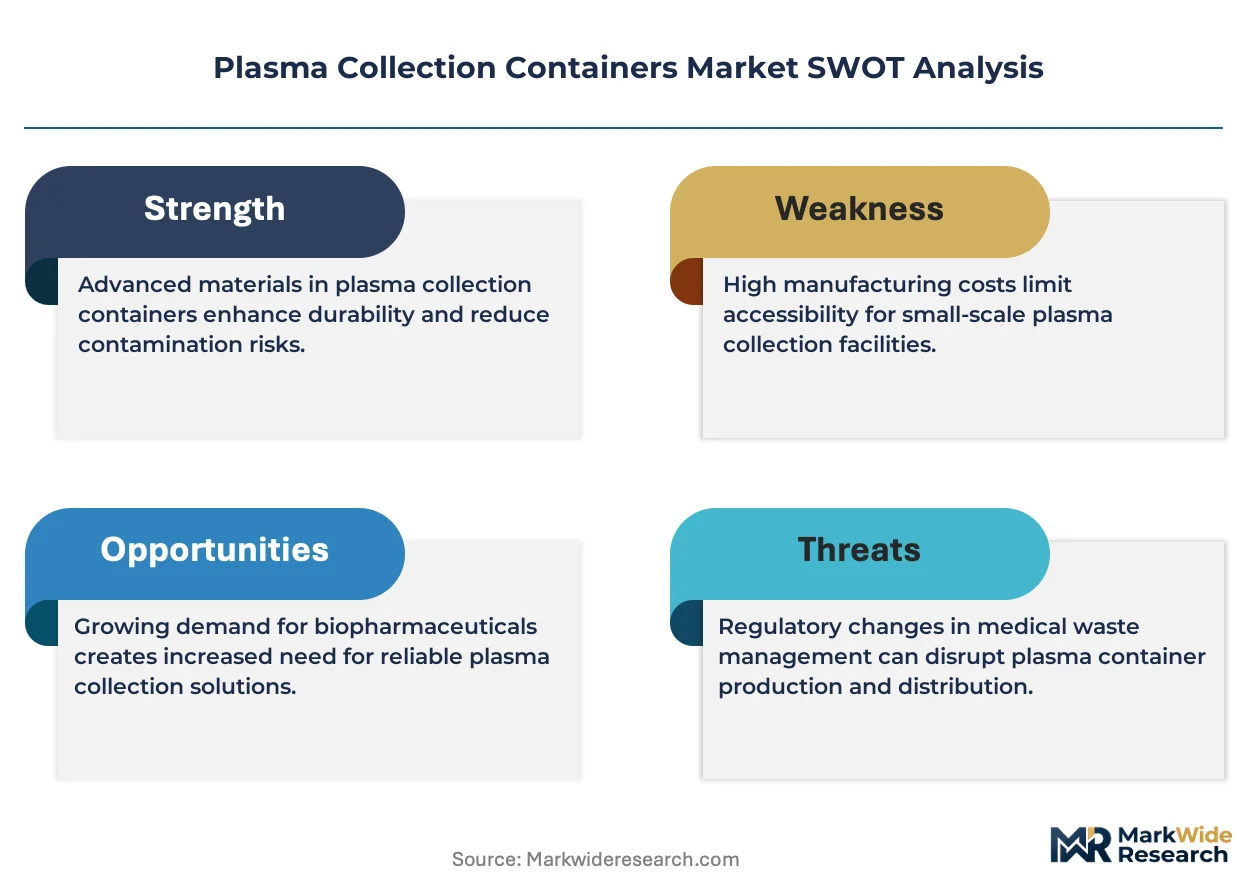
The FDA enforces container sterility and pyrogenicity standards through biologics licensing requirements, while the EMA's Medical Device Regulation mandates clinical evidence for container-plasma interaction. The EU F-Gas Regulation indirectly shapes demand by restricting blowing agents used in certain polymer foams that insulate cold-chain shipping containers. Stakeholders must monitor evolving leachable testing protocols and decide whether to absorb certification costs or exit higher-regulation jurisdictions.
Market Dynamics
Automated apheresis protocols are compressing collection cycle times while tightening container interface specifications, forcing suppliers to redesign docking geometries and anticoagulant stabilization chemistry simultaneously.
Growth Catalysts
- EMA Medical Device Regulation:Clinical evidence mandates for container-plasma interaction are accelerating R&D investment in biocompatibility testing infrastructure across German and French manufacturing bases.
- Pre-filled container formats:Hospitals in high-throughput therapeutic plasma exchange programs are specifying ready-to-use systems that eliminate compounding errors and reduce nursing labor per procedure.
- Polypropylene substitution:REACH scrutiny of phthalate plasticizers in PVC is redirecting procurement toward medical-grade polypropylene lines with validated sub-zero performance profiles.
Market Restraints
- Specialized polymer resin concentration:Medical-grade polypropylene supply concentrates among a handful of European petrochemical producers, exposing container manufacturers to input allocation risk during feedstock disruptions.
- Leachable testing burden:FDA biologics licensing requirements for extended extractables studies extend certification timelines by 18-24 months for novel material formulations.
- Glass container residual demand:Certain fractionation protocols in Japan and Switzerland retain glass preference for specific immunoglobulin collection workflows, fragmenting material standardization efforts.
Strategic Opportunities
- India plasma infrastructure buildout:CDSCO pathway harmonization with ICH standards is enabling multinational container suppliers to qualify products for India's expanding blood bank modernization programs.
- Cold-chain integration:EU F-Gas Regulation restrictions on insulating foam blowing agents are creating openings for vacuum-insulated container systems that maintain plasma stability through multi-day transport.
- RFID-enabled traceability:Convergence of container manufacturing with sensor embedding is electrifying demand for units that transmit temperature and chain-of-custody data to fractionation facility ERP systems.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in low-temperature medical polymer behavior command premium compensation, constraining R&D expansion at mid-tier container producers.
- Legacy apheresis equipment retrofit:Proprietary container interfaces from established automated collection systems create integration friction for suppliers introducing standardized docking designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Collection Containers Market |
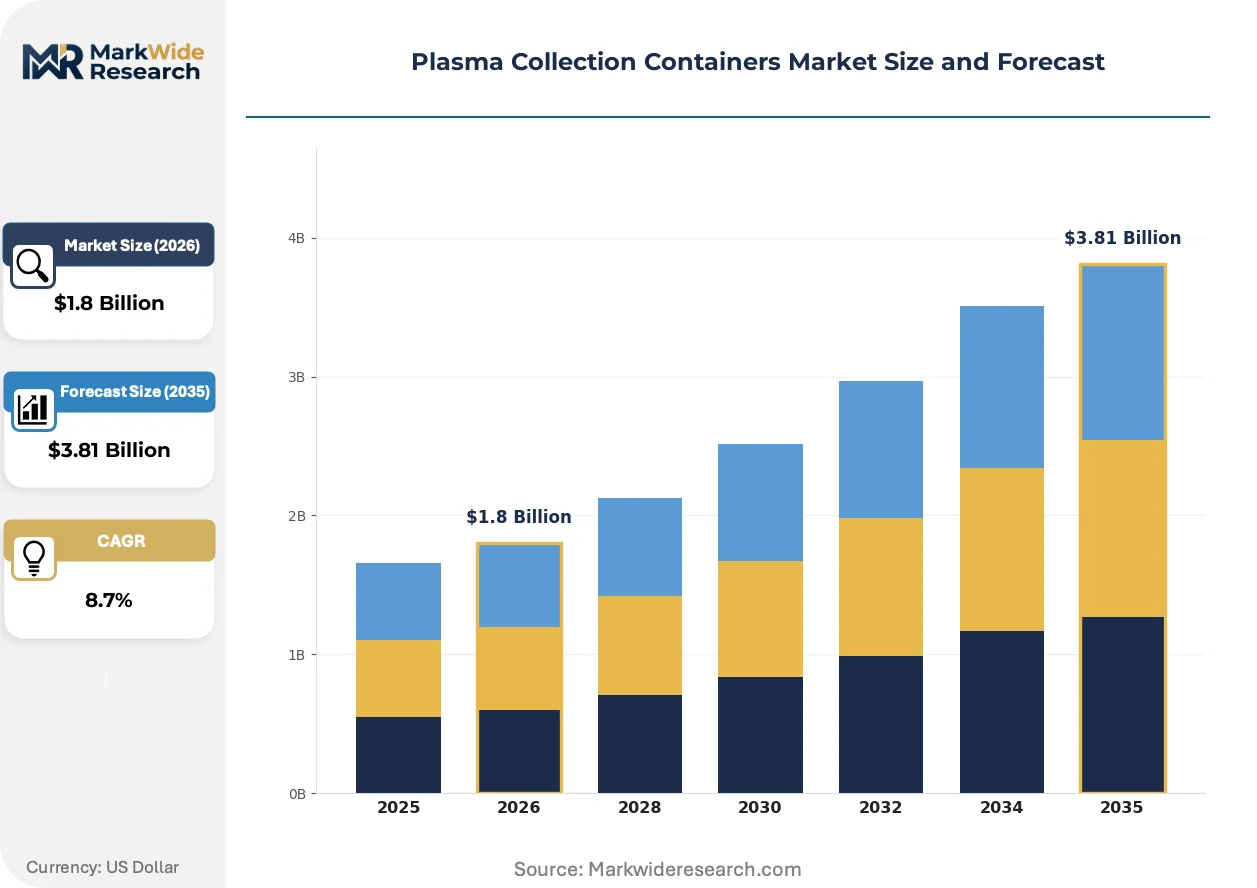
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bag Systems, Vial Systems, Tube Systems, Pre-filled Containers Material: Polyethylene, Polypropylene, PVC, Glass End User: Blood Banks, Hospitals, Diagnostic Laboratories, Research Institutions Application: Therapeutic Apheresis, Transfusion, Research, Diagnostic Testing |
| Companies Covered | Grifols, CSL Behring, Takeda Pharmaceutical Company, Becton Dickinson and Company, Terumo BCT, Fresenius Kabi, SARSTEDT AG, Greiner Bio-One, MEISE Medizintechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Collection Containers Market Evolving Landscape
Material science advances and regulatory chemistry requirements are converging to redefine container performance specifications, with particular pressure on extractables profiles and automated handling compatibility.
Closed-system transfer devices with integrated sterile docking ports are electrifying workflow efficiency in high-volume apheresis centers. Blood banks across Germany and the United States are specifying these systems to reduce contamination risk during plasma transfer to frozen storage. The technology is compressing labor requirements per collection while elevating barrier integrity standards for downstream container suppliers.
REACH authorization requirements for di(2-ethylhexyl) phthalate in medical applications are forcing PVC-dependent container lines toward alternative plasticizer systems or complete material substitution. German regulators at ECHA are prioritizing review of blood contact applications, accelerating industry transition timelines. Container producers with validated polypropylene platforms are capturing procurement preference from fractionators seeking regulatory certainty.
Consolidated buying by integrated plasma networks is compressing supplier margins while elevating service requirements. Large collection operators in Spain and the United States are unbundling container procurement from apheresis equipment service contracts, creating direct negotiation leverage. This pattern is most visible in North America, where captive collection networks specify container volumes across multi-year agreements with penalty clauses for supply disruption.
Plasma Collection Containers Market Segmentation
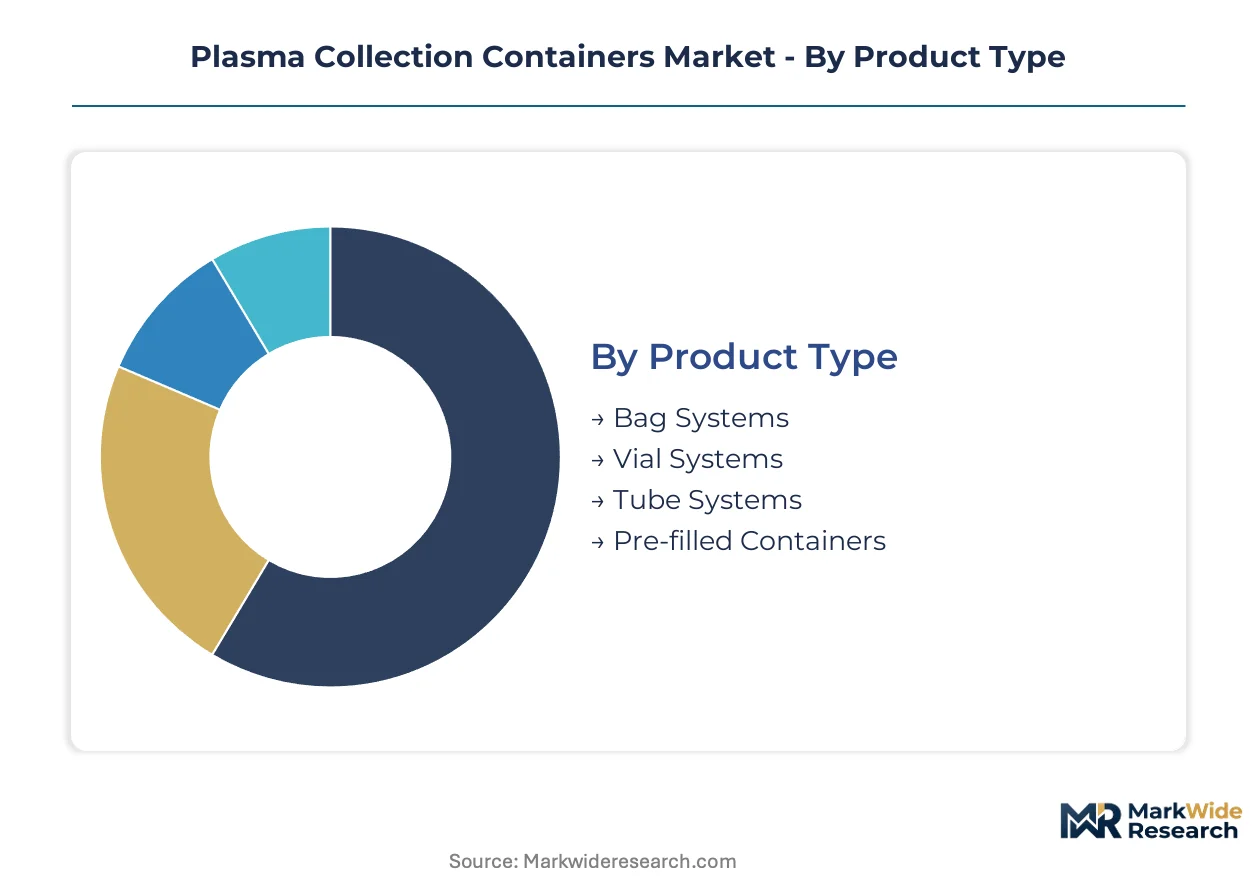
Container specifications diverge sharply between standalone collection workflows and integrated apheresis systems. Material selection and interface geometry determine compatibility with automated equipment and frozen storage protocols.
Product Type:
Bag systems operate as standalone collection vessels while pre-filled formats embed directly into closed therapeutic workflows.
- Bag Systems:Flexible multi-chamber designs fabricated from medical-grade polymers accommodate centrifugation and frozen storage at negative temperatures. Demand clusters in German and US blood banks scaling automated apheresis throughput. REACH compliance pressures are accelerating polypropylene adoption over legacy PVC formulations.
- Pre-filled Containers:Anticoagulant-stabilized units arrive ready for immediate therapeutic plasma exchange procedures. Hospitals in high-volume exchange programs specify these to eliminate compounding errors and reduce nursing labor per collection cycle.
- Vial Systems:Rigid cylindrical formats serve diagnostic sampling and small-volume research applications requiring precise aliquot extraction.
- Tube Systems:Connected vessel arrays enable sequential collection and processing steps within closed automated platforms.
Volume placements concentrate in bag systems; the faster expansion belongs to pre-filled containers.
Material:
Cost tiers separate commodity polymers from validated medical grades with sub-zero performance certification.
- Polypropylene:Crystalline thermoplastic with validated mechanical stability across plasma preservation temperatures. German fractionators are specifying medical-grade lines to preempt ECHA authorization reviews of phthalate plasticizers.
- PVC:Legacy material facing regulatory pressure from REACH di(2-ethylhexyl) phthalate scrutiny. Container producers with PVC-dependent lines are absorbing extended extractables testing burdens or accelerating material transition timelines.
- Polyethylene:Lower-density alternative for non-frozen transport applications and short-duration storage workflows.
- Glass:Retained in Japanese and Swiss immunoglobulin collection protocols where inert surface properties outweigh handling fragility concerns.
Procurement volumes favor polypropylene; glass maintains residual share in specialized fractionation segments.
End User:
Customer type determines volume scale and service intensity requirements across the supply base.
- Blood Banks:High-throughput collection centers specify container systems integrated with automated apheresis platforms. Captive plasma networks in Spain and the United States are consolidating procurement leverage across multi-year supply agreements.
- Hospitals:Therapeutic plasma exchange programs drive demand for pre-filled formats that streamline nursing workflows and reduce procedural error rates.
- Diagnostic Laboratories:Moderate-volume consumers prioritizing sterility assurance and lot traceability for analytical sample integrity.
- Research Institutions:Fragmented demand with specialized requirements for small-batch custom configurations and extended stability documentation.
Revenue concentration sits with blood banks; hospitals are climbing the fastest on pre-filled format adoption.
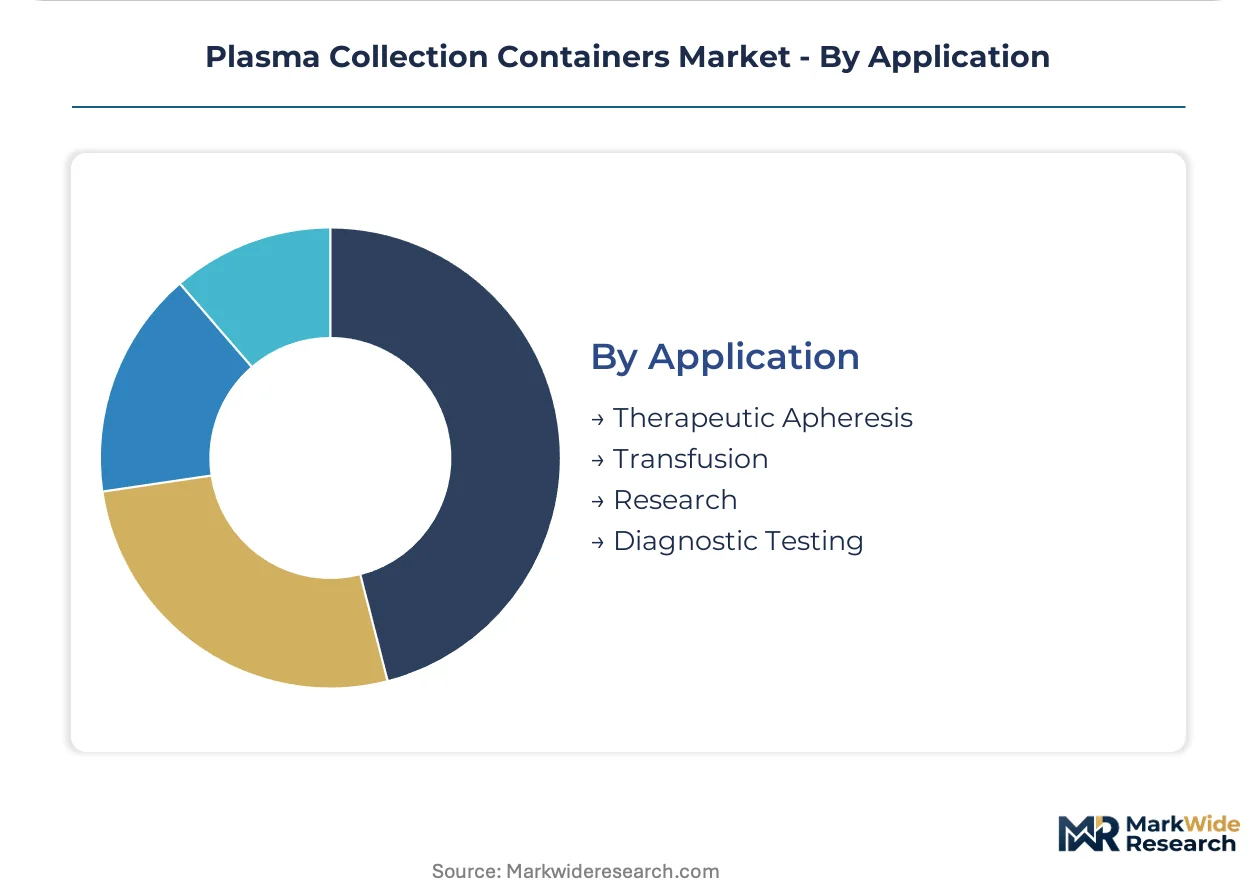
Application:
Maturity levels separate established transfusion workflows from emerging therapeutic and research segments.
- Therapeutic Apheresis:Plasma exchange procedures for autoimmune and neurological conditions require containers with validated anticoagulant compatibility and sterile docking interfaces. Automated protocol expansion in North American hospitals is tightening container specification requirements.
- Transfusion:Conventional plasma collection for fractionation into derivative products represents the volume foundation. German and Austrian plasma processors are deepening infrastructure investment.
- Research:Exploratory applications in cell therapy and regenerative medicine demand flexible container configurations with custom port geometries.
- Diagnostic Testing:Quality control and reference sample storage applications requiring extended temperature stability documentation.
Transfusion anchors current procurement; therapeutic apheresis is gaining share fastest on automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polypropylene feedstock from Rotterdam and Antwerp petrochemical clusters anchors European container manufacturing, while US Gulf Coast resin production supplies North American blood bank networks.
United States
Captive plasma collection networks in Texas and California are consolidating procurement leverage across multi-year container supply agreements. FDA biologics licensing requirements enforce extended extractables testing timelines for novel material formulations. The Research Triangle in North Carolina hosts specialized polymer science talent pools that container producers compete to access.
Germany
Plasma fractionation infrastructure in Bavaria and North Rhine-Westphalia is deepening demand for REACH-compliant polypropylene container lines. ECHA authorization reviews of di(2-ethylhexyl) phthalate are accelerating PVC substitution timelines. Heidelberg and Frankfurt clusters concentrate medical polymer R&D facilities serving European blood bank modernization.
Japan
Immunoglobulin collection protocols in Osaka and Tokyo metropolitan areas retain glass container preference for specific fractionation workflows. PMDA stability requirements for sub-zero plasma preservation shape material validation procedures. The Kansai region maintains specialized glass-forming capabilities for pharmaceutical-grade vessels.
India
Blood bank modernization programs in Maharashtra and Karnataka are expanding procurement volumes for automated apheresis-compatible container systems. CDSCO pathway harmonization with ICH standards enables multinational suppliers to qualify products for institutional tenders. The Delhi-NCR corridor concentrates diagnostic laboratory demand for sterile collection vessels.
Switzerland
Specialized fractionation operations in Basel and Zurich sustain residual demand for inert-surface glass containers in precision immunoglobulin workflows. Swissmedic stability documentation requirements exceed standard EU thresholds. The Basel biotech cluster drives custom container specifications for research-scale plasma processing.
Plasma Collection Containers Market Competitive Landscape
Global majors compete with regional champions across material certification and apheresis equipment integration. The vendor base stratifies into three tiers: integrated plasma network operators with captive container demand, diversified medical device conglomerates with hospital supply chain anchoring, and specialized polymer fabricators with regulatory chemistry expertise. Consolidated buying by large collection operators is compressing supplier margins while elevating service intensity requirements. Strategic moves center on backward integration into polymer resin sourcing and technology licensing for automated docking interfaces.
Within the integrated plasma network tier, Grifols and CSL Behring exemplify demand-side consolidation that shapes upstream container procurement patterns. Among diversified medical technology conglomerates, Becton Dickinson and Company occupies a position anchoring North American hospital supply chains through integrated distribution capabilities. Terumo BCT sits within the automated apheresis specialization segment, representing equipment-container interface control strategies that create proprietary ecosystem lock-in.
| Leading Market Players |
|---|
| Grifols |
| CSL Behring |
| Takeda Pharmaceutical Company |
| Becton Dickinson and Company |
| Terumo BCT |
| Fresenius Kabi |
| SARSTEDT AG |
| Greiner Bio-One |
| MEISE Medizintechnik |
| Others |
Value Network & Pricing Analysis
Captive plasma collection networks in Spain and the United States anchor procurement leverage through multi-year container supply agreements with penalty clauses for disruption. This buyer concentration compresses supplier margins while elevating service-bundling requirements across the contract structure.
Pricing Analysis
Service bundling with apheresis equipment maintenance contracts historically captured premium pricing, though large operators now unbundle container procurement to extract direct negotiation leverage. Three-tier pricing structure across premium certified, standard medical-grade, and economy non-validated tiers separates EMA-compliant polypropylene lines from legacy PVC formulations. Cost compression in standard tiers intensifies because REACH-driven material transitions force dual-track inventory carrying. Blood bank procurement committees exhibit highest price sensitivity, while Swiss fractionators maintaining glass protocols show lowest elasticity due to regulatory stability requirements.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO pathway are reshaping sourcing patterns for multinational suppliers qualifying products through local joint ventures. Medical-grade polypropylene feedstock concentrates in Belgium, the Netherlands, and Germany, where Rotterdam and Antwerp petrochemical clusters feed European container fabrication. Container manufacturing draws from specialized polymer resin grades, sterile barrier films, and precision-molded port components. Single-source vulnerability concentrates in European medical-grade polypropylene allocation during feedstock disruptions. Distribution runs through integrated plasma network procurement departments and hospital GPO contracts rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polypropylene substitution for phthalate-plasticized PVC represents the dominant technology-transition phase, with EMA MDR compliance deadlines forcing accelerated validation timelines across European manufacturing bases.
For Market Incumbents: Hedge material transition risk by securing dual-source polypropylene supply agreements with Rotterdam and Antwerp petrochemical producers before ECHA authorization reviews tighten. Accelerate in-house production of anticoagulant stabilization chemistry to defend margin position against unbundling procurement pressure from captive collection networks.
For New Entrants and Emerging Players: Direct-to-blood-bank digital procurement platforms offer the lowest-friction entry vector for qualified container suppliers seeking bypass of established GPO contracts. Target India's CDSCO harmonization window for fastest regulatory pathway to institutional tender participation, leveraging white-space in automated apheresis-compatible bag systems for high-throughput collection centers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier polymer fabricators with validated EMA MDR dossiers and stranded PVC-dependent revenue streams in Germany. Long-term viability hinges on 5-10 year regulatory chemistry expertise scarcity rather than commodity molding capacity. Monitor ECHA di(2-ethylhexyl) phthalate authorization timeline acceleration as the critical inflection signal for material substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Sourcing | Secures medical-grade polypropylene allocation from Antwerp and Rotterdam petrochemical clusters against feedstock disruption. |
| EMA MDR Compliance Certification | Unlocks procurement preference from German fractionators preempting ECHA phthalate authorization reviews. |
| RFID-Enabled Traceability Embedding | Captures demand from fractionation facilities requiring temperature and chain-of-custody ERP integration. |
| CDSCO Pathway Harmonization | Enables qualification for India's expanding blood bank modernization programs in Maharashtra and Karnataka. |
| Vacuum-Insulated Cold-Chain Systems | Addresses EU F-Gas Regulation restrictions on foam blowing agents for multi-day plasma transport stability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this plasma collection containers analysis. Primary interviews with blood bank procurement directors, biomedical engineers, GPO contracts managers, and polymer formulation chemists combined with secondary validation from FDA biologics licensing files, EMA MDR submission databases, and ECHA REACH authorization records. Bottom-up container volume modeling and top-down plasma fractionation capacity triangulation reconciled demand-side estimates.
Data-stream reconciliation across product type, material grade, end-user category, and application workflow dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro plasma collection volume trends incorporated anticoagulant stabilization chemistry evolution and automated apheresis protocol penetration rates as industry-specific forecast inputs.
The model holds under stable regulatory chemistry timelines; deviation in ECHA phthalate authorization acceleration or FDA extractables testing protocol expansion would shift material substitution velocity and certification cost burdens. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
South America Syringe Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Suture Wire Market
Medical Supplies
Skin Tac Market
Medical Supplies
Blood Collection Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Disposable Gloves Market