
 Oilfield Chemicals Market | 2026-2036
Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Chemicals Market Intelligence
Specialty chemical formulation revenue is rewriting profit distribution across the oilfield services stack. BASF leverages its integrated polymer supply chain to dominate high-performance drilling fluid additives. Dow sustains technology leadership in friction reducer chemistry for hydraulic fracturing. Schlumberger anchors its position through captive manufacturing of production chemicals across North American shale basins.
Oilfield chemicals comprise surfactant blends, corrosion inhibitors, biocides, and rheology modifiers engineered for extreme downhole conditions exceeding 150°C and 10,000 psi. These formulations prevent formation damage, maintain wellbore stability, and maximize hydrocarbon recovery across drilling, completion, and production phases. Production chemicals command the deepest margin pools due to recurring well intervention requirements and formulation customization. Stimulation chemicals represent the fastest-expanding category as operators lengthen lateral sections and raise proppant intensity in unconventional reservoirs. Drilling fluids remain the most mature segment, with differentiation shifting toward synthetic-base systems that satisfy offshore discharge regulations.
EPA oversees wastewater toxicity thresholds under the Clean Water Act, while OSHA mandates exposure limits for hydrogen sulfide scavengers and biocide handling. The Bureau of Land Management imposes chemical disclosure requirements for federal lease operations that shape product selection and documentation burdens. Stakeholders must monitor evolving state-level groundwater protection rules and decide whether to build regional blending capacity or rely on third-party logistics networks.
Market Dynamics
Permian Basin operators are compressing well spacing and intensifying proppant loads per lateral foot, forcing chemical suppliers to reformulate friction reducers and biocides for higher shear tolerance and extended residence times.
Growth Catalysts
- Proppant intensity escalation:Unconventional completions now exceed 3,000 pounds of proppant per lateral foot in the Delaware sub-basin, multiplying chemical volumes per stage and sustaining recurring revenue for stimulation fluid suppliers.
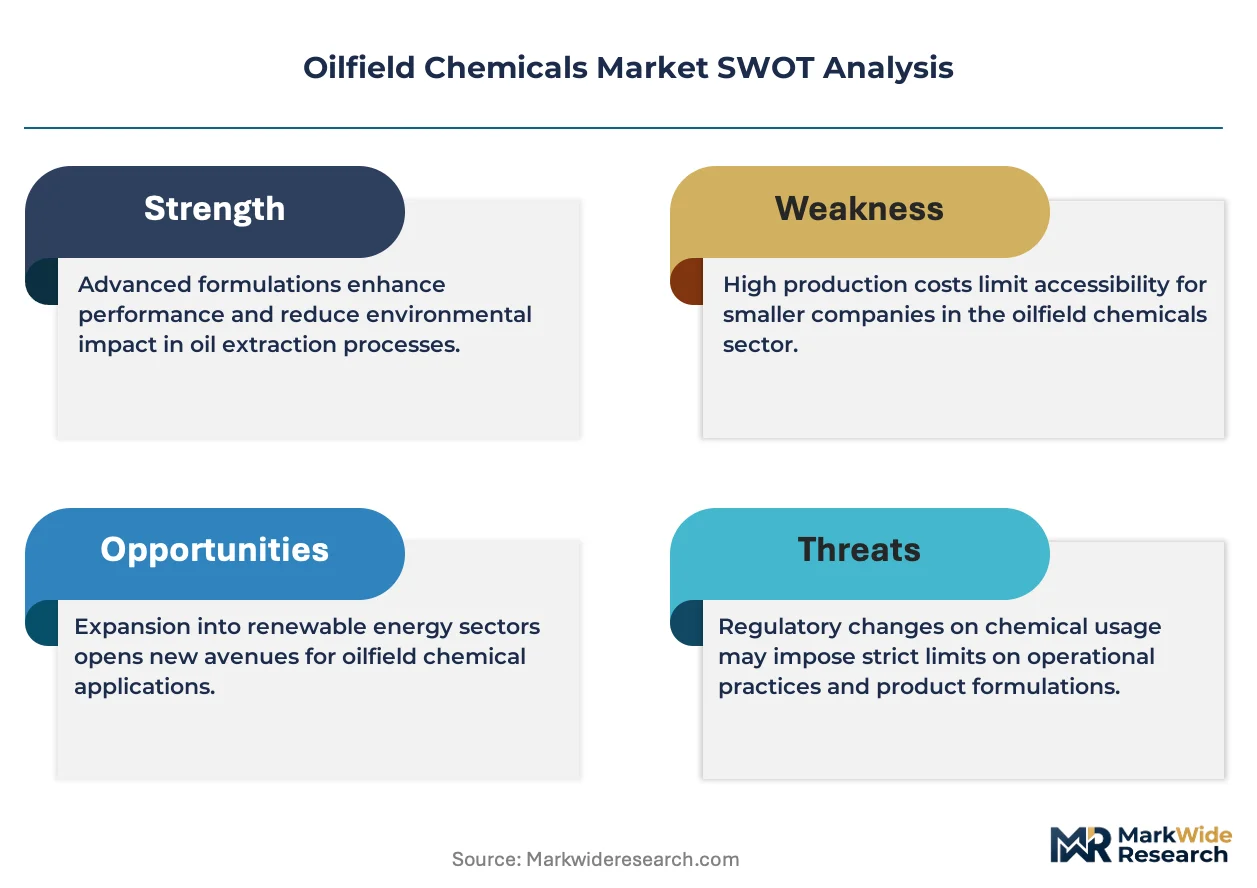
- EPA Clean Water Act discharge limits:Tighter toxicity thresholds for produced water discharge into navigable waters mandate biodegradable surfactant packages and non-toxic biocide alternatives, accelerating premium formulation adoption.
- Middle East sour gas expansion:Saudi Arabia and Qatar are developing high-H2S carbonate reservoirs where hydrogen sulfide scavengers and corrosion inhibitors face mandatory deployment, opening import substitution opportunities for regional blending capacity.
Market Restraints
- Ethylene oxide feedstock volatility:Surfactant manufacturers face margin compression when ethylene oxide spot prices spike, as nonionic surfactants constitute 40-60% of stimulation fluid costs and cannot be hedged beyond six-month contracts.
- Specialty polymer supply concentration:Polyacrylamide friction reducer supply chains concentrate among three German and Chinese producers, creating single-source vulnerability for North American pressure pumpers during ocean freight disruptions.
- Deepwater synthetic-base fluid substitution limits:Offshore drilling contractors cannot displace synthetic-base muds with water-base alternatives in high-pressure, high-temperature wells above 150°C without sacrificing wellbore stability and non-productive time penalties.
Strategic Opportunities
- Argentina Vaca Muerta underpenetration:Neuquén Basin unconventional development lags Permian intensity by 60-70%, creating first-mover advantage for chemical suppliers establishing local blending terminals ahead of YPF and Chevron volume ramps.
- Carbon capture utilization integration:CO2-enhanced oil recovery projects in West Texas and Saskatchewan require corrosion inhibitors and foaming agents formulated for impure CO2 streams containing H2S and water, a specification gap most majors have not addressed.
- EU Green Deal chemical disclosure mandates:REACH registration requirements for offshore North Sea operators are forcing real-time chemical inventory tracking, creating SaaS-enabled chemical management service opportunities for suppliers with digital logistics platforms.
Industry Challenges
- Reservoir-specific formulation turnaround:Operators demand customized stimulation packages within 72 hours of lab receipt of produced water samples, compressing R&D-to-field timelines that previously spanned weeks and straining technical service headcounts.
- Cross-border hazardous material documentation:Mexican customs authorities enforce inconsistent classification of biocide shipments at Eagle Ford border crossings, causing demurrage costs and forcing suppliers to maintain redundant inventory in Laredo and Reynosa.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Chemicals Market |
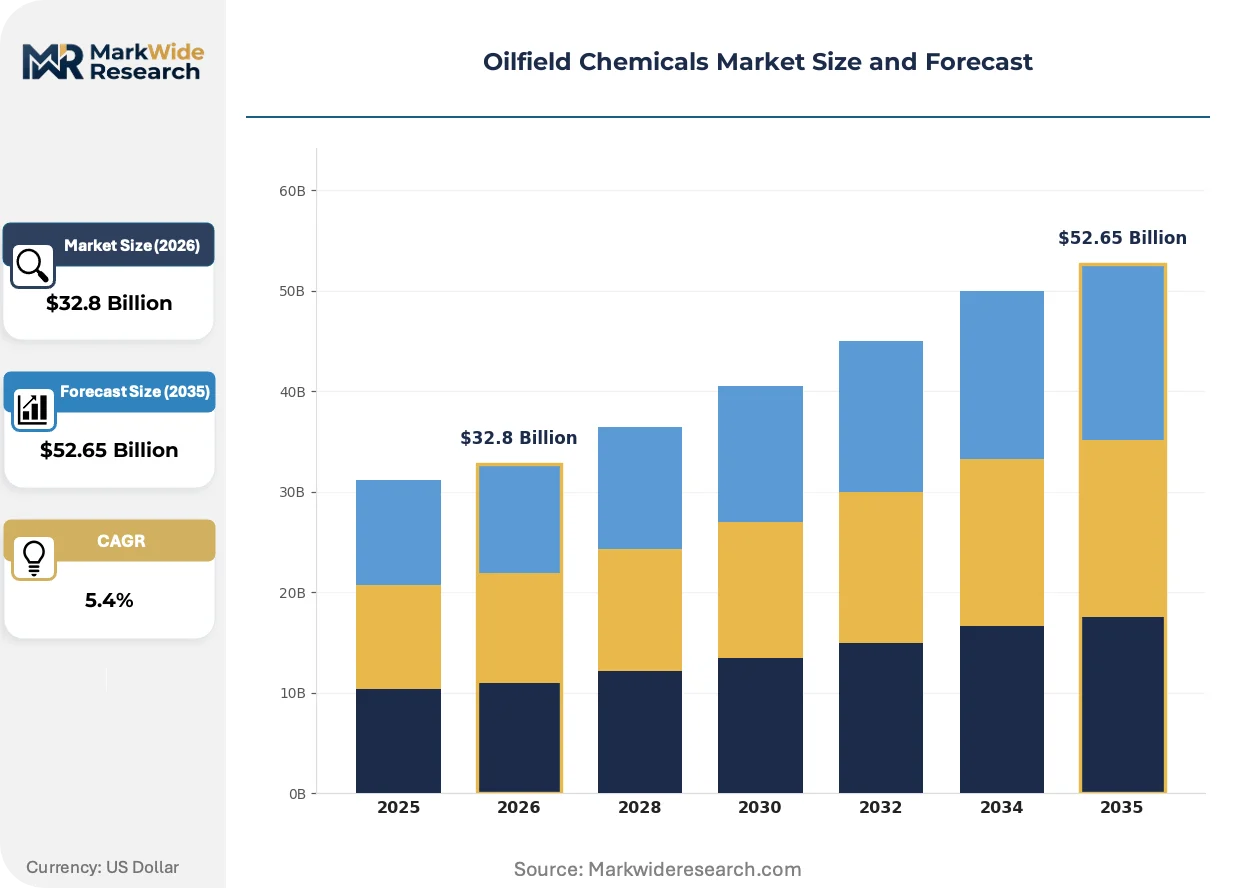
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Fluids, Production Chemicals, Cementing Additives, Stimulation Chemicals Application: Well Completion, Enhanced Oil Recovery, Drilling Operations, Refining Delivery Mode: Batch Delivery, Continuous Delivery, Onsite Production, Pre-mixed Solutions End User: Independent Operators, National Oil Companies, Service Companies, Offshore Producers |
| Companies Covered | BASF, Chevron Phillips Chemical, Schlumberger, Dow, Clariant, Halliburton, ChampionX, Solvay, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Chemicals Market Strategic Shifts & Innovations
Digital twin technology is virtualizing chemical dosage optimization across multi-well pads, replacing rule-of-thumb injection rates with real-time reservoir response modeling that cuts over-treatment waste and under-treatment risk.
Machine learning algorithms trained on microseismic and pressure data are virtualizing the role of field engineers in designing stage-specific friction reducer concentrations. Permian pressure pumpers now deploy automated blending skids that adjust polymer loading every 30 seconds based on surface treating pressure trends. This compression of human decision loops is squeezing margins for traditional technical service contracts while expanding software-enabled chemical management fees.
REACH authorization requirements for chromium-based corrosion inhibitors are forcing North Sea operators to qualify triazole and quaternary ammonium alternatives before 2026 sunset dates. Suppliers with pre-registered polymer packages capture platform maintenance contracts while laggards face 18-month requalification timelines. Norwegian Petroleum Safety Authority audits now prioritize chemical hazard substitution documentation over legacy compliance checklists.
Integrated majors are consolidating chemical procurement under enterprise supply agreements that bundle drilling, completion, and production chemicals with pressure pumping and artificial lift services. This unbundling of standalone chemical margins favors suppliers with captive pressure pumping fleets or exclusive partnerships with national oil companies. Saudi Aramco's long-term chemical supply tenders now specify minimum 15-year contract durations with fixed-price escalation clauses indexed to regional ethylene benchmarks.
Oilfield Chemicals Market Segmentation
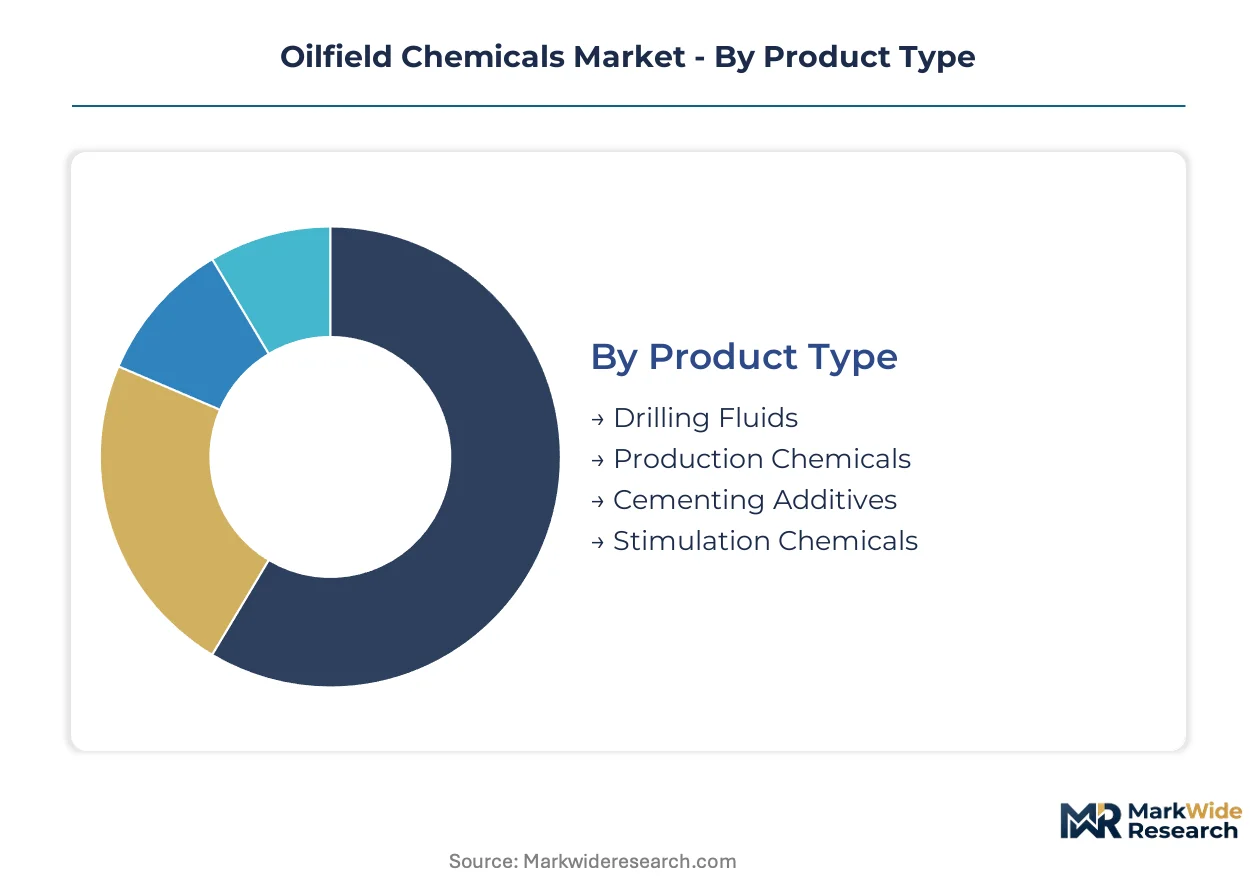
Oilfield chemical procurement decisions split across four distinct axes: product chemistry, operational phase, logistics configuration, and buyer type. Each axis carries different margin profiles, technical service intensity, and contract duration expectations that reshape supplier go-to-market strategy.
Product Type:
The use-case spectrum spans mature commodity formulations to engineered specialty packages customized for reservoir-specific conditions.
- Production Chemicals:Corrosion inhibitors, scale inhibitors, and demulsifiers deployed continuously throughout well life. Demand concentrates in Permian Basin stripper wells and Middle East sour gas fields where hydrogen sulfide scavengers face mandatory deployment under Saudi Aramco specifications.
- Stimulation Chemicals:Friction reducers, biocides, and surfactant blends engineered for high-shear hydraulic fracturing environments. Operators in the Delaware sub-basin now exceed 3,000 pounds of proppant per lateral foot, multiplying chemical volumes per stage and sustaining recurring revenue for suppliers with rapid formulation turnaround capability.
- Drilling Fluids:Synthetic-base and water-base systems maintaining wellbore stability across pressure regimes. Offshore Gulf of Mexico contractors face EPA discharge limits that constrain water-base substitution in high-temperature wells.
- Cementing Additives:Accelerators, retarders, and fluid loss controllers ensuring zonal isolation. Deepwater Brazil pre-salt developments specify ultra-lightweight cement systems with narrow density windows.
The dominant share belongs to Production Chemicals, while Stimulation Chemicals is closing the gap fastest.
Application:
Cost tier differentiation separates capital-intensive drilling phases from recurring production interventions with predictable opex budgets.
- Well Completion:Chemical-intensive perforation, fracturing, and gravel pack operations consuming 60-70% of total chemical spend per well. Multi-well pad development in the Permian and Eagle Ford compresses completion windows, forcing 72-hour formulation turnaround from lab receipt to field deployment.
- Enhanced Oil Recovery:Polymer floods, surfactant floods, and CO2 injection chemistry. West Texas CO2-EOR projects require corrosion inhibitors formulated for impure CO2 streams containing hydrogen sulfide and water, a specification gap most majors have not addressed.
- Drilling Operations:Fluid systems, lubricants, and wellbore stability packages. High-pressure high-temperature wells above 150°C in the Gulf of Mexico mandate synthetic-base muds that cannot displace water-base alternatives without non-productive time penalties.
- Refining:Desalting chemicals, corrosion inhibitors, and antifoulants for downstream processing. Refinery chemical procurement follows enterprise supply agreements with fixed-price escalation clauses indexed to regional ethylene benchmarks.
Well Completion commands the deepest margin pools, while Enhanced Oil Recovery is expanding most quickly as tertiary recovery projects multiply.
Delivery Mode:
Volume concentration determines whether suppliers capture blending margin or surrender it to third-party logistics networks.
- Continuous Delivery:Automated injection systems for production chemicals with real-time dosage optimization. Permian operators deploy digital twin technology replacing rule-of-thumb injection rates with reservoir response modeling.
- Batch Delivery:Stimulation chemical shipments synchronized to frac crew schedules. Pressure pumpers in the Permian now deploy automated blending skids adjusting polymer loading every 30 seconds based on surface treating pressure trends.
- Onsite Production:Mobile blending units for remote locations with prohibitive transport costs. Vaca Muerta development in Argentina favors onsite production given customs delays at Chilean border crossings.
- Pre-mixed Solutions:Standardized packages for routine maintenance with minimal technical service. Pre-mixed biocide solutions dominate workover rig operations in mature Texas conventional fields.
Continuous Delivery holds the largest installed base, while Onsite Production is gaining share fastest in frontier basins with infrastructure constraints.
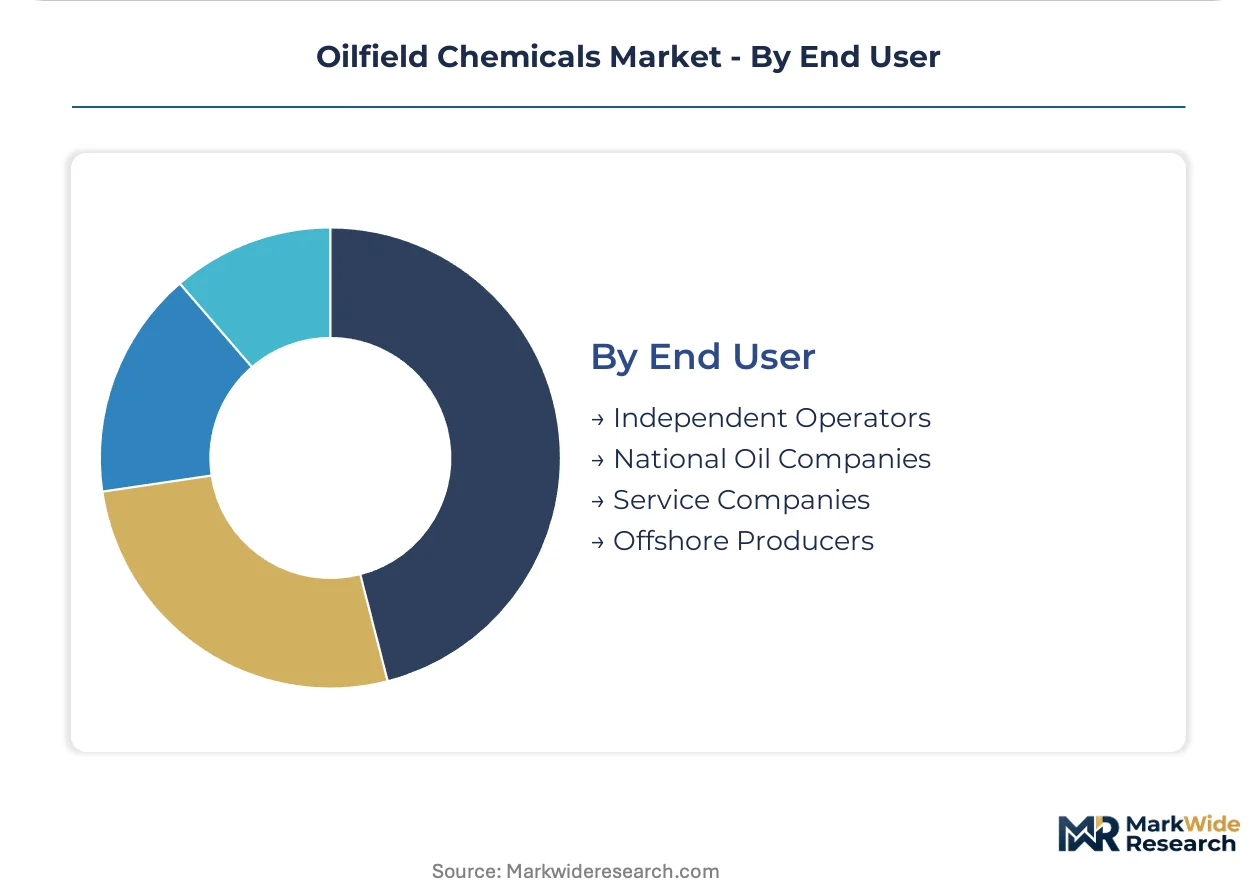
End User:
Customer type dictates contract structure, technical service intensity, and pricing power distribution.
- National Oil Companies:Saudi Aramco, ADNOC, and Petrobras specify minimum 15-year contract durations with fixed-price escalation clauses. Long-term tenders bundle drilling, completion, and production chemicals with pressure pumping services.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes procure chemicals for integrated service offerings. Captive manufacturing of production chemicals anchors competitive positioning across North American shale basins.
- Independent Operators:Permian pure-plays and Appalachian gas producers with spot market procurement flexibility. Smaller independents lack volume leverage for enterprise supply agreements, paying 15-25% premiums for technical service intensity.
- Offshore Producers:Deepwater specialists in the Gulf of Mexico and Brazil pre-salt with stringent discharge compliance requirements. EPA Clean Water Act toxicity thresholds mandate biodegradable surfactant packages and non-toxic biocide alternatives.
National Oil Companies represent the largest contract value, while Independent Operators are closing the gap fastest as private equity-backed consolidation creates larger procurement entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States absorb premium pricing for rapid formulation turnaround, while Middle East national oil companies leverage long-term tenders to lock in fixed-price escalation clauses. European offshore operators face the steepest compliance cost burdens under REACH authorization timelines.
United States
Permian Basin operators compress well spacing and intensify proppant loads beyond 3,000 pounds per lateral foot, multiplying chemical volumes per frac stage. EPA Clean Water Act discharge limits tighten toxicity thresholds for produced water released into navigable waters. Midland-Odessa chemical terminals now stock automated blending skids that adjust polymer loading every 30 seconds based on surface treating pressure trends.
Saudi Arabia
High-H2S carbonate reservoir development in the Ghawar and Safaniya fields mandates hydrogen sulfide scavengers and corrosion inhibitors under Saudi Aramco specifications. The national oil company now specifies minimum 15-year contract durations with fixed-price escalation clauses indexed to regional ethylene benchmarks. Jubail Industrial City hosts expanding regional blending capacity serving both domestic operators and export markets across the Gulf.
Germany
Specialty polymer supply chains concentrate among producers serving friction reducer demand for North American pressure pumpers. REACH authorization requirements for chromium-based corrosion inhibitors force qualification of triazole alternatives before 2026 sunset dates. Ludwigshafen chemical complexes anchor integrated polymer supply chains that dominate high-performance drilling fluid additive production.
China
Domestic shale development in Sichuan and Xinjiang basins drives import substitution for stimulation chemistries previously sourced from Western suppliers. The Ministry of Ecology and Environment enforces dual carbon goals that tighten wastewater discharge standards for drilling operations. Shanghai and Tianjin port clusters handle bulk surfactant imports while inland blending terminals serve remote Tarim Basin drilling campaigns.
Brazil
Pre-salt deepwater developments specify ultra-lightweight cement systems with narrow density windows for zonal isolation in high-pressure carbonate reservoirs. ANVISA and environmental regulators impose chemical disclosure requirements for offshore operations that shape product selection and documentation burdens. Macaé and Rio de Janeiro service bases concentrate technical service headcounts for rapid reservoir-specific formulation turnaround.
Oilfield Chemicals Market Key Industry Players
Integrated chemical majors and oilfield service conglomerates split the market into distinct capability tiers. The structure concentrates formulation expertise among players with captive polymer supply chains or exclusive national oil company partnerships. Three archetypes dominate: diversified chemical conglomerates with upstream integration, service companies with captive manufacturing arms, and regional specialists with rapid customization capabilities. Competitive moves center on enterprise supply agreement bundling and digital logistics platform deployment.
Among diversified chemical conglomerates, BASF and Dow exemplify archetypes leveraging integrated polymer supply chains to capture margin pools in high-performance additives. Schlumberger occupies a position representing service-company vertical integration, anchoring competitive positioning through captive production chemical manufacturing across North American shale basins.
| Leading Market Players |
|---|
| BASF |
| Chevron Phillips Chemical |
| Schlumberger |
| Dow |
| Clariant |
| Halliburton |
| ChampionX |
| Solvay |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Jubail Industrial City anchors regional blending capacity for Middle East sour gas development, and its expansion dynamics directly shape pricing power for hydrogen sulfide scavengers and corrosion inhibitors across Gulf export markets. When Saudi Aramco locks in 15-year fixed-price contracts indexed to regional ethylene benchmarks, competitors without captive polymer supply chains face margin compression in spot market negotiations.
Pricing Analysis
Technical service contracts drive lifetime value for oilfield chemical suppliers, with recurring production chemical interventions commanding premium pricing over transactional stimulation fluid sales. Three-tier pricing structure across premium, standard, and economy levels separates formulation customization depth, with reservoir-specific packages priced above commodity biocide blends. Cost compression in standard-tier friction reducers is intensifying because ethylene oxide feedstock volatility erodes hedged positions beyond six-month contracts. National oil companies exhibit lowest price sensitivity due to long-term offtake agreements, while independent Permian operators negotiate aggressively on spot procurement.
Supply Chain Analysis
Export-control scrutiny on polyacrylamide polymer technology limits friction reducer supply chain flexibility between German and Chinese producers. Specialty polymer manufacturing concentrates in Germany, China, and the United States, with Ludwigshafen chemical complexes and Shanghai port clusters serving as critical nodes. Raw material dependencies center on ethylene oxide, acrylamide monomers, and chromium-based corrosion inhibitor precursors. Single-source vulnerability from concentrated polyacrylamide supply creates structural risk during ocean freight disruptions. Distribution runs through regional blending terminals in Midland-Odessa, Jubail, and Macaé synchronized to frac crew schedules and platform maintenance windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oilfield chemicals track upstream capital expenditure cycles, and Permian Basin drilling permit volatility serves as the primary cyclical driver shaping near-term demand recovery trajectories.
For Market Incumbents: Insulate margin pools by deepening captive manufacturing of production chemicals across North American shale basins and securing exclusive partnerships with Saudi Aramco's long-term tender programs. Biocide formulation standardization under EPA Clean Water Act tightening threatens technical service differentiation. Backward integration into polymer supply chains anchors pricing power against ethylene oxide volatility. For New Entrants and Emerging Players: Establish a beachhead in Argentina's Vaca Muerta formation ahead of YPF and Chevron volume ramps, where local blending terminal gaps create first-mover advantage. Neuquén Basin unconventional development lags Permian intensity by 60-70%, representing the most penetrable geography. Deploy digital twin-enabled chemical management platforms to differentiate against legacy technical service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with rapid formulation turnaround capabilities and SaaS-enabled logistics platforms. Five-to-ten year viability hinges on suppliers capturing enterprise supply agreement bundling trends. Watch for inflection in Saudi Aramco chemical tender specifications signaling import substitution priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Blending Capacity Buildout | Jubail and Vaca Muerta terminals capture margin from import substitution in sour gas fields. |
| Backward Integration into Polymer Supply | Captive acrylamide production insulates BASF and Dow from ethylene oxide volatility. |
| Digital Twin Platform Deployment | Real-time dosage optimization replaces rule-of-thumb injection rates in Permian operations. |
| Long-term Supply Agreement with NOCs | Saudi Aramco's 15-year fixed-price contracts lock in ethylene-indexed escalation clauses. |
| Biodegradable Formulation Transition | EPA Clean Water Act compliance mandates accelerate premium surfactant package adoption. |
Research Approach
A spread of perspectives from chemical plant managers, pressure pumper procurement leads, national oil company technical directors, and distribution channel partners converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from customs and trade data, American Chemistry Council reports, SEC 10-K filings, and EPA discharge compliance records. Bottom-up well count and proppant intensity models triangulated against top-down chemical spend per barrel estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product chemistry tier, operational phase intensity, logistics configuration, and buyer contract structure. CAGRs derived from trajectory analysis of well completion counts, lateral length extension, and proppant loading trends. Forecast inputs incorporated rig count elasticity to WTI price bands and regulatory timeline certainty for REACH authorization sunsets.
Stress conditions across ethylene oxide price spikes, ocean freight disruption duration, and EPA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on Permian well spacing compression and Middle East sour gas development cadence. Material shifts in Saudi Aramco tender specifications or Clean Water Act toxicity threshold timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Upstream Services Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Romania Oil and Gas Downstream Market