
 Thermal Spray Coating for Oil and Gas Market | 2026-2036
Thermal Spray Coating for Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Coating for Oil and Gas Market Insights
Buyer concentration in the upstream segment is decoupling from historical supermajor dominance as independent shale operators and specialized drilling contractors multiply the customer base. Praxair Surface Technologies leverages its geographic footprint across North American oilfields to sustain service proximity. Kennametal Inc. anchors its position through carbide powder supply integration that competitors cannot easily replicate. Bodycote competes via heat-treatment and coating combinations that reduce vendor count for maintenance managers.
Thermal spray coating for oil and gas deposits molten or semi-molten metallic and ceramic feedstock onto substrates to create dense, adherent layers typically 50 microns to several millimeters thick, engineered to resist corrosion, erosion, and thermal fatigue in downhole, subsea, and refinery environments. WC-Co product types dominate revenue due to unmatched hardness in abrasive drilling conditions, while Ni-based alloys capture expanding share in sour gas applications where hydrogen sulfide attack demands nickel's corrosion resistance. Plasma spray technology leads in ceramic thermal barrier deposition for turbine and exhaust components, though HVOF gains ground where denser, lower-porosity metallic coatings satisfy stricter performance specifications.
OSHA process safety management rules and EPA emissions standards shape coating material selection and application site compliance, while the US Bureau of Safety and Environmental Enforcement mandates documented coating integrity for subsea equipment. ISO 14918 certification for thermal spray personnel and ASTM C633 adhesion testing create qualification barriers that filter out low-capability applicators. Stakeholders must monitor how methane reduction commitments and electrification trends reshape the investment timeline for coating infrastructure tied to hydrocarbon production.
Market Dynamics
Upstream operators in the Permian Basin and Gulf of Mexico corridor are compressing coating replacement cycles as drilling intensity and saltwater exposure accelerate equipment degradation, forcing applicators to scale service proximity.
Growth Catalysts
- WC-Co Hardfacing Demand:Tungsten carbide-cobalt overlays dominate downhole component protection in abrasive drilling conditions where tool life extension justifies premium coating spend.
- BSEE Equipment Integrity Mandates:The US Bureau of Safety and Environmental Enforcement now requires documented coating integrity for subsea blowout preventers and wellhead connectors.
- Ni-Based Alloy Expansion:Nickel alloys capture share in sour gas applications where hydrogen sulfide attack demands corrosion resistance beyond carbide capabilities.
Market Restraints
- Cobalt Powder Volatility:Tungsten carbide-cobalt feedstock prices fluctuate with cobalt mining concentration in the Democratic Republic of Congo and refined supply from Chinese processors.
- Applicator Certification Barriers:ISO 14918 personnel certification and ASTM C633 adhesion testing filter out low-capability service providers, constraining local supply in remote oilfields.
- Plasma Spray Limitations:Ceramic thermal barrier deposition via plasma spray produces higher porosity than HVOF alternatives, restricting use in critical subsea pressure boundaries.
Strategic Opportunities
- Electrification Infrastructure Pivot:Methane reduction commitments and electrification trends reshape investment timelines, opening coating demand for geothermal wellhead equipment and carbon capture injection systems.
- HVOF Technology Convergence:High-velocity oxy-fuel systems integrate with robotic application cells to deliver denser metallic coatings for stricter offshore performance specifications.
- Independent Shale Operator Channel:Specialized drilling contractors and private equity-backed upstream independents multiply the customer base beyond historical supermajor dominance.
Industry Challenges
- Thermal Spray Technician Scarcity:Skilled operators capable of maintaining HVOF and plasma spray parameters in field conditions command wage premiums that compress applicator margins.
- Multi-Vendor Integration Friction:Maintenance managers face complexity coordinating separate heat-treatment and coating vendors, driving preference toward combined service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Coating for Oil and Gas Market |
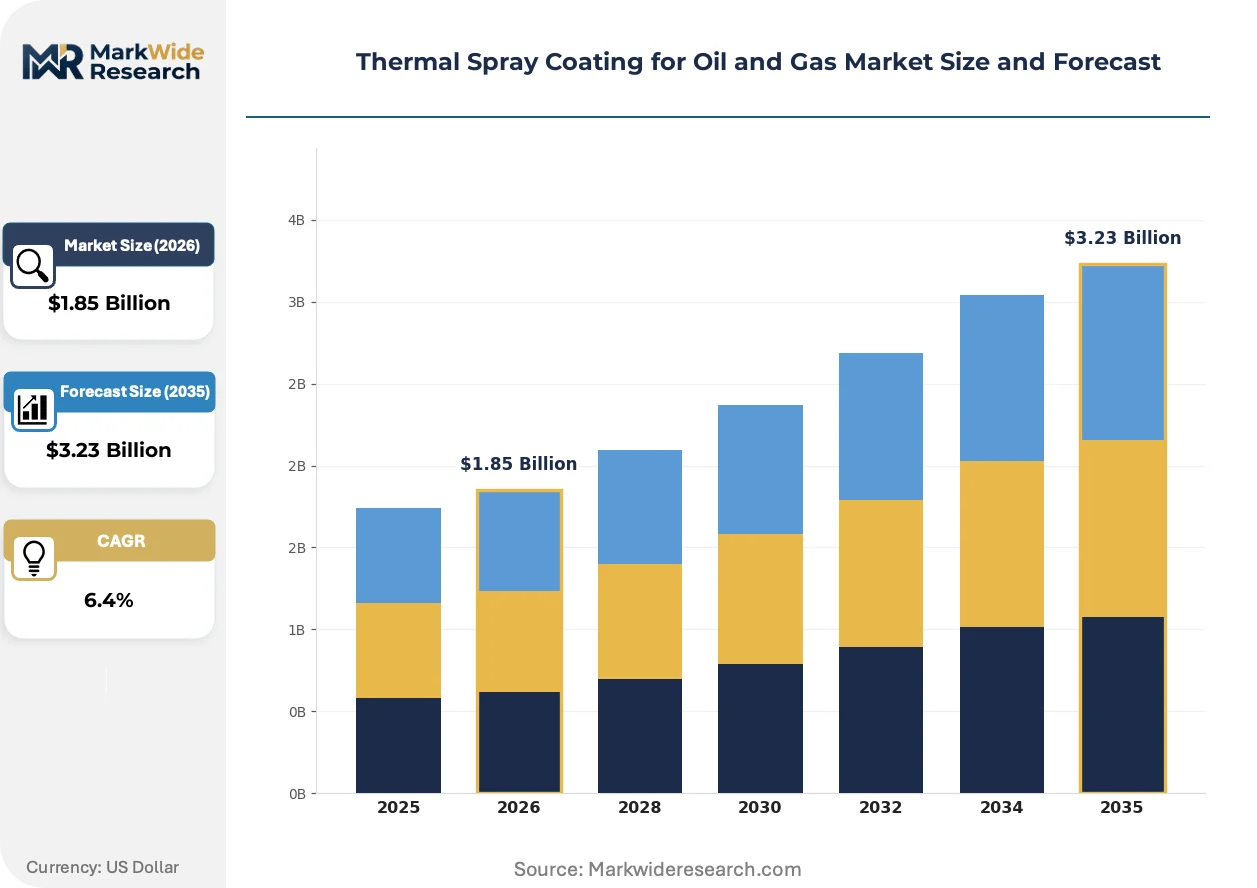
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: WC-Co, Ni-based Alloys, Cr3C2-NiCr, Al2O3 Application: Corrosion Protection, Wear Resistance, Thermal Barrier, Friction Reduction Technology: Plasma Spray, HVOF, Arc Spray, Flame Spray End User: Upstream, Midstream, Downstream, Maintenance Services |
| Companies Covered | Oerlikon Metco, Praxair Surface Technologies, Kennametal Inc., Flame Spray Coating Co., Metallization Ltd., Precision Coatings, Inc., Montreal Carbide Co. Ltd., A&A Thermal Spray Coatings, Bodycote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Coating for Oil and Gas Market Trends and Innovations
Application automation and feedstock formulation advances are compressing coating cycle times while expanding performance envelopes for extreme downhole environments.
Robotic thermal spray cells are integrating with real-time particle temperature and velocity monitoring to maintain coating density specifications across irregular subsea component geometries. Offshore fabricators in the Gulf of Mexico deploy these systems for wellhead connector overlays where manual application cannot guarantee repeatability. The technology is integrating quality assurance directly into deposition workflows, reducing post-coat inspection bottlenecks.
The US Bureau of Safety and Environmental Enforcement tightened offshore equipment integrity documentation requirements, mandating traceable coating thickness and adhesion records for subsea blowout preventers. Operators now specify certified applicator networks to avoid regulatory shutdown exposure. Deepwater developments in the Gulf of Mexico face the steepest compliance ramps as pre-2015 installed base requires recertification.
Maintenance procurement teams unbundle coating services from original equipment manufacturer service contracts, awarding work to independent thermal spray specialists with faster mobilization. Independent shale operators in the Permian Basin drive this shift by prioritizing uptime over brand loyalty. The pattern concentrates award volume with regional applicators maintaining stocked carbide powder inventories and mobile HVOF units.
Thermal Spray Coating for Oil and Gas Market Segmentation
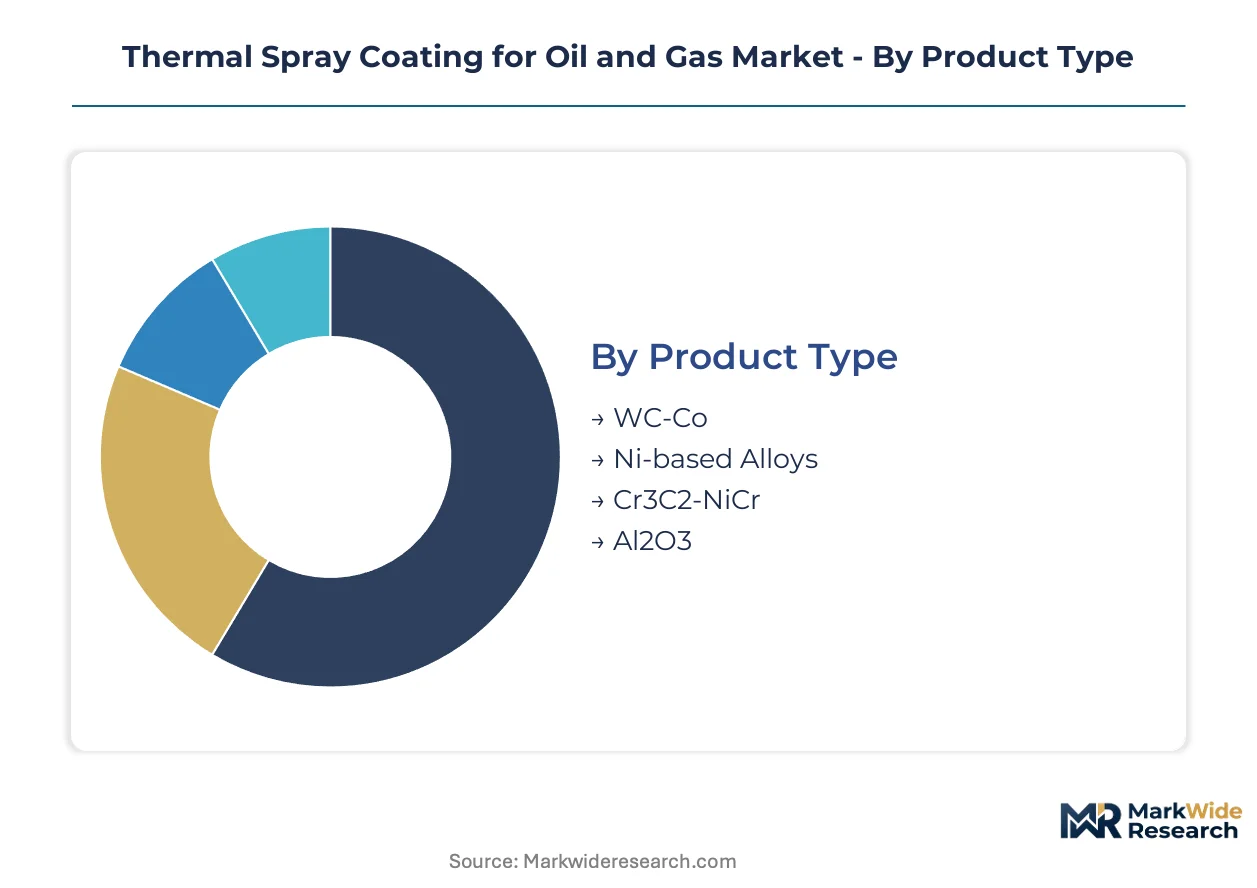
Coating specification, application environment, and end-user procurement authority each create distinct margin structures and certification requirements across the thermal spray value chain. Segmentation reveals where technology premiums command pricing power versus where commoditization pressures dominate.
Product Type:
ISO 14918 certification requirements intensify with coating complexity, with carbide systems demanding the most rigorous operator qualification and sour-gas alloys requiring supplemental hydrogen sulfide exposure testing.
- WC-Co:Tungsten carbide-cobalt composites deliver hardness exceeding 1200 HV for drill bit inserts and mud motor rotors in Permian Basin abrasive formations. Demand concentrates with independent shale operators prioritizing tool life over initial coating cost in high-frequency drilling programs.
- Ni-based Alloys:Nickel-chromium-molybdenum formulations resist hydrogen sulfide cracking in sour gas wellheads across the Gulf of Mexico. Growth accelerates where BSEE mandates documented corrosion resistance for subsea equipment integrity verification.
- Cr3C2-NiCr:Chromium carbide-nickel chromium systems operate at temperatures up to 900°C for turbine exhaust components in gas processing facilities.
- Al2O3:Alumina ceramic coatings provide electrical insulation and thermal protection for refinery heater tubes and flare tip assemblies.
Leading the category by volume: WC-Co. Growing fastest: Ni-based Alloys.
Application:
Performance specifications diverge sharply between surface-protective and functional coating roles, with thermal barrier systems commanding the highest deposition precision requirements.
- Corrosion Protection:Barrier coatings for subsea pipelines and wellhead equipment must demonstrate 25-year service life predictions through ASTM G85 salt spray testing. Offshore operators in the Gulf of Mexico specify these systems for cathodic protection supplementation where coating holidays risk localized pitting.
- Wear Resistance:Hardfacing overlays on pump impellers, valve seats, and rod couplings reduce metal loss in solids-laden production fluids. Permian Basin operators drive volume through accelerated replacement cycles on high-pressure fracturing equipment.
- Thermal Barrier:Ceramic topcoats insulate turbine blades and exhaust manifolds from combustion temperatures exceeding 1000°C in gas compression stations.
- Friction Reduction:Low-coefficient coatings on piston rods and pump plungers improve mechanical efficiency in artificial lift systems.
Dominant by revenue: Corrosion Protection. Expanding most quickly: Thermal Barrier.
Technology:
Capital intensity and operating cost structures separate field-deployable systems from fixed-facility precision deposition platforms.
- Plasma Spray:Electric arc plasma torches achieve temperatures exceeding 15000°C for ceramic deposition on complex geometries. Refinery maintenance contractors specify these systems for in-situ turbine blade restoration where component removal is cost-prohibitive.
- HVOF:High-velocity oxy-fuel combustion produces dense metallic coatings with porosity below 1% for critical pressure-containing components. Offshore fabricators adopt robotic HVOF cells for wellhead connector overlays where BSEE traceability requirements demand parameter documentation.
- Arc Spray:Twin-wire electric arc systems offer the lowest per-kilogram deposition cost for large-area pipeline rehabilitation projects.
- Flame Spray:Powder and wire flame systems provide portable coating capability for remote wellsite repairs with minimal infrastructure requirements.
Highest installed base: Plasma Spray. Steepest adoption trajectory: HVOF.
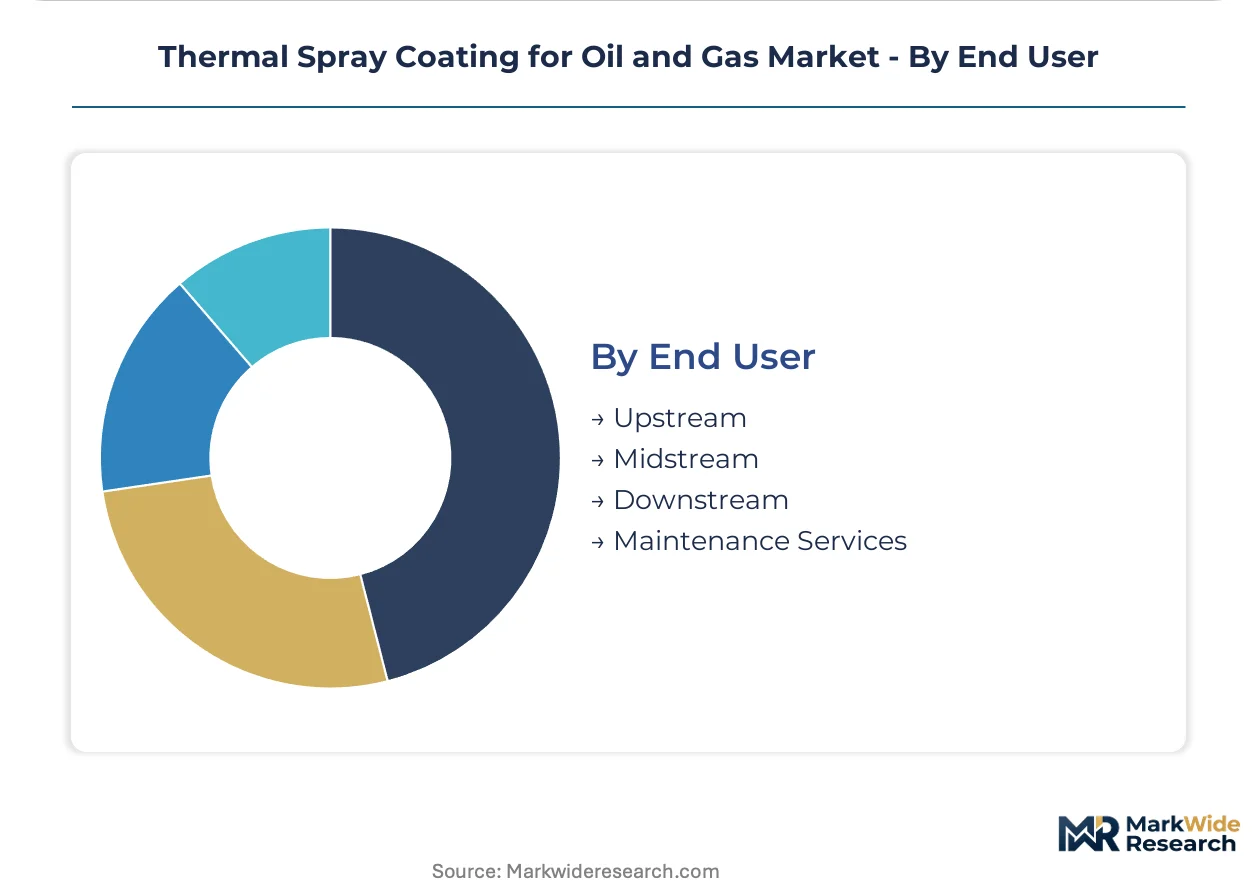
End User:
Procurement authority and technical specification control shift dramatically across the hydrocarbon value chain, with maintenance services capturing growing coating decision influence.
- Upstream:Exploration and production operators specify coatings for downhole tools, subsea trees, and wellhead equipment where failure costs exceed coating expenditure by orders of magnitude. Independent shale producers in the Permian Basin unbundle coating procurement from OEM service contracts to accelerate mobilization.
- Maintenance Services:Third-party repair contractors coordinate coating application with heat treatment and machining operations to reduce vendor count for turnaround managers. These providers stock carbide powder inventories and deploy mobile HVOF units for field-responsive service.
- Midstream:Pipeline operators and gas processing facilities specify internal diameter coatings for flow assurance and compressor station component protection.
- Downstream:Refinery operators apply thermal spray for fluid catalytic cracking unit component restoration and fired heater tube protection.
Largest volume purchaser: Upstream. Gaining procurement share fastest: Maintenance Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream drilling intensity concentrates coating demand in the United States, where independent shale operators and offshore fabricators compress replacement cycles faster than any other single-country market.
United States
Permian Basin independents and Gulf of Mexico offshore fabricators drive WC-Co consumption for downhole tools and subsea wellheads. OSHA process safety management rules and EPA emissions standards govern application site compliance. Houston-area service clusters stock carbide powder inventories and deploy mobile HVOF units for field-responsive coating.
Norway
North Sea deepwater developments require corrosion-resistant overlays for subsea trees and pipeline end terminations. The Norwegian Petroleum Safety Authority mandates documented coating integrity for pressure-containing equipment. Stavanger and Bergen harbor specialized applicators serving Equinor-operated installations with robotic deposition cells.
Saudi Arabia
Sour gas reservoirs in the Eastern Province accelerate Ni-based alloy adoption for hydrogen sulfide resistance. The country's national petroleum regulator enforces equipment integrity verification for high-pressure wellhead systems. Dhahran-based maintenance contractors coordinate thermal spray with heat treatment for gas processing facility turnarounds.
China
Sichuan Basin shale operators and South China Sea offshore projects expand ceramic thermal barrier demand for turbine components. GB standards and MIIT industrial safety regulations shape coating material selection. Yangtze River Delta fabricators integrate plasma spray with automated quality monitoring for refinery equipment restoration.
Brazil
Pre-salt carbonate formations drive hardfacing consumption for drill bit inserts and mud motor components in abrasive conditions. ANP regulatory frameworks require traceable coating records for subsea production systems. Rio de Janeiro and Macaé service bases support Petrobras-contracted coating campaigns with stocked alloy feedstocks.
Thermal Spray Coating for Oil and Gas Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue robotics integration and field-deployable service models. The supplier base organizes around three strategic archetypes: integrated powder-coating combinations, standalone application specialists, and diversified industrial service conglomerates. Consolidation pressure intensifies as maintenance procurement teams reduce vendor counts. Geographic proximity to Permian and Gulf of Mexico drilling corridors determines contract capture more than technology differentiation alone.
Among diversified industrial service providers, Bodycote exemplifies the heat-treatment-plus-coating bundling archetype that maintenance managers favor for turnaround simplification. Kennametal Inc. occupies a position defined by captive carbide powder supply that competitors cannot readily replicate. Praxair Surface Technologies anchors the geographic footprint strategy with service proximity across North American oilfields. These three represent distinct competitive vectors: bundled service integration, upstream feedstock control, and regional density deployment.
| Leading Market Players |
|---|
| Oerlikon Metco |
| Praxair Surface Technologies |
| Kennametal Inc. |
| Flame Spray Coating Co. |
| Metallization Ltd. |
| Precision Coatings, Inc. |
| Montreal Carbide Co. Ltd. |
| A&A Thermal Spray Coatings |
| Bodycote |
| Others |
Pricing and Supply Chain Analysis
Cobalt metal price benchmarks from the London Metal Exchange cascade through tungsten carbide-cobalt powder pricing tiers, compressing margins for applicators locked into spot-market feedstock purchases while rewarding vertically integrated suppliers with captive carbide production. The spread between premium certified coatings and uncertified alternatives widens as BSEE documentation requirements harden buyer preferences for traceable application networks.
Pricing Analysis
Volume concentrates in standard-grade WC-Co overlays for Permian Basin drill bits, while margin pools in Ni-based alloy systems for Gulf of Mexico sour gas applications where hydrogen sulfide certification commands premium positioning. Price differentiation rests on ISO 14918 operator certification status and robotic application cell deployment, with uncertified field applicators undercutting on mobilization speed. Cost compression in standard carbide hardfacing intensifies as independent shale operators unbundle procurement from OEM service contracts. Maintenance services contractors prove least price-sensitive, prioritizing single-vendor turnaround coordination over per-kilogram coating economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese refined cobalt processors and DRC mining concentration for tungsten carbide-cobalt feedstock, exposing applicators to geopolitical disruption and export restriction cascades. Raw material flows draw from Swedish tungsten powder producers, American carbide manufacturers, and Japanese plasma spray equipment fabricators. Supply chain risk centers on tariff exposure for ceramic thermal barrier powders sourced from European specialty chemical producers. Distribution runs through Houston-area service clusters stocking carbide inventories for field-responsive deployment, with regional applicators capturing maintenance procurement awards through proximity rather than technology differentiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where BSEE equipment integrity mandates create a regulatory moat that filters out low-capability applicators and concentrates award volume with certified networks.
For Market Incumbents: Anchor position through captive carbide powder supply integration and robotic HVOF cell deployment across Gulf of Mexico fabrication corridors, defending against emerging entrants pursuing mobile application service models. Certification investment in ISO 14918 personnel networks and ASTM C633 adhesion testing infrastructure raises competitive barriers that scale economies alone cannot replicate. Capacity addition in Permian Basin service clusters captures unbundled procurement from independent shale operators prioritizing uptime velocity. For New Entrants and Emerging Players: Digital-channel routes through maintenance procurement platforms offer lower-friction entry than direct upstream operator sales cycles, particularly for regional applicators with stocked powder inventories and rapid mobilization capabilities. White-space targets concentrate in geothermal wellhead equipment and carbon capture injection systems where coating specifications remain undefined and incumbent certification advantages have not yet crystallized. The most penetrable segment sits with private equity-backed drilling contractors in the Permian Basin seeking to reduce OEM service contract dependency. For Investors and Strategic Acquirers: Distressed-cycle entries favor heat-treatment-plus-coating bundled service providers in North American oilfield corridors where maintenance managers are consolidating vendor counts. Long-term viability hinges on regulatory compliance infrastructure rather than commodity coating throughput, positioning certified applicator networks for durable margin capture. The signal to watch is BSEE enforcement intensity for subsea equipment recertification, which would accelerate replacement cycle compression and concentrate demand with documented-capability providers.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic HVOF Cell Deployment | Automated deposition cells satisfy BSEE traceability requirements for subsea wellhead connectors. |
| Captive Carbide Powder Integration | In-house tungsten carbide-cobalt production shields margins from LME cobalt price volatility. |
| Geothermal Equipment Certification | Early coating specification capture in geothermal wellheads builds position before standards harden. |
| Mobile Application Service Expansion | Field-deployable HVOF units capture unbundled procurement from Permian Basin independents. |
| Heat-Treatment Bundling | Combined thermal processing and coating services reduce vendor count for turnaround managers. |
Research Methodology
Document review covered SEC filings from thermal spray equipment manufacturers, BSEE regulatory enforcement records, and ASTM coating standards documentation, complemented by interviews with maintenance directors at Permian Basin drilling contractors, procurement leads at Gulf of Mexico offshore fabricators, thermal spray application technicians, and carbide powder supply managers. Secondary validation drew from OSHA process safety management guidance, EPA emissions compliance databases, and ISO certification registry records. Bottom-up segment sizing triangulated against top-down energy sector capital expenditure patterns.
Cross-referencing historical coating replacement cycle data with expert panel input on electrification timeline impacts shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type hierarchy, application environment severity, technology capital intensity, and end-user procurement authority concentration. CAGRs were derived from equipment installed base depreciation schedules and regulatory mandate implementation pacing, with inputs from sour gas reservoir development projections and shale drilling intensity forecasts.
The model holds under steady regulatory enforcement intensity and hydrocarbon production investment continuity; deviation in methane reduction policy acceleration or cobalt supply disruption would shift coating demand composition and feedstock cost structures. Forecasts reflect assumptions about certification barrier persistence and independent operator procurement behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Wellhead System Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Canada LNG Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Brazil Oil and Gas Midstream Market