
 Consumer Lithium-Ion Battery Market | 2026-2036
Consumer Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Lithium-Ion Battery Market Insights
Silicon anode chemistry is consolidating around graphite-dominant architectures in premium consumer cells, trimming cost-per-watt-hour for smartphone and laptop packs. Contemporary Amperex Technology Co. Limited leverages integrated cathode production to secure raw material streams across Fujian and Sichuan provinces. LG Energy Solution anchors its consumer division in cylindrical and pouch formats for power tool OEMs. Panasonic Holdings Corporation competes on cylindrical cell consistency for high-drain wearable applications.
A consumer lithium-ion battery stores electrochemical energy through lithium-ion shuttling between a metal-oxide cathode and a carbonaceous anode, typically operating at 3.2–4.2 volts with energy densities reaching 250–300 watt-hours per kilogram in advanced cell designs. Its commercial purpose centers on delivering rechargeable, lightweight power for portable and mobile devices where energy-to-weight ratio determines product viability. Li-Polymer configurations dominate slim-form smartphone and wearable segments where mechanical flexibility outweighs absolute energy density. Li-NMC chemistry leads in power tools and electric scooters demanding higher discharge rates. Portable electronics as a product category remains the most mature margin pool, while electric vehicle applications within consumer-grade micromobility represent the fastest structural expansion.
China's SAMR enforces GB standards for cell cycle life and safety testing that determine factory access to domestic consumer electronics supply chains. The EU Battery Regulation mandates recycled content thresholds and digital passports, reshaping export compliance costs for Asian cell makers. Japan's METI reviews consumer battery standards through JIS frameworks that influence regional procurement specifications. Stakeholders must track how carbon border adjustments and chemistry-specific recycling mandates redirect sourcing strategies before compliance deadlines harden.
Market Dynamics
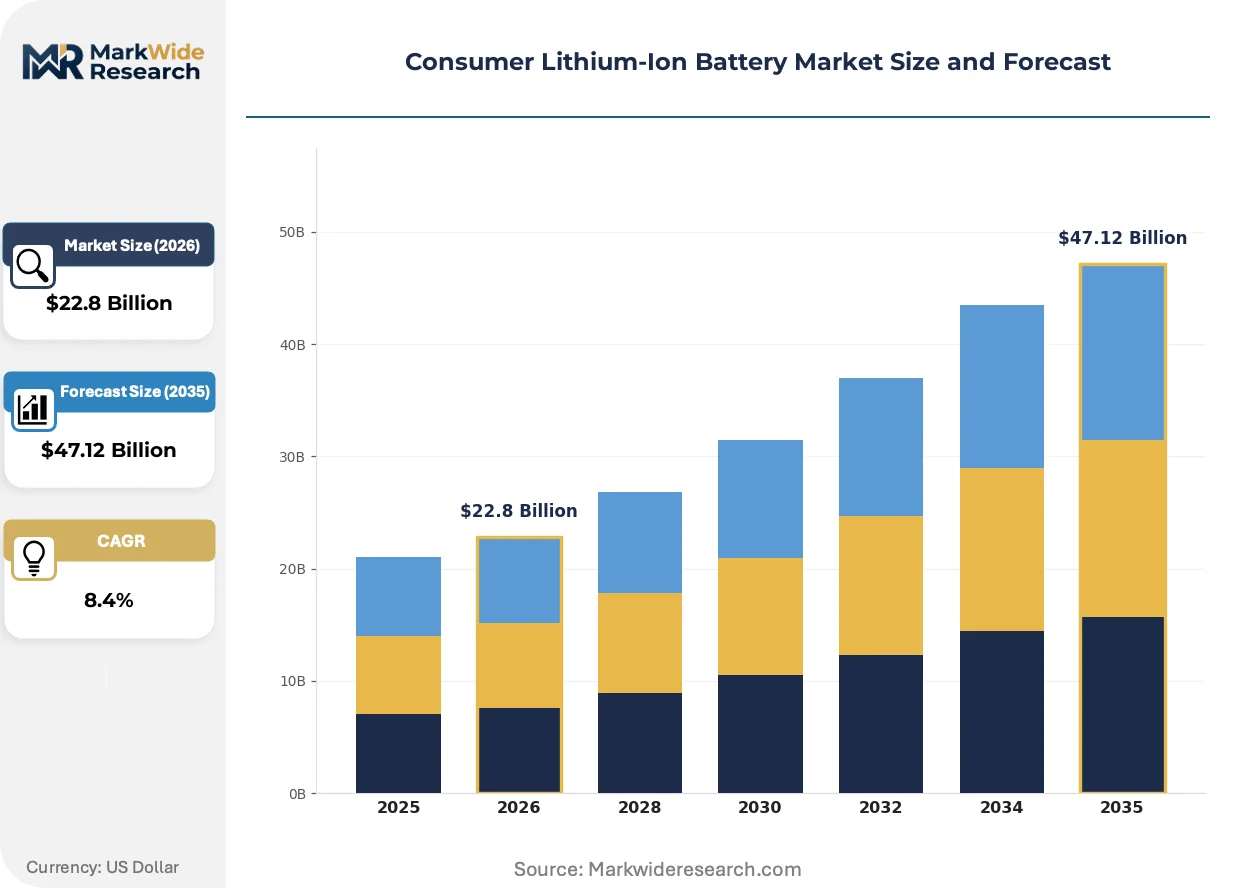
Silicon-dominant anode architectures are compressing cost curves for high-density cells while GB standards and the EU Battery Regulation force simultaneous carbon footprint disclosure and recycled content compliance across export supply chains.
Growth Catalysts
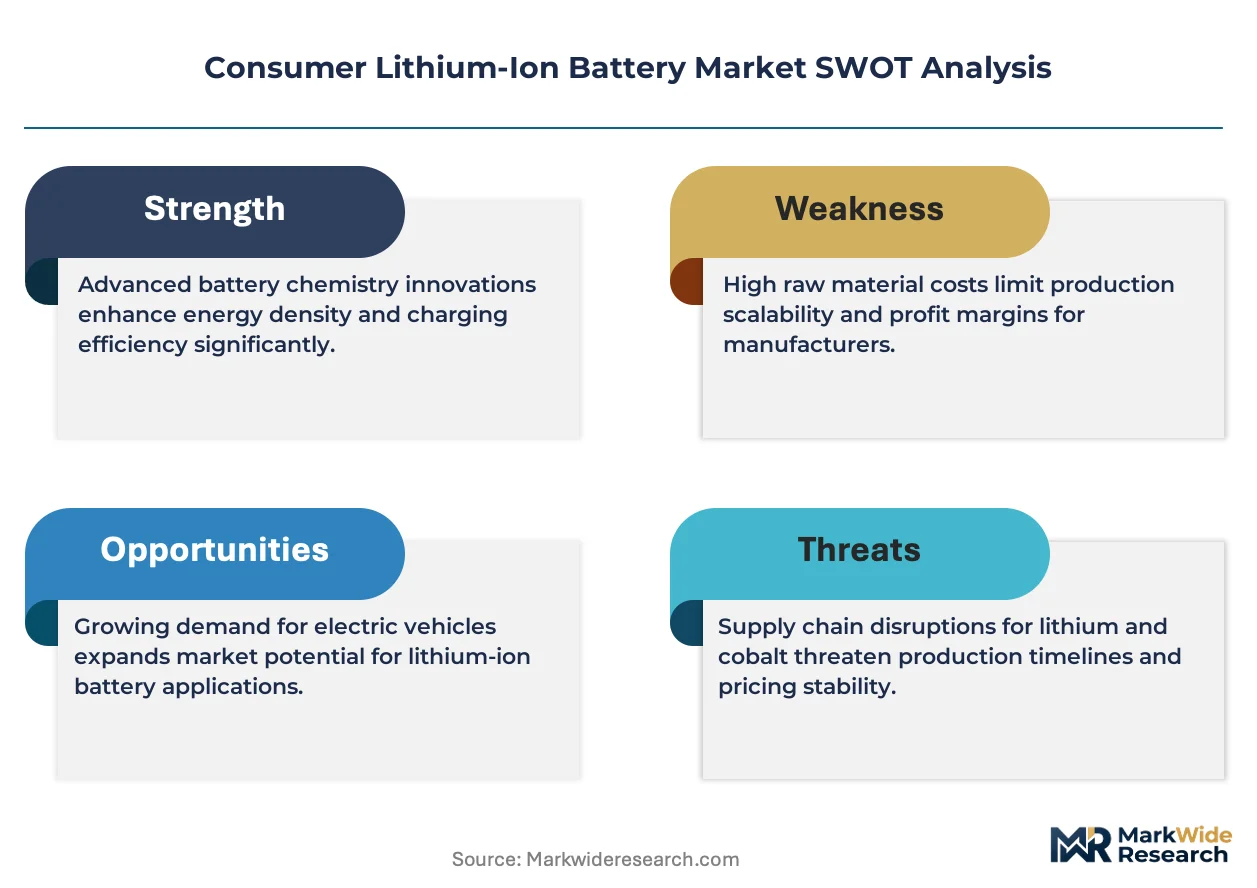
- High-discharge Li-NMC chemistry:Power tool OEMs and electric scooter fleets in Vietnam and Indonesia are standardizing on nickel-manganese-cobalt formulations that sustain 3C continuous discharge rates without thermal runaway.
- EU Battery Regulation recycled content mandates:Digital passport requirements and minimum recycled lithium thresholds are accelerating closed-loop material flows among cell exporters targeting European consumer electronics channels.
- Fujian-Sichuan cathode integration:Integrated precursor-to-cathode production corridors are securing refined lithium hydroxide streams against spot market volatility for premium smartphone cell output.
Market Restraints
- Graphite anode supply concentration:Spherical purified graphite for silicon-blend anodes concentrates in Heilongjiang and Shandong provinces, exposing cell makers to single-source dependency risks.
- Cycle life degradation in silicon-rich blends:Volume expansion above 300% during lithiation fractures solid-electrolyte interphase layers, limiting commercial silicon loadings to sub-10% weight fractions despite theoretical capacity advantages.
- Carbon border adjustment friction:The EU's embedded emissions calculation methodology for imported cells creates compliance cost asymmetries against domestic European cell assembly operations.
Strategic Opportunities
- Wearable micro-cell form factors:Sub-50mAh curved pouch configurations for hearables and skin-patch medical devices remain undersupplied relative to projected demand from Shenzhen and Dongguan electronics clusters.
- India BIS certification pathway:Compulsory registration scheme expansion for lithium-ion cells creates first-mover positioning for manufacturers establishing local testing partnerships before 2025 enforcement windows.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator development for consumer cells above 4.4V nominal voltage is opening architecture differentiation against liquid-electrolyte incumbents in premium laptop segments.
Industry Challenges
- Dry electrode coating scale-up:Solvent-free electrode manufacturing requires 200+ MPa calendering pressures that degrade coating uniformity at production speeds above 50 meters per minute, constraining throughput for silicon-anode layers.
- UN 38.3 certification backlog:Third-party testing laboratory capacity for lithium cell air transport safety validation creates 12-16 week queue delays that compress product launch windows for seasonal consumer electronics cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Lithium-Ion Battery Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Electronics, Power Tools, Electric Vehicles, Wearable Devices Application: Smartphones, Laptops, Electric Scooters, Drones Technology: Li-NMC, Li-Polymer, Li-Ion, Li-iron Phosphate End User: Consumer Electronics, Automotive, Industrial, Healthcare |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, SAMSUNG SDI, BYD Company Ltd., SK On, Amperex Technology Limited, Toshiba Corporation, A123 Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Lithium-Ion Battery Market Trends and Innovations
Electrochemical system architectures are bifurcating between cost-optimized graphite-dominant cells for mass-market portable electronics and silicon-blend premium configurations for extended-range micromobility and high-drain wearables.
Silicon nanowire composite anodes are electrifying energy density trajectories for premium smartphone and laptop packs by accommodating 3579 mAh/g theoretical capacity against graphite's 372 mAh/g limit. Korean and Chinese cell makers are qualifying 5-10% silicon oxide loadings for 2024 flagship device launches. This chemistry transition is electrifying tiered product segmentation between endurance-focused premium SKUs and value-optimized standard configurations.
The EU Battery Regulation's digital passport mandate is forcing upstream material provenance documentation from mine site through cell assembly for all batteries placed on the European market. Cell importers must deploy blockchain-anchored chain-of-custody systems to satisfy recycled content verification requirements. Premium consumer electronics brands with European distribution are absorbing compliance costs into supplier qualification programs that exclude non-compliant Asian mid-tier cell sources.
Fleet procurement consolidation among Southeast Asian electric scooter operators is compressing supplier negotiation cycles from annual frameworks to quarterly volume commitments with price reopener clauses. Indonesian and Vietnamese mobility platforms are bypassing traditional electronics distributors to contract directly with cylindrical cell specialists for 18650 and 21700 format supply. This disintermediation is most visible in Jakarta and Ho Chi Minh City where fleet operators now represent 40% of regional high-discharge cell offtake.
Consumer Lithium-Ion Battery Market Segmentation
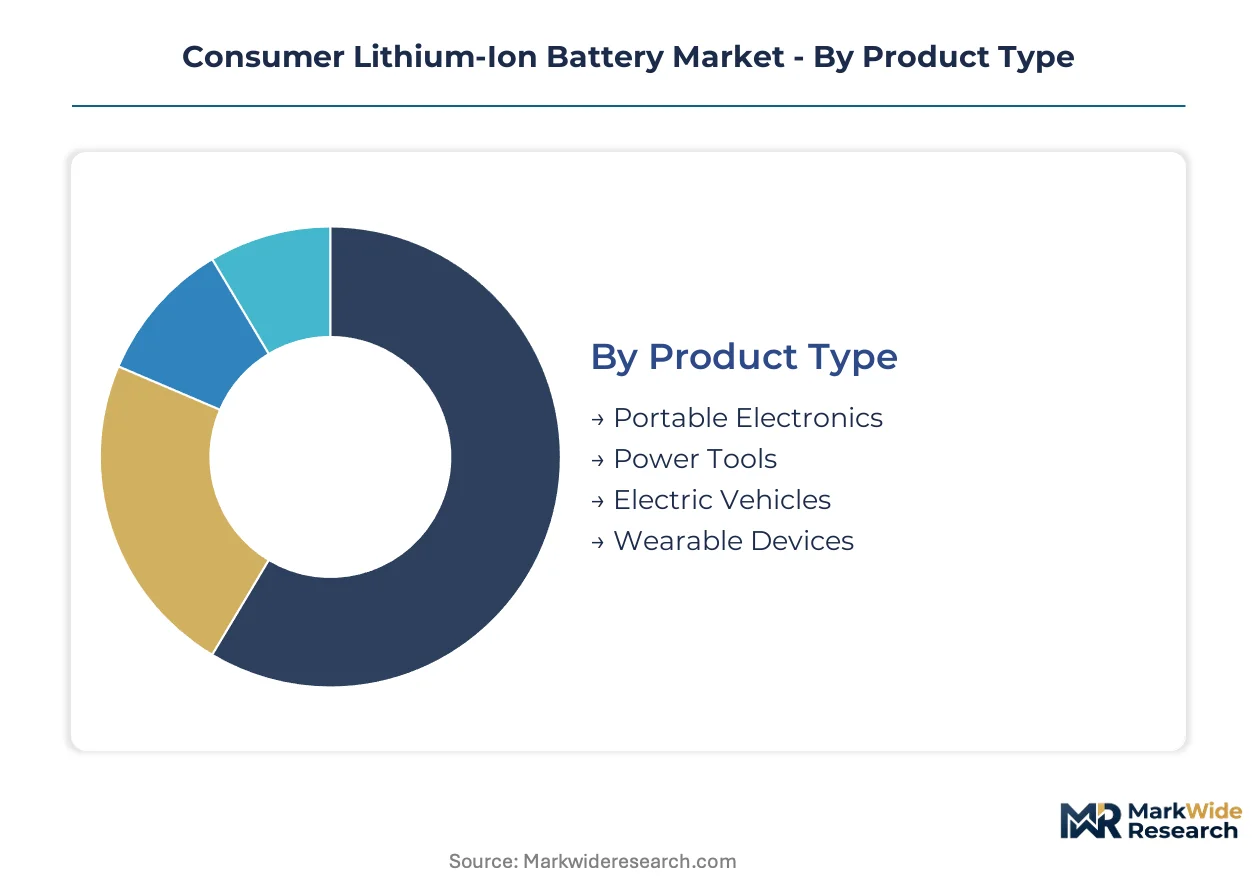
Segmentation in consumer lithium-ion batteries reveals how certification requirements, chemistry choices, and end-use durability demands fragment procurement strategies across electronics OEMs. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier qualification timelines.
Product Type:
UN 38.3 air transport certification and IEC 62133 safety testing apply differentially across product categories, with micromobility and power tool segments facing the most stringent thermal runaway documentation.
- Portable Electronics:Slim-form pouch cells dominate smartphone and tablet configurations where mechanical flexibility trumps absolute energy density. Demand concentrates in Shenzhen and Dongguan manufacturing clusters where OEMs specify sub-4mm thickness tolerances and 500-cycle minimum lifespans.
- Power Tools:Cylindrical 18650 and 21700 formats sustain 3C continuous discharge rates for cordless drill and saw platforms. Milwaukee Tool and Stanley Black & Decker procurement teams in North America prioritize cell consistency over energy density for thermal stability under load.
- Electric Vehicles:Consumer-grade micromobility applications including electric scooters and e-bikes require high-discharge 21700 cells with reinforced safety vents. Vietnamese and Indonesian fleet operators now represent the fastest-expanding demand channel within this segment.
- Wearable Devices:Sub-50mAh curved pouch configurations serve hearables and skin-patch medical applications where form factor constraints override capacity optimization.
Leading the category by volume: Portable Electronics. Growing fastest: Electric Vehicles.
Application:
End-use durability requirements and replacement cycle frequency determine whether OEMs prioritize cycle life, energy density, or discharge rate in cell specification.
- Smartphones:Silicon-blend anode architectures at 5-10% loading are penetrating flagship device tiers where 4500mAh+ capacities differentiate premium SKUs. Samsung and Apple supply chains in Vietnam and India absorb most incremental high-density cell output.
- Laptops:Prismatic and pouch formats at 11.1V nominal voltage dominate thin-and-light categories where 100Wh airline carry-on limits constrain pack design. Dell and HP procurement specifications emphasize 800-cycle lifespans for enterprise fleet deployments.
- Electric Scooters:Swappable battery architectures in Jakarta and Ho Chi Minh City fleet operations standardize on 21700 cylindrical cells with IP67 ingress protection.
- Drones:High-C-rate Li-Polymer packs for commercial UAV platforms prioritize discharge consistency over energy density for stable voltage under hover load.
Smartphones command the largest absolute cell volume. Electric Scooters are climbing the fastest as fleet procurement consolidates.
Technology:
Material chemistry selection directly determines which GB standards, JIS frameworks, or EU Battery Regulation recycled content thresholds apply to cell export qualification.
- Li-NMC:Nickel-manganese-cobalt oxide cathodes deliver 200+ Wh/kg energy density with 3C discharge capability for power tools and micromobility. Chinese SAMR cycle life testing and EU digital passport mandates impose parallel compliance burdens on NMC cell exporters.
- Li-Polymer:Gel electrolyte pouch configurations enable sub-3mm form factors for wearable and smartphone applications where mechanical abuse tolerance matters more than cost-per-Wh.
- Li-Ion:Traditional liquid-electrolyte cylindrical formats retain cost advantages in mass-market portable electronics where standardization outweighs performance differentiation.
- Li-iron Phosphate:LFP chemistry trades energy density for thermal stability and cycle life, penetrating entry-level electric scooter segments where safety certification costs dominate procurement decisions.
Li-NMC holds the dominant revenue share. Li-iron Phosphate is gaining share fastest in cost-sensitive micromobility applications.
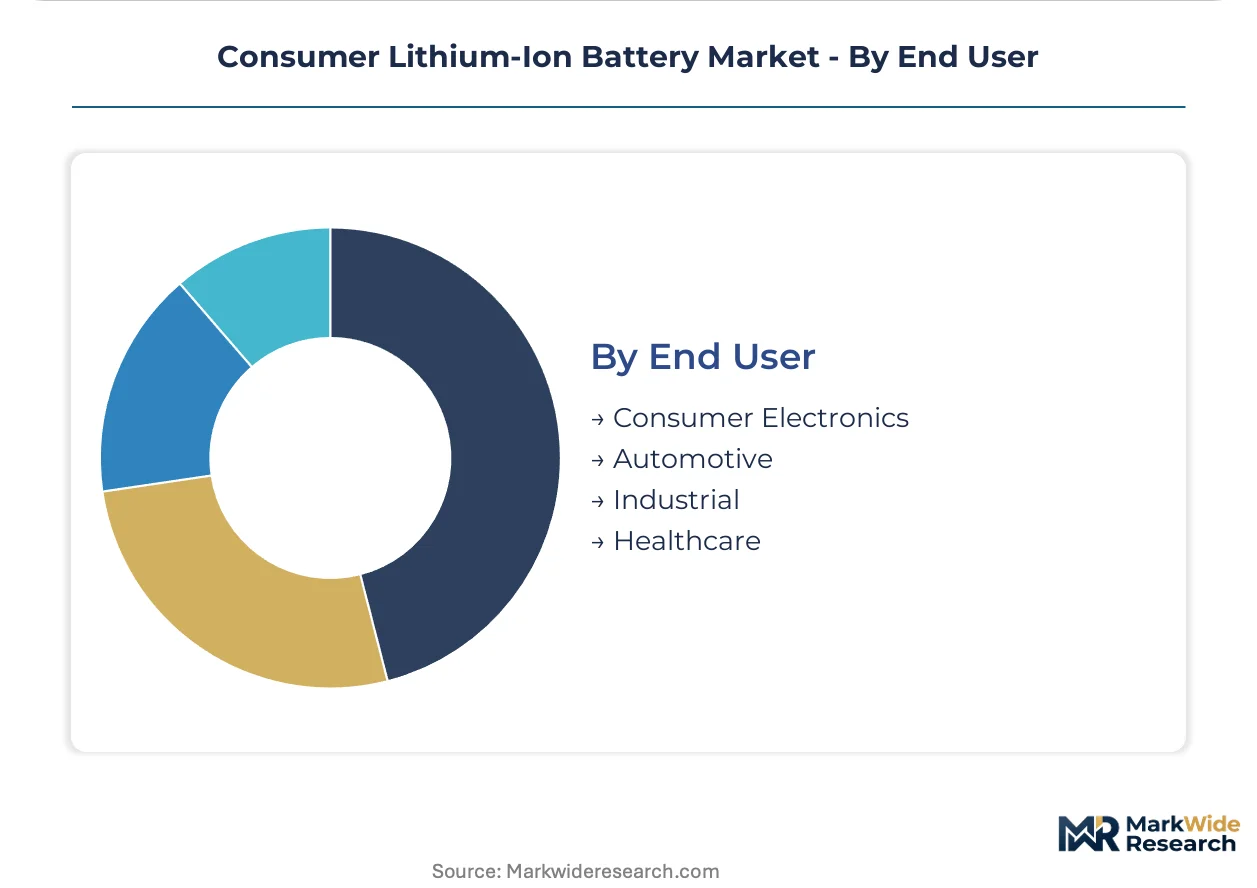
End User:
Customer procurement sophistication and volume scale determine whether cell suppliers compete on specification flexibility, price, or integrated module design services.
- Consumer Electronics:Smartphone and laptop OEMs in China, Vietnam, and India specify cell dimensions and connector configurations 18-24 months ahead of product launch, locking suppliers into dedicated production lines.
- Automotive:Electric scooter fleet operators in Southeast Asia bypass traditional electronics distributors to contract directly with cylindrical cell specialists for quarterly volume commitments with price reopener clauses.
- Industrial:Power tool OEMs and cordless equipment manufacturers prioritize cell-to-cell voltage consistency for pack balancing in high-vibration operating environments.
- Healthcare:Skin-patch and continuous glucose monitor applications require ISO 13485 quality system certification and lot-level traceability that excludes most consumer-grade cell suppliers.
Consumer Electronics leads by cell volume. Automotive is expanding most quickly as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric scooter fleet procurement concentrates in Vietnamese and Indonesian metropolitan corridors, while smartphone OEM demand clusters in Shenzhen, Dongguan, and Ho Chi Minh City manufacturing zones. China's integrated cathode production corridors and the EU Battery Regulation's digital passport mandates are redirecting export compliance investments across Asian cell manufacturing hubs.
China
Shenzhen and Dongguan electronics clusters drive premium smartphone cell demand with sub-4mm thickness specifications. SAMR enforces GB standards for cycle life and safety testing that determine factory access to domestic supply chains. Fujian-Sichuan integrated precursor-to-cathode production corridors secure refined lithium hydroxide streams against spot market volatility.
Vietnam
Ho Chi Minh City fleet operators now represent 40% of regional high-discharge cell offtake for electric scooter swappable battery architectures. Samsung and Apple supply chains absorb most incremental high-density silicon-blend cell output for flagship device production. Local procurement teams specify cell dimensions 18-24 months ahead of product launch.
Indonesia
Jakarta micromobility platforms bypass traditional electronics distributors to contract directly with cylindrical cell specialists for quarterly volume commitments. Fleet procurement consolidation compresses supplier negotiation cycles from annual frameworks to quarterly price reopener clauses. IP67 ingress protection specifications dominate 21700 format demand.
South Korea
Seoul Capital Area cell makers qualify 5-10% silicon oxide loadings for 2024 flagship device launches. Korean manufacturers anchor consumer divisions in cylindrical and pouch formats for power tool OEMs. METI-aligned JIS frameworks influence regional procurement specifications across Northeast Asian electronics channels.
Japan
Kansai and Chubu industrial corridors compete on cylindrical cell consistency for high-drain wearable applications. METI reviews consumer battery standards through JIS frameworks that shape regional qualification timelines. Domestic manufacturers prioritize cell-to-cell voltage consistency for pack balancing in high-vibration operating environments.
Consumer Lithium-Ion Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated cathode production corridors secure raw material streams against spot market volatility. The vendor base stratifies across three tiers: diversified energy conglomerates with upstream mining interests, specialized cell manufacturers with format-specific expertise, and regional fabricators serving local electronics clusters. Tier-one players compete on specification flexibility and dedicated production line commitments, while mid-tier specialists differentiate through silicon-anode qualification timelines. Strategic archetypes include backward-integrated material controllers, format-focused cylindrical/pouch specialists, and premium-tier solid-state electrolyte developers. Geographic expansion and technology licensing represent the dominant competitive moves, with Asian manufacturers establishing local testing partnerships ahead of BIS and EU certification deadlines.
Within the diversified conglomerate tier, Contemporary Amperex Technology Co. Limited exemplifies backward-integrated material control through captive cathode production, while LG Energy Solution occupies a position as a format-focused specialist with cylindrical and pouch expertise. Panasonic Holdings Corporation anchors the premium-tier vector for high-drain wearable consistency. These three entities represent distinct strategic archetypes: integrated material security, format specialization, and precision manufacturing for medical-grade applications.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| SAMSUNG SDI |
| BYD Company Ltd. |
| SK On |
| Amperex Technology Limited |
| Toshiba Corporation |
| A123 Systems LLC |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's recycled content mandates gate qualified supply for premium-tier pricing access, forcing cell exporters to absorb digital passport compliance costs before European consumer electronics channels open. This sustainability threshold fragments procurement into certified premium streams and standard-grade alternatives.
Pricing Analysis
Volume-mass-market portable electronics splits from margin-rich premium smartphone and micromobility segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and silicon-anode loading intensity. Pricing pressure stems from GB standards compliance investments in Fujian-Sichuan production corridors. Power tool OEMs exhibit highest price sensitivity due to annual procurement cycles, while healthcare device manufacturers tolerate premium tiers for ISO 13485 traceability.
Supply Chain Analysis
Single-source vulnerability sits with spherical purified graphite production concentrating in Heilongjiang and Shandong provinces. Raw material streams draw from lithium hydroxide refining in Sichuan, nickel sulfate processing in Indonesia, and cobalt hydroxide shipments from the DRC. Tariff exposure through carbon border adjustment mechanisms threatens export cost structures. Distribution runs through Shenzhen and Dongguan electronics clusters for domestic Chinese OEMs, with Ho Chi Minh City and Jakarta emerging as direct fleet procurement nodes bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spherical graphite purification capacity constraints prop pricing power for qualified anode suppliers, transforming this market into a supply-constrained story where certification timelines determine factory access.
For Market Incumbents: Lock in cathode precursor supply through Fujian-Sichuan corridor partnerships before spot market volatility intensifies. Secure dedicated production line commitments from Samsung and Apple supply chains in Vietnam and India. Invest in dry electrode coating scale-up to defend throughput advantages against emerging solid-state electrolyte developers. For New Entrants and Emerging Players: Solid-state electrolyte convergence above 4.4V nominal voltage offers technology-first wedge positioning against liquid-electrolyte incumbents in premium laptop segments. Target wearable micro-cell form factors in Shenzhen-Dongguan electronics clusters where sub-50mAh curved pouch configurations remain undersupplied. Pursue India BIS certification partnerships ahead of enforcement windows to establish first-mover laboratory relationships. For Investors and Strategic Acquirers: Quarterly volume commitment reopener clauses in Jakarta and Ho Chi Minh City fleet contracts are the leading indicator that procurement consolidation is accelerating pricing transparency. Five-to-ten year viability favors backward-integrated material controllers with captive cathode production. Watch for UN 38.3 certification backlog resolution as the inflection signal for seasonal product launch window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Passport Compliance Investment | EU Battery Regulation mandates force blockchain-anchored provenance systems for recycled content verification. |
| Silicon-Anode Qualification Acceleration | Korean and Chinese cell makers compete on 5-10% silicon oxide loading timelines for flagship device launches. |
| Fujian-Sichuan Corridor Integration | Captive precursor-to-cathode production secures lithium hydroxide streams against spot market volatility. |
| Wearable Micro-Cell Capacity Addition | Sub-50mAh curved pouch configurations address undersupply in hearables and skin-patch medical applications. |
| India BIS Certification Partnership | Local testing relationships create defensible positioning before compulsory registration scheme enforcement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this consumer lithium-ion battery assessment. Primary interviews with cell procurement managers at smartphone OEMs, fleet operations directors at Indonesian micromobility platforms, and cathode plant managers in Sichuan province combined with SAMR GB standard documentation, EU Battery Regulation implementation guidance, and UN 38.3 certification databases. Bottom-up cell shipment tallies by format and chemistry triangulated against top-down electronics OEM production forecasts.
Data-stream reconciliation across product type, application technology, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating electric scooter fleet procurement consolidation patterns and silicon-anode adoption trajectories in premium smartphone tiers. Modeled outputs reflect differential compliance cost absorption rates across certified and non-certified supplier tiers.
Several conditions sit outside the modeled scope, including speculative solid-state electrolyte commercialization timelines and unannounced carbon border adjustment rate structures. Forecasts reflect documented assumptions about GB standards enforcement consistency and EU digital passport technical specification finalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market