
 Sodium-Ion Battery Market | 2026-2036
Sodium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium-Ion Battery Market Intelligence
OEM-direct supply contracts for electric two-wheelers is rewriting how sodium-ion cells reach end users in Asia. Contemporary Amperex Technology Co. Limited leverages its existing lithium-ion manufacturing footprint to anchor sodium-ion pilot lines at scale. HiNa Battery Technology Co. Ltd. specializes in prismatic formats for grid storage applications. Faradion Limited competes through hard carbon anode expertise developed at its UK research base.
A sodium-ion battery electrochemically stores energy through sodium-ion intercalation into hard carbon or soft carbon anodes paired with sodium manganese oxide cathodes, achieving energy densities of 100-160 Wh/kg with operating voltages near 3.1V, primarily serving cost-sensitive applications where lithium supply risk or price volatility threatens project economics. Prismatic formats dominate current manufacturing commitments because pack integration simplicity attracts grid storage developers seeking to minimize balance-of-system costs. Solid-state sodium-ion architectures represent the fastest-growing technology segment as polymer-ceramic electrolyte research from multiple laboratories approaches commercial thresholds.
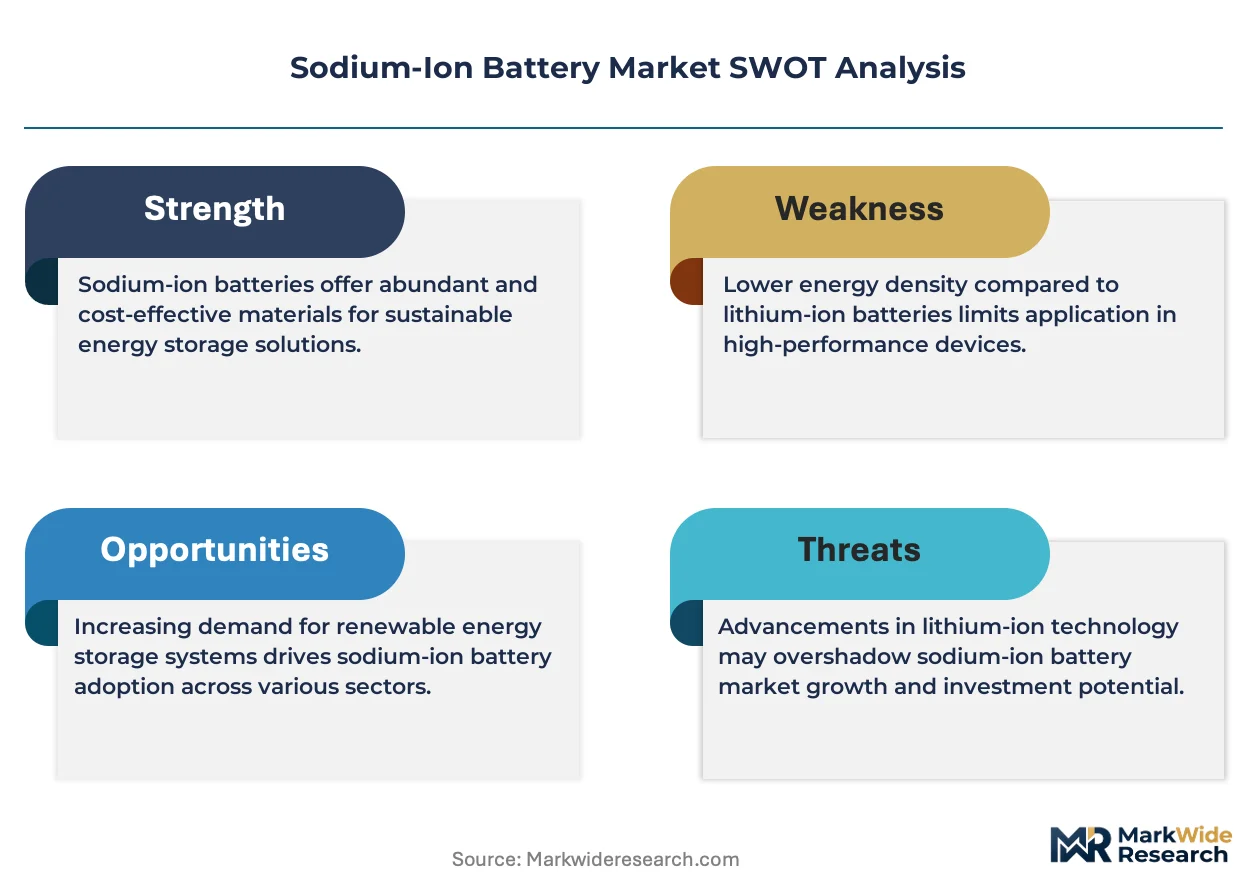
The EU's F-Gas Regulation and CE marking requirements under the EU Green Deal shape product standards for imported sodium-ion modules entering European renewable energy installations. China's GB standards from SAMR and MIIT directives govern domestic cell certification, while India's BIS and PLI scheme create conditional market access for foreign suppliers targeting public transportation tenders. Stakeholders must monitor how rapidly evolving cathode chemistries alter certification baselines and whether supply chain localization mandates in major economies fragment manufacturing geography.
Market Dynamics
The sodium-ion battery sector is experiencing a fundamental supply-side reconfiguration as lithium carbonate price volatility and China's dual carbon goals from the MEE force cell manufacturers to diversify cathode chemistries. Hard carbon anode sourcing and sodium manganese oxide production are concentrating in Jiangsu and Hunan provinces.
Growth Catalysts
- China's dual carbon goals:The MEE mandates drive state-owned grid operators to procure sodium-ion systems for stationary storage, bypassing lithium supply constraints.
- Hard carbon anode advances:Biomass-derived precursor processing is lowering material costs for prismatic cell formats targeting grid applications.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in energy infrastructure is accelerating sodium-based chemistry adoption in renewable installations.
Market Restraints
- Energy density ceiling:Sodium-ion cells top out near 160 Wh/kg, excluding them from premium electric vehicle platforms requiring 250+ Wh/kg.
- Hard carbon supply concentration:Biomass precursor processing capacity clusters in China, creating geographic single-point vulnerability.
- CE marking complexity:Evolving EU battery passport requirements under the EU Green Deal extend certification timelines for imported modules.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing create entry pathways for sodium-ion suppliers targeting public transportation tenders.
- Two-wheeler electrification:Southeast Asian markets with price-sensitive consumers represent untapped demand for sodium-ion powered scooters and motorcycles.
- Solid-state convergence:Polymer-ceramic electrolyte research is opening pathways to higher-voltage sodium metal anode architectures.
Industry Challenges
- Electrolyte formulation expertise:Sodium-compatible electrolyte salt synthesis requires chemists with rare specialized training, constraining pilot line scaling.
- GB standard alignment:China's SAMR and MIIT certification updates for new cathode compositions force continuous re-qualification of cell designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium-Ion Battery Market |
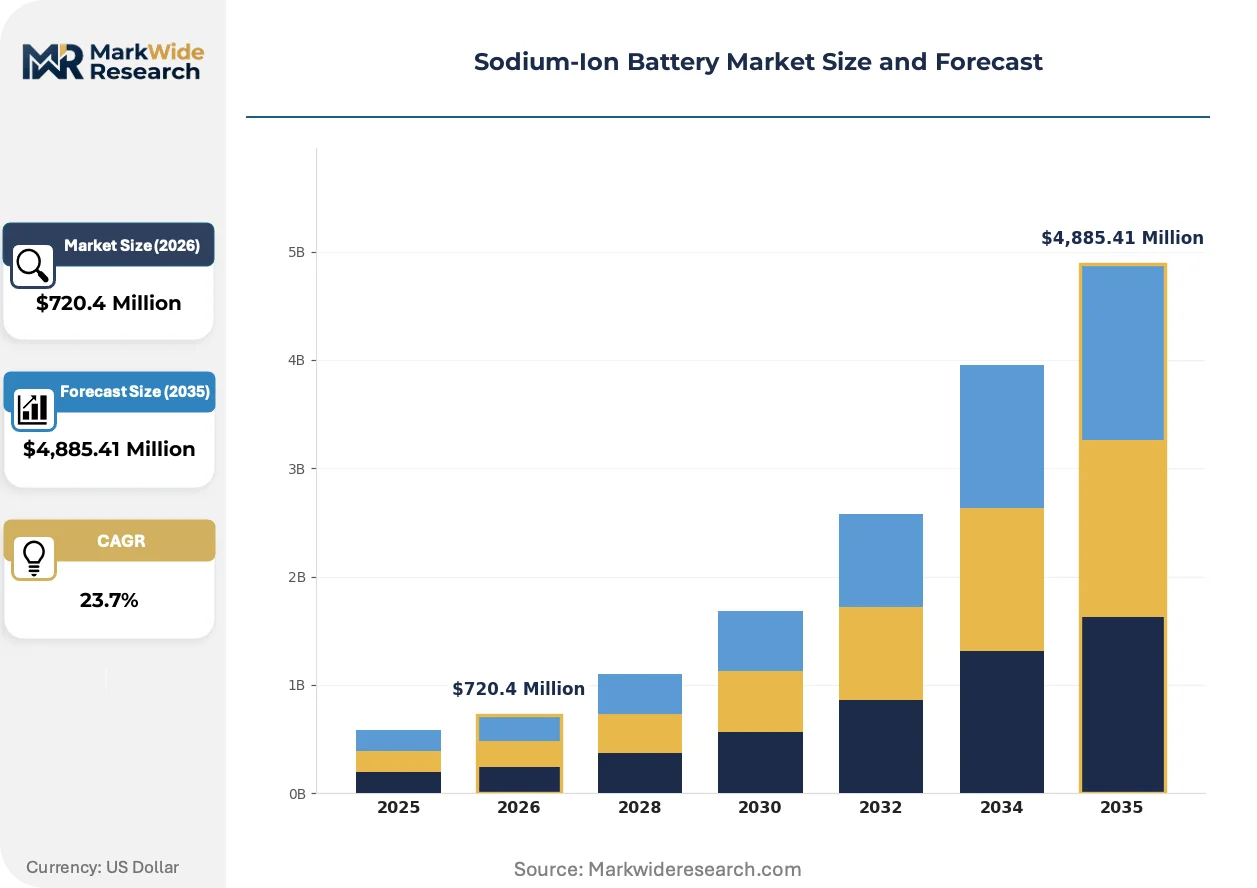
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $4,885.41 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Solid-state Technology: Hard Carbon, Soft Carbon, Composite Carbon, Sodium Manganese Oxide Application: Grid Storage, Electric Bicycles, Portable Electronics, Marine Energy Storage End User Industry: Public Transportation, Consumer Devices, Renewable Energy, Data Centers |
| Companies Covered | Contemporary Amperex Technology Co. Limited, HiNa Battery Technology Co. Ltd., Faradion Limited, Altris AB, Natron Energy Inc., TIAMAT SAS, NGK Insulators Ltd, Aquion Energy, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium-Ion Battery Market Strategic Shifts & Innovations
Sodium-ion technology is advancing through three interconnected vectors: electrode material evolution, regulatory chemistry mandates, and procurement model restructuring. Each vector is compressing development cycles and redrawing competitive boundaries.
Hard carbon anode technology is migrating from laboratory-scale biomass pyrolysis to continuous-roll manufacturing systems. Stationary storage developers in Europe are qualifying these anodes for 6,000+ cycle life requirements. The shift is compressing the cost gap with graphite anodes from lithium-ion systems.
The EU's F-Gas Regulation is banning fluorinated greenhouse gases from grid-scale battery thermal management systems by 2030. Sodium-ion chemistries with non-fluorinated electrolytes gain automatic compliance advantage. German and Dutch renewable developers are prioritizing sodium-ion modules in RFP scoring.
Cell procurement is consolidating around OEM-direct contracts for electric two-wheeler platforms. Asian manufacturers are bypassing traditional distributor networks to secure volume commitments. This disintermediation is most visible in China's Jiangsu province, where gigafactory output is pre-allocated to scooter assemblers through multi-year offtake agreements.
Sodium-Ion Battery Market Segmentation
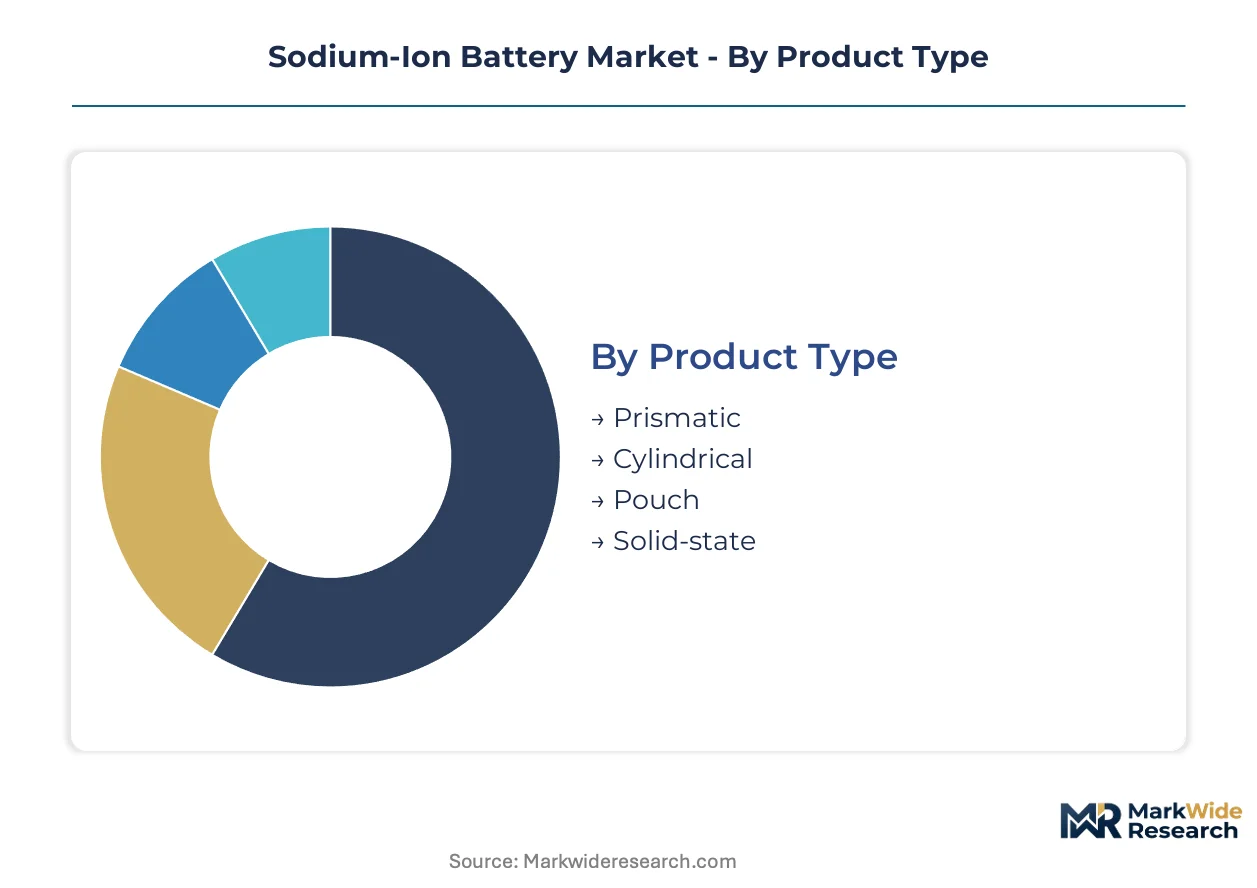
Sodium-ion battery segmentation reveals how cell geometry, electrode chemistry, and end-use economics intersect. Manufacturers configure product portfolios around specific voltage windows and cycle life requirements rather than pursuing universal formats.
Product Type:
Cost tier differentiation across cell geometries determines which applications prove economically viable at current manufacturing scales.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers deliver simplified pack integration and thermal management. Grid storage developers in Jiangsu province favor this format for minimizing balance-of-system costs in containerized installations.
- Cylindrical:Rolled jellyroll construction inside steel cans leverages mature winding equipment from lithium-ion production lines. The format dominates electric bicycle battery packs where vibration resistance and automated assembly matter most.
- Pouch:Laminated foil enclosures enable flexible form factors and weight optimization for portable electronics. Consumer device OEMs specify pouch cells when space constraints override cycle life priorities.
- Solid-state:Polymer-ceramic electrolyte architectures replace liquid electrolytes with ion-conducting membranes. Laboratory research from multiple EU-funded consortia approaches commercial thresholds for higher-voltage operation.
Prismatic holds installed capacity. Solid-state is rotating up the share rankings.
Technology:
Application requirements determine which anode-cathode pairings achieve commercial traction versus remaining in pilot production.
- Hard Carbon:Biomass-derived pyrolyzed carbon structures accommodate sodium-ion intercalation with minimal volume expansion. Jiangsu and Hunan province manufacturers are scaling continuous-roll processing for 6,000+ cycle life grid storage contracts.
- Soft Carbon:Graphitic microcrystalline domains from petroleum coke precursors offer lower cost but reduced capacity. The chemistry serves price-sensitive electric two-wheeler markets where energy density requirements stay modest.
- Composite Carbon:Engineered blends of hard and soft carbon domains balance rate capability with cost. Material suppliers in China are qualifying composite formulations for data center backup power applications.
- Sodium Manganese Oxide:Layered oxide cathodes provide voltage stability and manganese abundance without nickel or cobalt dependencies. The chemistry aligns with EU F-Gas Regulation compliance for renewable energy installations.
Hard carbon dominates procurement volumes. Sodium manganese oxide is climbing the fastest as cathode standardization accelerates.
Application:
Volume concentration varies dramatically across use cases based on price tolerance and performance specifications.
- Grid Storage:Megawatt-hour scale stationary systems prioritize cycle life and capital cost over gravimetric energy density. State-owned operators under China's MEE directives are procuring sodium-ion systems to bypass lithium supply constraints.
- Electric Bicycles:Light electric vehicle platforms accept 100-160 Wh/kg densities when cell costs drop below lithium-ion alternatives. OEM-direct contracts from Jiangsu gigafactories are pre-allocating output to scooter assemblers.
- Portable Electronics:Consumer devices demand compact formats where sodium-ion's size penalty limits addressable share. Niche applications in outdoor equipment exploit the chemistry's wider temperature tolerance.
- Marine Energy Storage:Saltwater-compatible electrolytes and non-flammable thermal profiles suit maritime auxiliary power. European shipbuilders are qualifying sodium-ion for harbor craft electrification under EU Green Deal timelines.
Grid storage commands committed capacity. Marine energy storage is expanding most quickly as harbor regulations tighten.
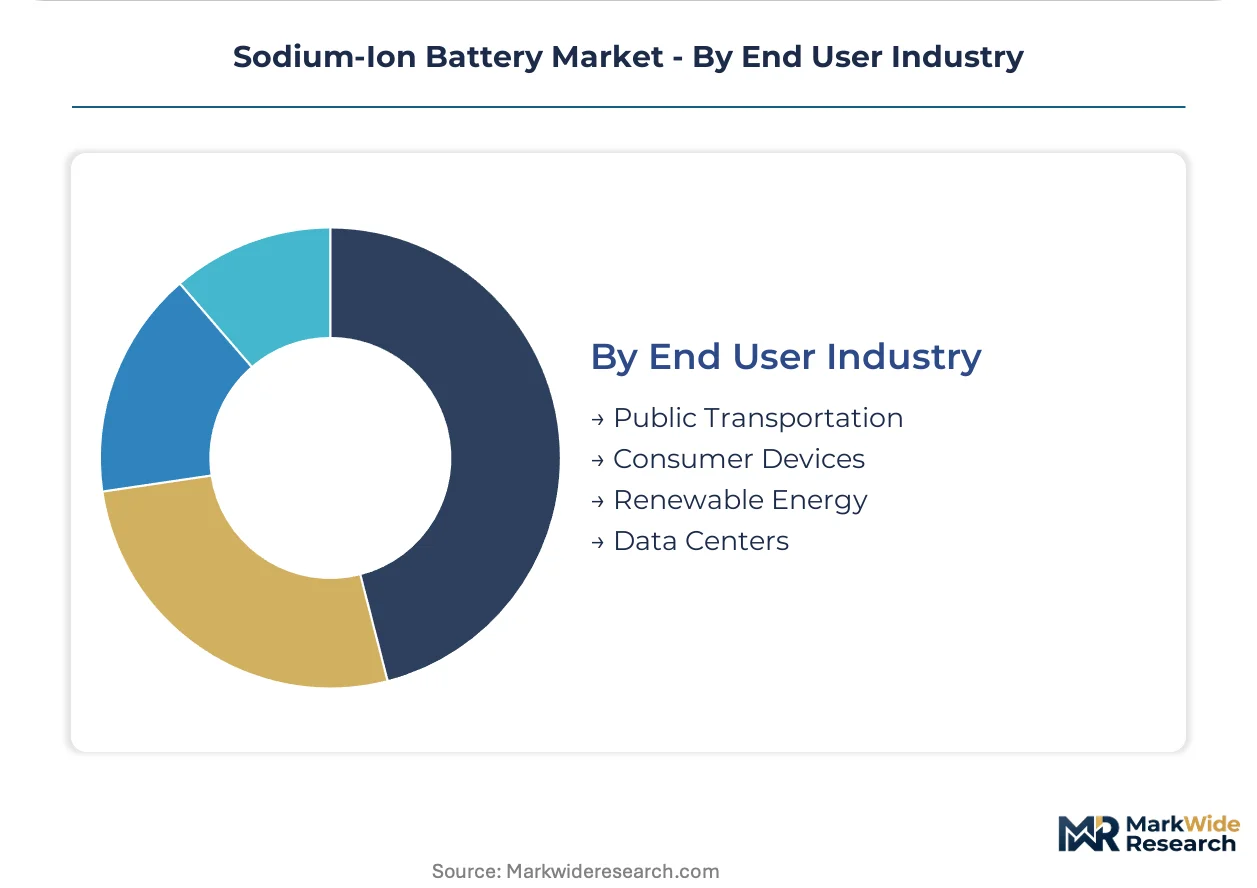
End User Industry:
Customer type determines procurement scale, certification requirements, and contract structure for cell suppliers.
- Public Transportation:Municipal bus and rail operators issue volume tenders with stringent safety certification. India's PLI scheme creates conditional market access for foreign suppliers targeting state transit authorities.
- Consumer Devices:Electronics OEMs negotiate annual pricing with flexibility for rapid specification changes. The segment demands fastest delivery cycles and lowest minimum order quantities.
- Renewable Energy:Solar and wind farm developers integrate storage for grid stabilization and energy shifting. German and Dutch developers prioritize sodium-ion modules in RFP scoring due to F-Gas Regulation alignment.
- Data Centers:Hyperscale computing facilities require uninterruptible power with fire safety redundancy. The sector values sodium-ion's thermal runaway resistance for indoor installations.
Renewable energy holds contracted pipeline. Data centers are gaining share fastest as fire code restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's high-voltage grid interconnects position China as the primary demand sink for sodium-ion storage systems. European port electrification programs and India's industrial corridor expansion create secondary growth poles.
China
Jiangsu and Hunan provinces host seven active gigafactory projects supplying state-owned grid operators under MEE dual carbon mandates. GB standards from SAMR and MIIT govern cell certification for stationary storage tenders. Nantong and Changsha industrial clusters concentrate hard carbon anode processing capacity for prismatic cell output.
Germany
North Rhine-Westphalia's renewable developers prioritize sodium-ion modules in RFP scoring to satisfy EU F-Gas Regulation phase-down timelines. The KBA and federal network agency coordinate harbor craft electrification standards for maritime auxiliary power. Düsseldorf-Cologne logistics corridors distribute imported cells to Dutch and Belgian grid installations.
India
Maharashtra and Gujarat state transit authorities issue volume tenders for electric bus fleets under the PLI scheme's advanced chemistry cell manufacturing incentives. BIS certification requirements create conditional market access for foreign suppliers. Mumbai-Ahmedabad industrial belt assemblers pre-allocate sodium-ion output to two-wheeler OEMs.
United States
Texas ERCOT grid operators evaluate sodium-ion systems for frequency regulation as lithium supply risk enters procurement calculations. FERC Order 2222 enables distributed storage aggregation models favoring cost-competitive chemistries. Houston-Gulf Coast petrochemical corridors repurpose existing carbon precursor processing for hard carbon anode supply.
Japan
Tokyo Bay industrial zones qualify sodium-ion cells for data center backup power under METI fire safety guidelines. JIS standards from the Ministry of Economy, Trade and Industry govern module certification for indoor installations. Kawasaki-Yokohama manufacturing clusters develop composite carbon anode formulations for niche electronics applications.
Sodium-Ion Battery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in anode, cathode, and electrolyte supply. The vendor base splits between diversified battery conglomerates repurposing lithium-ion infrastructure and pure-play sodium specialists building dedicated pilot lines. Two archetypes dominate: incumbent diversifiers leveraging existing manufacturing footprints, and chemistry-native startups scaling novel electrode formulations. Capacity expansion and strategic partnerships constitute the primary competitive moves, with OEM-direct offtake agreements replacing traditional distributor networks.
Among China-based fabricators, Contemporary Amperex Technology Co. Limited and HiNa Battery Technology Co. Ltd. occupy positions spanning both archetypes. Faradion Limited anchors the European specialist tier. These three exemplify how geographic concentration in Jiangsu and UK research bases shapes competitive positioning without requiring uniform scale or technology strategies.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| HiNa Battery Technology Co. Ltd. |
| Faradion Limited |
| Altris AB |
| Natron Energy Inc. |
| TIAMAT SAS |
| NGK Insulators Ltd |
| Aquion Energy |
| BYD |
| Others |
Cost & Logistics Intelligence
Jiangsu province's gigafactory clusters concentrate prismatic cell capacity, granting Chinese manufacturers asymmetric leverage over contract negotiations with European renewable developers and Indian transit authorities. This geographic chokepoint transmits upstream biomass precursor costs directly into module pricing for grid storage tenders.
Pricing Analysis
Volume-discount tiering separates gigawatt-hour offtake agreements from container-scale procurement and pilot-line sampling orders. Certification grade under EU F-Gas Regulation and China's GB standards drives price differentiation between compliant and pre-certified modules. Cost compression in economy-tier cells is intensifying because hard carbon anode suppliers compete for biomass feedstock with activated carbon producers. Public transportation tenders exhibit highest price sensitivity; data center operators prioritize thermal safety specifications over unit economics.
Supply Chain Analysis
Supplier-financing facilities from Jiangsu equipment vendors extend payment terms to 180 days for electrolyte salt and separator producers scaling pilot lines. Hard carbon anode production draws from coconut shell and rice husk precursors concentrated in China, India, and Southeast Asia. Single-source vulnerability clusters in biomass pyrolysis capacity along the Yangtze River Delta. Distribution runs through OEM-direct contracts bypassing traditional cell distributors for electric two-wheeler and grid storage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium-ion chemistry constitutes a high-growth disruption as solid-state polymer-ceramic architectures approach commercial thresholds and EU F-Gas Regulation mandates eliminate fluorinated electrolyte competitors from renewable installations.
For Market Incumbents: Pre-empt solid-state specialists by securing exclusive hard carbon anode offtake from Jiangsu biomass processors before capacity constraints tighten. Anchor lithium-ion manufacturing footprints with dedicated sodium-ion pilot lines to defend against pure-play entrants targeting grid storage tenders. Prioritize GB standard and CE marking certification investment to maintain access to Chinese state-owned operator and European renewable developer procurement channels. For New Entrants and Emerging Players: India's Maharashtra and Gujarat state transit authorities represent underpenetrated demand for electric bus fleet tenders under PLI scheme incentives. Marine energy storage for European harbor craft electrification offers white-space positioning with less incumbent saturation than grid storage. Pursue joint development agreements with German shipbuilders to establish qualification credentials before scaling manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry play because electrode formulation expertise constrains pilot line scaling more than capital availability. Target acquisition candidates with proprietary hard carbon precursor processing or sodium manganese oxide cathode IP rather than pack assemblers. Monitor solid-state electrolyte research milestones from EU-funded consortia as the inflection signal for technology leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hard Carbon Anode Capacity Buildout | Jiangsu and Hunan province manufacturers secure biomass precursor supply for 6,000+ cycle life grid contracts. |
| OEM-Direct Offtake Agreement | Scooter assemblers in China's Jiangsu province lock volume commitments bypassing traditional distributor networks. |
| Solid-State Electrolyte R&D Partnership | EU-funded polymer-ceramic research consortia approach commercial thresholds for higher-voltage sodium metal architectures. |
| GB Standard and CE Marking Certification | SAMR and EU F-Gas Regulation compliance enables access to Chinese state grid and European renewable developer tenders. |
| Biomass Precursor Backward Integration | Coconut shell and rice husk pyrolysis capacity insulates against activated carbon industry feedstock competition. |
Research Approach
Desk research of customs trade data, SAMR certification filings, and EU F-Gas Regulation implementation guidance preceded structured interviews with grid storage procurement officers, sodium-ion cell engineering directors, hard carbon anode material suppliers, and renewable developer project finance leads. Primary fieldwork combined with secondary validation from EIA storage deployment databases, IEA stationary energy storage reports, and MIIT directive documentation. Bottom-up cell shipment tallies by format and application triangulated against top-down market sizing from gigafactory capacity announcements.
Assumptions held lithium carbonate price volatility within observed ranges and solid-state electrolyte commercialization timelines at laboratory-to-pilot stage across the analysis window. Segmentation modeling incorporated cell geometry, anode chemistry, cathode composition, end-use application, and regional regulatory framework dimensions. CAGRs derived from volume-weighted average of annual capacity additions and procurement pipeline conversion rates. Hard carbon precursor availability and sodium manganese oxide cathode standardization curves served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by diversified battery conglomerates or breakthrough solid-state electrolyte announcements from EU research consortia would shift outcomes. Macroeconomic commodity price spikes, accelerated EU F-Gas Regulation phase-down timelines, or technological deviation in cathode chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Dual Carbon Battery Market