
 South America Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
South America Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lithium-Ion Battery for Electric Vehicle Market Insights
Market Context
The direct procurement channel between cell manufacturers and Brazilian OEMs is narrowing as local assembly requirements tighten. BYD Company Ltd anchors its position through captive vertical integration from mineral refining through module assembly in Brazil. LG Energy Solution competes by leveraging its existing relationships with Korean automakers operating plants in the Mercosur zone. Contemporary Amperex Technology Co Limited sustains relevance through aggressive pricing on LFP cell volumes destined for São Paulo-based bus manufacturers.
Technical Definition and Segment Structure
The South America lithium-ion battery for electric vehicle constitutes rechargeable electrochemical energy storage systems employing lithium iron phosphate, nickel manganese cobalt, or nickel cobalt aluminum cathode chemistries paired with graphite or silicon-enhanced anodes, engineered to deliver cycle lives exceeding two thousand charge events under tropical thermal profiles. These systems power traction motors, regenerative braking architectures, and auxiliary loads across passenger cars, buses, and light commercial vehicles operating on the region's varied altitude and temperature gradients. Prismatic formats dominate Brazilian OEM contracts due to superior pack-level volumetric efficiency and thermal management integration, while LFP chemistry captures expanding share in price-sensitive fleet segments where energy density trade-offs yield lower total cost of ownership. The aftermarket segment remains structurally underdeveloped, creating margin concentration among integrators capable of remanufacturing retired bus packs for stationary storage applications in Chilean mining operations.
Regulatory Frame and Outlook
Brazil's ANFAVEA emission protocols and Rota 2030 local content thresholds, Chile's National Electromobility Strategy administered by the Ministry of Energy, and Argentina's lithium export valorization mandates under the Secretariat of Mining collectively reshape product certification, supply chain localization, and cathode precursor sourcing requirements across the Andean lithium triangle. ANVISA chemical substance notifications and INMETRO safety conformity assessments add compliance layers for imported cell assemblies entering Brazilian ports. Stakeholders must monitor evolving rules of origin under Mercosur-EU negotiations, as European battery passport requirements threaten to bifurcate certification standards for exporters versus domestic-market suppliers.
Market Dynamics
Brazil's Rota 2030 local content thresholds are forcing cell manufacturers to relocate module assembly lines to São Paulo state, compressing the direct import channel and privileging integrators with captive cathode precursor capacity.
Growth Catalysts
- Fleet electrification mandates:Chile's National Electromobility Strategy administered by the Ministry of Energy mandates progressive zero-emission targets for urban bus operators in Santiago and Valparaíso.
- Lithium valorization policy:Argentina's Secretariat of Mining export mandates require downstream processing of lithium carbonate within domestic territory before battery-grade material release.
- Tropical thermal engineering:Prismatic LFP cell architectures engineered for 45°C ambient operation are capturing procurement contracts from Brazilian bus manufacturers operating in Manaus and Fortaleza.
Market Restraints
- Cathode precursor concentration:NCM precursor refining capacity concentrates in Chinese industrial zones, exposing Brazilian pack assemblers to shipping cost volatility and currency mismatch.
- ANVISA chemical notification delays:Brazil's national health regulator requires 180-day review cycles for electrolyte salt imports, extending qualification timelines for new cell suppliers.
- Silicon anode degradation:Volume expansion failure modes in silicon-enhanced graphite blends limit cycle life guarantees below fleet operator requirements for 4,000-cycle bus applications.
Strategic Opportunities
- Andean stationary storage redeployment:Retired bus battery packs from Santiago operators are being remanufactured for Chilean mining site microgrids, creating circular revenue streams for integrators with disassembly capabilities.
- Light commercial vehicle electrification:Argentina's Mercosur-aligned freight operators in Córdoba and Rosario are piloting LFP-powered delivery vans for last-mile logistics corridors.
- Mercosur-EU rules of origin alignment:Battery passport traceability requirements under negotiation are creating first-mover advantage for cell assemblers with certified conflict-mineral documentation.
Industry Challenges
- Thermal management engineering scarcity:Pack-level liquid cooling design expertise remains concentrated among Korean and Chinese engineering teams, forcing Brazilian OEMs to outsource subsystem development.
- INMETRO certification backlog:Brazil's national metrology institute faces 14-month queue times for lithium-ion storage system safety assessments, delaying product launches for imported cell assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lithium-Ion Battery for Electric Vehicle Market |
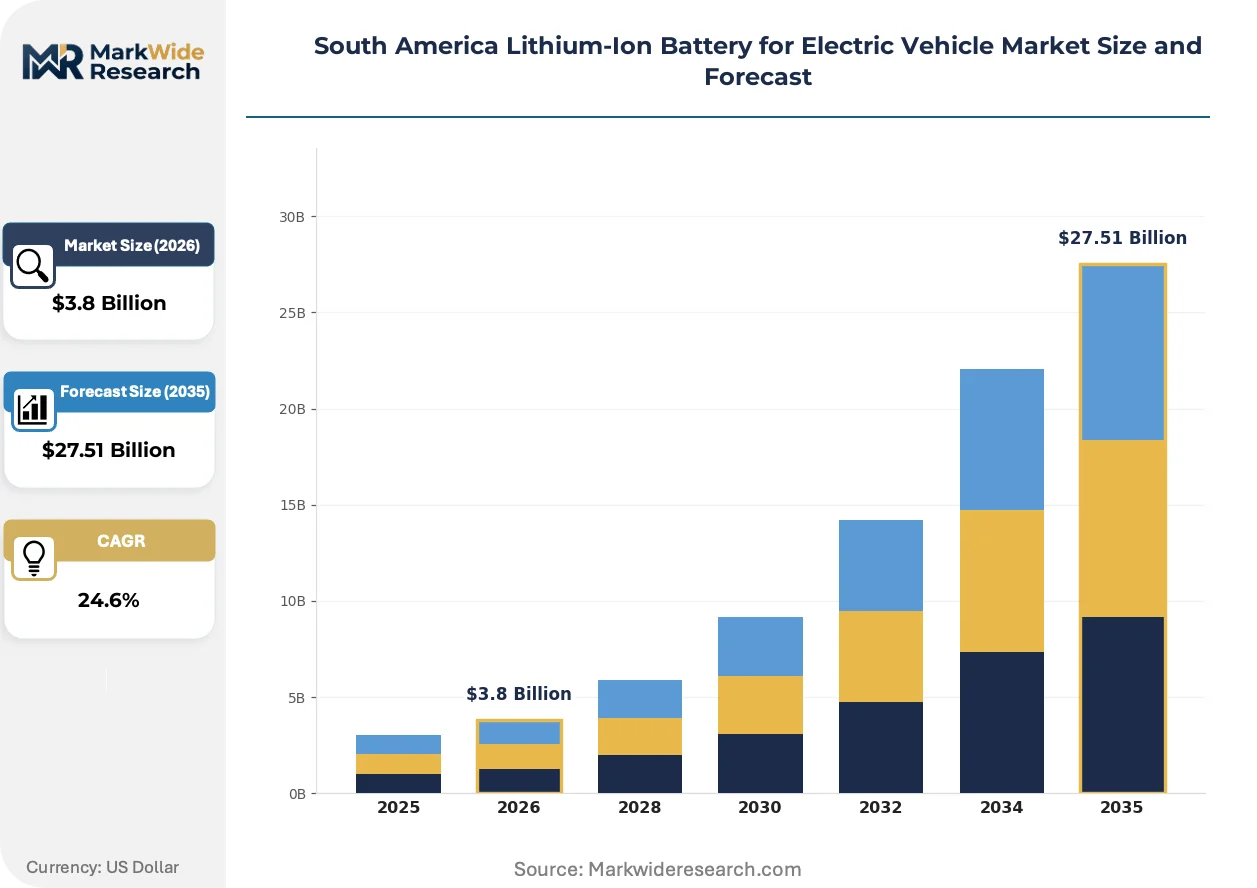
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Module Technology: LFP, NMC, NCA, LCO End User: OEMs, Fleet Operators, Aftermarket, Integrators Installation: Residential, Commercial, Industrial, Mobile |
| Companies Covered | BYD Company Ltd, Contemporary Amperex Technology Co Limited, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, EnerSys, SK Innovation, Toshiba Corporation, Northvolt, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Digital twin architectures and solid-state prototyping are compressing development cycles for South American battery applications, while procurement patterns favor integrators with remanufacturing capabilities.
Cell-to-pack architectures are virtualizing module-level assembly steps by eliminating traditional module housings and connecting cells directly to pack structures. Brazilian bus manufacturers in São Paulo state are adopting these designs to reduce weight and improve volumetric energy density. This topology is virtualizing the role of tier-two module suppliers, compressing margin capture toward cell manufacturers and pack integrators with thermal simulation capabilities.
ANVISA's updated chemical substance notification framework is expanding disclosure requirements for electrolyte additives and binder solvents entering Brazilian ports. The regulation forces cell importers to submit complete Bill of Materials documentation six months ahead of shipment clearance. NCM chemistry suppliers are responding by pre-qualifying alternative electrolyte formulations with reduced fluorinated salt content.
Fleet operators in Santiago and São Paulo are consolidating procurement through multi-year total-cost-of-ownership contracts rather than per-unit battery purchases. This model transfers degradation risk to integrators and demands guaranteed residual value for second-life applications. Chilean mining companies are the most aggressive adopters, requiring fifteen-year service agreements covering both traction and stationary storage duty cycles.
South America Lithium-Ion Battery for Electric Vehicle Market Segmentation
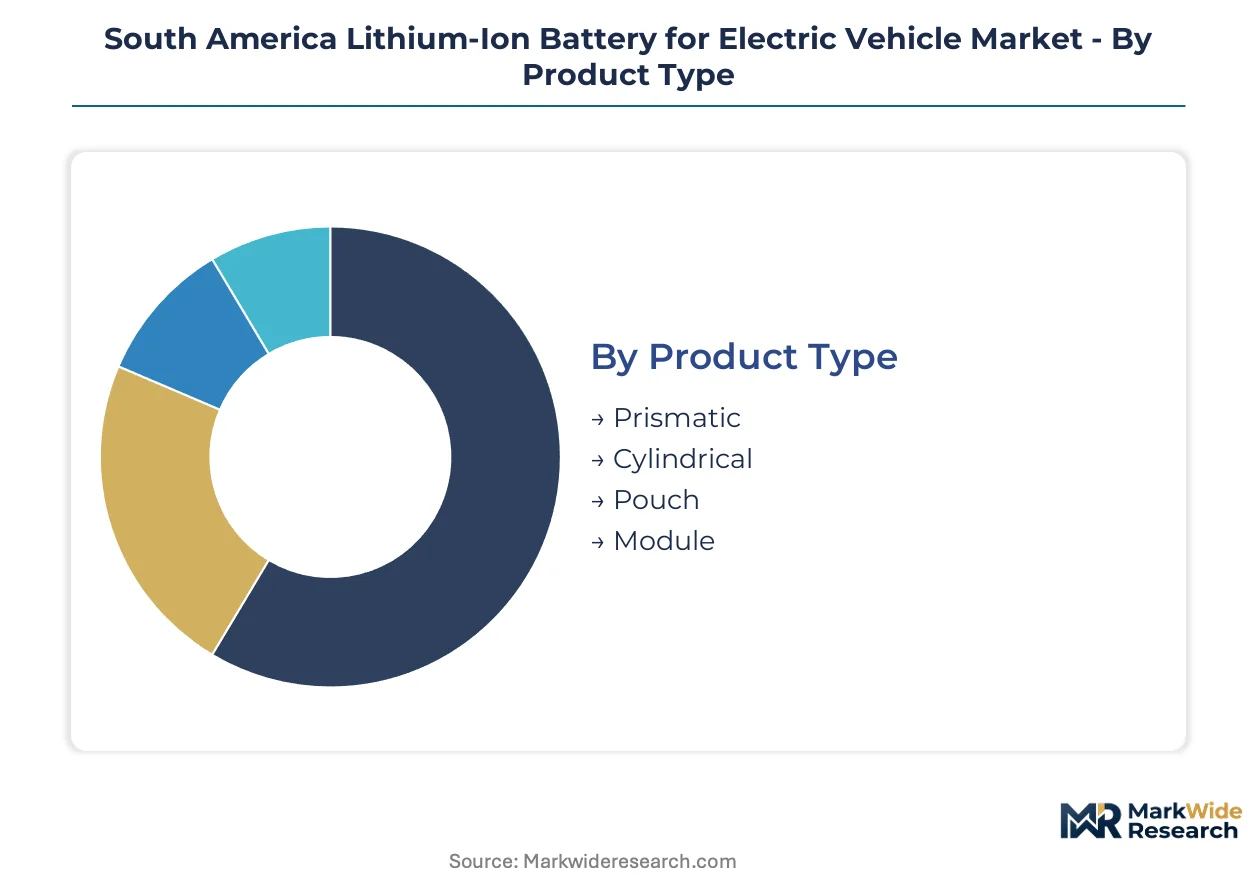
Cell format and chemistry selection in South America tracks directly to thermal stress profiles and local content compliance requirements. Brazilian bus manufacturers and Argentine fleet operators prioritize specifications that withstand tropical ambient conditions while satisfying Rota 2030 assembly mandates.
Product Type:
Use-case spectrum spans from volume-manufactured passenger car packs to custom-engineered bus installations requiring active thermal management.
- Prismatic:Rigid aluminum-encased cells deliver superior volumetric efficiency and simplified liquid cooling integration. São Paulo-based OEMs specify prismatic formats for electric bus contracts where pack-level space constraints and thermal stability under 45°C operation are non-negotiable.
- Cylindrical:Rolled electrode architectures with steel casing provide mechanical robustness and mature automation pathways. Chilean mining vehicle conversions favor cylindrical cells for vibration resistance in off-highway duty cycles across the Atacama.
- Pouch:Laminated polymer-encased designs maximize gravimetric energy density but require compression frames. Limited adoption in Brazilian applications due to swelling management complexity under high-humidity port conditions.
- Module:Pre-assembled cell groups with integrated battery management system circuitry. Cell-to-pack architectures are displacing discrete module procurement in São Paulo manufacturing corridors.
The dominant share belongs to Prismatic, while Cylindrical is closing the gap fastest in mining-adjacent applications.
Technology:
Cost tier stratification separates premium energy density chemistries from volume-positioned alternatives.
- LFP:Lithium iron phosphate cathodes trade energy density for cycle life and thermal safety. Brazilian fleet operators in Fortaleza and Manaus specify LFP for bus applications where 4,000-cycle guarantees outweigh gravimetric performance priorities.
- NMC:Nickel manganese cobalt layered oxides balance energy density and cost. Korean automakers operating Mercosur assembly plants source NMC cells for passenger electric vehicles targeting premium positioning.
- NCA:Nickel cobalt aluminum formulations deliver highest gravimetric energy density. Limited penetration in South America due to cobalt sourcing constraints and ANVISA notification complexity for high-nickel cathode precursors.
- LCO:Lithium cobalt oxide retains niche presence in hybrid auxiliary power units. Argentine light commercial retrofits occasionally specify LCO for compact 48V starter-generator applications.
LFP commands the installed base volume, with NMC expanding most quickly among passenger vehicle OEMs.
End User:
Customer type determines warranty structures, financing arrangements, and second-life obligation allocation.
- OEMs:Original equipment manufacturers integrate batteries at vehicle assembly. Brazilian automotive plants under Rota 2030 require localized module assembly, compressing direct import channels.
- Fleet Operators:Bus and commercial vehicle owners procuring direct from integrators. Santiago municipal operators negotiate fifteen-year total-cost-of-ownership contracts transferring degradation risk to suppliers.
- Aftermarket:Replacement and retrofit battery sales for existing vehicle populations. Structurally underdeveloped across South America due to limited electric vehicle parc and remanufacturing capability concentration.
- Integrators:Pack assemblers sourcing cells and managing subsystem integration. Chilean mining microgrid developers represent emerging demand for retired bus pack redeployment.
OEMs retain the dominant procurement volume, though Fleet Operators are gaining share fastest through consolidated tender structures.
Installation:
Application context dictates enclosure standards, grid interconnection requirements, and operational duty profiles.
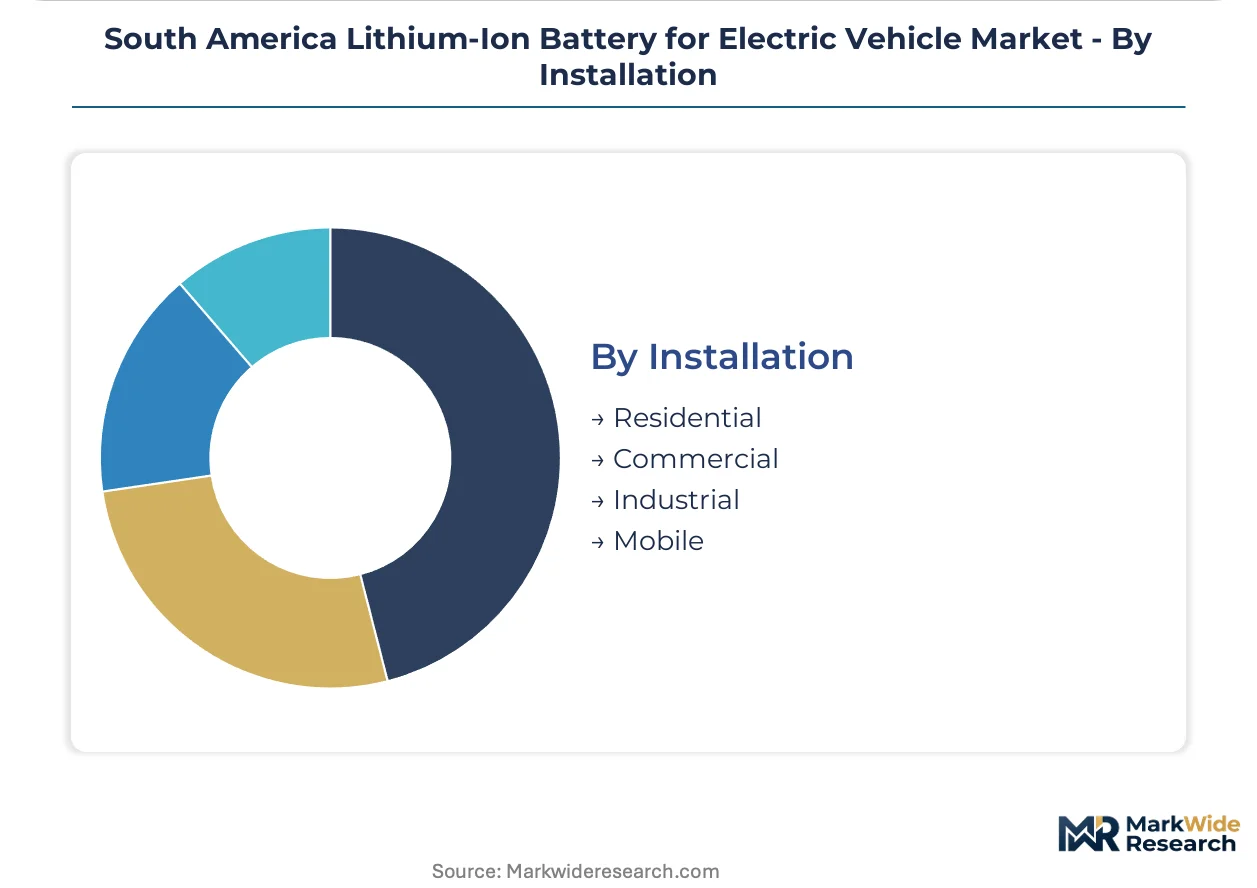
- Residential:Home-based charging infrastructure and stationary storage. Minimal segment presence given South America's low single-family garage penetration and multi-unit dwelling dominance.
- Commercial:Fleet depots, retail charging hubs, and corporate vehicle pools. Brazilian supermarket chains in São Paulo state pilot commercial charging for last-mile delivery electrification.
- Industrial:Mining site microgrids and manufacturing facility backup power. Chilean copper operations in Antofagasta redeploy retired Santiago bus batteries for peak shaving and diesel displacement.
- Mobile:Vehicle-integrated traction and auxiliary power systems. Encompasses all on-road electric bus, passenger car, and light commercial applications across Mercosur territory.
Mobile installations dominate by unit volume, while Industrial applications are climbing the fastest through second-life redeployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's lithium valorization mandates grant Buenos Aires asymmetric pricing leverage over Brazilian pack assemblers dependent on imported cathode precursors. Chilean mining operators extract further rent through second-life battery redeployment contracts.
Brazil
Fleet electrification tenders from São Paulo municipal operators and Rota 2030 local content thresholds drive procurement volumes. ANFAVEA emission protocols and INMETRO safety assessments reshape supplier qualification timelines. The southeastern manufacturing corridor anchored by São Paulo state concentrates module assembly investments from Korean and Chinese cell manufacturers.
Chile
National Electromobility Strategy mandates zero-emission targets for Santiago and Valparaíso urban bus fleets. Ministry of Energy administration creates standardized procurement frameworks for municipal operators. Antofagasta mining operations in the Atacama Desert redeploy retired Santiago bus batteries for peak shaving microgrids.
Argentina
Secretariat of Mining export mandates require domestic downstream processing of lithium carbonate before battery-grade material release. Córdoba and Rosario freight operators pilot LFP-powered delivery vans for last-mile logistics corridors. The Jujuy and Catamarca provinces anchor lithium brine extraction feeding regional cathode precursor supply.
Colombia
Medellín and Bogotá metropolitan transit authorities issue consolidated electric bus tenders with fifteen-year service agreements. National Ministry of Transport incentives accelerate depot charging infrastructure deployment. The Aburrá Valley industrial cluster attracts pack integrators serving Andean mining logistics applications.
South America Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Chinese vertical integrators and Korean cell specialists split the market through divergent localization strategies. The structure concentrates margin capture among three archetypes: mineral-to-module vertical integrators, chemistry-focused cell manufacturers, and thermal-engineering pack integrators. Competitive moves center on São Paulo module assembly relocation and captive cathode precursor sourcing from the Andean lithium triangle.
Within the vertical integrator tier, BYD Company Ltd exemplifies backward integration from lithium refining through module assembly. Contemporary Amperex Technology Co Limited occupies a position as a scale-driven LFP supplier aggressive on volume pricing. LG Energy Solution anchors the Korean specialist archetype leveraging existing Mercosur automaker relationships.
| Leading Market Players |
|---|
| BYD Company Ltd |
| Contemporary Amperex Technology Co Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| EnerSys |
| SK Innovation |
| Toshiba Corporation |
| Northvolt |
| Others |
Pricing and Supply Chain Analysis
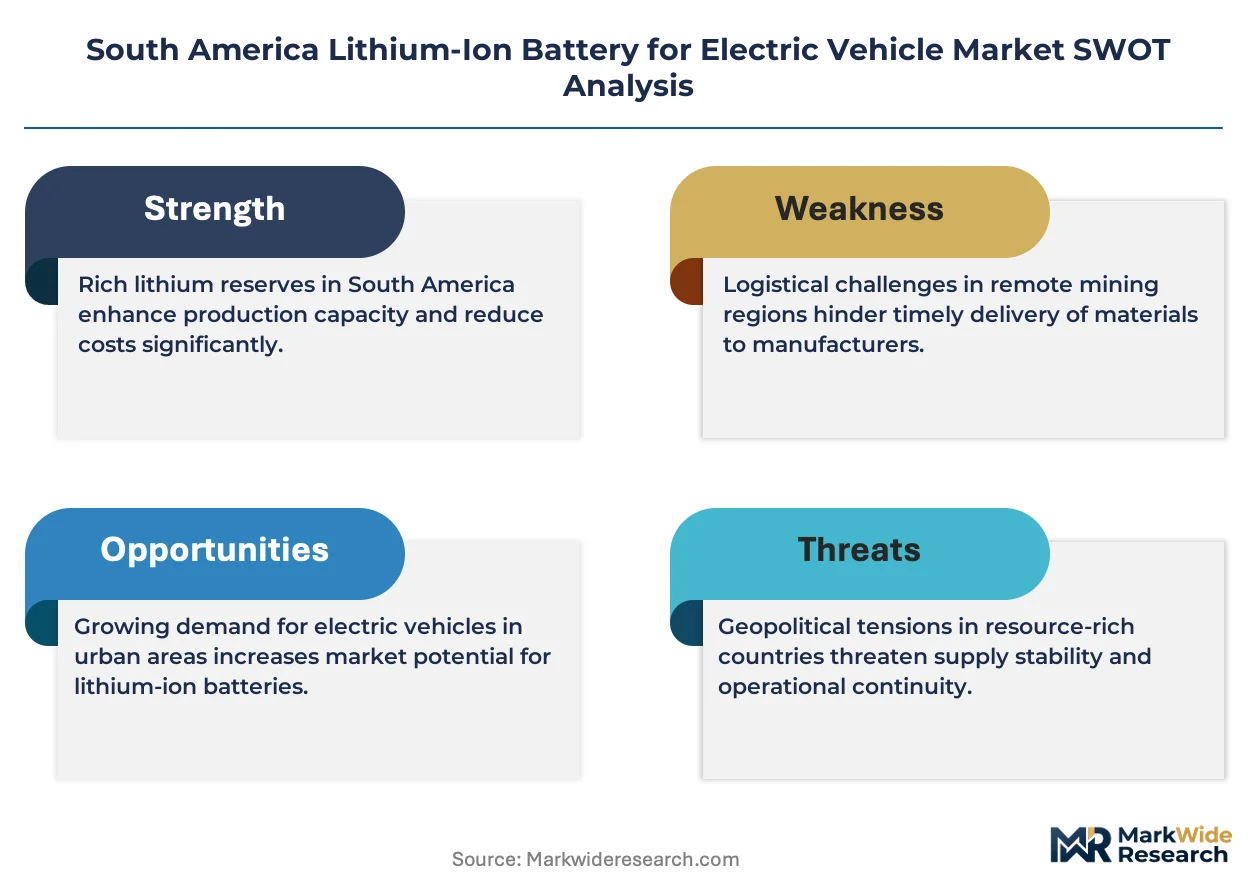
The Andean lithium triangle's cathode precursor capacity dynamics grant Argentine and Chilean feedstock suppliers asymmetric leverage over Brazilian pack assemblers, compressing margins for integrators lacking captive mineral access while inflating input costs for NCM-dependent contracts.
Pricing Analysis
Configured-to-order pricing for custom-engineered bus packs commands substantial premiums over standard LFP cell volumes, with differentiation driven by thermal management certification tier and volume scale commitments. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with fifteen-year service agreements from municipal operators on per-unit procurement. Cost compression in the standard tier is intensifying because Chinese LFP suppliers are flooding São Paulo manufacturing corridors with aggressive volume pricing. Fleet operators in Santiago demonstrate highest price sensitivity, while Chilean mining companies purchasing second-life redeployment contracts show lowest sensitivity due to diesel displacement economics.
Supply Chain Analysis
Upstream feedstock concentration in China's Jiangsu and Fujian provinces for NCM precursor refining, combined with South Korean cathode material processing, creates geographic dependency for Brazilian pack assemblers. Raw material flows hinge on lithium carbonate from Argentina's Jujuy province, cobalt hydroxide from the Democratic Republic of Congo, and electrolyte salts from Japanese chemical specialists. Single-source vulnerability in NCM precursor shipping routes through the Panama Canal exposes integrators to logistics chokepoint risk. Distribution runs through São Paulo-based module assembly facilities serving Rota 2030-compliant OEMs, with direct cell-to-pack channels displacing traditional tier-two module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where guaranteed residual value contracts and fifteen-year total-cost-of-ownership agreements are expanding faster than standalone hardware transactions, transferring degradation risk to integrators while locking in recurring revenue streams.
For Market Incumbents: Harden defensive positions by deepening backward integration into Andean lithium refining and securing INMETRO certification ahead of fourteen-month assessment queues. Captive cathode precursor capacity in Catamarca province defends margin position against Chinese LFP price aggression. Thermal management engineering talent retention represents the critical lever against Korean and Chinese engineering team concentration. For New Entrants and Emerging Players: Pursue white-space opportunities in Argentine light commercial vehicle retrofit markets around Córdoba and Rosario, where Mercosur-aligned freight operators are piloting LFP-powered delivery vans with minimal incumbent presence. Aftermarket remanufacturing for Chilean mining microgrids offers the most penetrable application, with disassembly capabilities as the specific go-to-market angle against integrators lacking circular revenue infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pack integrators with guaranteed residual value contracts spanning both traction and stationary storage duty cycles. Long-term viability across a five-to-ten-year window favors archetypes with certified conflict-mineral documentation aligned to emerging Mercosur-EU battery passport requirements. The specific signal to watch as inflection indicator is INMETRO queue clearance acceleration for cell assemblies entering Brazilian ports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Argentine Secretariat of Mining mandates force domestic downstream processing, creating captive feedstock access. |
| Cell-to-Pack Architecture Adoption | São Paulo bus manufacturers eliminate module housings, compressing margin capture toward thermal-simulation-capable integrators. |
| Second-Life Remanufacturing Capability Buildout | Antofagasta mining operations redeploy retired Santiago bus batteries, generating circular revenue streams. |
| ANVISA Pre-Qualification Investment | Brazil's chemical substance notification framework demands six-month advance documentation, privileging prepared suppliers. |
| Mercosur-EU Battery Passport Alignment | Traceability requirements under negotiation create first-mover advantage for certified conflict-mineral documentation holders. |
Research Methodology
Operator-level perspectives from fleet procurement directors, OEM platform engineers, thermal management specialists, and mining microgrid developers anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation against ANFAVEA production databases, INMETRO certification records, Chilean Ministry of Energy electromobility filings, and Argentine Secretariat of Mining export statistics. Bottom-up cell volume estimates triangulated against top-down OEM capacity announcements across the analysis window.
Scenario-bracketing framed the analytical approach, modeling demand trajectories across vehicle class, cathode chemistry, and regional production cluster dimensions. CAGRs derived from logistic diffusion curves fitted to fleet electrification mandate timelines and Rota 2030 local content threshold implementation. Industry-specific forecast inputs incorporated ANVISA notification cycle durations and INMETRO safety assessment queue lengths as supply-side constraints.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, lithium carbonate spot volatility, and Mercosur-EU negotiation outcomes would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and cathode chemistry substitution elasticities. Cross-checking against IEA electric vehicle deployment benchmarks and ANFAVEA monthly production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
UAV Lithium Battery Market