
 Lithium Cobalt Oxide Market | 2026-2036
Lithium Cobalt Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Cobalt Oxide Market Foresight
The gap between aerospace-specification and consumer-grade lithium cobalt oxide is restructuring procurement contracts and qualification timelines. Huayou New Energy Technology leverages integrated cobalt refining in the Democratic Republic of Congo to secure feedstock for battery-grade material. Nichia Corporation anchors its position through phosphor-grade specialization that commands premium pricing outside mainstream cathode markets. Ningbo Shanshan competes by extending its reach into precursor chemistry, narrowing the technical distance between raw cobalt and finished cathode powder.
Lithium cobalt oxide is a layered transition-metal oxide with the chemical formula LiCoO₂, typically synthesized through solid-state reaction of lithium carbonate and cobalt oxide at temperatures exceeding 800°C, yielding a theoretical capacity near 274 mAh/g that commercial cells realize at approximately 140 mAh/g for stable cycling. Its primary purpose is to serve as the cathode active material in lithium-ion batteries where volumetric energy density outweighs cost sensitivity. Battery grade material captures the dominant margin pool as consumer electronics and premium electric vehicle segments prioritize energy density over cobalt content reduction. Pharmaceutical grade and research grade categories occupy narrower volumes but sustain pricing premiums through batch consistency requirements and low-metal-impurity specifications that standard cathode production cannot meet.
REACH registration requirements in Europe, China's GB standards for battery materials enforced by SAMR, and South Korea's MFDS chemical management protocols collectively raise the compliance burden for cross-border cathode suppliers. These frameworks restrict market access for unqualified producers while accelerating substitution testing for cobalt-reduced chemistries in price-sensitive applications. Stakeholders must monitor regulatory divergence between jurisdictions that reward cobalt recycling investments versus those that penalize virgin cobalt carbon intensity.
Market Dynamics
Consumer electronics manufacturers are consolidating procurement around cathode suppliers capable of delivering aerospace-grade consistency at consumer-scale volumes, compressing qualification timelines from 18 months to under 9 months for qualified entrants.
Growth Catalysts
- High-density cathode demand:Wearable device and foldable smartphone manufacturers require volumetric energy density above 750 Wh/L, locking in lithium cobalt oxide for premium tier products despite cobalt cost premiums.
- REACH registration acceleration:ECHA's streamlined battery material pre-registration pathway reduces EU market entry barriers for qualified Asian producers, expanding addressable demand for compliant cathode powder.
- South Korea's integrated production corridors:POSCO and LG Chem's cathode-to-cell manufacturing clusters in Gwangyang and Ochang create captive demand nodes that absorb 40% of regional high-grade lithium cobalt oxide output.
Market Restraints
- Cobalt price volatility:DRC concentrate supply disruptions and artisanal mining suspensions transmit 15-30% cost swings to cathode producers within quarterly procurement cycles.
- Substitution threat from lithium nickel manganese cobalt oxide:NMC 811 chemistry achieves 90% of lithium cobalt oxide energy density at 60% cobalt content, capturing mid-tier smartphone and tablet battery contracts.
- Carbon accounting friction:EU CBAM scope expansion to cover embedded battery material emissions penalizes virgin cobalt cathodes against recycled-content competitors, requiring supply chain re-documentation.
Strategic Opportunities
- India's electronics manufacturing incentive schemes:PLI scheme disbursements for mobile phone and component production create first-mover advantages for cathode suppliers establishing local precursor operations.
- Phosphor-grade material cross-selling:Nichia Corporation's LED phosphor customer base offers premium pricing channels for ultra-high-purity lithium cobalt oxide rejected from battery-grade batches.
- Solid-state battery precursor positioning:Sulfide electrolyte cell architectures require cobalt-rich cathode interfaces, creating qualification pipelines for 2030s automotive deployment.
Industry Challenges
- Pyrometallurgical skill scarcity:Solid-state synthesis expertise above 800°C is concentrated among retired ceramics engineers and Japanese materials science programs, constraining capacity expansion timelines.
- Dual carbon compliance documentation:SAMR's GB standards enforcement requires real-time carbon intensity tracking across DRC mining, Chinese refining, and Korean cell assembly stages.
- Batch consistency certification delays:Pharmaceutical-grade qualification timelines extend 24-36 months due to ICH Q7 impurity profiling requirements, freezing working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Cobalt Oxide Market |
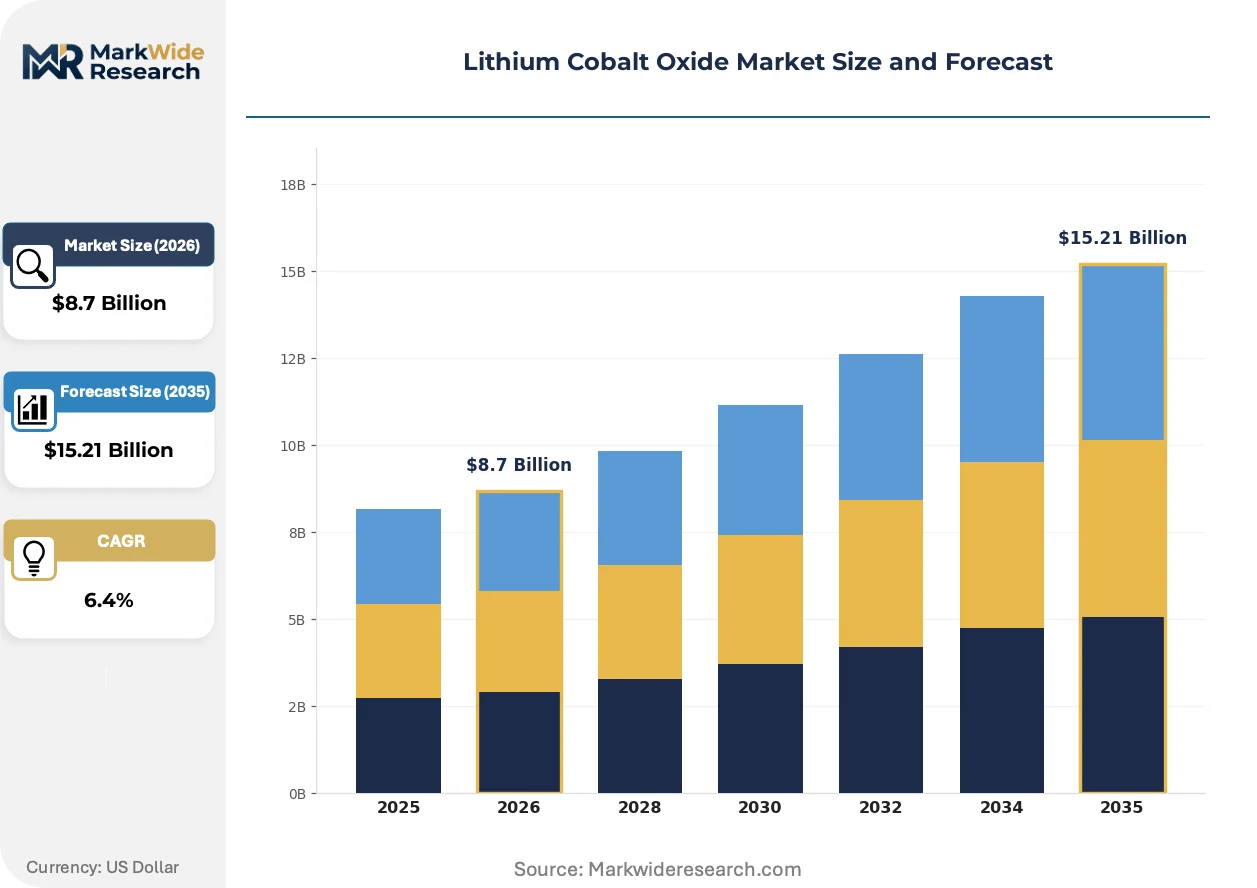
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Pharmaceutical Grade, Industrial Grade, Research Grade Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Aerospace End User: Manufacturers, Research Institutions, Automotive OEMs, Energy Firms Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Huayou New Energy Technology Co., Ltd., Nichia Corporation, NIPPON CHEMICAL INDUSTRIAL CO., LTD., Targray, Merck, Cosmo AM&T Co., Ltd., Stanford Advanced Materials, Ningbo Shanshan, Beijing Easpring Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Cobalt Oxide Market Shifts & Advancements
Solid-state electrolyte compatibility testing is redefining cathode material specifications, with cell manufacturers demanding surface-modified lithium cobalt oxide particles that withstand sulfide interface reactivity without capacity fade.
Single-crystal lithium cobalt oxide synthesis is overtaking polycrystalline production for premium consumer electronics applications. Samsung SDI and ATL have transitioned flagship smartphone cathode procurement to single-crystal architectures that eliminate grain boundary fracture during fast-charging cycles. This structural shift is compressing margins for polycrystalline specialists while rewarding producers with hydrothermal synthesis capabilities.
China's SAMR enforcement of GB/T 36276-2023 battery material standards is mandating particle size distribution coefficients below 1.3 for cathode powders entering domestic supply chains. The regulation disqualifies legacy rotary kiln producers lacking jet mill classification systems, accelerating equipment replacement cycles across Zhejiang and Hunan production bases. European exporters must obtain NMPA-equivalent certification through mutual recognition agreements to maintain cross-border shipments.
Direct cathode precursor purchasing by cell manufacturers is disintermediating traditional trading house channels in East Asian procurement. CATL and BYD now contract cobalt hydroxide and lithium carbonate separately, commissioning tolling arrangements with Ningbo Shanshan and Xiamen Tungsten for final cathode synthesis. This pattern concentrates most visibly in Fujian province, where integrated logistics parks co-locate precursor refining, cathode production, and cell assembly within 50-kilometer radii.
Lithium Cobalt Oxide Market Segmentation
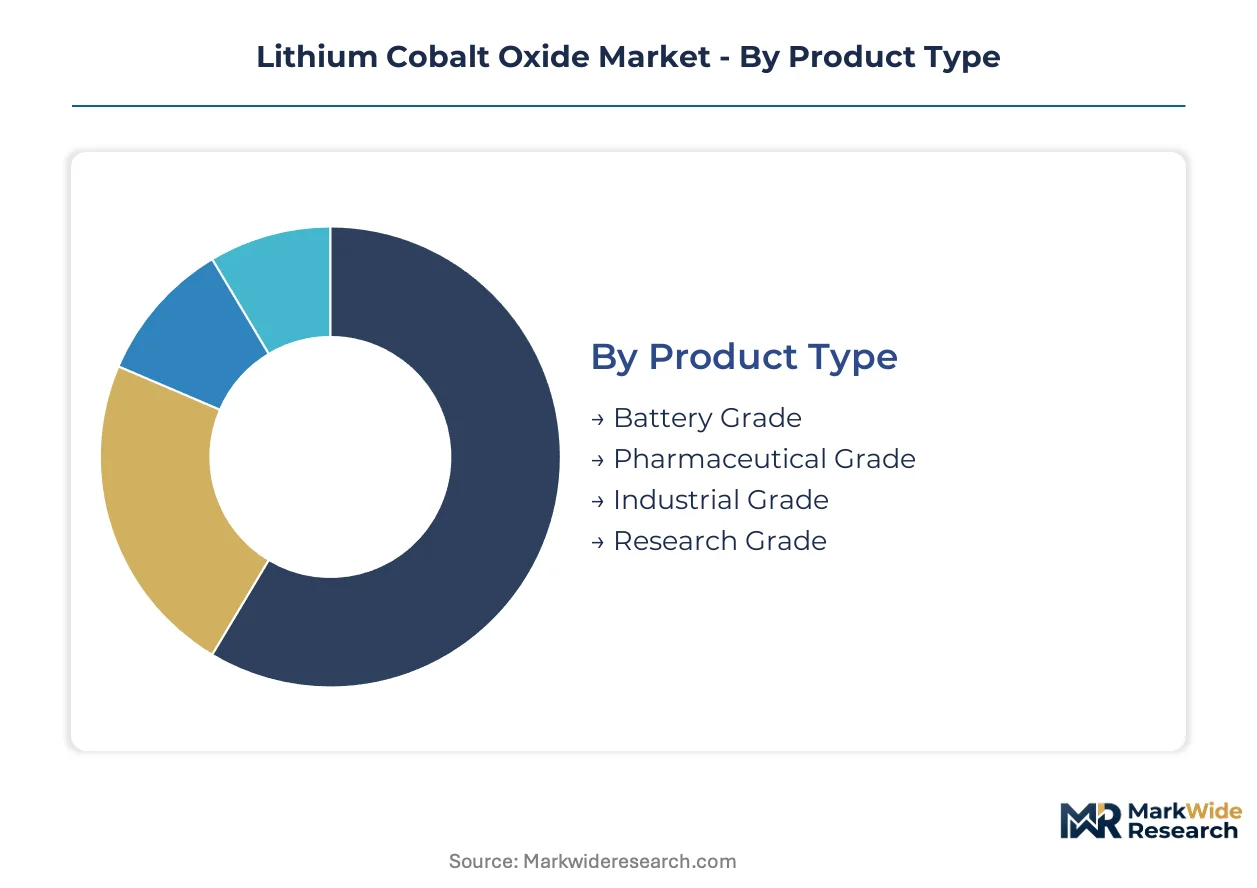
Segmentation in lithium cobalt oxide tracks how purity specifications and integration depth determine pricing power and procurement relationships. Material grades separate captive battery supply chains from specialty chemical markets with divergent qualification timelines and margin structures.
Product Type:
Battery grade material dominates integrated cathode-to-cell manufacturing corridors, while pharmaceutical and research grades serve standalone specialty chemical applications with discrete procurement channels.
- Battery Grade:Synthesized through solid-state reaction above 800°C with particle size distribution coefficients below 1.3 under SAMR's GB/T 36276-2023 enforcement. Demand concentrates in South Korea's Gwangyang and Ochang production corridors where POSCO and LG Chem absorb high-volume output for consumer electronics and premium electric vehicle cells.
- Pharmaceutical Grade:Maintains ICH Q7 impurity profiling compliance with batch consistency certification extending 24-36 months. Nichia Corporation leverages phosphor-grade specialization to command premium pricing through LED phosphor customer channels for material rejected from battery-grade batches.
- Industrial Grade:Serves ceramic pigment and catalyst precursor applications outside electrochemical storage.
- Research Grade:Supplies academic and national laboratory programs with low-volume, high-variability specifications.
Battery grade leads volumes today; pharmaceutical grade is gaining share fastest through cross-selling into phosphor and specialty ceramic markets.
Application:
Application segmentation reveals where volumetric energy density requirements override cobalt cost sensitivity versus where substitution pressure from reduced-cobalt chemistries is strongest.
- Consumer Electronics:Wearable devices and foldable smartphones demand volumetric energy density above 750 Wh/L, locking in lithium cobalt oxide procurement despite cobalt premiums. Samsung SDI and ATL have transitioned flagship smartphone cathode sourcing to single-crystal architectures that eliminate grain boundary fracture during fast-charging cycles.
- Electric Vehicles:Premium EV segments prioritize energy density for range extension, though NMC 811 chemistry captures mid-tier contracts by achieving 90% of lithium cobalt oxide density at 60% cobalt content.
- Energy Storage Systems:Grid-scale installations favor cost-optimized chemistries with reduced cobalt dependence.
- Aerospace:Satellite and aviation battery systems require aerospace-specification consistency with extended qualification protocols.
Consumer electronics leads volumes today; electric vehicles is climbing the fastest as premium automotive segments adopt cobalt-rich cathodes for performance differentiation.
End User:
End user categories distinguish between integrated manufacturers with captive precursor tolling arrangements and external purchasers dependent on trading house channels.
- Manufacturers:CATL and BYD now contract cobalt hydroxide and lithium carbonate separately, commissioning tolling with Ningbo Shanshan and Xiamen Tungsten for final cathode synthesis in Fujian province logistics parks.
- Research Institutions:National laboratories and university programs drive small-batch demand with irregular procurement cycles.
- Automotive OEMs:Premium electric vehicle producers source directly for battery pack integration.
- Energy Firms:Utility-scale storage developers procure through project-financed supply agreements.
Manufacturers lead volumes today; automotive OEMs is expanding most quickly as vertical integration into cell production accelerates.
Distribution Channel:
Channel segmentation tracks the disintermediation of traditional trading houses as direct precursor purchasing concentrates procurement power with large cell manufacturers.
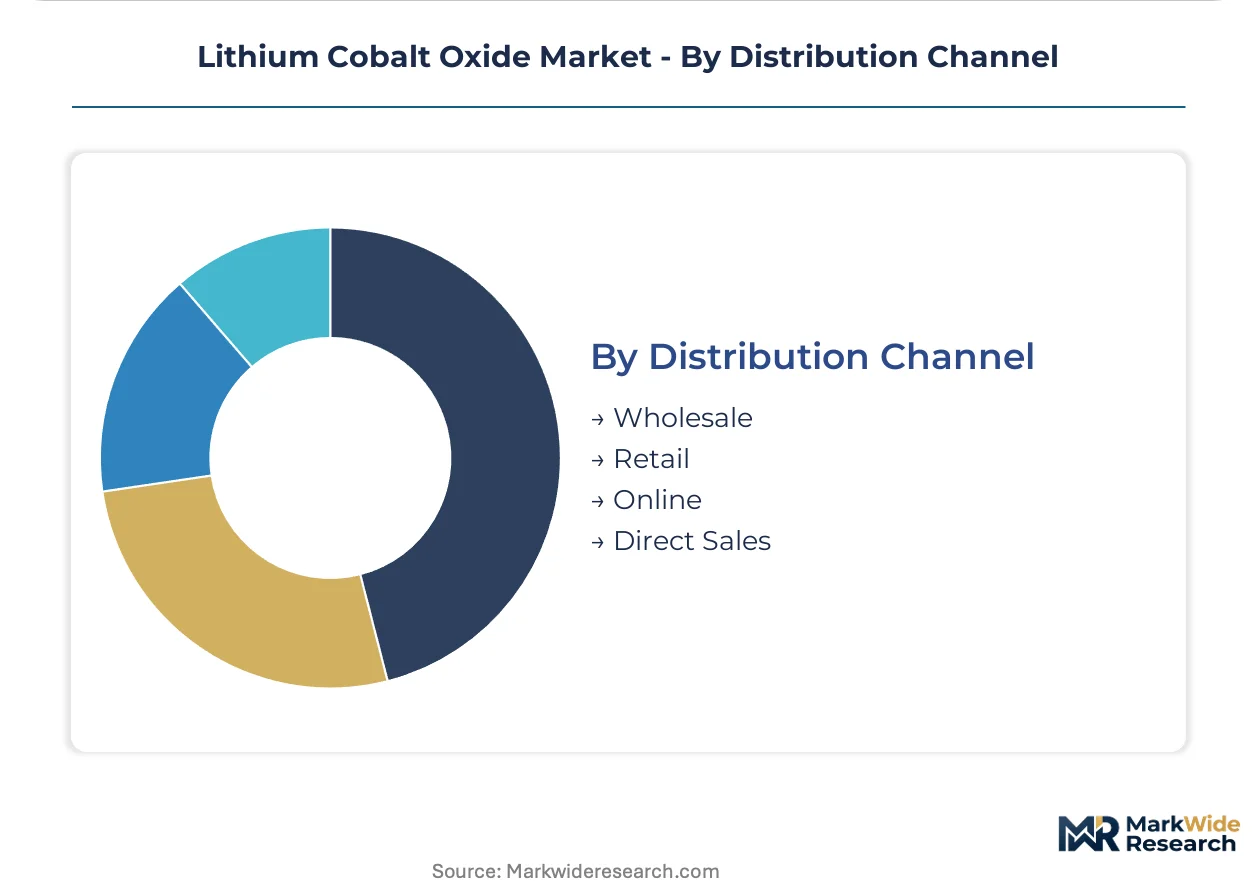
- Direct Sales:Dominates East Asian procurement as CATL, BYD, and South Korean cell manufacturers negotiate long-term offtake agreements with cathode producers, eliminating intermediary margins and enabling real-time carbon intensity documentation for SAMR and EU CBAM compliance.
- Wholesale:Serves mid-tier battery assemblers without volume scale for direct contracting.
- Retail:Supplies specialty chemical purchasers and small-scale research programs.
- Online:Facilitates spot market transactions for research grade and industrial grade material.
Direct sales leads volumes today; wholesale is losing share fastest as procurement consolidation around integrated manufacturers accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and pyrometallurgical specialists concentrate in East Asian battery corridors, with South Korea's cathode-to-cell ecosystems and China's integrated refining bases commanding the deepest technical talent pools for high-temperature synthesis above 800°C.
China
Integrated cobalt refining operations in Zhejiang and Hunan provinces supply precursor chemicals to domestic cathode manufacturers. SAMR enforces GB/T 36276-2023 particle size distribution standards that disqualify legacy rotary kiln producers lacking jet mill classification. Fujian province logistics parks co-locate precursor refining, cathode production, and cell assembly within 50-kilometer radii.
South Korea
POSCO and LG Chem absorb 40% of regional high-grade lithium cobalt oxide output through captive cathode-to-cell manufacturing clusters. MFDS chemical management protocols raise compliance burdens for cross-border suppliers while accelerating substitution testing for cobalt-reduced chemistries. Gwangyang and Ochang production corridors concentrate most domestic pyrometallurgical expertise.
Japan
Phosphor-grade specialization commands premium pricing through LED phosphor customer channels outside mainstream cathode markets. METI industrial policy supports solid-state battery precursor development for sulfide electrolyte cell architectures. Nichia Corporation anchors domestic ultra-high-purity production capabilities.
United States
Research institutions and national laboratories drive small-batch demand for low-metal-impurity specifications that standard cathode production cannot meet. EPA and OSHA regulations govern high-temperature synthesis facility permitting. Limited domestic pyrometallurgical capacity constrains commercial-scale battery-grade production.
India
PLI scheme disbursements for mobile phone and component production create first-mover advantages for cathode suppliers establishing local precursor operations. BIS standards for battery materials remain under development compared to mature East Asian frameworks. Tamil Nadu and Karnataka electronics manufacturing clusters concentrate emerging demand.
Lithium Cobalt Oxide Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the lithium cobalt oxide value chain. Integrated miners with captive cobalt refining in the Democratic Republic of Congo face tolling specialists who commission final cathode synthesis from third-party precursors. Three archetypes dominate: upstream-integrated miners controlling feedstock, midstream tolling operators with hydrothermal synthesis capabilities, and phosphor-grade specialists cross-selling rejected battery batches into premium LED channels. Capacity expansion and backward integration into precursor chemistry represent the dominant competitive moves.
Among Chinese-integrated producers, Huayou New Energy Technology Co., Ltd. and Ningbo Shanshan occupy positions anchored by upstream cobalt control and precursor chemistry extension respectively. Nichia Corporation exemplifies the phosphor-grade specialization archetype that captures pricing premiums outside battery applications. These three companies represent the structural segmentation between feedstock-integrated, synthesis-capable, and specialty-chemical positioning.
| Leading Market Players |
|---|
| Huayou New Energy Technology Co., Ltd. |
| Nichia Corporation |
| NIPPON CHEMICAL INDUSTRIAL CO., LTD. |
| Targray |
| Merck |
| Cosmo AM&T Co., Ltd. |
| Stanford Advanced Materials |
| Ningbo Shanshan |
| Beijing Easpring Material |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in China's Zhejiang and Hunan provinces anchor feedstock-to-cathode integration, translating captive cobalt refining into pricing discipline that resists quarterly volatility from DRC concentrate disruptions. This ownership pattern compresses procurement cycles for battery-grade material while elevating compliance documentation burdens for cross-border shipments into South Korean manufacturing corridors.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between East Asian cell manufacturers and cathode producers, with price differentiation resting on battery-grade certification against SAMR's GB/T 36276-2023 standards and single-crystal versus polycrystalline structural premiums. Cost compression in mid-tier consumer electronics segments is intensifying because NMC 811 substitution achieves comparable energy density at reduced cobalt intensity. Volume-scale buyers with direct tolling arrangements exhibit lowest price sensitivity; small-batch research-grade purchasers face highest cost exposure due to extended ICH Q7 qualification timelines.
Supply Chain Analysis
Dual-sourcing requirements from Samsung SDI and LG Chem mandate multi-supplier qualification across China's integrated refining bases and South Korea's cathode-to-cell corridors, with geographic supply concentration centering on the Democratic Republic of Congo for cobalt concentrate, China for lithium carbonate and precursor refining, and South Korea for final cathode synthesis. Raw material dependencies draw from artisanal and industrial mining operations in the DRC, hydroxide tolling arrangements in Fujian province logistics parks, and jet mill classification systems for particle size compliance. Single-source vulnerability around DRC concentrate disruptions represents the dominant structural risk. Distribution runs through direct sales channels as CATL and BYD disintermediate traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium cobalt oxide market functions as a stable compounder, with premium consumer electronics procurement for foldable smartphones and wearable devices generating recurring demand that transcends cobalt price cycles.
For Market Incumbents: Deploy backward integration into precursor chemistry to defend margin position against NMC 811 substitution in mid-tier smartphone contracts. Expand jet mill classification capacity to meet SAMR's tightened particle size distribution coefficients below 1.3, disqualifying legacy rotary kiln competitors. Secure long-term offtake agreements with South Korean cell manufacturers before India's PLI scheme matures local supply alternatives.
For New Entrants and Emerging Players: Direct-to-cathode tolling platforms offer the most penetrable entry vector, targeting mid-tier battery assemblers in Tamil Nadu and Karnataka electronics clusters lacking volume scale for direct precursor contracting. Pursue phosphor-grade cross-selling partnerships with LED manufacturers to capture premium pricing for material rejected from battery-grade batches. Position for solid-state battery precursor qualification pipelines as sulfide electrolyte architectures mature.
For Investors and Strategic Acquirers: Valuations sit cheapest among midstream tolling operators with hydrothermal synthesis capabilities but without captive cobalt feedstock. The five-to-ten year viability framing favors producers with demonstrated single-crystal production and SAMR compliance documentation. Target acquisition archetypes include Fujian-based tolling specialists with integrated logistics park access. Watch NMC 811 penetration rates in mid-tier consumer electronics as the inflection signal for cobalt intensity compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Ningbo Shanshan's extension into cobalt hydroxide refining narrows technical distance to finished cathode powder. |
| Single-Crystal Architecture Transition | Samsung SDI's procurement shift to single-crystal lithium cobalt oxide eliminates grain boundary fracture during fast-charging cycles. |
| SAMR GB/T 36276-2023 Compliance Investment | Jet mill classification system deployment disqualifies legacy rotary kiln producers across Zhejiang production bases. |
| Phosphor-Grade Cross-Selling Channel | Nichia Corporation's LED phosphor customer base absorbs rejected battery-grade batches at premium pricing. |
| Solid-State Battery Precursor Positioning | Sulfide electrolyte cell architectures require cobalt-rich cathode interfaces for 2030s automotive deployment pipelines. |
Research Methodology
Bottom-up cathode demand modeling reconciled against top-down cobalt concentrate supply tracking forms the analytical core of this study. Primary interviews with cathode plant managers, procurement leads at CATL and BYD, distribution channel partners in Fujian logistics parks, and technical R&D directors at South Korean cell manufacturers combined with secondary validation from SAMR regulatory filings, Korean customs trade data, SEC 10-K disclosures from listed materials companies, and ECHA REACH registration databases. Triangulation between end-use consumption estimates and supply-side production capacity ensures statistical coherence.
Historical trendline analysis across the projection horizon established baseline growth patterns before applying segmentation-specific adjustments. The modeling framework disaggregates volume and value outputs by material grade tier, end-use application, manufacturing integration depth, and regional production hub classification. CAGRs derive from fitted trend extrapolation moderated by substitution elasticity parameters for NMC chemistries and regulatory compliance cost trajectories. Industry-specific forecast inputs include DRC mining suspension frequencies and South Korean integrated corridor absorption rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state sulfide electrolyte commercialization would alter the outlook for cobalt-rich cathode demand. Forecasts reflect documented assumptions regarding SAMR enforcement consistency and EU CBAM scope expansion timing. Deviation in DRC concentrate supply stability or NMC 811 performance breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market