
 North America Consumer Battery Market | 2026-2036
North America Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Consumer Battery Market Analytics
Battery-as-a-service and subscription-based power management is hardening into a distinct revenue layer alongside hardware sales. Panasonic Corporation leverages its joint manufacturing footprint with Tesla to sustain captive demand for cylindrical cells. Duracell anchors the primary battery segment through dominant shelf presence across US retail channels. LG Energy Solution competes in the rechargeable tier by specializing in high-nickel chemistries for power tool OEMs.
The North America Consumer Battery comprises electrochemical cells designed for portable, non-industrial use, typically delivering 1.5V to 3.7V through alkaline manganese dioxide or lithium cobalt oxide chemistries, with energy densities ranging from 100 Wh/kg to 250 Wh/kg depending on cathode formulation. These devices store and discharge electrical energy through reversible or irreversible redox reactions to power cordless electronics, handheld tools, and personal mobility devices. Lithium-ion product types command the fastest expansion as nickel-cadmium formats face phase-out pressures from environmental directives. Smartphone applications concentrate the highest absolute volume, though wearable devices represent the steepest trajectory as miniaturization demands thinner form factors. Online retail channels are capturing share from supermarkets as direct-to-consumer battery subscriptions gain traction.
The US Environmental Protection Agency and California's Department of Toxic Substances Control enforce strict mercury and cadmium content limits that shape permissible chemistries and disposal pathways. Health Canada and the US Consumer Product Safety Commission coordinate recall protocols and thermal runaway reporting standards that manufacturers must satisfy for cross-border market access. Stakeholders must monitor how state-level right-to-repair legislation alters replacement battery accessibility and aftermarket revenue pools.
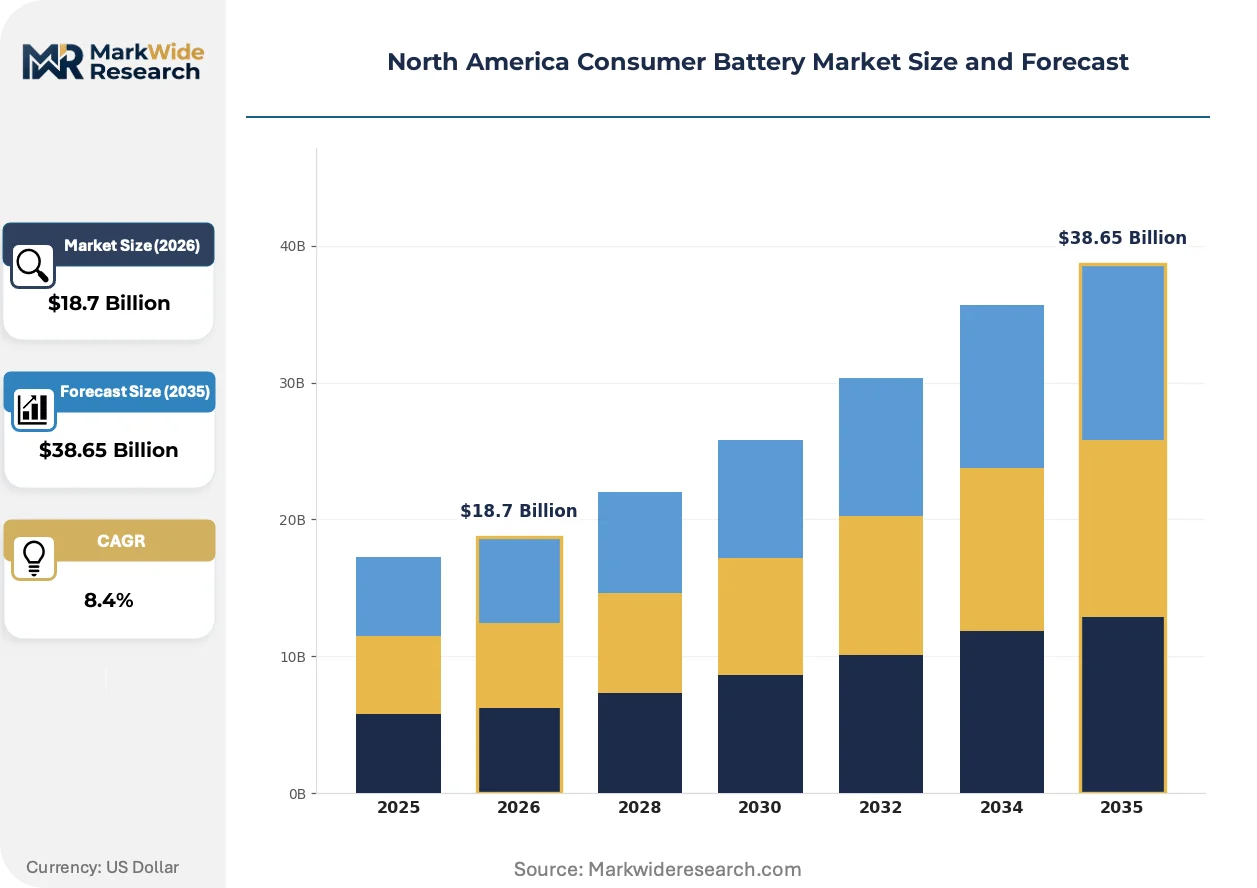
Market Dynamics
Domestic cell assembly capacity expansion under the US Inflation Reduction Act is restructuring supplier-buyer relationships across the North American consumer battery value chain. The policy-driven reshoring push is forcing manufacturers to reconfigure cathode sourcing and electrode coating operations within US and Canadian borders.
Growth Catalysts
- Wearable Electronics Density:Miniaturization demands from fitness trackers and medical patches in California's consumer electronics corridor are pulling ultra-thin lithium polymer cell volumes upward.
- IRA Production Tax Credits:The US Inflation Reduction Act's advanced manufacturing credit is incentivizing gigafactory investments in Michigan and Texas for cylindrical cell assembly.
- Power Tool Electrification:Cordless platform standardization by professional construction OEMs is compressing replacement cycles for high-discharge 18650 and 21700 formats.
Market Restraints
- Cobalt and Lithium Price Volatility:Cathode active material costs fluctuate with Democratic Republic of Congo mining output and Chilean brine extraction constraints.
- Single-Source Separator Supply:Polyolefin microporous membrane production concentrates among Japanese and South Korean chemical conglomerates, creating chokepoint vulnerability.
- California DTSC Chemistry Limits:The state's Department of Toxic Substances Control restricts mercury and cadmium content below federal EPA thresholds, forcing dual-formulation inventory management.
Strategic Opportunities
- Battery-as-a-Service Subscriptions:Direct-to-consumer recurring revenue models for smart home device power management are bypassing traditional retail markup structures.
- Ontario Manufacturing Zone:Canada's emerging battery cell assembly hub near Windsor is attracting electrode coating and electrolyte filling investments to serve US Midwest OEM demand.
- Right-to-Repair Legislation:State-level mandates in New York and Minnesota are opening aftermarket replacement battery access for consumer electronics previously sealed by manufacturers.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:The specialized chemist and process engineer pool for non-flammable additive development remains shallow across US and Canadian universities.
- UN 38.3 Certification Timelines:Lithium-ion air transport safety testing protocols create 8-12 month delays for new cell geometries targeting drone and mobility applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Consumer Battery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Lithium-ion, Nickel-Cadmium, Zinc-carbon Application: Smartphones, Laptops, Wearable Devices, Power Tools End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Tesla, Panasonic Corporation, LG Energy Solution, Samsung SDI, Duracell, CATL, BYD, SK On, Northvolt, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Consumer Battery Market Evolving Landscape
Solid-state electrolyte development and silicon-anode integration are compressing the performance gap between consumer and automotive cell architectures. These material shifts are enabling thinner form factors while raising energy density ceilings for portable electronics.
Solid-state battery prototyping is unifying the previously separate development tracks of consumer electronics and electric vehicle cell architectures. Samsung SDI and QuantumScape pilot lines are supplying automotive-grade ceramic electrolyte samples to smartphone OEMs for validation. This convergence is compressing R&D timelines and forcing shared tooling investments across previously siloed application teams.
The US Environmental Protection Agency's proposed expanded hazardous waste classification for lithium-ion batteries is tightening disposal and recycling infrastructure requirements. The rule would mandate cradle-to-grave tracking for cells above 100 watt-hours, elevating reverse logistics costs for power tool and e-mobility categories. Manufacturers are responding by pre-funding recycler partnerships in Texas and Arizona to secure certified processing capacity.
Direct-to-consumer subscription models are displacing supermarket and big-box retail as the primary acquisition channel for smart home battery systems. Amazon and specialized IoT vendors are bundling cell replacement with device warranties, capturing lifetime value previously fragmented across retail intermediaries. This shift concentrates most visibly in California and New York metro areas where smart thermostat and security camera penetration rates lead national averages.
North America Consumer Battery Market Segmentation
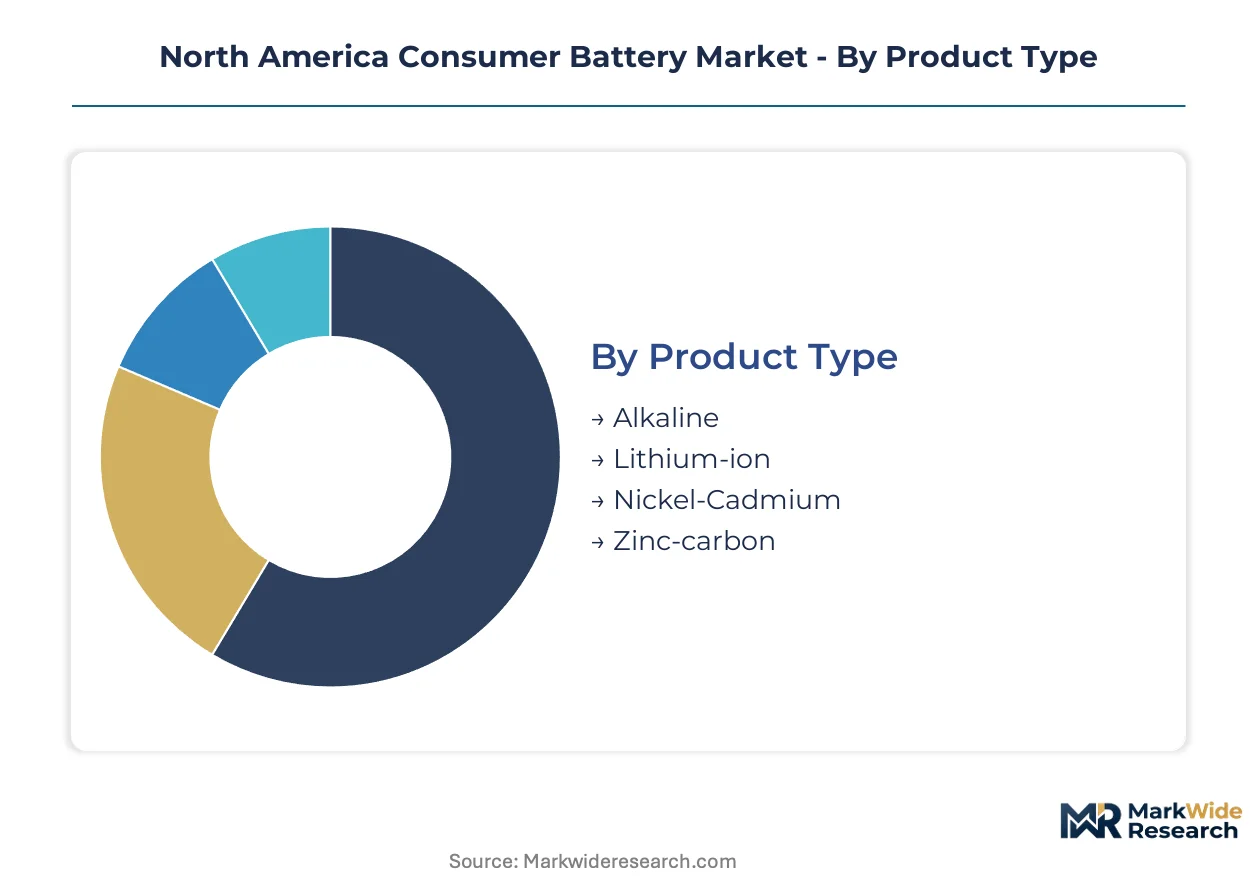
Consumer battery purchasing decisions in North America hinge on discharge profile requirements, replacement cycle economics, and regulatory compliance across state and provincial jurisdictions. Segmentation reveals how chemistry selection, device integration depth, and channel access create distinct profit pools for manufacturers and distributors.
Product Type:
Buyers prioritize energy density against unit cost when selecting cell chemistry for specific device categories.
- Lithium-ion:Reversible intercalation chemistry delivers 150-250 Wh/kg energy density through layered oxide cathodes. Demand concentrates in California's consumer electronics corridor where wearable miniaturization requires ultra-thin polymer pouch formats. The US Inflation Reduction Act's production tax credits are accelerating domestic cylindrical cell assembly in Michigan and Texas.
- Alkaline:Manganese dioxide cathode with zinc anode provides 1.5V nominal output at sub-dollar unit economics for single-use applications. Shelf-stable inventory dominates US retail mass merchandising channels from Duracell and Energizer portfolios. Replacement cycles remain tied to seasonal toy and flashlight demand spikes.
- Nickel-Cadmium:Rechargeable format with memory effect limitations faces phase-out pressure from EPA and California DTSC cadmium content restrictions. Legacy power tool platforms in industrial maintenance settings sustain residual demand.
- Zinc-carbon:Lowest-cost primary chemistry with 85 Wh/kg density serves price-sensitive emergency lighting and remote control applications. Mexican maquiladora assembly supports North American supply.
Alkaline leads on scale; lithium-ion leads on momentum.
Application:
Device integration depth determines whether batteries ship as captive sealed units or accessible replacement SKUs.
- Wearable Devices:Fitness trackers and medical patches in Ontario's emerging manufacturing zone pull sub-2mm lithium polymer cell volumes. Form factor constraints force custom cell geometries with shortened certification timelines.
- Smartphones:Sealed lithium-ion pouch cells dominate absolute volume with replacement demand suppressed by manufacturer adhesive bonding and warranty restrictions. Right-to-repair legislation in New York and Minnesota is gradually reopening aftermarket access.
- Power Tools:Cordless platform standardization by professional construction OEMs drives 18650 and 21700 cylindrical format demand. Battery-as-a-service subscriptions from Milwaukee and DeWalt compress replacement cycles.
- Laptops:18650 cell packs face thinning demand as tablet and smartphone substitution accelerates. Enterprise refresh cycles sustain commercial procurement volumes.
Smartphones lead on scale; wearable devices lead on momentum.
End User:
Procurement sophistication separates institutional buyers from household replacement purchasing.
- Residential:Household consumers purchase alkaline AA/AAA multipacks through supermarkets and online retail. Smart home device proliferation is expanding lithium-ion demand for thermostats, security cameras, and robotic vacuums.
- Commercial:Facility managers source bulk replacement cells through industrial distributors. Corporate sustainability mandates are driving preference for certified recycling take-back programs.
- Industrial:Maintenance departments specify high-discharge rechargeable formats for portable instrumentation. UN 38.3 certification requirements delay new supplier qualification.
- Automotive:Aftermarket key fob and tire pressure sensor batteries represent marginal volume. OEM integration of larger traction batteries sits outside consumer battery scope.
Residential leads on scale; commercial leads on momentum.
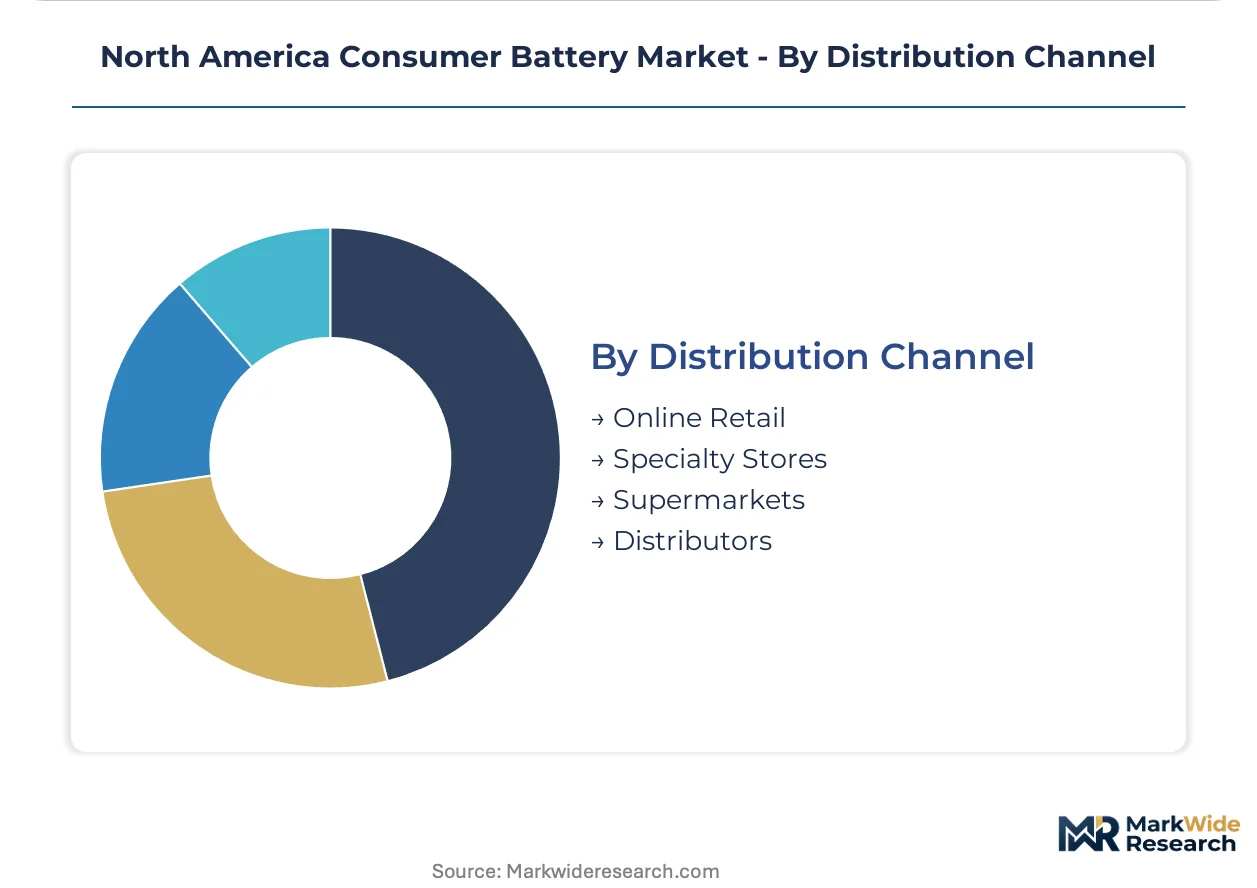
Distribution Channel:
Channel selection determines margin capture and customer lifetime value potential.
- Online Retail:Amazon and direct-to-consumer platforms bypass traditional retail markups. Subscription bundling with smart home warranties concentrates in California and New York metro areas.
- Supermarkets:Mass merchandising anchors alkaline volume through impulse placement at checkout. Shelf space consolidation favors Duracell and Energizer duopoly positions.
- Specialty Stores:Electronics retailers serve enthusiast demand for high-drain lithium primary cells in photography and drone applications. Staff expertise drives upsell to premium chemistries.
- Distributors:Industrial supply houses manage commercial and institutional procurement with volume pricing tiers. Technical support services differentiate from transactional retail.
Supermarkets lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more consumer battery demand than Canada, though Ontario's manufacturing investments are narrowing the production gap. Mexico's maquiladora sector supplies zinc-carbon cells at the lowest cost tier across the three-nation trade bloc.
United States
California's consumer electronics corridor drives lithium polymer demand for fitness trackers and medical patches. The EPA enforces mercury and cadmium content limits that shape permissible chemistries nationwide. Michigan and Texas host expanding cylindrical cell assembly capacity under IRA production tax credits.
Canada
Ontario's emerging battery manufacturing zone near Windsor attracts electrode coating investments to serve US Midwest OEM demand. Health Canada coordinates recall protocols with the US Consumer Product Safety Commission for cross-border market access. Toronto-Waterloo corridor startups prototype solid-state electrolyte formulations for wearables.
Mexico
Maquiladora assembly plants in Baja California and Chihuahua supply zinc-carbon cells for price-sensitive remote control and emergency lighting applications. The country's national environmental regulator enforces hazardous waste tracking for imported lithium-ion cells. Guadalajara's electronics cluster supports alkaline battery packaging for US retail channels.
North America Consumer Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf dominance concentrating among legacy alkaline marketers while rechargeable volumes flow through OEM captive arrangements. The structure tiers into three archetypes: chemistry specialists controlling cathode formulations, platform-integrated suppliers serving single OEM ecosystems, and diversified industrials spanning primary and secondary cell categories. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure electrode coating and electrolyte filling capacity within trade-advantaged jurisdictions.
Among Japan-based corporations, Panasonic Corporation exemplifies the platform-integrated archetype through its joint manufacturing footprint with electric vehicle OEMs. LG Energy Solution anchors the South Korean specialist tier with high-nickel chemistry focus. Duracell occupies the branded mass-market position through dominant US retail channel presence.
| Leading Market Players |
|---|
| Tesla |
| Panasonic Corporation |
| LG Energy Solution |
| Samsung SDI |
| Duracell |
| CATL |
| BYD |
| SK On |
| Northvolt |
| Others |
Value Network & Pricing Analysis
California DTSC cadmium content mandates and New York right-to-repair legislation are forcing manufacturers to maintain dual-formulation inventories and accessible replacement designs, compressing margins on standardized product lines while opening premium tiers for compliant specialty cells.
Pricing Analysis
Capacity additions in Michigan and Texas under IRA production tax credits are reshaping price floors for cylindrical lithium-ion formats. Three-tier pricing structure across premium certified, standard retail, and economy private-label levels stratifies the market, with UL certification and domestic assembly commanding measurable premiums. Cost compression in alkaline commodity tiers intensifies as Mexican maquiladora output expands. Residential household buyers exhibit highest price sensitivity through supermarket multipack purchasing, while industrial procurement through authorized distributors shows lowest sensitivity due to UN 38.3 certification requirements and warranty bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from power tool and consumer electronics manufacturers, bypassing traditional distributor markups. Cathode active material supply concentrates in China, South Korea, and Japan, with North American cell assembly operations drawing from Asian precursor shipments. Polyolefin separator membranes, electrolyte salts, and cobalt hydroxide represent critical input dependencies. Single-source vulnerability in microporous membrane production creates chokepoint exposure for North American gigafactory ramp schedules. Distribution runs through a hybrid structure combining Amazon direct-to-consumer platforms, industrial supply houses for commercial accounts, and mass retail for alkaline replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-anode integration and solid-state electrolyte maturation are enabling premium-tier product shifts that expand margin pools beyond commodity cell economics, while IRA domestic content bonuses reduce effective production costs for qualified manufacturers.
For Market Incumbents: Anticipate cobalt price volatility and Korean-Japanese separator supply concentration by securing backward integration into electrode coating capacity in Ontario and Michigan. Prioritize UL certification investments for premium-tier positioning as California DTSC restrictions tighten. Channel control through battery-as-a-service subscription platforms defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Enter via Ontario's emerging manufacturing zone to capture IRA-advantaged supply to US Midwest power tool OEMs. Target wearable device lithium polymer segments where custom form factor demands and shortened certification timelines disadvantage scaled incumbents. Pursue solid-state electrolyte partnerships with Toronto-Waterloo corridor research programs as a technical differentiation anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with electrode coating and electrolyte filling specialists possessing qualified North American capacity positions. Five-to-ten year viability hinges on domestic supply chain qualification under evolving EPA hazardous waste tracking rules. Monitor UN 38.3 certification backlog durations as an inflection signal for new entrant timing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Gigafactory Capacity Buildout | IRA production tax credits in Michigan and Texas reshape supplier-buyer contract structures. |
| Backward Integration into Cathode Precursor | Ontario electrode coating investments reduce exposure to Asian chemical conglomerate pricing. |
| Solid-State Electrolyte Partnership | Samsung SDI and QuantumScape pilot lines accelerate consumer-automotive R&D convergence. |
| Battery-as-a-Service Platform Launch | Amazon and IoT vendors bundle cell replacement with smart home warranties in California. |
| Certified Recycling Pre-Funding | Texas and Arizona recycler partnerships secure capacity under EPA expanded hazardous waste rules. |
Research Methodology
Multiple input streams — primary interviews with cell manufacturing executives, cathode procurement leads at power tool OEMs, and specialty retail category buyers, alongside secondary validation through EPA regulatory filings, USITC trade data, and IRA implementation guidance — were reconciled through bottom-up shipment analysis and top-down demand modeling. Industry stakeholders including solid-state R&D directors, UN 38.3 certification specialists, and industrial distributor operations heads contributed qualitative assessments of technical and commercial constraints.
Historical capacity utilization and pricing patterns were cross-referenced against expert panel inputs regarding IRA incentive capture timelines and cobalt market dynamics. Segmentation dimensions modeled across the projection horizon include chemistry format, device integration depth, and channel access tier, with CAGRs derived from install-base replacement cycle analysis and electrification penetration assumptions. Specific forecast inputs incorporated wearable device miniaturization trajectories and right-to-repair legislative propagation patterns.
Inputs from regulatory agency guidance documents and OEM procurement disclosures were available through the study window; gaps in proprietary cell cost structures and exact IRA qualification thresholds introduce uncertainty bands around margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Power Tool Batteries Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Seawater Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Romania Rechargeable Battery Market
Batteries
Electric Battery Market
Batteries
Iron Flow Battery Market
Batteries
Micro Battery Market
Batteries
East Europe Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Global Industrial Battery Market
Batteries
Forklift Battery Market
Batteries
Home Inverter Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Rear Rack Battery Market
Batteries
Aluminum Wire Battery Market