
 Germany Electric Vehicle Battery Electrolyte Market | 2026-2036
Germany Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Electrolyte Market Insights
The German automotive supplier channel is fragmenting as battery electrolyte procurement shifts from centralized chemical distributors toward direct OEM-contractor relationships. BASF SE leverages its Ludwigshafen integrated production complex to sustain captive supply advantages for lithium-ion cell producers. Evonik Industries AG specializes in high-purity additive formulations that differentiate its portfolio for next-generation solid-state programs.
Germany electric vehicle battery electrolyte encompasses the ion-conducting medium—typically lithium hexafluorophosphate dissolved in carbonate solvents like ethylene carbonate and dimethyl carbonate—that enables lithium-ion transport between anode and cathode during charge and discharge cycles. Liquid electrolytes currently dominate installed capacity due to mature manufacturing economics, though solid electrolytes represent the fastest-growing chemistry as German OEMs prioritize energy density targets above 400 Wh per kilogram. Battery chemistry segmentation shows lithium-ion formats anchoring near-term revenue pools while sodium-ion variants attract research funding from Stuttgart-based energy storage providers seeking mineral supply security.
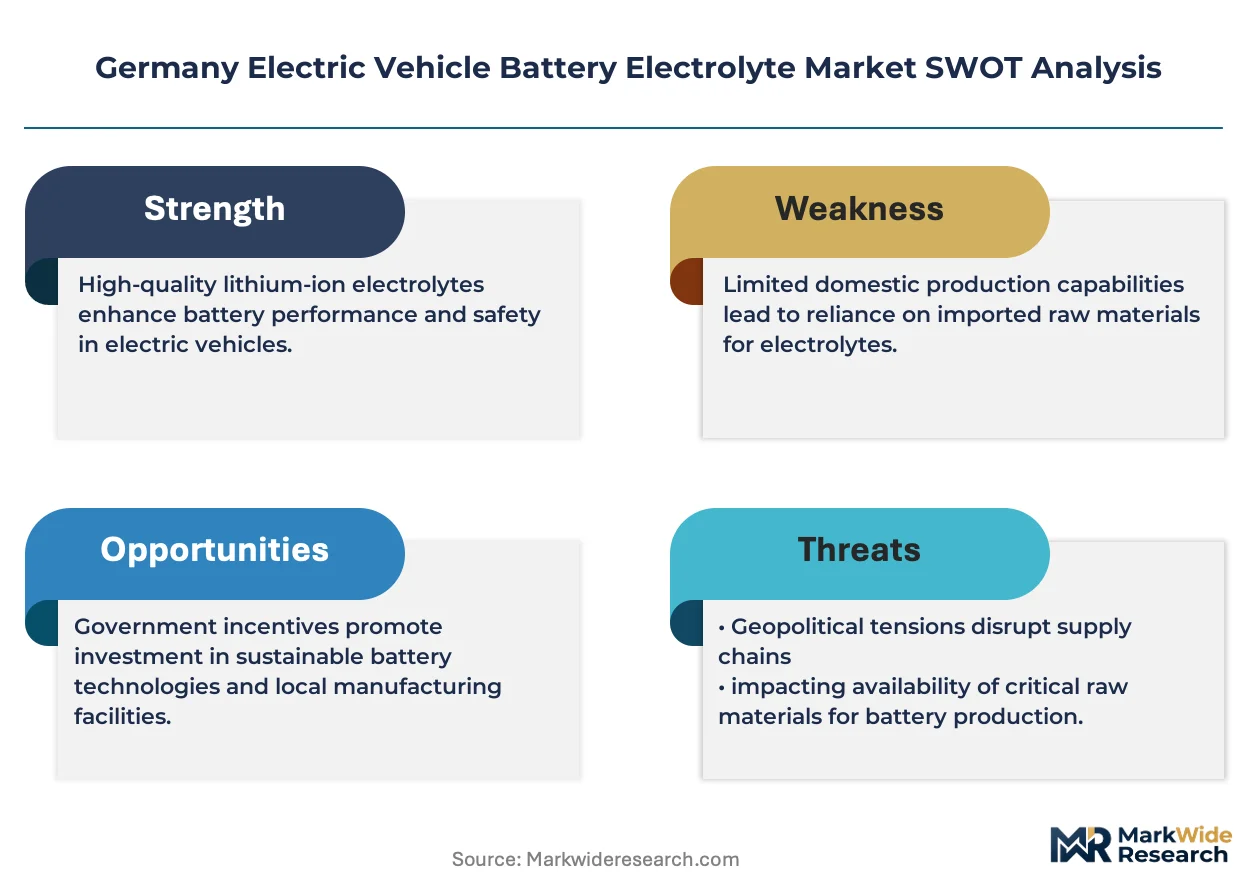
KBA type-approval requirements and EU Battery Regulation recycling mandates are tightening purity standards for electrolyte salt content and fluorinated additive disclosure. The EU Green Deal's carbon border adjustments and Germany's national circular economy framework for batteries are reshaping how producers document supply chain emissions across raw material extraction through cell assembly. Stakeholders must monitor how delegated acts under the EU Battery Regulation define recycled content thresholds for electrolyte components.
Market Dynamics
The EU Battery Regulation's recycled content mandates are forcing electrolyte producers to reconfigure salt recovery loops and carbonate solvent purification systems ahead of delegated act deadlines.
Growth Catalysts
- EU Green Deal carbon border adjustments:German OEMs now prioritize domestic electrolyte sourcing to avoid embedded emissions tariffs on imported cells. This accelerates captive production investments in Ludwigshafen and Schwarzheide.
- Solid-state battery roadmaps:Stuttgart-based manufacturers are scaling pilot lines for sulfide and oxide electrolyte formats. These programs demand high-purity additive portfolios that command technical premiums.
- Baden-Württemberg automotive cluster concentration:Proximity between Mercedes-Benz, Porsche, and Bosch cell assembly plants enables just-in-time electrolyte delivery. Logistics costs compress versus distant supply bases.
Market Restraints
- Lithium hexafluorophosphate supply concentration:Over 70% of global salt capacity sits in Chinese integrated producers. German formulators face input cost volatility and currency exposure on long-haul procurement.
- Fluorinated additive disclosure requirements:ECHA's PFAS restriction proposals threaten perfluorinated wetting agents used in high-voltage cells. Reformulation timelines compress against certification deadlines.
- Technical limitation in solid-state interface stability:Ceramic electrolyte formats suffer from dendrite penetration at sub-zero temperatures. This defers full electric vehicle deployment in Nordic export markets.
Strategic Opportunities
- Sodium-ion battery research funding:Stuttgart energy storage providers are piloting hard carbon anode systems with non-lithium salts. These programs seek mineral supply security outside cobalt and nickel value chains.
- Direct OEM-contractor relationships:Procurement patterns are bypassing centralized chemical distributors. Electrolyte blenders now negotiate multi-year offtake agreements with Volkswagen Group and BMW.
- German circular economy framework incentives:Federal funding streams support solvent recovery and salt regeneration infrastructure. Black mass processing investments in Saxony-Anhalt create feedstock arbitrage opportunities.
Industry Challenges
- Electrolyte formulation chemist scarcity:German technical universities produce insufficient specialists in ionic liquid and polymer gel systems. BASF and Evonik compete for the same talent pool.
- KBA type-approval timeline compression:New cell chemistries require 18-24 month validation cycles. Electrolyte variants must lock specifications early, limiting formulation flexibility.
- Legacy lead-acid recycling infrastructure retrofit:Existing smelters lack hydrometallurgical capability for lithium salt recovery. Capital requirements for conversion strain mid-tier processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Electrolyte Market |
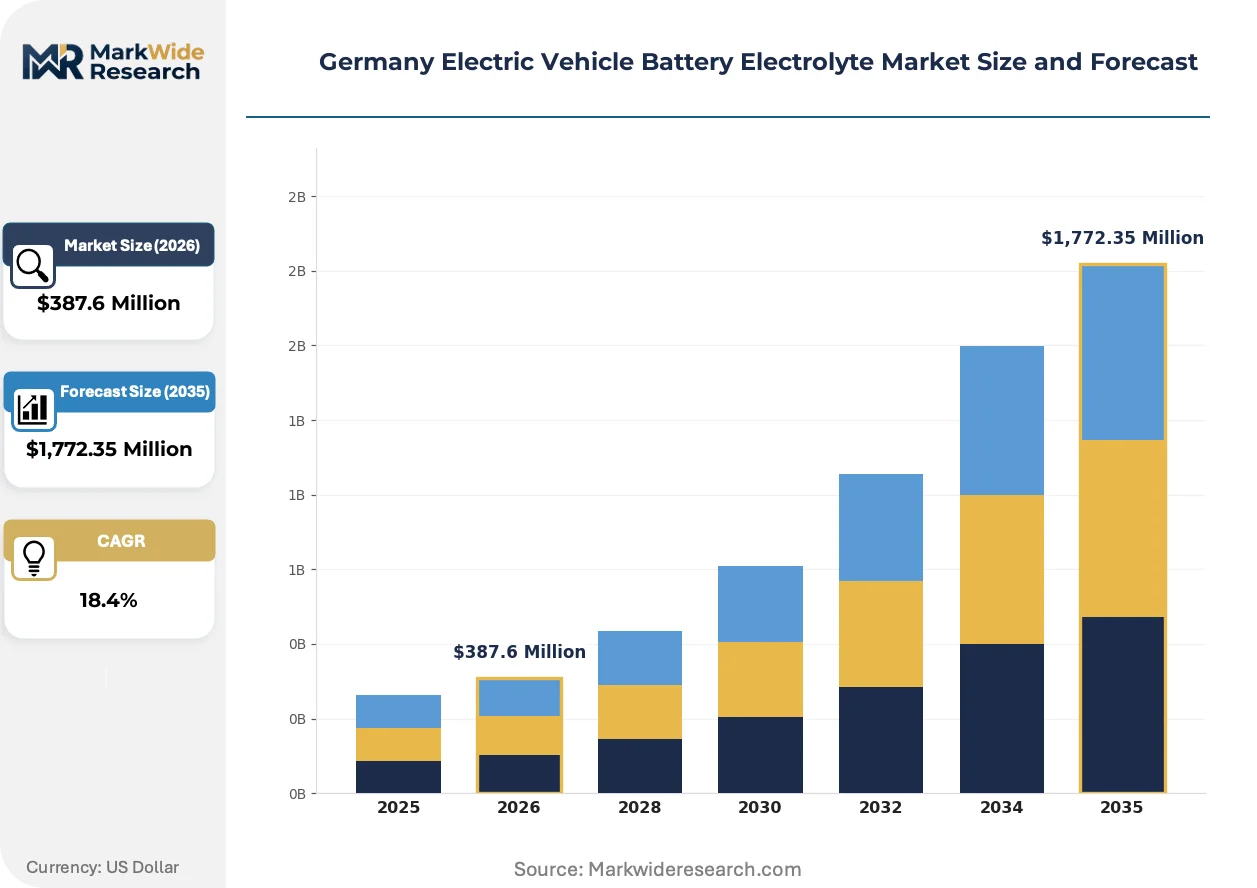
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolytes, Solid Electrolytes, Gel Electrolytes, Polymer Electrolytes Battery Chemistry: Lithium-ion, Sodium-ion, Nickel Metal Hydride, Lithium Polymer End User: Automobile Manufacturers, Battery Manufacturers, Research Institutes, Energy Storage Providers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Mitsubishi Chemical Group, BASF SE, Evonik Industries AG, Solvay SA, UBE Industries Ltd, Umicore SA, 3M Co., Arkema SA, Capchem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Electrolyte Market Trends and Innovations
Digital process control systems are penetrating electrolyte blending operations, enabling real-time impurity detection that compresses batch rejection rates and accelerates qualification timelines for cell producers.
Artificial intelligence-driven quality assurance is digitizing impurity profiling in carbonate solvent distillation. German specialty chemical plants deploy machine vision and spectroscopic sensors to flag ppm-level deviations before final blending. This compresses rework costs and accelerates customer qualification timelines for next-generation cell formats.
REACH authorization requirements for cyclic carbonate solvents are tightening supply chain documentation burdens. Formulators must now trace ethylene carbonate and dimethyl carbonate through multiple synthesis steps to demonstrate compliance. Small blenders without integrated back-integration face exclusion from premium automotive supplier lists.
Cell producers are consolidating electrolyte procurement around single-source technical partnerships. This displaces the traditional multi-vendor qualification model where three to five blenders competed per plant. The shift concentrates volume with integrated producers capable of co-locating blending facilities adjacent to gigafactory sites in Lower Saxony and Thuringia.
Germany Electric Vehicle Battery Electrolyte Market Segmentation
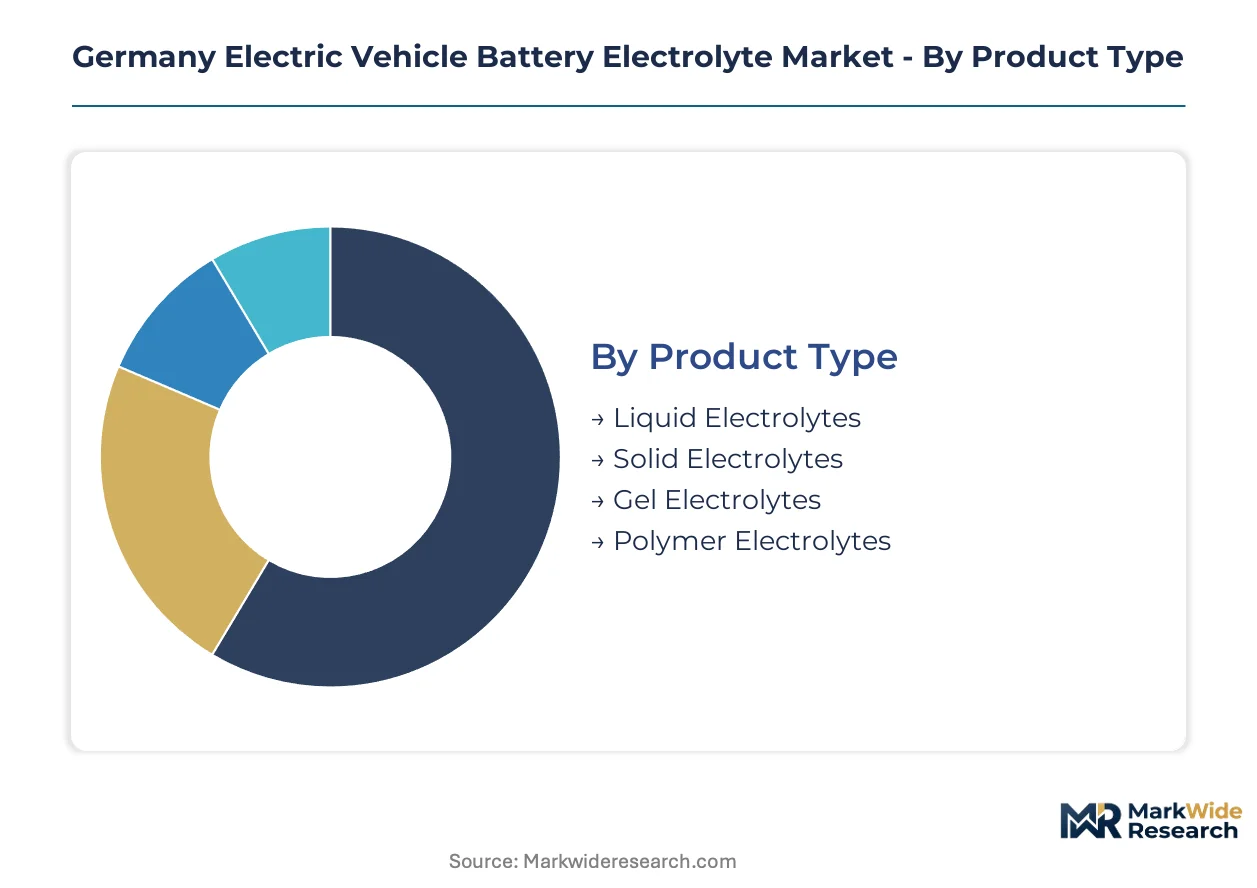
German electrolyte procurement patterns diverge sharply across cell formats and end-use specifications. Each segment carries distinct purity requirements, logistics constraints, and qualification timelines that shape supplier selection.
Product Type:
Formulation chemistry spans liquid, solid, gel, and polymer systems, each commanding different manufacturing infrastructure and OEM validation pathways.
- Liquid Electrolytes:Lithium hexafluorophosphate salt dissolved in ethylene carbonate and dimethyl carbonate solvents dominates current production volumes. Stuttgart-based cell assembly plants source these formulations from Ludwigshafen chemical complexes to minimize carbon border adjustment exposure.
- Solid Electrolytes:Sulfide and oxide ceramic formats enable energy density targets above 400 Wh per kilogram. Mercedes-Benz and Porsche pilot lines in Baden-Württemberg are scaling sulfide electrolyte procurement for next-generation cell architectures.
- Gel Electrolytes:Polymer matrices with trapped liquid phases occupy niche applications in flexible cell designs. Research funding from Stuttgart energy storage providers supports pilot production.
- Polymer Electrolytes:Dry ion-conducting polymers eliminate flammability risks in high-temperature automotive environments. Technical limitations in room-temperature conductivity constrain near-term deployment.
Established volume favors liquid formulations; emerging adoption favors solid-state chemistry.
Battery Chemistry:
Active material systems determine salt selection, solvent compatibility, and additive portfolios across the German supplier base.
- Lithium-ion:NMC and LFP cathode configurations anchor procurement volumes from Volkswagen Group and BMW cell plants. KBA type-approval requirements mandate strict purity documentation for these formulations.
- Sodium-ion:Hard carbon anode systems with sodium salts attract federal research funding seeking mineral supply security outside cobalt and nickel chains. Stuttgart-based energy storage providers are piloting non-lithium formats.
- Nickel Metal Hydride:Aqueous potassium hydroxide electrolytes persist in hybrid electric vehicle auxiliary systems. Toyota Motor Europe maintains limited procurement from legacy German chemical distributors.
- Lithium Polymer:Pouch cell formats with gelled electrolyte matrices serve premium passenger vehicle segments requiring packaging flexibility. Porsche Taycan battery packs utilize these configurations.
Revenue concentration sits with lithium-ion; steepest expansion trajectory belongs to sodium-ion research programs.
End User:
Customer categories span integrated OEM cell plants, independent battery manufacturers, research institutions, and grid storage developers with divergent technical specifications.
- Automobile Manufacturers:Volkswagen Group, BMW, and Mercedes-Benz operate captive cell assembly in Lower Saxony and Thuringia. These facilities negotiate direct electrolyte offtake agreements bypassing traditional chemical distributors.
- Battery Manufacturers:Independent cell producers including Northvolt and CATL German subsidiaries purchase formulated electrolytes under multi-year supply contracts. BASF SE leverages Ludwigshafen integration to serve this channel.
- Research Institutes:Fraunhofer and Max Planck centers pilot next-generation ionic liquid and solid-state formulations. Federal funding streams support pre-commercial electrolyte development.
- Energy Storage Providers:Grid-scale battery developers in Baden-Württemberg source sodium-ion electrolytes for stationary applications. Mineral supply security drives procurement diversification away from lithium dependence.
Procurement volume concentrates with automobile manufacturers; formulation innovation originates in research institutes.
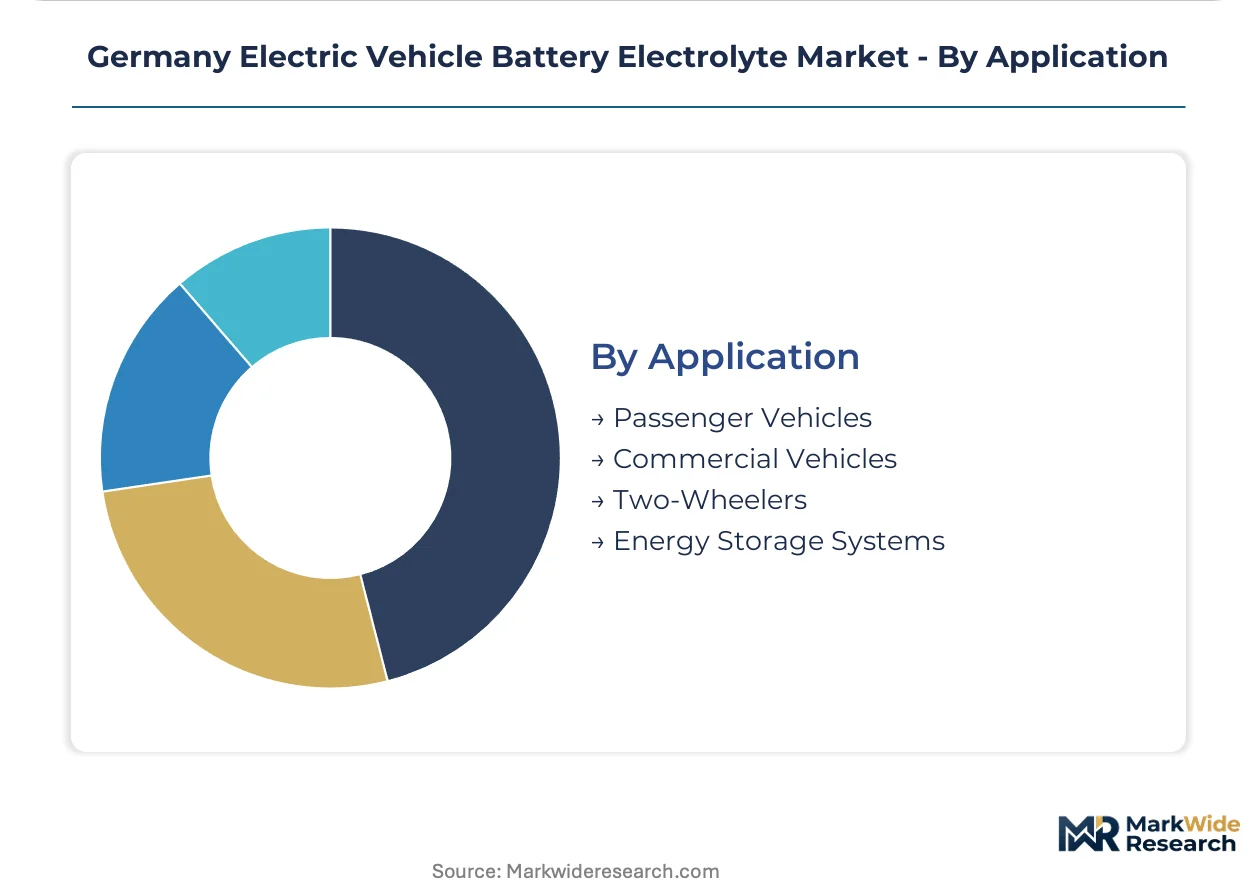
Application:
End-use segments impose distinct thermal management, cycle life, and safety certification requirements on electrolyte specifications.
- Passenger Vehicles:Premium electric sedans and SUVs from Stuttgart manufacturers demand high-voltage additive packages enabling fast-charging protocols. EU Battery Regulation recycling mandates tighten purity standards for this segment.
- Commercial Vehicles:Heavy-duty truck and bus batteries require extended cycle life under continuous load profiles. Fleet operators in Bavaria prioritize electrolyte thermal stability for depot charging infrastructure.
- Two-Wheelers:Electric motorcycle and scooter batteries utilize lower-cost carbonate solvent blends. These applications tolerate higher impurity thresholds than automotive grades.
- Energy Storage Systems:Grid-scale installations prioritize cost optimization over energy density. Sodium-ion electrolyte research targets this application for mineral supply security.
Passenger vehicles command premium formulation margins; energy storage systems drive cost-down pressure on standard electrolyte grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Baden-Württemberg exceeds that in peripheral German states by double-digit margins, reflecting cluster density and just-in-time logistics advantages. Stuttgart-based OEMs extract supplier concessions unavailable to distant competitors. This asymmetry shapes electrolyte procurement geography across the federal republic.
Baden-Württemberg
Mercedes-Benz and Porsche operate captive cell pilot lines demanding sulfide electrolyte formats for solid-state programs. KBA type-approval requirements mandate 18-24 month validation cycles that lock suppliers into early specification commitments. The Stuttgart automotive cluster concentrates BASF and Evonik technical service teams adjacent to OEM engineering centers.
North Rhine-Westphalia
Ford Cologne and legacy chemical infrastructure around Leverkusen sustain mid-volume liquid electrolyte demand for hybrid vehicle programs. REACH authorization documentation for cyclic carbonate solvents burdens formulators without integrated back-integration. The Cologne-Düsseldorf corridor hosts distributor networks serving independent battery assemblers.
Lower Saxony
Volkswagen Group's Salzgitter cell factory anchors the largest single-site electrolyte procurement commitment in Germany. EU Battery Regulation recycled content mandates are forcing salt recovery loop investments ahead of delegated act deadlines. The Wolfsburg-Brunswick industrial zone attracts blending facility co-location from integrated producers.
Bavaria
BMW's Munich engineering headquarters and Dingolfing assembly plant drive high-voltage additive demand for premium electric sedan fast-charging protocols. ECHA's PFAS restriction proposals threaten perfluorinated wetting agents used in BMW's cell specifications. The Munich-Stuttgart corridor enables technical collaboration between OEM formulators and Fraunhofer research institutes.
Thuringia
CATL's Erfurt subsidiary and emerging cell producers source standard-grade carbonate blends under multi-year supply contracts. Germany's national circular economy framework directs federal funding toward solvent recovery infrastructure in former industrial zones. The Erfurt-Jena corridor leverages academic partnerships with Friedrich Schiller University for next-generation ionic liquid development.
Germany Electric Vehicle Battery Electrolyte Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The German electrolyte market exhibits tiered consolidation around integrated chemical conglomerates and focused additive formulators. Three archetypes dominate: diversified material science conglomerates with captive salt production, specialty chemical houses concentrating high-purity additive portfolios, and Asian integrated producers leveraging global lithium hexafluorophosphate scale. Capacity expansion and direct OEM-contractor relationship formation constitute the primary competitive vectors displacing traditional distributor channels.
Within the diversified conglomerate tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning. BASF anchors its Ludwigshafen integrated production complex to sustain captive supply advantages for lithium-ion cell producers across German automotive clusters. Evonik occupies a position as a specialty additive formulator, differentiating through high-purity portfolios targeting next-generation solid-state programs. Mitsubishi Chemical Group represents the Asian integrated producer archetype, sitting within global supply networks that dominate lithium salt capacity.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| BASF SE |
| Evonik Industries AG |
| Solvay SA |
| UBE Industries Ltd |
| Umicore SA |
| 3M Co. |
| Arkema SA |
| Capchem |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese lithium hexafluorophosphate production is compressing input costs for German formulators while simultaneously eroding their bargaining power against integrated Asian suppliers. This utilization asymmetry forces domestic blenders to absorb margin pressure on standard carbonate formulations while extracting premiums from captive supply arrangements with Baden-Württemberg OEMs.
Pricing Analysis
The customization-premium spread between configured-to-order solid-state electrolyte packages and standard liquid carbonate blends now exceeds triple-digit percentage points. Price differentiation rests on KBA type-approval certification tiers and volume scale commitments, with automotive OEMs locking multi-year offtake agreements. Cost compression in commodity-grade formulations is intensifying because Chinese integrated producers are flooding European spot markets. Battery manufacturers remain most price-sensitive, while research institutes tolerate premium pricing for pre-commercial ionic liquid samples.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for German electrolyte formulators. Geographic supply concentration centers on China, South Korea, and Japan for lithium hexafluorophosphate salt and high-purity carbonate solvents. Raw material dependencies draw from fluorinated additive precursors and ethylene carbonate feedstocks. Single-source vulnerability in sulfide ceramic powders for solid-state programs threatens Stuttgart-based pilot lines. Distribution runs through direct OEM-contractor channels that are displacing legacy chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German electrolyte procurement is evolving into a service-attach opportunity as technical qualification support and formulation co-development contracts expand faster than commodity blend volumes. Recurring-revenue layers around salt regeneration and solvent recovery services are capturing disproportionate margin pools.
For Market Incumbents: Pre-empt sodium-ion electrolyte standardization by locking hard carbon anode partnerships with Stuttgart energy storage providers before research funding crystallizes into procurement specifications. BASF and Evonik should deepen captive supply integration into Lower Saxony gigafactory sites to defend against Asian integrated producers establishing European blending capacity. Certification investment in EU Battery Regulation delegated act compliance represents the critical defensive lever. For New Entrants and Emerging Players: Build out sodium-ion electrolyte formulation capability targeting grid-scale energy storage providers in Baden-Württemberg seeking mineral supply security outside lithium dependence. The most penetrable segment sits with research institutes piloting next-generation ionic liquid systems, where technical service intensity matters more than manufacturing scale. A go-to-market angle through Fraunhofer partnership programs offers qualification pathway credibility without legacy distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty additive formulators with multi-year technical service contracts tied to solid-state battery roadmaps. Long-term viability across the next decade hinges on positioning upstream of OEM direct procurement consolidation. Acquisition targets should display integrated salt recovery loops or sulfide electrolyte pilot production capability. The signal to watch is delegated act finalization under the EU Battery Regulation, which will trigger capital deployment into circular economy infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Production | Captive supply security reduces Chinese import dependency for Ludwigshafen chemical complexes. |
| Solid-State Electrolyte Pilot Scale-Up | Sulfide and oxide ceramic formats enable Mercedes-Benz energy density targets above 400 Wh per kilogram. |
| Solvent Recovery Infrastructure Investment | German circular economy framework incentives support black mass processing in Saxony-Anhalt. |
| Direct OEM Technical Partnership | Volkswagen Group and BMW are consolidating procurement around single-source electrolyte relationships. |
| Sodium-Ion Research Consortium Participation | Federal funding streams in Stuttgart target mineral supply security outside cobalt and nickel chains. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrolyte formulation chemists, OEM procurement directors, and KBA type-approval specialists; and secondary validation through customs trade data, EU Battery Regulation delegated act drafts, and ACC industry reports. Bottom-up triangulation across plant-level capacity disclosures and top-down demand modeling from vehicle production databases ensured cross-verification. The stakeholder set included BASF technical service teams, Evonik R&D directors, Northvolt supply chain managers, and Fraunhofer institute program leads.
Forecast inputs considered electrolyte content per vehicle across passenger and commercial segments, battery chemistry migration from NMC to LFP and sodium-ion formats, and regional production cluster development in Lower Saxony and Thuringia. Segmentation dimensions spanned formulation chemistry, battery chemistry, end-user category, and application type. CAGRs were derived from slope analysis of annual volume build rates against OEM electrification roadmaps. Industry-specific inputs included KBA validation timeline compression effects and EU Green Deal carbon border adjustment implementation schedules.
Practitioners should monitor ECHA PFAS restriction proposal advancement and Chinese lithium salt capacity utilization for early signals of forecast revision. Forecasts reflect assumptions around solid-state battery pilot line commercialization timing and delegated act recycled content threshold stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market