
 Lawn Mower Lithium Battery Market | 2026-2036
Lawn Mower Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Mower Lithium Battery Market Insights
UL 2580 certification for lithium battery safety in outdoor power equipment is rotating the competitive landscape toward suppliers with proven thermal-runaway testing. Trojan Battery Co. leverages its deep-cycle heritage to anchor credibility among commercial mower fleets. Johnson Controls International PLC sustains manufacturing scale across multiple electrochemistries. East Penn Manufacturing Co. competes through backward integration into lead-acid conversion channels while building lithium expertise.
Lawn mower lithium batteries store electrochemical energy in cylindrical or prismatic cells, typically delivering 40V to 80V at capacities from 2Ah to 8Ah, with fast-charge architectures targeting 30-minute to 2-hour cycles for professional crews. LFP chemistry dominates the installed base due to thermal stability and cycle-life economics, while NMC formulations capture premium rider-mower segments where energy density commands price tolerance. Power rating stratification mirrors equipment class: 40V serves walk-behind residential units, 60V-80V targets commercial zero-turn platforms where runtime extension determines contractor productivity.
EPA small off-road engine standards and California Air Resources Board zero-emission mandates shape product roadmaps for OEM battery sourcing. OSHA workplace noise regulations amplify electric mower adoption in commercial landscaping, expanding aftermarket replacement demand. Stakeholders must monitor how NHTSA shipping-classification rules for lithium cells reshape logistics costs and regional distribution strategies.
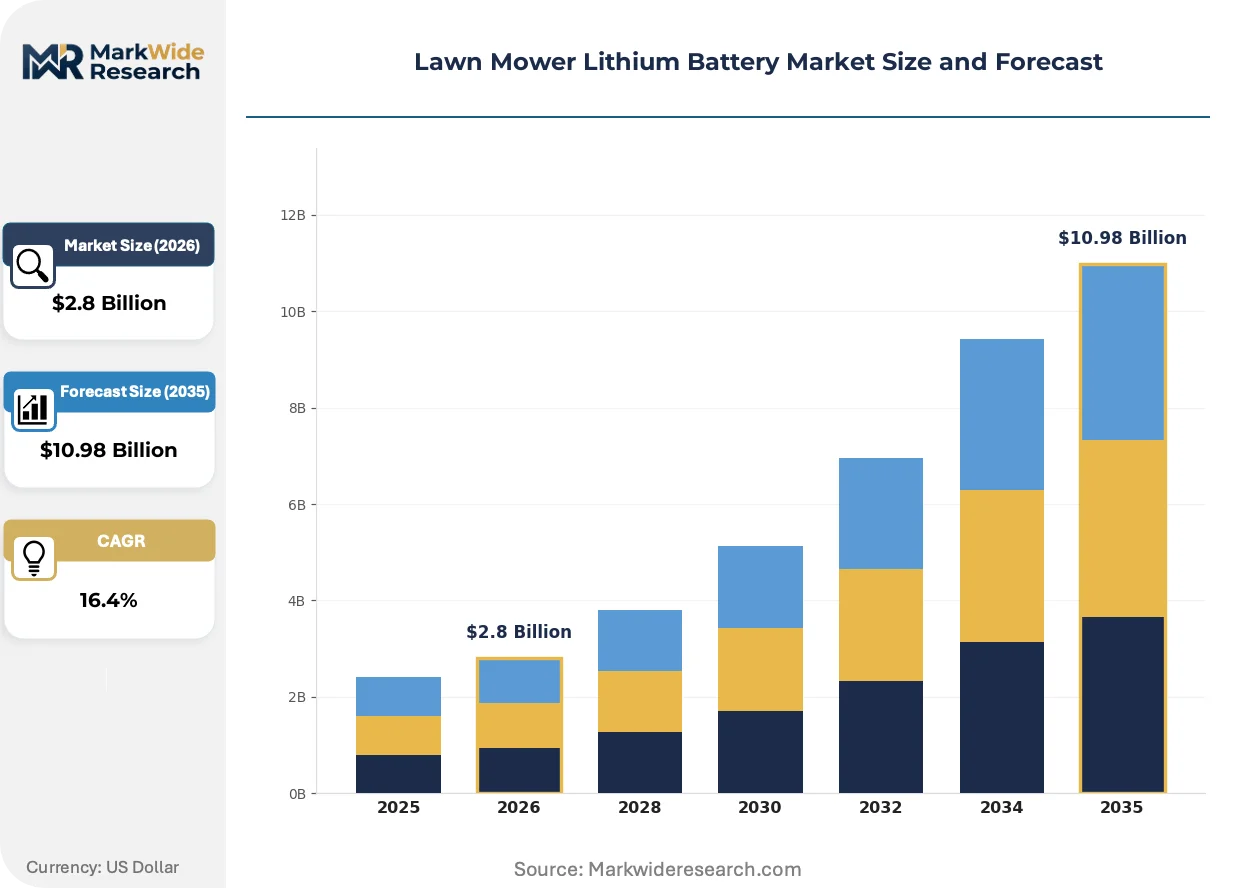
Market Dynamics
EPA small off-road engine standards and California Air Resources Board zero-emission mandates are compressing the transition timeline for gasoline-to-electric conversion across commercial and residential mower fleets. This regulatory pressure concentrates sourcing decisions among battery suppliers with certified thermal-runaway containment and fast-charge architectures.
Growth Catalysts
- OSHA workplace noise regulations:Commercial landscaping contractors in the United States face decibel limits that electric mowers satisfy, accelerating fleet electrification and replacement battery procurement.
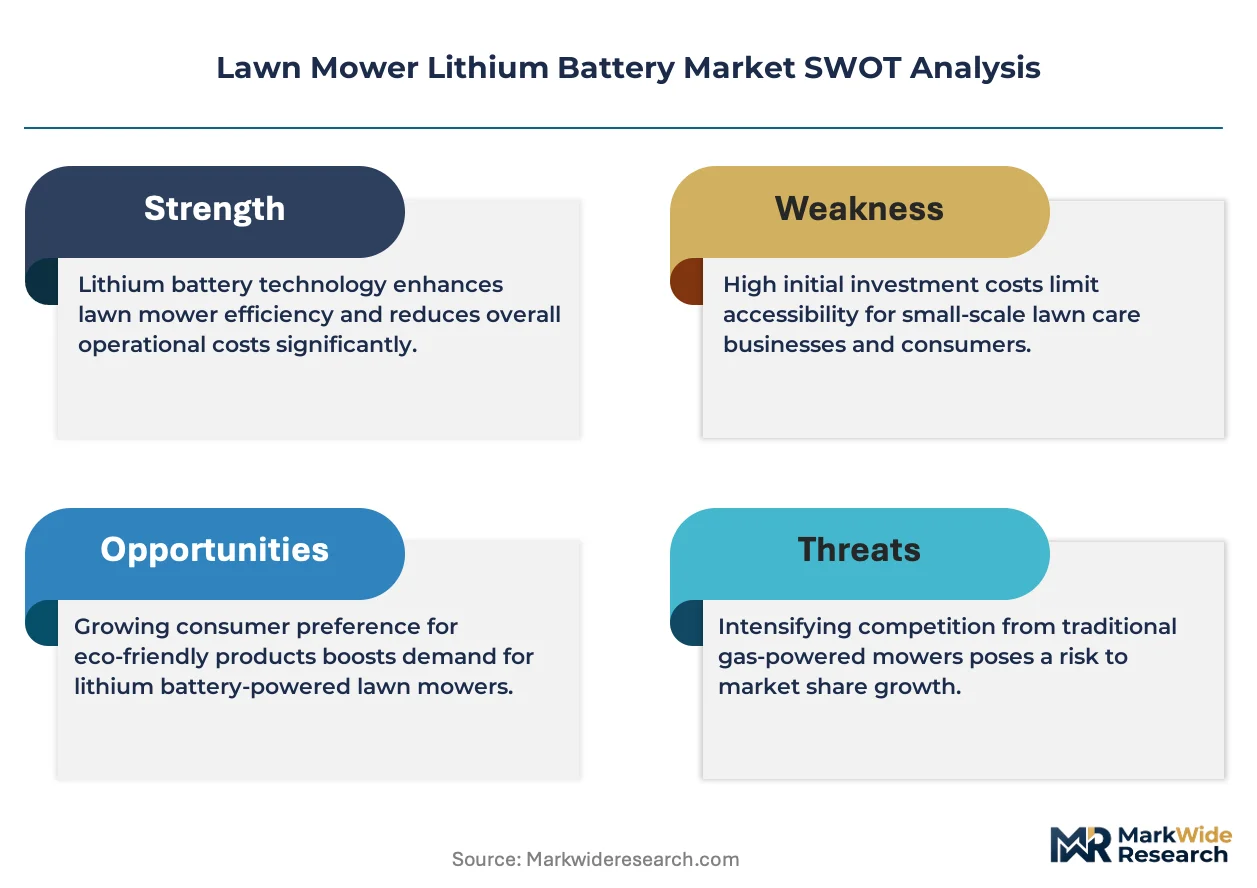
- Fast-charge architectures:Lithium iron phosphate cell configurations now enable 30-minute to 2-hour charge cycles, eliminating downtime penalties that previously constrained professional crew adoption.
- Suburban lawn culture concentration:Premium battery uptake clusters in United States metropolitan exurbs where large lot sizes sustain demand for higher-voltage, extended-runtime packs.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode active materials create margin compression for battery assemblers without long-term offtake agreements.
- NHTSA shipping-classification rules:Hazmat designation for lithium cells above certain energy thresholds inflates logistics costs and constrains regional distribution network density.
- Lead-acid residual infrastructure:Existing recycling and retail channels for flooded batteries slow lithium conversion in price-sensitive residential segments.
Strategic Opportunities
- Rider-mower premium segments:NMC chemistry penetration in zero-turn platforms commands price tolerance for energy density advantages over LFP alternatives.
- UL 2580 certification gap:Suppliers with proven thermal-runaway testing credentials capture OEM sourcing decisions as safety standards tighten.
- Commercial fleet leasing channels:Battery-as-a-service models for landscaping contractors reduce upfront capital barriers and lock in recurring revenue streams.
Industry Challenges
- UL 2580 certification timeline:Third-party safety testing cycles extend 12-18 months, delaying product launches and freezing supplier qualification windows.
- Electrochemistry talent scarcity:Cell engineering and battery management system firmware expertise concentrates among a limited pool of specialists, inflating compensation costs.
- Legacy equipment integration:Retrofit battery packs must accommodate proprietary connector and control protocols from incumbent gasoline mower platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Mower Lithium Battery Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, LCO, NCA Power Rating: 40V, 48V, 60V, 80V Capacity: 2Ah, 4Ah, 6Ah, 8Ah Charging Time: 30 min, 1 hour, 2 hours, 3 hours |
| Companies Covered | Anhui Uplus Energy Technology Co. Ltd., East Penn Manufacturing Co., Exide Technologies, Harris Battery Co., Johnson Controls International PLC, Trojan Battery Co., Yuasa Battery, Marshall Power Australia Pty Ltd., Yucell Industry Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Mower Lithium Battery Market Trends and Innovations
Solid-state and silicon-anode research is migrating from electric vehicle programs into outdoor power equipment, promising energy density gains that would extend runtime without pack weight penalties. This technology transfer is compressing development cycles and reshaping supplier R&D priorities.
Lithium iron phosphate chemistry is supplanting nickel-manganese-cobalt formulations in walk-behind residential units where thermal stability and cycle-life economics outweigh energy density requirements. Commercial contractors deploying 40V platforms prioritize LFP packs for their 2000-plus cycle durability. This chemistry rotation is compressing price premiums between premium and standard battery tiers.
California Air Resources Board zero-emission mandates are forcing OEMs to eliminate small off-road gasoline engines from 2024 product lines. Battery suppliers must scale manufacturing to absorb surge demand from compliant equipment launches. Professional landscaping fleets in the state face compressed replacement timelines as gasoline equipment ages out of permitted use.
Landscaping contractors are consolidating procurement through national equipment rental networks rather than decentralized dealer channels. Rental fleet operators negotiate volume battery sourcing agreements directly with cell manufacturers, disintermediating traditional aftermarket distributors. This channel shift concentrates in United States Sun Belt markets where year-round mowing sustains high equipment utilization rates.
Lawn Mower Lithium Battery Market Segmentation
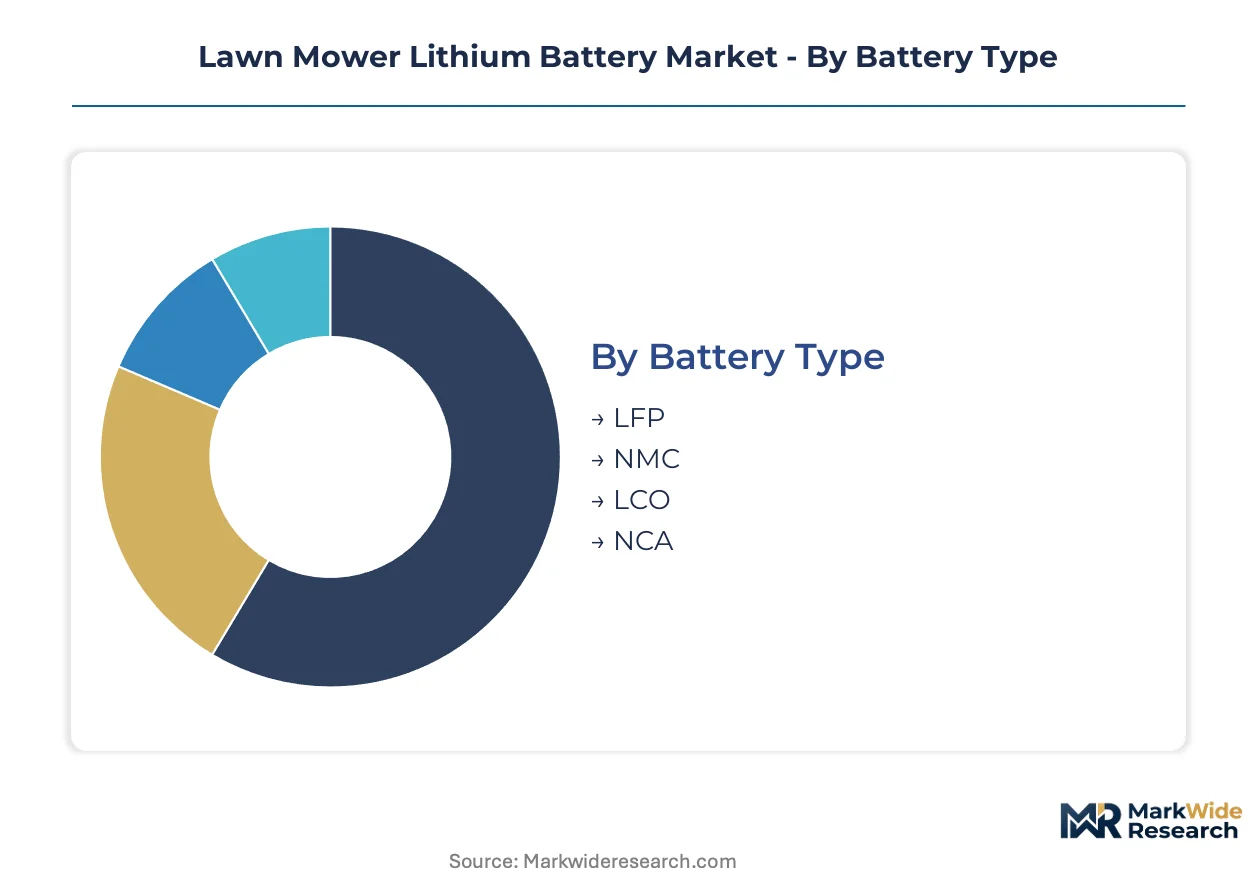
Segmentation in lawn mower lithium batteries reveals how technical specifications map to distinct use cases and margin structures. Voltage tiers and cell chemistry choices directly determine which customer segments suppliers can profitably serve.
Battery Type:
Margin pools concentrate in NMC formulations for premium rider equipment, while LFP dominates volume through replacement cycles in commercial walk-behind fleets.
- LFP:Lithium iron phosphate cells deliver thermal stability and 2000-plus cycle durability. Demand clusters among United States commercial landscaping contractors running 40V walk-behind platforms where runtime economics outweigh energy density premiums.
- NMC:Nickel-manganese-cobalt chemistry packs higher energy density into equivalent pack volumes. Zero-turn rider mowers in suburban United States exurbs absorb these packs where weight reduction and extended cutting sessions command price tolerance.
- LCO:Lithium cobalt oxide formulations occupy niche applications requiring maximum volumetric energy density.
- NCA:Nickel-cobalt-aluminum variants serve specialized high-discharge scenarios in premium equipment segments.
The dominant share belongs to LFP, while NMC is closing the gap fastest.
Power Rating:
Application requirements stratify cleanly across voltage tiers, with professional equipment driving uptake at higher ratings.
- 40V:Entry-level residential walk-behind mowers and light-duty commercial units deploy these packs. United States homeowner demand sustains volume here, though margins compress against lead-acid conversion pricing.
- 48V:Mid-tier residential self-propelled platforms and compact commercial equipment favor this intermediate voltage for balanced power-to-weight ratios.
- 60V:Commercial stand-on and small zero-turn mowers standardize on this tier. Professional crews in California facing CARB zero-emission mandates accelerate fleet conversion here.
- 80V:Heavy-duty zero-turn and ride-on platforms for municipal and estate-scale mowing require maximum sustained discharge capability. OSHA workplace noise regulations amplify electric adoption in this class.
40V retains volume leadership, though 60V-80V tiers are expanding most quickly.
Capacity:
Runtime requirements scale with lot size and crew productivity targets, concentrating revenue in mid-range capacities.
- 2Ah:Compact residential trimmers and edgers utilize these lightweight packs. United States urban homeowners with small lots generate replacement demand.
- 4Ah:Standard walk-behind mowers deploy this capacity for typical 30-45 minute runtime sessions. Suburban United States markets sustain volume procurement here.
- 6Ah:Extended-runtime residential and light commercial equipment favors this tier. Professional crews prioritize these packs for reduced mid-day charging interruptions.
- 8Ah:Maximum runtime configurations for estate-scale and commercial rider platforms command premium positioning. Fast-charge architectures become essential at this capacity to avoid crew downtime penalties.
4Ah holds the installed base majority, while 6Ah climbs the fastest.
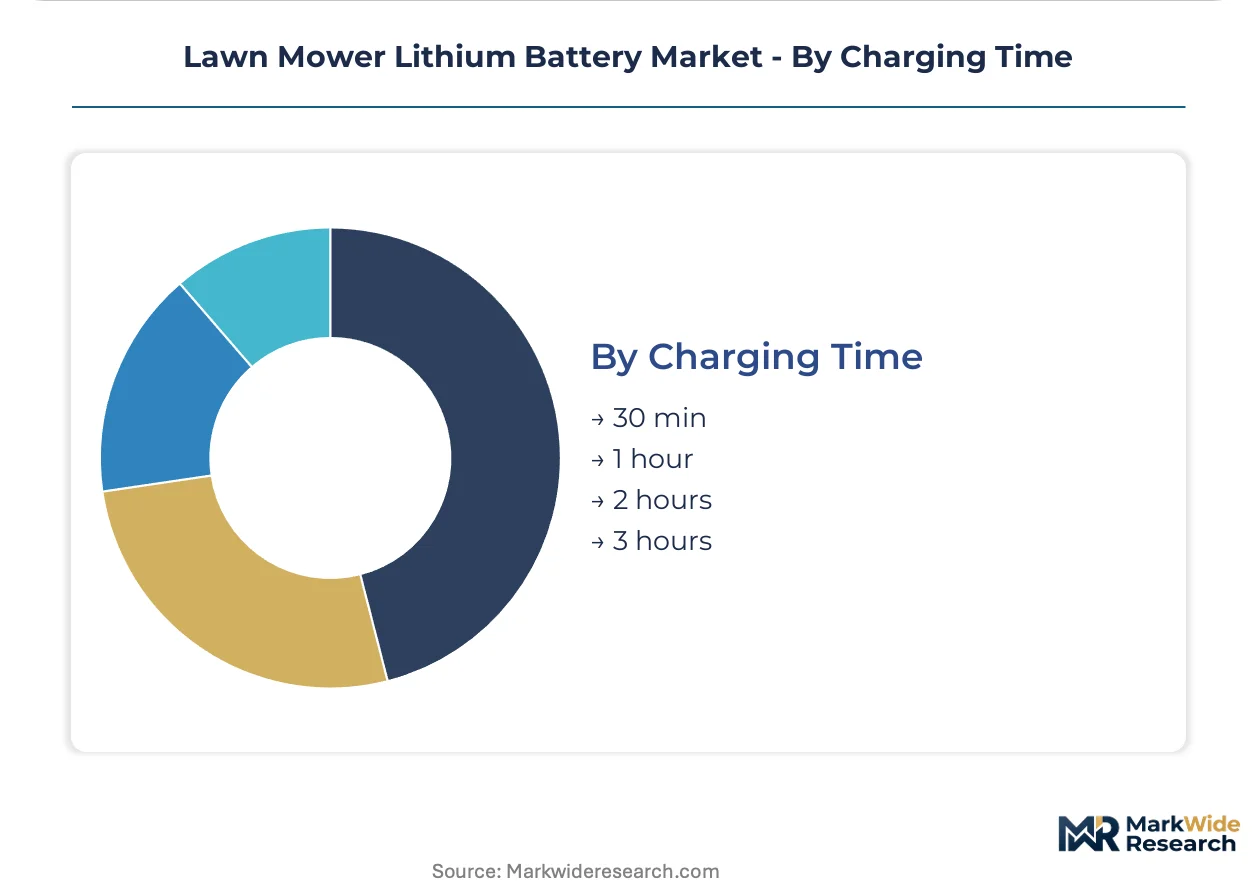
Charging Time:
Professional crew economics create acute pressure on recharge windows, concentrating innovation investment in sub-hour solutions.
- 30 min:Ultra-fast architectures using specialized LFP cell configurations and thermal management systems. United States commercial fleet operators pay premiums for these packs to sustain continuous crew productivity.
- 1 hour:Standard fast-charge target for professional-grade equipment. Landscapers running multiple battery sets rotate through lunch-break charging cycles.
- 2 hours:Residential and light commercial acceptable threshold. Overnight charging habits dominate this segment.
- 3 hours:Economy-tier residential packs where cost minimization outweighs convenience factors. Lead-acid residual infrastructure slows displacement here.
1 hour configurations dominate current procurement, while 30 minute solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial landscaping contractors concentrate procurement in suburban United States exurbs, while residential replacement demand clusters in metropolitan areas with large lot sizes. Battery suppliers prioritize certification alignment with EPA and CARB mandates when selecting geographic expansion sequences.
United States
Professional landscaping fleets in Florida and Texas drive 60V-80V platform adoption for year-round mowing operations. EPA small off-road engine standards and CARB zero-emission mandates compress gasoline-to-electric conversion timelines across commercial fleets. Atlanta and Dallas-Fort Worth anchor distribution hub expansion for fast-charge battery architectures serving Sun Belt contractors.
Germany
Municipal green-space maintenance contracts in Bavaria and North Rhine-Westphalia accelerate electric rider-mower procurement. REACH compliance requirements for chemical substance registration shape cell chemistry selection among battery assemblers serving European OEMs. Stuttgart's industrial corridor hosts testing facilities for thermal-runaway containment validation under UL 2580-equivalent standards.
China
Export-oriented cell manufacturers in Guangdong and Jiangsu provinces supply cylindrical LFP formats to outdoor power equipment brands. MIIT industrial policy and dual carbon goals channel subsidies toward battery energy density improvements. Shenzhen's electronics manufacturing clusters integrate battery management system firmware with mower control protocols.
United Kingdom
Estate-scale grounds maintenance in Surrey and Oxfordshire sustains premium 80V pack demand for extended runtime applications. CE marking requirements and forthcoming UKCA transition rules govern product conformity assessment for imported battery systems. London's green-space procurement policies increasingly specify zero-emission equipment for park maintenance contracts.
Australia
Commercial mowing contractors in Queensland and New South Wales prioritize fast-charge architectures to maximize equipment utilization across extended growing seasons. State-level environmental protection agencies in Victoria and South Australia implement noise restriction bylaws that electric mowers satisfy. Melbourne's equipment rental networks consolidate battery procurement through direct manufacturer agreements.
Lawn Mower Lithium Battery Market Competitive Landscape
Player mix skews toward diversified industrial battery conglomerates with legacy lead-acid infrastructure transitioning lithium portfolios. Market structure concentrates among North American and East Asian suppliers with certified thermal-runaway testing capabilities. Three archetypes dominate: deep-cycle heritage specialists leveraging commercial fleet relationships, diversified energy storage conglomerates with multi-electrochemistry manufacturing scale, and export-focused cell assemblers serving OEM private-label programs. Competitive moves center on UL 2580 certification acquisition and backward integration into cathode active material supply.
Among North American heritage manufacturers, Trojan Battery Co. and East Penn Manufacturing Co. exemplify the deep-cycle-to-lithium transition archetype, while Johnson Controls International PLC represents diversified conglomerate scale. These three anchors illustrate how supplier credibility in commercial landscaping channels derives from legacy fleet relationships and certification timelines rather than pure technology differentiation.
| Leading Market Players |
|---|
| Anhui Uplus Energy Technology Co. Ltd. |
| East Penn Manufacturing Co. |
| Exide Technologies |
| Harris Battery Co. |
| Johnson Controls International PLC |
| Trojan Battery Co. |
| Yuasa Battery |
| Marshall Power Australia Pty Ltd. |
| Yucell Industry Limited |
| Others |
Pricing and Supply Chain Analysis
UL 2580 certification gates both supplier qualification windows and price tier separation in lawn mower lithium batteries, compressing margins for uncertified assemblers while enabling certified players to command sustained premiums across commercial fleet channels.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement between cell manufacturers and battery assemblers, transferring raw material volatility directly to pack pricing. Three-tier pricing structure across premium, standard, and economy levels separates UL 2580-certified fast-charge architectures from uncertified residential packs and lead-acid conversion alternatives. Cost compression in the economy tier is intensifying because flooded battery residual infrastructure sustains price-sensitive homeowner demand. Commercial landscaping contractors show lowest price sensitivity, prioritizing 30-minute charge cycles and thermal-runaway containment over per-Ah cost.
Supply Chain Analysis
Inventory lead times for cylindrical LFP cells stretch 12-16 weeks from Guangdong and Jiangsu province manufacturers, constraining OEM launch schedules for CARB-compliant equipment lines. Cathode active material supply draws from Chinese and South Korean precursor processors, with Australian and Chilean lithium carbonate feeding upstream. Single-source vulnerability concentrates in battery management system firmware development, where Shenzhen electronics clusters integrate proprietary mower control protocols. Distribution runs through national equipment rental networks and regional aftermarket distributors serving Sun Belt commercial fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of electrochemistry talent and UL 2580 testing capacity concentrates competitive advantage among suppliers with established certification timelines, locking out late entrants from commercial OEM sourcing decisions.
For Market Incumbents: Compound UL 2580 certification credentials into exclusive supply agreements with zero-turn mower OEMs facing CARB zero-emission deadlines. Deepen backward integration into cathode active material supply to offset lithium carbonate volatility, while expanding fast-charge manufacturing capacity in Dallas-Fort Worth and Atlanta distribution corridors to capture Sun Belt fleet conversion demand. For New Entrants and Emerging Players: UL 2580 fast-track certification programs offer entry pathways into the 60V-80V commercial rider segment where incumbent capacity constraints delay qualification windows. Target estate-scale grounds maintenance in United Kingdom Surrey and Oxfordshire corridors, where premium 8Ah pack demand outstrips certified supplier availability. Pursue battery-as-a-service leasing models for landscaping contractors to bypass upfront capital barriers and establish recurring revenue footholds. For Investors and Strategic Acquirers: EPA small off-road engine standards and CARB zero-emission mandates reshape the acquisition landscape toward suppliers with proven thermal-runaway testing and commercial fleet relationships. Five-to-ten year viability favors diversified industrial battery conglomerates with legacy lead-acid infrastructure convertible to lithium scale. Target acquisition archetypes include deep-cycle heritage specialists with Trojan Battery Co.-like commercial channel anchoring. Watch NHTSA shipping-classification rule enforcement as inflection signal for logistics cost restructuring and regional distribution network consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| UL 2580 Certification Investment | Unlocks OEM sourcing decisions for CARB-compliant zero-turn platforms. |
| Backward Integration into Cathode Materials | Secures lithium carbonate supply against price volatility for pack assemblers. |
| Battery-as-a-Service Leasing Models | Reduces capital barriers for commercial landscaping contractors. |
| Fast-Charge Architecture R&D | Enables 30-minute charge cycles that professional crews pay premiums for. |
| Sun Belt Distribution Hub Expansion | Positions inventory close to Florida and Texas year-round mowing operations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, CARB zero-emission mandate documentation, and SEC 10-K disclosures from diversified battery manufacturers. Primary interviews captured perspectives from commercial landscaping fleet operators, OEM procurement managers, battery management system firmware engineers, and aftermarket distribution channel heads. Secondary validation drew from UL certification databases, NHTSA hazmat shipping classifications, and United States customs import records for lithium cell trade flows. Bottom-up unit economics for 40V through 80V pack configurations were triangulated against top-down market size estimates.
Segmentation dimensions modeled include cell chemistry type, voltage tier, capacity rating, and charge architecture speed across the projection horizon. The analytical framework incorporated professional versus residential end-use splits, regional regulatory cluster variations, and fleet conversion timing assumptions. CAGRs were derived from equipment replacement cycle analysis and electrification mandate compliance schedules. Industry-specific forecast inputs encompassed lithium carbonate price trajectory scenarios and UL 2580 certification pipeline visibility.
Underlying assumptions cover EPA enforcement continuity and CARB mandate phase-in adherence, with deviation risk concentrated in lithium carbonate supply disruptions and NHTSA shipping-classification rule modifications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market