
 All-Terrain Crane Market | 2026-2036
All-Terrain Crane Market Size, Share, and Industry Trends Forecast 2026-2036
All-Terrain Crane Market Analysis
Telematics-enabled fleet management is pivoting crane contracts from hardware sales to uptime-guarantee models. Liebherr-International AG leverages its European service network to anchor premium aftermarket revenue. XCMG Group competes on manufacturing scale across emerging infrastructure corridors. Tadano Limited specializes in compact all-terrain configurations for constrained urban job sites.
An all-terrain crane combines highway-speed roadability with rough-terrain flotation and multi-axle steering, typically offering lift capacities from 40 to 1,200 tonnes through telescopic or lattice boom configurations. Its primary purpose spans heavy lifting, material handling, and equipment installation across dispersed construction, energy, and industrial sites where site access precludes conventional truck cranes or crawler alternatives. Truck-mounted cranes dominate volume in mature markets where rapid highway transit between projects determines fleet utilization rates. Rental services capture expanding share as contractors prioritize operational flexibility over capital commitment, particularly in cyclical oil and gas and mining end-user segments.
German KBA vehicle-type approval and EU machinery directive compliance shape axle-load configurations and stability-control system requirements for cranes operating across European road networks. OSHA crane operator certification standards in the United States elevate training and inspection protocols, affecting fleet deployment economics. Japan's METI energy-efficiency benchmarks and emerging carbon-border considerations will influence powertrain choices as stakeholders weigh diesel-hybrid transitions against total cost of ownership across project lifecycles.
Market Dynamics
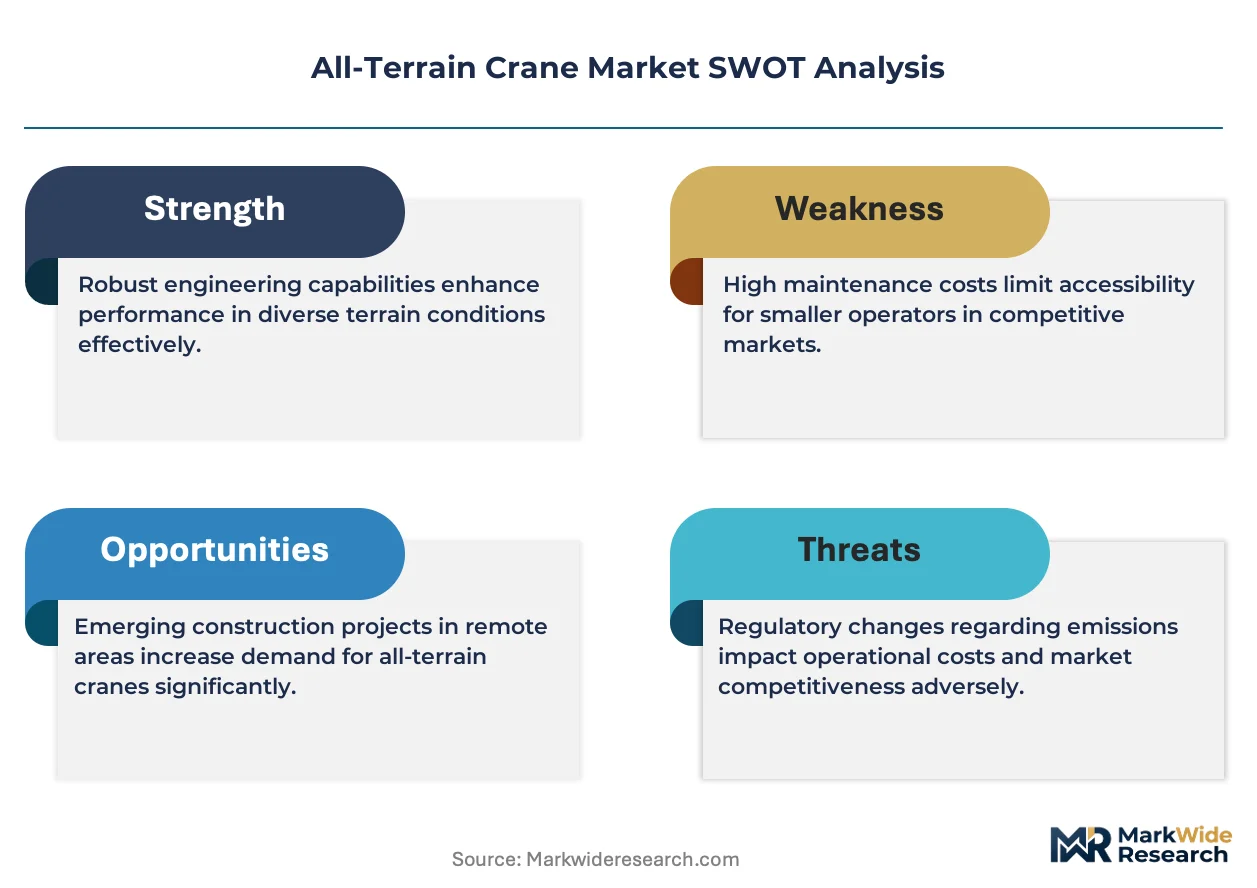
Telematics-enabled fleet management is pivoting crane contracts from hardware sales to uptime-guarantee models, compressing capital deployment cycles and elevating service-network density as the primary competitive moat.
Growth Catalysts
- EU Stage V emission standards:Tighter diesel particulate limits are forcing fleet turnover toward Stage V-compliant powertrains, accelerating replacement demand in German and French rental fleets.
- Offshore wind installation:European energy developers are expanding heavy-lift fleets for turbine component handling at port logistics clusters, particularly in Denmark and the Netherlands.
- Lattice boom configurations:Higher lift capacities for refinery and petrochemical maintenance are displacing crawler cranes in modular construction projects across the US Gulf Coast.
Market Restraints
- Specialized steel plate supply:High-strength quenched and tempered steel for boom fabrication concentrates among a limited supplier base in Germany and Japan, creating input cost volatility.
- Axle-load regulatory fragmentation:German KBA vehicle-type approval diverges from French ANSM standards, forcing redundant certification costs for cross-border fleet deployment.
- Crawler crane substitution:Lower daily rental rates for crawler alternatives in long-duration infrastructure projects constrain all-terrain crane utilization in bridge and dam construction.
Strategic Opportunities
- India port modernization:Sagarmala infrastructure corridors are creating demand for mobile heavy-lift capacity at container terminals in Jawaharlal Nehru Port and Mundra.
- EU Green Deal retrofit incentives:Member-state subsidy programs for diesel-hybrid conversions are opening aftermarket powertrain upgrade revenue streams.
- Telematics-AI convergence:Predictive maintenance algorithms integrated with crane load-monitoring systems are enabling performance-based contracting models.
Industry Challenges
- Certified operator scarcity:OSHA crane operator certification standards in the United States create training bottlenecks, extending crew mobilization timelines for specialized lift operations.
- Multi-axle steering calibration:Complex electronic stability control systems require manufacturer-authorized service intervention, limiting third-party maintenance options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Terrain Crane Market |
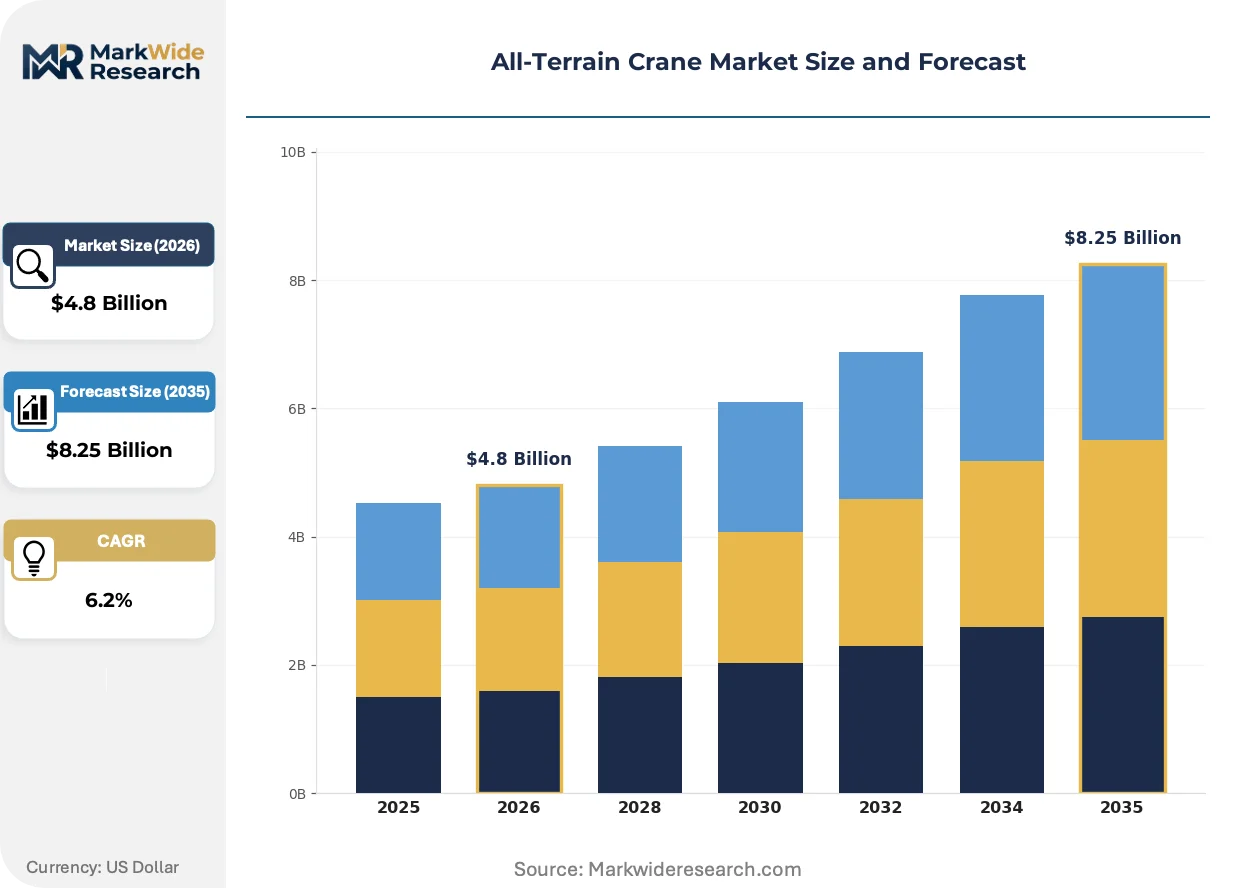
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Cranes, Folding Cranes, Truck-Mounted Cranes, Lattice Boom Cranes End User: Construction, Oil & Gas, Mining, Infrastructure Sales Channel: Direct Sales, Distributors, Online Sales, Rental Services Application: Heavy Lifting, Material Handling, Site Preparation, Equipment Installation |
| Companies Covered | Liebherr-International AG, XCMG Group, Zoomlion Heavy Industry Science and Technology Co., Ltd., Terex Corporation, Sany Heavy Industry Co., Ltd., Manitowoc, Tadano Limited, Konecranes PLC, Kobelco Cranes Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Terrain Crane Market Emerging Trajectories
Diesel-hybrid powertrains and predictive load-sensing systems are compressing fuel consumption benchmarks while telematics platforms restructure ownership economics around guaranteed uptime rather than asset transfer.
Variable displacement hydraulic pump technology is converging with real-time boom stability sensors to enable precision lifting in wind-affected conditions. Offshore wind contractors in the North Sea are deploying these configurations for nacelle installation at hub heights exceeding 150 meters. The technology is converging with remote operator assistance systems to reduce on-site crew requirements for precision placement operations.
EU machinery safety directives are mandating redundant load-moment limiters and automatic overload protection across all new crane registrations. Manufacturers must integrate dual-sensor validation systems to satisfy CE marking requirements for the European Economic Area. German rental fleets are absorbing compliance costs through extended lease terms, while Italian and Spanish contractors delay procurement pending clarity on retrofit obligations.
Rental service providers are unbundling maintenance and inspection packages from base equipment rates, creating transparent cost structures for project-based contractors. Oil and gas operators in the US Permian Basin are favoring this model to align crane availability with drilling cycle volatility. The shift is most pronounced in cyclical end-use segments where capital commitment flexibility outweighs long-term ownership economics.
All-Terrain Crane Market Segmentation
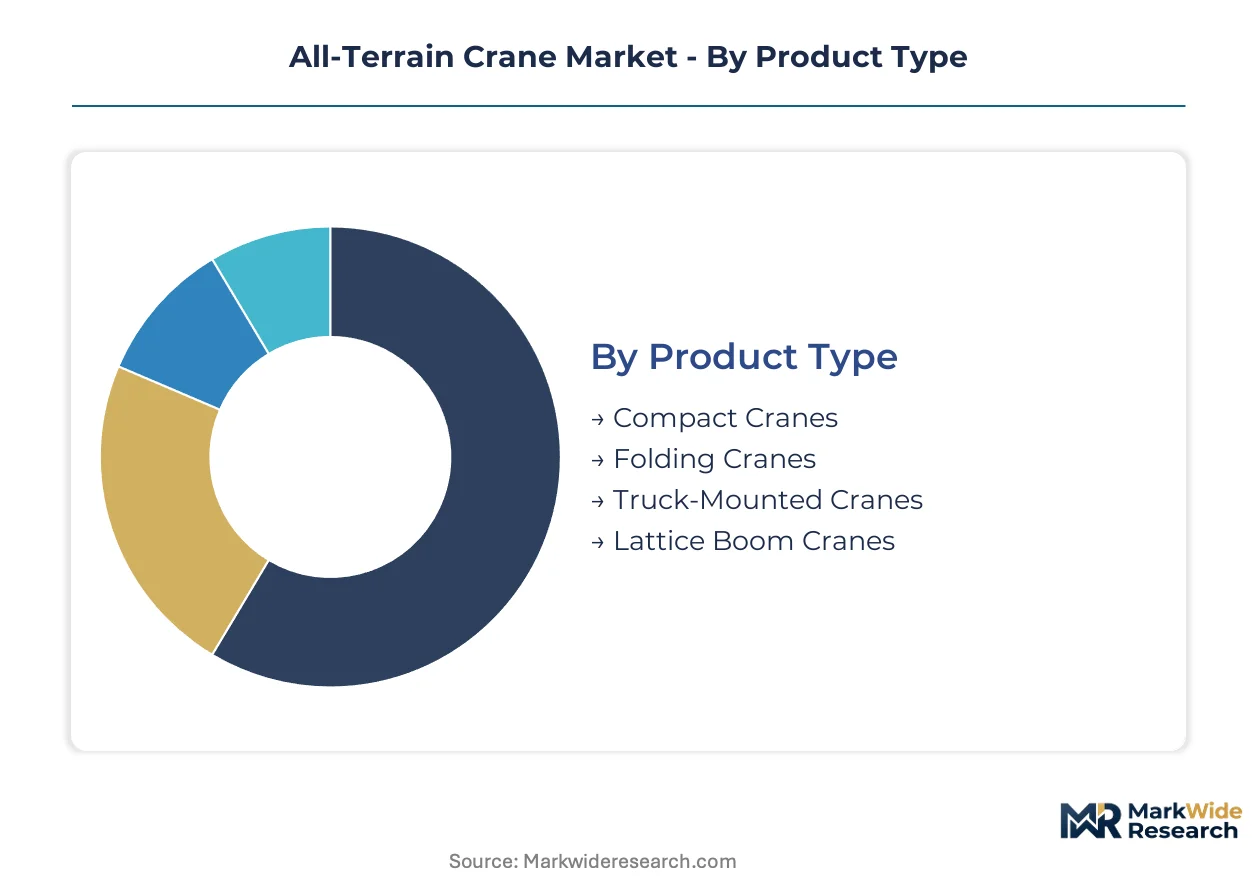
Segmentation in all-terrain cranes reveals how axle-load configurations, boom technologies, and contracting models align with distinct project economics. Supply concentration varies sharply across product types and sales channels, shaping margin structures and competitive positioning.
Product Type:
Supply concentration in boom fabrication and chassis engineering creates divergent manufacturing footprints across crane configurations.
- Truck-Mounted Cranes:Highway-speed mobility with telescopic booms dominates mature European rental fleets where rapid inter-site transit determines utilization economics. German KBA vehicle-type approval requirements concentrate production among established chassis integrators serving port logistics clusters in Hamburg and Rotterdam.
- Lattice Boom Cranes:Modular boom sections enable lift capacities exceeding 750 tonnes for refinery maintenance and offshore wind nacelle handling. Demand concentrates along the US Gulf Coast petrochemical corridor where crawler crane substitution accelerates deployment flexibility.
- Compact Cranes:Narrow chassis configurations navigate constrained urban job sites in Japanese metropolitan construction zones.
- Folding Cranes:Reduced transport dimensions serve remote mining operations in Australian iron ore and Chilean copper belts.
Truck-mounted cranes absorb the bulk of installed capacity; lattice boom configurations are expanding most quickly.
End User:
Project cycle volatility and capital commitment horizons segment demand across contractor ownership models.
- Construction:Residential and commercial building contractors favor rental services for phased lifting requirements across dispersed sites. OSHA crane operator certification standards in the United States elevate crew mobilization costs, compressing project margins for specialized lift operations.
- Oil & Gas:Drilling cycle volatility in the Permian Basin drives preference for uptime-guarantee contracts over asset ownership. Telematics-enabled fleet management aligns crane availability with well completion schedules.
- Infrastructure:Bridge and dam projects in India's Sagarmala corridors demand mobile heavy-lift capacity at container terminals.
- Mining:Australian and Chilean extraction operations require rough-terrain flotation for equipment maintenance in remote pit environments.
Construction claims the largest equipment base; oil and gas contracting models are shifting fastest toward service-based revenue.
Sales Channel:
Channel economics reflect customer risk tolerance and fleet management sophistication across end-use segments.
- Rental Services:Unbundled maintenance and inspection packages create transparent cost structures for project-based contractors. European energy developers expanding offshore wind fleets favor rental flexibility for turbine component handling campaigns.
- Distributors:Regional inventory positioning and manufacturer-authorized service networks anchor aftermarket revenue in German and French markets.
- Direct Sales:Large mining and oil and gas operators with captive maintenance capabilities procure directly for fleet standardization.
- Online Sales:Digital platforms serve secondary equipment markets and spare parts procurement for independent crane service providers.
Rental services capture the dominant transaction volume; direct sales retain importance in resource extraction verticals.
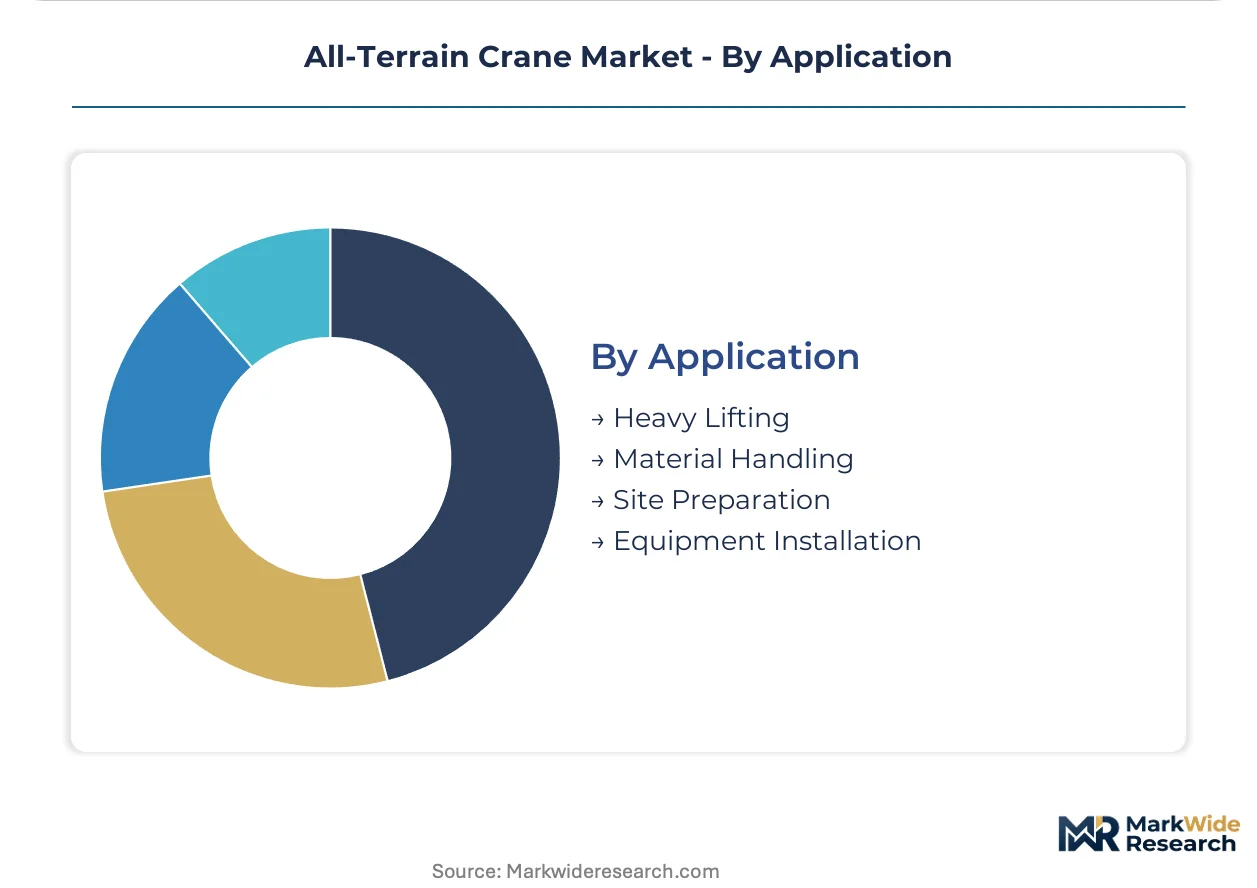
Application:
Lift precision requirements and site access constraints determine crane configuration selection across project types.
- Heavy Lifting:Refinery vessel installation and wind turbine nacelle placement demand load-moment limiters with redundant sensor validation per EU machinery safety directives. Variable displacement hydraulic pumps enable precision control in wind-affected North Sea conditions.
- Equipment Installation:Manufacturing facility relocations and power plant commissioning require multi-axle steering for confined site maneuvering.
- Material Handling:Port container terminals in Jawaharlal Nehru Port and Mundra deploy mobile capacity for cargo logistics.
- Site Preparation:Foundation and grading contractors utilize compact configurations for utility pole and precast element placement.
Heavy lifting commands the premium equipment tier; equipment installation applications are climbing the fastest on infrastructure renewal cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chassis integrators and Japanese boom fabricators concentrate production, while demand disperses across port logistics clusters and energy installation corridors spanning five continents.
United States
OSHA crane operator certification standards elevate crew mobilization costs for specialized lift operations across the Permian Basin drilling cycle. EPA emission benchmarks intersect with state-level fleet turnover incentives in Texas and Louisiana. Gulf Coast petrochemical clusters absorb lattice boom configurations for refinery maintenance campaigns displacing crawler alternatives.
Germany
KBA vehicle-type approval requirements and EU Stage V emission standards compress replacement cycles in Hamburg and Rotterdam port logistics networks. Machinery safety directives mandate redundant load-moment limiters for CE marking compliance. Bavarian rental fleets extend lease terms to absorb stability-control system upgrade costs.
China
Dual carbon goals and MIIT energy-efficiency benchmarks accelerate diesel-hybrid powertrain adoption across Yangtze River Delta manufacturing zones. GB standards for mobile cranes tighten axle-load documentation for highway transit permits. Zhengzhou and Xuzhou machinery clusters export telescopic boom configurations to Belt and Road infrastructure corridors.
India
Sagarmala port modernization programs generate mobile heavy-lift demand at Jawaharlal Nehru Port and Mundra container terminals. CEA grid connectivity mandates for renewable energy projects expand turbine installation fleets. Maharashtra and Gujarat infrastructure contractors prioritize rental flexibility over capital commitment for cyclical construction phases.
Japan
METI energy-efficiency benchmarks influence powertrain selection in Tokyo and Osaka metropolitan construction zones. JIS standards for crane stability control align with compact chassis configurations navigating constrained urban job sites. Chubu region fabricators specialize in narrow-axle designs for seismic-resistant building projects.
All-Terrain Crane Market Vendor Landscape
Top-tier vendors anchor premium service-network density, while mid-tier fabricators compete on manufacturing scale and regional price positioning. The vendor base stratifies across three strategic archetypes: European heritage brands with dense aftermarket infrastructure, Chinese scale players with integrated supply chains, and Japanese precision specialists in compact configurations. Consolidation pressure intensifies through technology licensing partnerships and geographic expansion into emerging infrastructure corridors.
Within the European heritage tier, Liebherr-International AG and Tadano Limited exemplify contrasting strategic positions—one leveraging dense service networks for uptime-guarantee contracts, the other specializing in constrained-site mobility. XCMG Group represents the scale-driven archetype among Chinese manufacturers, occupying a position defined by integrated boom fabrication and chassis engineering capacity. These three anchors illustrate how competitive positioning diverges across aftermarket revenue capture, manufacturing scale, and application-specific specialization.
| Leading Market Players |
|---|
| Liebherr-International AG |
| XCMG Group |
| Zoomlion Heavy Industry Science and Technology Co., Ltd. |
| Terex Corporation |
| Sany Heavy Industry Co., Ltd. |
| Manitowoc |
| Tadano Limited |
| Konecranes PLC |
| Kobelco Cranes Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
High-strength quenched and tempered steel plate indices cascade through boom fabrication costs into three-tier pricing structures across premium, standard, and economy equipment tiers. German and Japanese mill concentration amplifies volatility for chassis integrators serving Hamburg and Rotterdam port logistics clusters.
Pricing Analysis
Margin tightening in standard-tier configurations reflects Stage V powertrain compliance costs absorbed by Bavarian rental fleets. Three-tier pricing structure across premium, standard, and economy levels differentiates by CE marking certification depth and manufacturer-authorized service network density. Cost-down pressure on economy-tier units accelerates because Chinese scale players capture Belt and Road procurement volume. Oil and gas contractors in the Permian Basin exhibit lowest price sensitivity due to uptime-guarantee contract preferences.
Supply Chain Analysis
EU Stage V domestic-content mandates reshape sourcing toward European axle-load component suppliers for KBA vehicle-type approval compliance. Boom fabrication concentrates in Germany and Japan; chassis engineering clusters in China and the United States. High-strength steel plate, electronic stability control systems, and multi-axle steering hydraulics constitute critical input dependencies. Single-source vulnerability concentrates in German quenched steel plate mills. Distribution runs through manufacturer-authorized service networks anchoring aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU machinery safety directive compliance costs and telematics-AI convergence are forcing consolidation among undifferentiated mid-tier fabricators lacking service-network density.
For Market Incumbents: Acquire telematics-enabled fleet management platforms to anchor uptime-guarantee contract economics. Deepen backward integration into high-strength steel plate supply through offtake agreements with German mills. Invest in predictive maintenance algorithm development to defend against emerging software-defined crane entrants. For New Entrants and Emerging Players: Capture India port modernization demand at Jawaharlal Nehru Port and Mundra through rental-service partnerships with Sagarmala infrastructure contractors. Target compact crane configurations for Japanese metropolitan seismic-resistant building projects. Deploy digital-first procurement platforms to bypass established distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor European heritage brands with dense aftermarket infrastructure in Germany and France. Long-term viability hinges on service-network density as the primary competitive moat across the projection horizon. Monitor EU Green Deal retrofit subsidy program uptake as inflection indicator for aftermarket powertrain upgrade revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Predictive maintenance algorithms enable performance-based contracting with oil and gas operators. |
| Diesel-Hybrid Powertrain Conversion | EU Green Deal subsidies unlock aftermarket upgrade revenue streams in German rental fleets. |
| Service Network Expansion | Manufacturer-authorized density anchors premium uptime-guarantee contract economics. |
| Compact Configuration Development | Narrow-axle designs penetrate Japanese metropolitan construction zones with seismic requirements. |
| Port Logistics Cluster Partnership | Offshore wind nacelle handling contracts in Rotterdam and Hamburg secure heavy-lift fleet deployment. |
Methodological Framework
Trade association filings, customs export records, and EU machinery directive registration databases formed the secondary backbone for this analysis. Primary interviews with fleet managers at German rental operators, maintenance directors at US Gulf Coast petrochemical facilities, and procurement leads at Indian port authorities validated demand assumptions. Bottom-up and top-down triangulation reconciled equipment shipment data with project pipeline announcements across wind energy installation corridors.
Bottom-up modeling segmented volume by axle-load configuration, boom technology type, and contracting model across the projection horizon. Top-down validation cross-referenced macro infrastructure spending patterns with crane utilization rates in cyclical end-use segments. CAGRs derived from regression analysis of historical fleet turnover against regulatory compliance deadlines. Stage V emission standard phase-in schedules and OSHA certification requirement changes served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines; deviation in EU machinery safety directive retrofit obligation clarity or German KBA approval processing delays would shift replacement demand patterns. Forecasts reflect documented assumptions regarding telematics adoption curves and rental-service penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Global Excavators Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Felling Heads Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Casting Equipment Market