
 Ultrasonic Welding Machine Market | 2026-2036
Ultrasonic Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Welding Machine Market Outlook
Tier-1 automotive suppliers is unwinding legacy resistance to ultrasonic welding for battery module assembly. Herrmann Ultrasonics leverages its German engineering base to dominate high-frequency systems for electric vehicle powertrains. Telsonic anchors its position through backward integration into transducer manufacturing, ensuring supply security for Asian electronics customers. Emerson Electric's Branson unit competes across medical and packaging verticals with broad channel control in North America.
An ultrasonic welding machine generates mechanical vibrations at frequencies typically between 20 kHz and 70 kHz to create solid-state molecular bonds between thermoplastic components without external heat or adhesives. The equipment converts electrical energy into acoustic waves through piezoelectric transducers, then focuses that energy via titanium or aluminum horns to melt and fuse material interfaces in milliseconds. Automatic systems command the largest installed base across high-volume automotive and packaging lines, while handheld configurations represent the fastest-growing category as field repair and prototyping demand expands among small enterprises. Digital control technology leads on precision and traceability, though analog systems persist in cost-sensitive packaging environments where repeatability requirements remain modest.
The FDA enforces validation protocols for medical device assembly equipment under 21 CFR Part 820 quality system regulations, directly shaping ultrasonic welder specifications for hermetic sealing applications. The EU MDR and REACH compliance frameworks in Europe impose material traceability and biocompatibility standards that filter equipment selection in cardiovascular and diagnostic device manufacturing. Japan's METI promotes energy-efficient manufacturing equipment through industrial standards that influence transducer efficiency benchmarks. Stakeholders must weigh regulatory divergence against platform standardization when configuring product portfolios for multi-region deployment.
Market Dynamics
Medical device validation requirements under FDA 21 CFR Part 820 and EU MDR are compressing equipment replacement cycles while forcing manufacturers toward digital-traceable welding platforms. This regulatory tightening is accelerating displacement of analog systems across cardiovascular and diagnostic assembly lines.
Growth Catalysts
- Battery module assembly:Electric vehicle powertrain manufacturers are specifying high-frequency ultrasonic systems for cell-to-cell bonding as thermal management demands intensify. Germany's southern industrial corridor around Stuttgart anchors this demand concentration.
- EU MDR validation protocols:The Medical Device Regulation mandates hermetic sealing documentation for cardiovascular implants, forcing equipment upgrades toward closed-loop process control systems with full parameter traceability.
- Field repair proliferation:Small enterprises in North American packaging and automotive aftermarket segments are driving handheld configuration demand for prototyping and localized component repair.
Market Restraints
- Titanium horn supply concentration:Aerospace-grade titanium sourcing for acoustic horns concentrates with limited specialty metal suppliers, creating input cost volatility and extended lead times for high-precision systems.
- Piezoelectric ceramic dependency:Transducer manufacturing relies on PZT ceramic supply chains centered in East Asian specialty material producers, exposing equipment makers to geographic concentration risk.
- Resistance welding substitution:Battery manufacturers in cost-sensitive segments retain metal joining alternatives for non-hermetic applications, limiting ultrasonic penetration in high-volume commodity cell production.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO regulatory alignment with international standards under the Medical Device Rules 2017 is attracting contract manufacturers seeking MDR-compliant assembly equipment for export markets.
- Energy efficiency mandates:Japan's METI industrial standards for manufacturing equipment efficiency create transducer performance benchmarks that favor advanced generator technology with regenerative power recovery.
- Convergence with laser marking:Integration of ultrasonic welding stations with inline laser traceability systems enables single-platform compliance with FDA UDI requirements for device identification.
Industry Challenges
- Process engineer scarcity:Qualified technicians capable of optimizing weld parameter development for novel polymer combinations remain concentrated with incumbent equipment suppliers, constraining customer self-sufficiency.
- IQ/OQ/PQ timeline compression:Medical device manufacturers face compressed installation and operational qualification schedules under accelerated product launch timelines, straining field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Welding Machine Market |
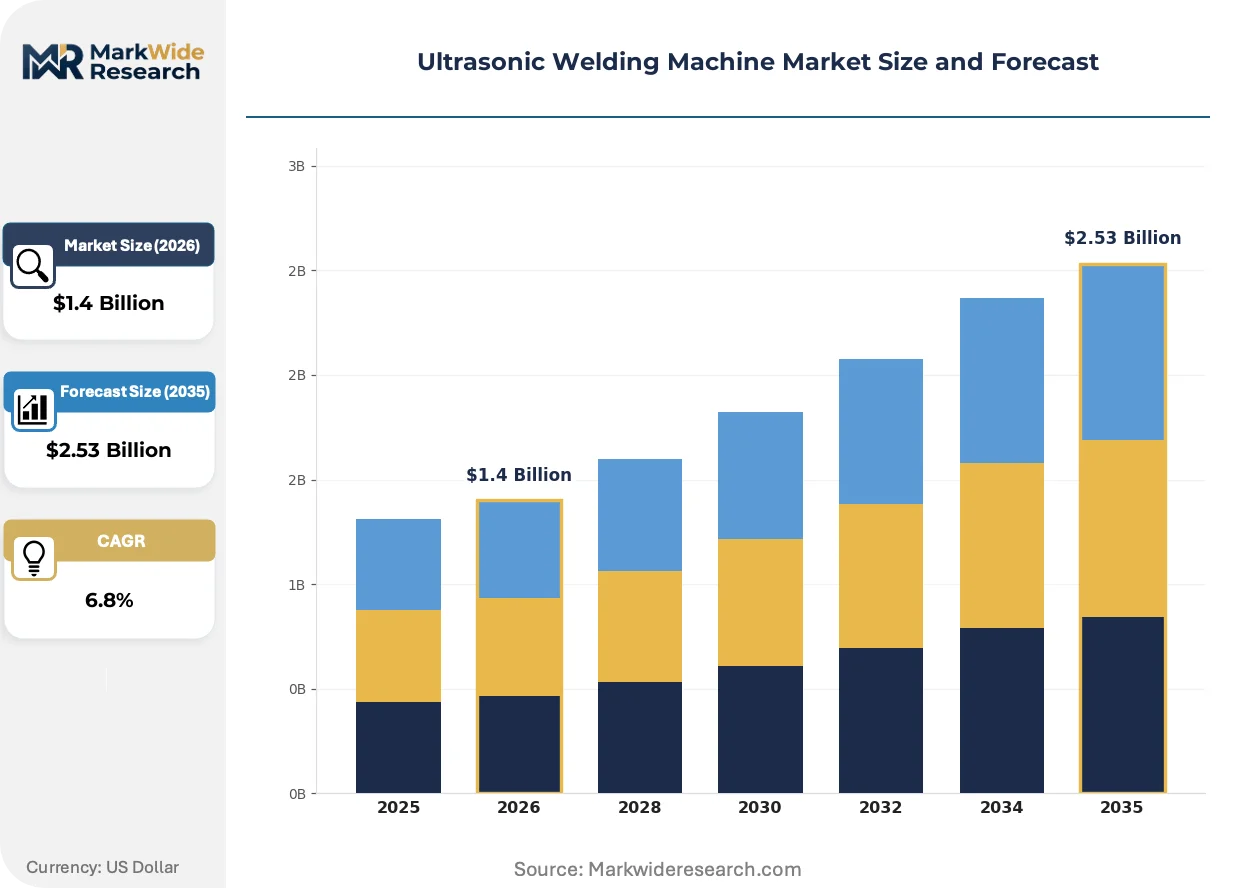
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Automatic, Semi-Automatic, Tabletop Application: Automotive Components, Medical Devices, Electronics Assembly, Packaging End User: Manufacturers, OEMs, Tier-1 Suppliers, Small Enterprises Technology: Digital Control, Analog Control, Continuous Wave, Pulse Mode |
| Companies Covered | Herrmann Ultrasonics, Telsonic, Emerson Electric (Branson Ultrasonics), Schunk Sonosystems, MS Ultraschall Technologie, Dukane Corporation, Rinco Ultrasonics, Plus Welding, Sonics & Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Welding Machine Market Strategic Shifts
Digital control architectures are displacing analog generator platforms across precision applications, while regulatory traceability mandates reshape equipment specification criteria. These forces are converging to elevate software-enabled process monitoring from optional feature to baseline requirement.
High-frequency generator technology is decomposing traditional 20 kHz dominance in automotive battery applications. Powertrain engineers at European and North American EV manufacturers are specifying 35-40 kHz systems for thin-gauge copper welding to minimize heat-affected zones. This frequency migration is decomposing the installed base of legacy equipment and compressing replacement cycles among tier-1 suppliers.
REACH substance restrictions on certain polymer additives are forcing material reformulations that alter weldability characteristics. European cardiovascular device manufacturers must revalidate established process windows as suppliers phase out restricted plasticizers and stabilizers. The diagnostic segment is responding fastest, with manufacturers pre-qualifying alternative resin grades through joint development programs with welding equipment vendors.
Equipment-as-a-service arrangements are displacing traditional capital purchase models among mid-volume medical device contract manufacturers. Monthly subscription structures bundle hardware, validation support, and predictive maintenance, reducing upfront capex barriers for emerging market entrants. This financing innovation is most visible in German and Swiss precision manufacturing clusters where equipment utilization rates support usage-based pricing.
Ultrasonic Welding Machine Market Segmentation
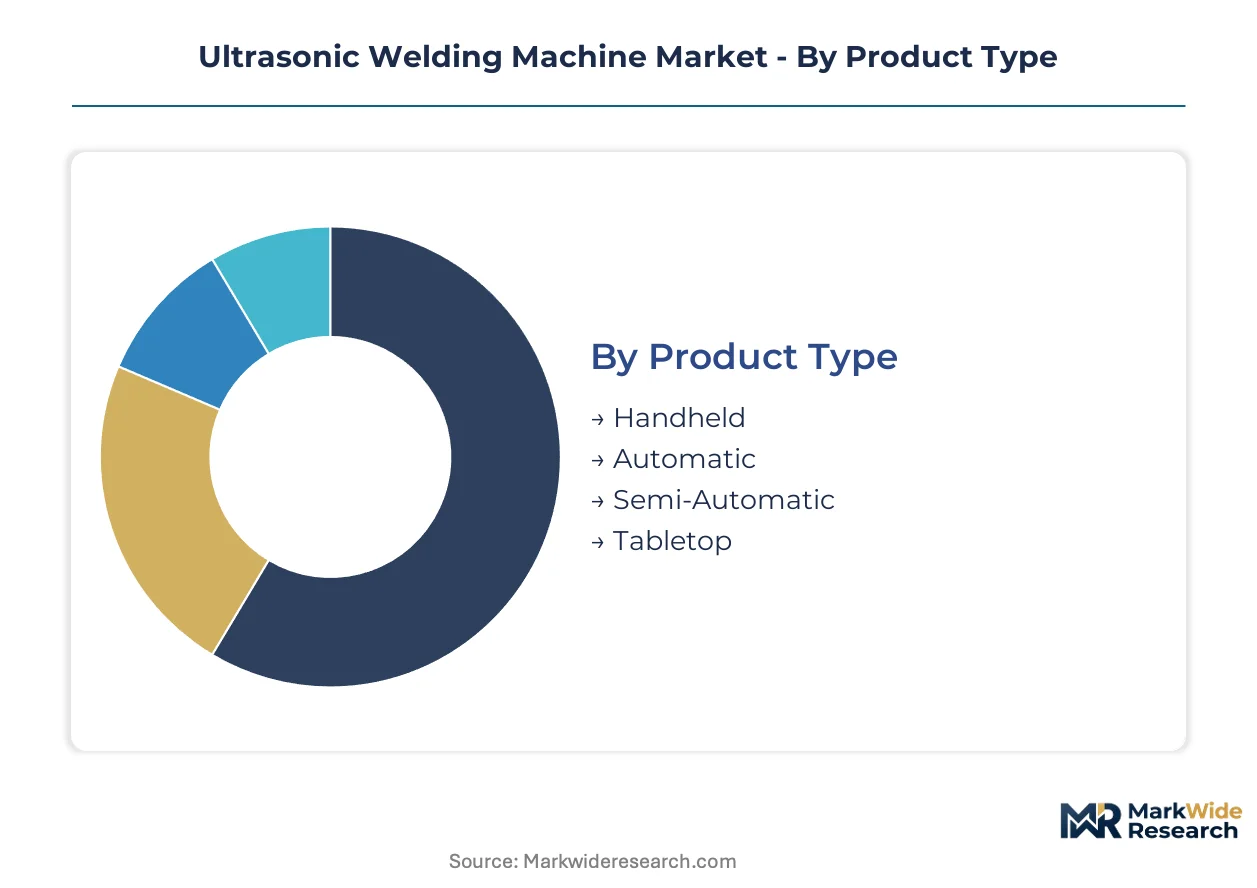
Ultrasonic welding equipment selection hinges on validation requirements that vary sharply across medical, automotive, and electronics end-uses. Regulatory frameworks in the US, Europe, and Asia-Pacific impose distinct traceability and precision standards that reshape equipment specifications by segment.
Product Type:
FDA 21 CFR Part 820 and EU MDR validation protocols create divergent equipment specifications across automation levels, with hermetic sealing applications demanding closed-loop control systems that handheld units cannot deliver.
- Automatic:These systems integrate servo-driven positioning with real-time amplitude modulation for high-volume production lines. Automotive battery module assembly in Germany's southern industrial corridor around Stuttgart specifies these configurations for cell-to-cell bonding under thermal management constraints.
- Handheld:Portable units weighing under 5 kilograms enable field repair and prototyping workflows. Small enterprises across North American packaging and automotive aftermarket segments are expanding adoption most quickly for localized component repair.
- Semi-Automatic:Operator-assisted systems bridge manual loading with automated weld sequencing for mid-volume medical device contract manufacturers.
- Tabletop:Compact bench-mounted units serve R&D laboratories and pilot production facilities with limited floor space.
Established volume favors Automatic systems in regulated mass production; emerging adoption favors Handheld configurations in distributed repair networks.
Application:
Cost tier differentiation separates capital-intensive validation requirements in cardiovascular manufacturing from commodity packaging where repeatability standards remain modest.
- Medical Devices:Hermetic sealing for cardiovascular implants and diagnostic cartridges demands full parameter traceability. EU MDR documentation requirements are forcing equipment upgrades toward digital control platforms with IQ/OQ/PQ validation support.
- Automotive Components:Battery module assembly for electric vehicle powertrains specifies 35-40 kHz high-frequency systems to minimize heat-affected zones in thin-gauge copper welding. European and North American EV manufacturers are driving specification changes fastest.
- Electronics Assembly:Fine-pitch connector welding and micro-component joining require precision amplitude control for sensitive circuit boards.
- Packaging:Tamper-evident seals and blister pack assembly utilize analog control systems where cost sensitivity outweighs traceability needs.
Medical Devices command premium pricing through validation complexity; Automotive Components show steepest expansion trajectory from electrification investment.
End User:
Customer type determines procurement structure, with OEMs and Tier-1 suppliers favoring capital purchase models while contract manufacturers shift toward equipment-as-a-service arrangements.
- Tier-1 Suppliers:These automotive component manufacturers specify integrated welding cells with robotic material handling. Unwinding legacy resistance to ultrasonic technology for battery applications is compressing replacement cycles among German and North American suppliers.
- Small Enterprises:Limited capital availability drives demand for handheld configurations and subscription-based service models. German and Swiss precision manufacturing clusters show fastest uptake of usage-based pricing structures.
- Manufacturers:Integrated production facilities with captive assembly operations prioritize platform standardization across multiple product lines.
- OEMs:Original equipment manufacturers specify welding equipment for in-house powertrain and medical device production with direct supplier relationships.
Tier-1 Suppliers concentrate procurement volume; Small Enterprises are gaining share fastest through financing innovation.
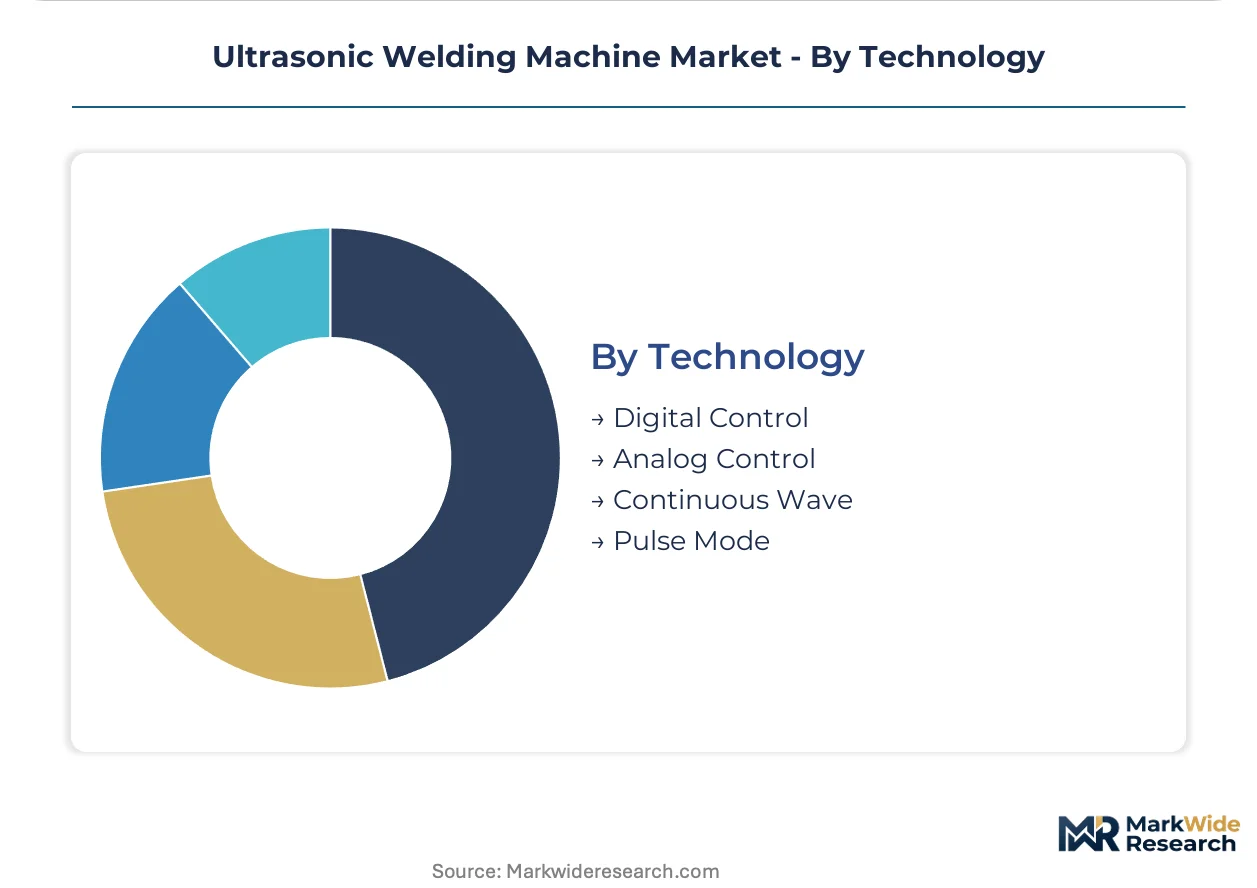
Technology:
Supply concentration in piezoelectric ceramics and generator electronics shapes technology availability, with East Asian specialty material producers influencing transducer manufacturing economics.
- Digital Control:Microprocessor-based systems enable closed-loop process monitoring with full parameter logging for regulatory submission. FDA and EU MDR traceability mandates are accelerating displacement of analog alternatives across cardiovascular assembly lines.
- Analog Control:Simpler generator architectures persist in cost-sensitive packaging environments where weld consistency requirements remain modest.
- Continuous Wave:Sustained acoustic energy delivery suits thick-section thermoplastic joining with consistent melt pool formation.
- Pulse Mode:Intermittent energy application reduces thermal stress for heat-sensitive polymers and multi-layer material stacks.
Digital Control dominates new specification activity; Pulse Mode shows expanding adoption for advanced material combinations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ultrasonic welding equipment exports flow primarily to North American automotive battery manufacturers and Asian electronics assembly hubs, establishing a transatlantic-Asia trade corridor that concentrates high-frequency system demand.
United States
FDA 21 CFR Part 820 validation protocols drive medical device manufacturers toward digital-traceable welding platforms for hermetic sealing applications. The regulatory framework mandates full parameter documentation for cardiovascular implant assembly. Greater Boston and the Minneapolis-St. Paul corridor host the densest concentrations of contract manufacturers upgrading analog systems.
Germany
EU MDR compliance deadlines are compressing equipment replacement cycles across cardiovascular and diagnostic device production. The Medical Device Regulation requires closed-loop process control with IQ/OQ/PQ validation support. Stuttgart and Munich anchor the southern industrial corridor where tier-1 automotive suppliers specify 35-40 kHz systems for EV battery module assembly.
China
Electronics contract manufacturers are expanding precision joining capacity for fine-pitch connector welding and micro-component assembly. MIIT industrial standards promote energy-efficient manufacturing equipment adoption. The Yangtze River Delta and Pearl River Delta clusters concentrate demand for high-volume automatic systems serving consumer electronics OEMs.
Japan
METI energy efficiency mandates for industrial equipment are shaping transducer performance benchmarks with regenerative power recovery requirements. The regulatory framework favors advanced generator technology in precision manufacturing. The Kanto region around Tokyo and the Chubu region around Nagoya host automotive and electronics manufacturers specifying pulse-mode systems for heat-sensitive polymer stacks.
India
CDSCO regulatory alignment with international standards under the Medical Device Rules 2017 is attracting export-oriented contract manufacturers seeking MDR-compliant assembly equipment. The framework enables European market access for domestically produced cardiovascular and diagnostic devices. Maharashtra and Gujarat host the fastest-expanding precision manufacturing clusters adopting subscription-based equipment financing models.
Ultrasonic Welding Machine Market Competitive Environment
Player mix skews toward European engineering-intensive specialists with deep vertical integration into transducer manufacturing. Market structure concentrates among German and Swiss fabricators controlling high-frequency generator technology, while North American participants compete through broad channel coverage across medical and packaging verticals. Three archetypes dominate: precision system specialists with captive ceramic supply, diversified industrial conglomerates with welding divisions, and regional fabricators serving cost-sensitive packaging segments. Competitive dynamics center on backward integration into piezoelectric materials and geographic expansion through validation-support partnerships.
Among German-based precision specialists, Herrmann Ultrasonics and Schunk Sonosystems exemplify the engineering-intensive archetype with integrated transducer manufacturing capabilities. Telsonic anchors the Swiss-German cross-border segment through upstream control over acoustic component supply. Emerson Electric's Branson unit occupies a position among diversified industrial participants competing across multiple verticals through established North American distribution infrastructure. These three company groupings represent distinct strategic postures: captive supply security, geographic-specialization focus, and channel-breadth coverage.
| Leading Market Players |
|---|
| Herrmann Ultrasonics |
| Telsonic |
| Emerson Electric (Branson Ultrasonics) |
| Schunk Sonosystems |
| MS Ultraschall Technologie |
| Dukane Corporation |
| Rinco Ultrasonics |
| Plus Welding |
| Sonics & Materials |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for aerospace-grade titanium horns concentrate pricing power with specialty metal suppliers serving German and Swiss precision fabricators, while inventory buffers at transducer manufacturers insulate high-frequency system pricing from PZT ceramic volatility.
Pricing Analysis
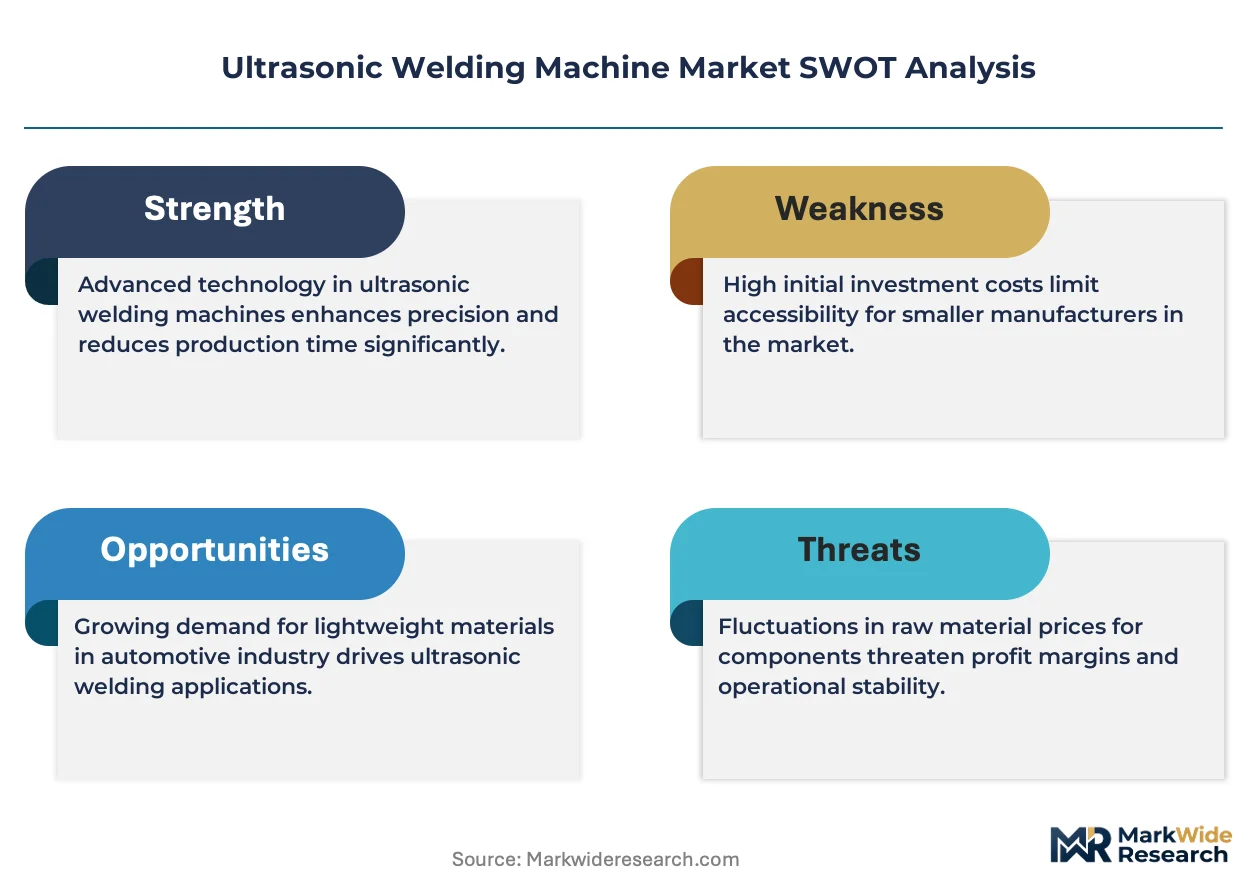
Next-generation 35-40 kHz digital control systems command substantial premiums over legacy 20 kHz analog platforms, while prior-generation equipment faces accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation support depth and generator architecture complexity. Price differentiation hinges on FDA 21 CFR Part 820 certification tier and volume scale, with medical device OEMs showing lowest price sensitivity and packaging converters highest. Cost compression in economy-tier analog systems is intensifying because Asian electronics assemblers are consolidating procurement around digitally traceable mid-tier alternatives.
Supply Chain Analysis
Inventory buffers at Japanese and German transducer manufacturers typically cover eight to twelve weeks of PZT ceramic consumption, though aerospace-grade titanium horn stockpiles concentrate with limited specialty suppliers in the United States and Russia. Raw material dependencies center on lead zirconate titanate ceramics, Grade 5 titanium billet, and high-purity aluminum for acoustic components. Single-source vulnerability in aerospace-grade titanium sourcing creates structural risk for high-precision system delivery schedules. Distribution runs through direct OEM relationships for automatic systems and regional distributor networks for handheld configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resistance welding substitution in cost-sensitive battery cell production threatens ultrasonic penetration in high-volume commodity segments, forcing incumbents to defend positioning through precision differentiation and regulatory compliance depth.
For Market Incumbents: Shield market position by deepening backward integration into piezoelectric ceramic supply and expanding validation-support capacity for compressed IQ/OQ/PQ timelines. Prioritize captive supply security for PZT transducer manufacturing to offset East Asian geographic concentration risk. Channel control through direct OEM relationships for automatic systems remains essential against emerging Asian competitors.
For New Entrants and Emerging Players: CDSCO certification fast-track under India's Medical Device Rules 2017 enables European market access for export-oriented contract manufacturers seeking MDR-compliant assembly equipment. Target handheld configuration demand among North American small enterprises in packaging and automotive aftermarket segments. Equipment-as-a-service financing models reduce upfront capex barriers for mid-volume medical device contract manufacturers in German and Swiss precision clusters.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EU MDR validation requirements are compressing equipment replacement cycles and elevating software-enabled process monitoring to baseline specification. Acquisition targets should emphasize precision system specialists with integrated transducer manufacturing and established validation-support infrastructure. The signal to watch is frequency migration acceleration in European EV battery module assembly specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PZT Ceramic Supply | Captive transducer manufacturing secures supply continuity against East Asian geographic concentration risk. |
| Digital Control Platform Migration | FDA 21 CFR Part 820 traceability mandates accelerate displacement of analog systems across cardiovascular assembly lines. |
| Equipment-as-a-Service Financing Launch | Subscription models reduce upfront capex barriers for emerging market entrants in German precision manufacturing clusters. |
| High-Frequency Generator Development | 35-40 kHz systems address thin-gauge copper welding specifications from European EV powertrain engineers. |
| Validation Support Capacity Expansion | IQ/OQ/PQ timeline compression under accelerated medical device launches strains incumbent field service networks. |
Study Parameters
Desk research of equipment specification databases, regulatory filing repositories, and trade flow records preceded structured interviews with ultrasonic welding equipment procurement managers at Tier-1 automotive suppliers, biomedical engineers at cardiovascular device manufacturers, and aftermarket service heads at precision fabrication facilities. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, and customs trade data enabled bottom-up and top-down triangulation across product type, application, technology, and end-user segments.
Variance decomposition across frequency tier, automation level, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from modeled unit shipments and average selling price trajectories incorporating generator technology migration, validation complexity premiums, and financing model adoption curves. Industry-specific forecast inputs included EV battery module assembly specifications and CDSCO regulatory alignment progress under India's Medical Device Rules 2017.
Underlying assumptions cover sustained electrification investment in European and North American automotive manufacturing, with deviation risk concentrated in titanium supply disruption and resistance welding technology advancement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Agitators Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Construction Pump Market
Construction Equipment
Welding Equipment Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Trenchers Market
Construction Equipment
Mini Cranes Market
Construction Equipment
India Crane Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Europe Welding Equipment Market