
 Global Cut and Bend Equipment Market | 2026-2036
Global Cut and Bend Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cut and Bend Equipment Market Intelligence
A shift in procurement preference from general contractors toward specialized structural fabricators is redrawing the competitive landscape for cut and bend equipment. Schnell S.p.A. leverages its extensive portfolio of automated systems to cater to high-volume fabrication facilities. In contrast, KRB Machinery specializes in robust, high-output machinery tailored for the North American precast industry. Eurobend S.A. positions itself with flexible, modular solutions adaptable to both small workshops and large construction sites.
Cut and bend equipment encompasses machinery designed to shear and shape steel reinforcement bars, commonly known as rebar, for concrete structures. These systems are engineered to process various rebar diameters, typically from 6mm to 50mm, ensuring compliance with structural engineering blueprints. Computer Numerical Control (CNC) technology leads the high-end segment, delivering superior accuracy and automation for complex shapes. Demand from large-scale infrastructure projects and commercial construction increasingly specifies CNC-processed rebar to meet tight project schedules.
Equipment safety and operator protection are governed by frameworks like OSHA regulations in the United States and the mandatory CE marking for machinery in Europe. In China, national GB standards for construction materials directly influence the specifications required for rebar processing equipment. The decision to invest in automated versus manual equipment hinges on the strategic balance between capital expenditure, regional labor costs, and project quality mandates.
Market Dynamics
The structural shift toward prefabrication and modular construction is the central force shaping the cut and bend equipment market. This industrialization of construction moves rebar processing off-site into controlled factory environments, elevating demand for automated, high-throughput systems over manual, on-site tools.
Growth Catalysts
- Public Infrastructure Investment:Government-led infrastructure programs, such as India's National Infrastructure Pipeline, create sustained demand for processed rebar, directly benefiting equipment manufacturers who supply to large-scale public works contractors.
- Prefabrication Adoption:The increasing use of prefabrication in commercial and residential construction requires precisely engineered rebar cages, a need met by advanced CNC-automated cut and bend systems that offer repeatability and speed.
- Stringent Building Codes:Modern seismic and structural building codes in regions like Japan and the United States mandate complex rebar shapes and tight tolerances, making automated processing equipment essential for compliance.
Market Restraints
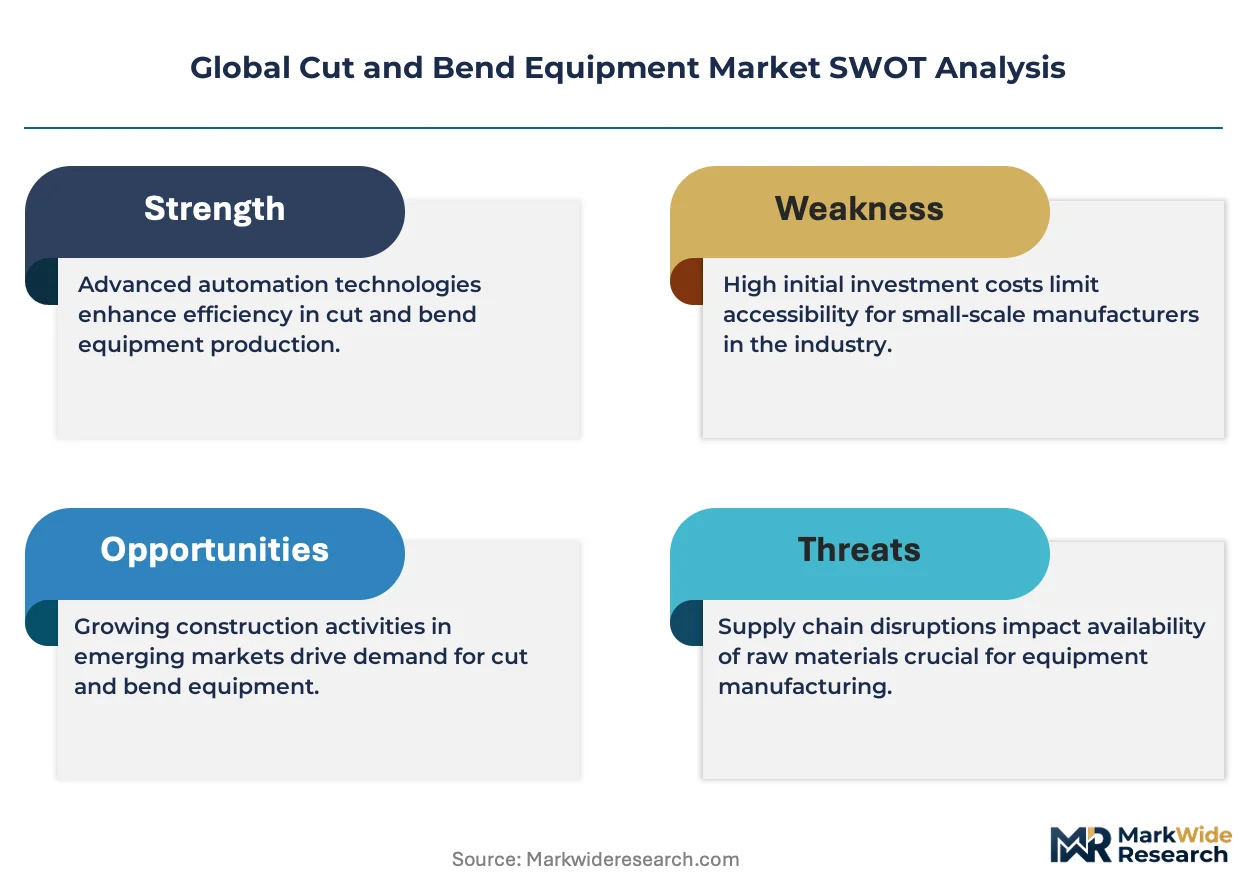
- High Capital Expenditure:The significant upfront investment required for automated CNC machinery presents a major barrier for small to medium-sized fabricators, slowing technology adoption in markets with constrained access to capital.
- Skilled Labor Scarcity:Operating and maintaining sophisticated CNC-based equipment requires trained technicians, and a shortage of this specialized labor can limit the operational efficiency and uptake of advanced systems.
- Manual Method Persistence:In regions with low labor costs, traditional manual or semi-automatic rebar processing methods remain economically viable for smaller projects, limiting the addressable market for fully automated solutions.
Strategic Opportunities
- BIM Integration:Developing software that allows for direct data transfer from Building Information Modeling (BIM) platforms to CNC machines offers a significant opportunity to streamline the fabrication workflow and reduce errors.
- Renewable Energy Sector:The construction of wind turbine foundations and solar farm infrastructure requires large volumes of standardized rebar, creating a new, high-growth application segment for specialized, high-capacity equipment.
- Emerging Market Penetration:Expanding into developing economies in Southeast Asia and Africa, where significant infrastructure development is planned, provides a new frontier for equipment sales and service contracts.
Industry Challenges
- Regulatory Compliance Variation:Manufacturers face complexity and cost in designing equipment that complies with disparate regional safety standards, such as Europe's CE marking and China's GB standards for machinery.
- Legacy System Integration:Fabricators often struggle to integrate new, automated cut and bend lines with their existing factory floor systems, creating operational bottlenecks and delaying return on investment.
- Supply Chain Vulnerability:The reliance on a concentrated pool of global suppliers for critical components like CNC controllers and servomotors exposes equipment manufacturers to potential disruptions and price volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cut and Bend Equipment Market |
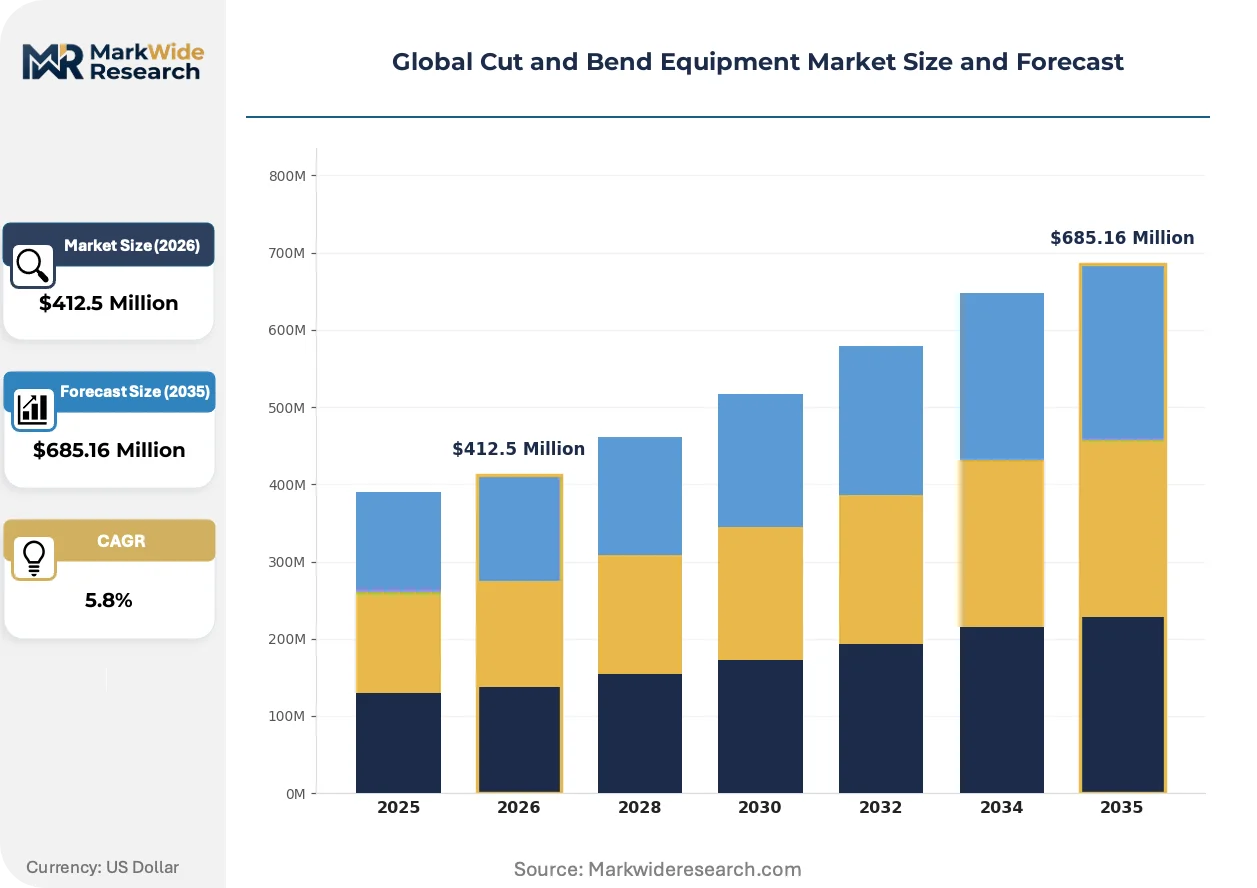
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutters, Hydraulic Benders, Electric Machines, Pneumatic Tools, Portable Units Technology: Computer Numerical Control, Electromechanical, Hydraulic, Pneumatic, Battery Powered Application: Infrastructure Projects, Commercial Construction, Residential Developments, Shipbuilding, Bridge Manufacturing End User: General Contractors, Structural Fabricators, Metal Workshops, Civil Engineers, Maintenance Providers |
| Companies Covered | Progress Holding AG, Toyo Kensetsu Kohki Co., Ltd., Eurobend S.A., PEDAX GmbH, KRB Machinery, Schnell S.p.A., TJK Machinery (Tianjin) Co., Ltd., SweBend AB, M.E.P. Macchine Elettroniche Piegatrici S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cut and Bend Equipment Market Strategic Shifts & Innovations
Automation and data connectivity are transforming rebar processing from a fragmented, manual trade into a precise, integrated manufacturing discipline. This evolution prioritizes production efficiency, material traceability, and seamless integration with digital construction workflows, defining the next generation of equipment.
Fully automated robotic handling systems are a key technological evolution. These systems manage the entire process from loading raw rebar stock onto the machine to unloading and stacking finished bent shapes or assembled cages. Large-scale structural fabricators and precast concrete producers are the primary adopters, seeking to maximize throughput. This level of automation is supplanting manual material handling, significantly reducing labor requirements and minimizing production cycle times.
Heightened focus on operator safety is driving equipment design, influenced by regulatory frameworks like OSHA in the United States. These regulations compel the integration of advanced safety features, including light curtains, two-hand controls, and fully enclosed processing areas to prevent accidents. Consequently, manufacturers are engineering these protective measures as standard components, particularly for machines targeting markets in North America and the European Union.
A fundamental change in project execution involves outsourcing rebar processing to specialized off-site facilities. Instead of cutting and bending rebar on the construction site, general contractors now frequently rely on dedicated fabricators who can deliver pre-assembled components just-in-time. This behavioral shift is most advanced in developed construction markets, fueling demand for centralized, high-output machinery capable of serving multiple projects simultaneously.
Global Cut and Bend Equipment Market Segmentation
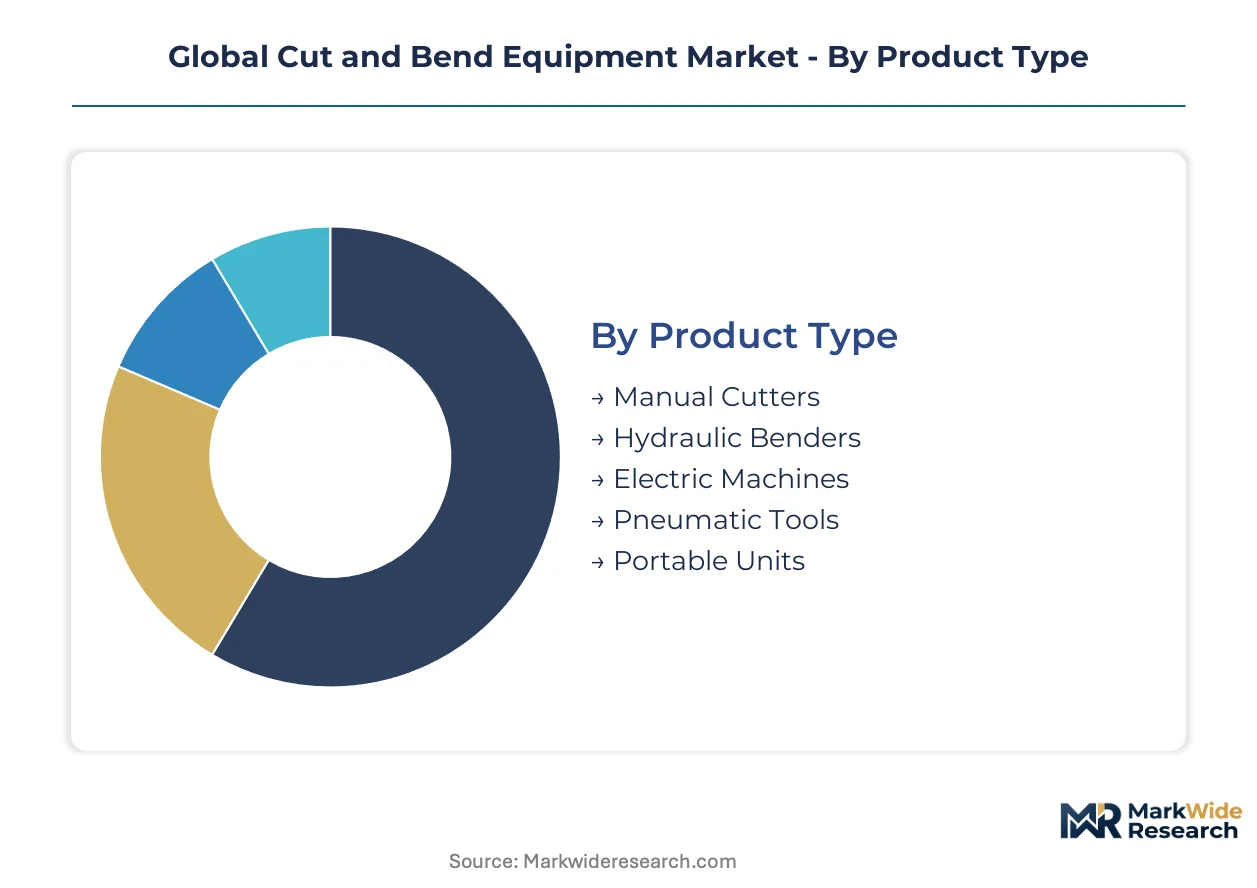
Segmentation within the cut and bend equipment market reveals the diverse technological requirements and operational scales across the construction industry. Understanding these distinct categories helps manufacturers align product development with specific end-user demands. The analysis identifies key areas of innovation and market concentration.
Product Type:
Margin pools within the product type segment are influenced by automation levels and specialized capabilities.
- Manual Cutters:Manual cutters are hand-operated tools for small-scale rebar cutting on diverse job sites.
- Hydraulic Benders:Hydraulic benders utilize fluid pressure to deliver high bending force, ideal for processing larger rebar diameters with precision. Commercial construction projects increasingly specify these machines to meet stringent structural requirements for complex building designs.
- Electric Machines:These units employ electric motors for cutting and bending rebar, offering a balance of power and efficiency for various construction tasks. Demand concentrates in India, driven by extensive public works and urban development initiatives requiring consistent rebar processing.
- Pneumatic Tools:Pneumatic tools use compressed air to power cutting or bending operations, finding use in specific industrial applications.
- Portable Units:Portable units offer flexibility for on-site rebar fabrication, favored by smaller contractors for their mobility.
The dominant share belongs to Electric Machines, while Portable Units are closing the gap fastest.
Technology:
Equipment costs within the technology segment vary significantly based on automation sophistication and power source.
- Computer Numerical Control:CNC technology automates rebar processing for superior accuracy and complex shapes, integrating directly with digital construction blueprints. Demand from large-scale infrastructure projects increasingly specifies CNC-processed rebar to meet tight project schedules and compliance.
- Electromechanical:Electromechanical systems combine electric motors with mechanical components for robust and reliable rebar cutting and bending. Commercial construction across Europe adopts these systems due to their operational efficiency and adaptability to various rebar types.
- Hydraulic:Hydraulic systems provide high force for bending larger rebar diameters, common in heavy civil engineering applications.
- Pneumatic:Pneumatic technology offers lightweight and responsive rebar processing solutions for specialized tasks in workshops.
- Battery Powered:Battery powered units provide cordless operation for enhanced mobility on remote or restricted construction sites.
The adoption of Computer Numerical Control technology is expanding most quickly due to stringent building codes and the shift towards prefabrication.
Application:
The volume of rebar processed dictates equipment requirements within each application segment.
- Infrastructure Projects:This segment involves large-scale public works like roads, railways, and utilities, requiring high-throughput, robust cut and bend equipment. Government-led infrastructure programs, such as India's National Infrastructure Pipeline, create sustained demand for processed rebar.
- Commercial Construction:Commercial construction encompasses office buildings, retail centers, and industrial facilities, demanding precise rebar fabrication for complex structural designs. The increasing use of prefabrication in these projects requires advanced CNC-automated cut and bend systems for repeatability.
- Residential Developments:Residential developments utilize cut and bend equipment for foundations and structural elements in housing projects.
- Shipbuilding:Shipbuilding employs specialized rebar processing for marine structures, requiring corrosion-resistant and precisely shaped components.
- Bridge Manufacturing:Bridge manufacturing necessitates high-capacity equipment for large-diameter rebar, ensuring structural integrity for heavy loads.
The Infrastructure Projects segment holds the largest share, driven by extensive government investments in public works globally.
End User:
Customer types within the end-user segment define the scale, automation needs, and service requirements for equipment.
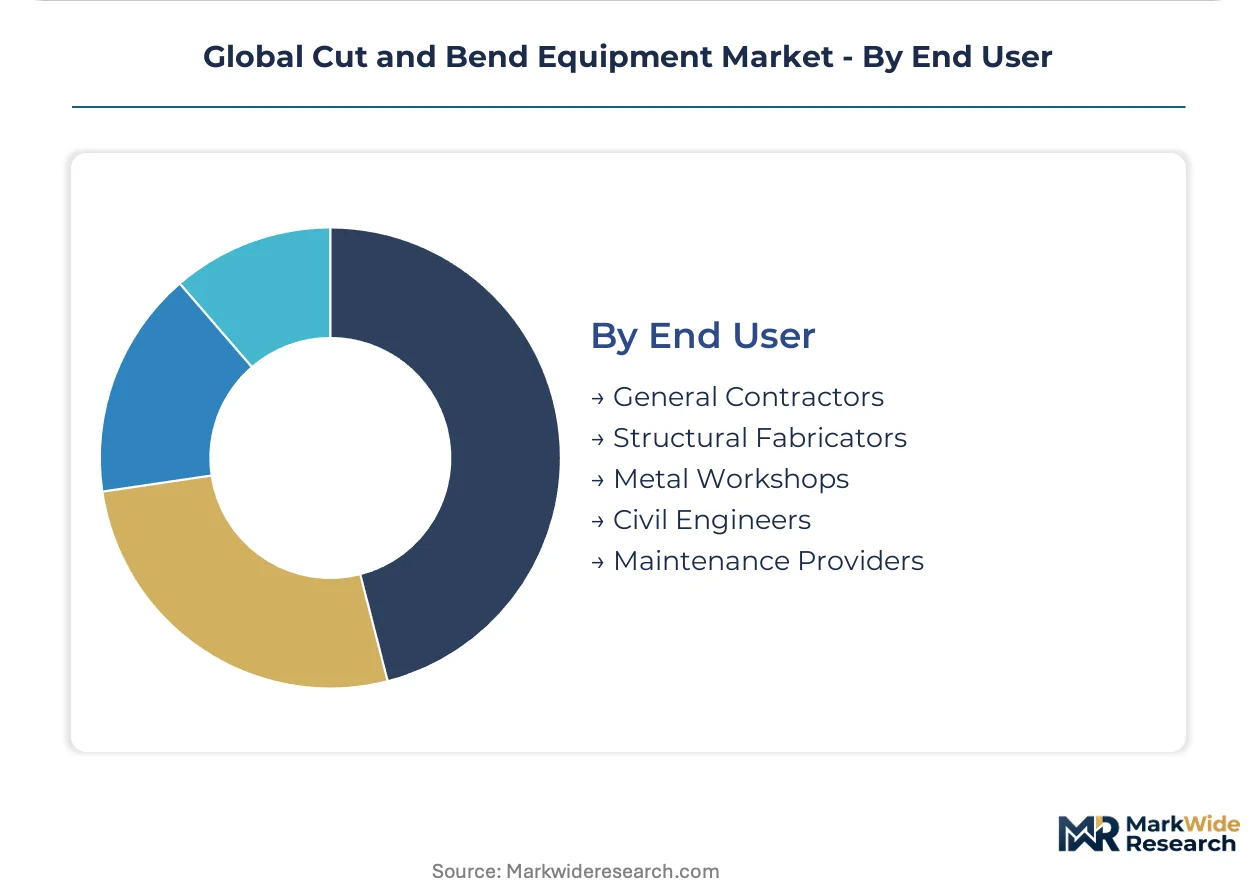
- General Contractors:General contractors manage overall construction projects, often requiring versatile equipment for on-site rebar processing or integration with prefabricated solutions. The decision to invest in automated versus manual equipment hinges on regional labor costs and project quality mandates.
- Structural Fabricators:These specialized entities process rebar off-site in controlled factory environments, demanding automated, high-throughput systems for efficiency. A shift in procurement preference from general contractors towards these fabricators is redrawing the competitive landscape for equipment.
- Metal Workshops:Metal workshops use cut and bend equipment for smaller, custom rebar jobs and specialized metalworking tasks.
- Civil Engineers:Civil engineers influence equipment selection through design specifications and compliance with structural engineering blueprints.
- Maintenance Providers:Maintenance providers utilize rebar equipment for repairs and retrofitting existing concrete structures.
The increasing specialization of Structural Fabricators is influencing equipment demand significantly, favoring advanced automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's extensive National Infrastructure Pipeline underpins significant demand for cut and bend equipment. This ambitious program drives investment in roads, railways, and urban development projects. Such large-scale public works necessitate high-throughput rebar processing machinery.
India
Public infrastructure programs and rapid urbanization fuel demand for rebar processing equipment in India. The PLI scheme supports domestic manufacturing, indirectly boosting demand for construction machinery. Major urban centers like Delhi-NCR concentrate extensive residential and commercial development, requiring efficient rebar fabrication.
United States
The Bipartisan Infrastructure Law stimulates substantial demand for advanced rebar equipment across the United States. OSHA regulations mandate strict safety features on all machinery, influencing equipment design. Key construction hubs such as Texas and Florida experience continuous growth in commercial and residential projects, driving equipment procurement.
Germany
High standards for structural integrity in commercial buildings and civil engineering projects drive demand for precision rebar processing in Germany. The mandatory CE marking ensures compliance with European safety, health, and environmental protection requirements for machinery. Bavarian industrial clusters specialize in advanced manufacturing, fostering innovation in automated rebar systems.
China
Extensive urban development and large-scale transportation networks generate immense demand for cut and bend equipment across China. National GB standards for construction materials directly influence the specifications required for rebar processing equipment. The Yangtze River Delta region, a major economic zone, sees continuous investment in high-rise construction and industrial facilities.
Global Cut and Bend Equipment Market Key Industry Players
Concentration sits with specialized manufacturers offering high-automation solutions for large-scale fabricators. The market structure exhibits a tiered landscape, with global players dominating the high-end automated segment and regional vendors serving more localized needs. Strategic archetypes include automated system integrators, robust machinery specialists, and flexible modular solution providers. Companies pursue geographic expansion and portfolio diversification to capture market share across diverse construction sectors.
Within the automated systems segment, Italy-based Schnell S.p.A. exemplifies a company focused on extensive portfolios for high-volume fabrication facilities, catering to industrial-scale rebar processing. US-based KRB Machinery represents specialists in robust, high-output machinery, particularly tailored for the demanding North American precast industry requirements. Eurobend S.A., a Greece-based entity, occupies a position with flexible, modular solutions adaptable to both small workshops and large construction sites, reflecting a versatile market approach. These companies anchor different facets of the market's evolving demand for specialized and efficient rebar processing technology.
| Leading Market Players |
|---|
| Progress Holding AG |
| Toyo Kensetsu Kohki Co., Ltd. |
| Eurobend S.A. |
| PEDAX GmbH |
| KRB Machinery |
| Schnell S.p.A. |
| TJK Machinery (Tianjin) Co., Ltd. |
| SweBend AB |
| M.E.P. Macchine Elettroniche Piegatrici S.p.A. |
| Others |
Cost & Logistics Intelligence
CE marking requirements for machinery gate both equipment supply qualification and price differentiation across European markets. This regulatory framework ensures product quality and safety, influencing manufacturer investment in compliance and subsequently impacting pricing strategies.
Pricing Analysis
Volume-based discount structures characterize pricing across the cut and bend equipment market. Price differentiation stems from automation levels and specialized capabilities, particularly for high-end CNC systems. Pricing softness runs through manual equipment due to regional labor cost variations. Structural fabricators, requiring high-throughput automated systems, exhibit lower price sensitivity compared to smaller metal workshops.
Supply Chain Analysis
The reliance on a concentrated pool of global suppliers for critical components like CNC controllers and servomotors underwrites potential supply chokepoints. Key manufacturing hubs in Germany, Italy, and China produce core machinery. Equipment manufacturers draw from specialized component suppliers across Europe and Asia. Single-source vulnerability for advanced electronic components represents a structural risk. Distribution runs through a network of regional dealers and direct sales channels to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cut and bend equipment market presents a defensive moat, primarily due to high capital expenditure for advanced automated systems and specialized labor requirements.
For Market Incumbents:Shield core market share by investing in advanced automation R&D for next-generation CNC systems. Consolidate regional service networks to maintain customer loyalty against emerging competitors. Address the skilled labor scarcity threat by offering comprehensive training programs for operator proficiency. Deepen vertical integration into critical component manufacturing to mitigate supply chain vulnerabilities.
For New Entrants and Emerging Players:Accelerated CE marking pathways for modular equipment offer new entrants a strategic entry point. Target underpenetrated developing economies in Southeast Asia with flexible, scalable solutions. Focus on developing software for BIM integration as a distinct go-to-market angle. The residential developments segment in emerging markets represents the most penetrable application for new entrants.
For Investors and Strategic Acquirers:The Bipartisan Infrastructure Law reshapes the acquisition landscape, favoring companies with proven high-throughput solutions. Long-term viability over a 5-10 year window favors specialized structural fabricators with strong automation capabilities. Acquisition targets should possess robust intellectual property in CNC technology or a strong presence in emerging markets. Watch for increased government funding allocations for infrastructure projects as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand CNC System Portfolio | Enhances precision and automation for complex rebar shapes, meeting stringent building codes. |
| Invest in Robotic Handling | Reduces labor requirements and optimizes production cycle times for high-volume facilities. |
| Develop BIM Integration Software | Streamlines fabrication workflows by enabling direct data transfer from digital blueprints. |
| Target Southeast Asian Markets | Captures new growth opportunities driven by extensive planned infrastructure development. |
| Strengthen After-Sales Service | Ensures operational continuity for sophisticated machinery, building customer trust and retention. |
Research Approach
Desk research of industry reports, government publications, and company filings preceded structured interviews with equipment manufacturers, structural fabricators, and civil engineers. This approach combined primary insights from industry stakeholders with secondary validation from publicly available data. Bottom-up and top-down triangulation ensured comprehensive market sizing and forecast accuracy.
Variance decomposition techniques were applied to analyze market growth drivers and restraints over the projection horizon. The analytical framework modeled market segmentation across product type, technology, application, end-user, and regional construction spending. Compound annual growth rates were derived from historical data trends and anticipated future demand for processed rebar, incorporating infrastructure investment plans.
Decision-makers should treat outputs as directional under current regulatory stability and material supply chain conditions; significant deviation would warrant model refresh. Forecasts reflect assumptions regarding global economic stability and continued infrastructure investment. Practitioners should keep alternative scenarios live as government spending priorities and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Jackhammer Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Welding Equipment and Consumables Market