
 UK Factoring Services Market | 2026-2036
UK Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK Factoring Services Market Insights
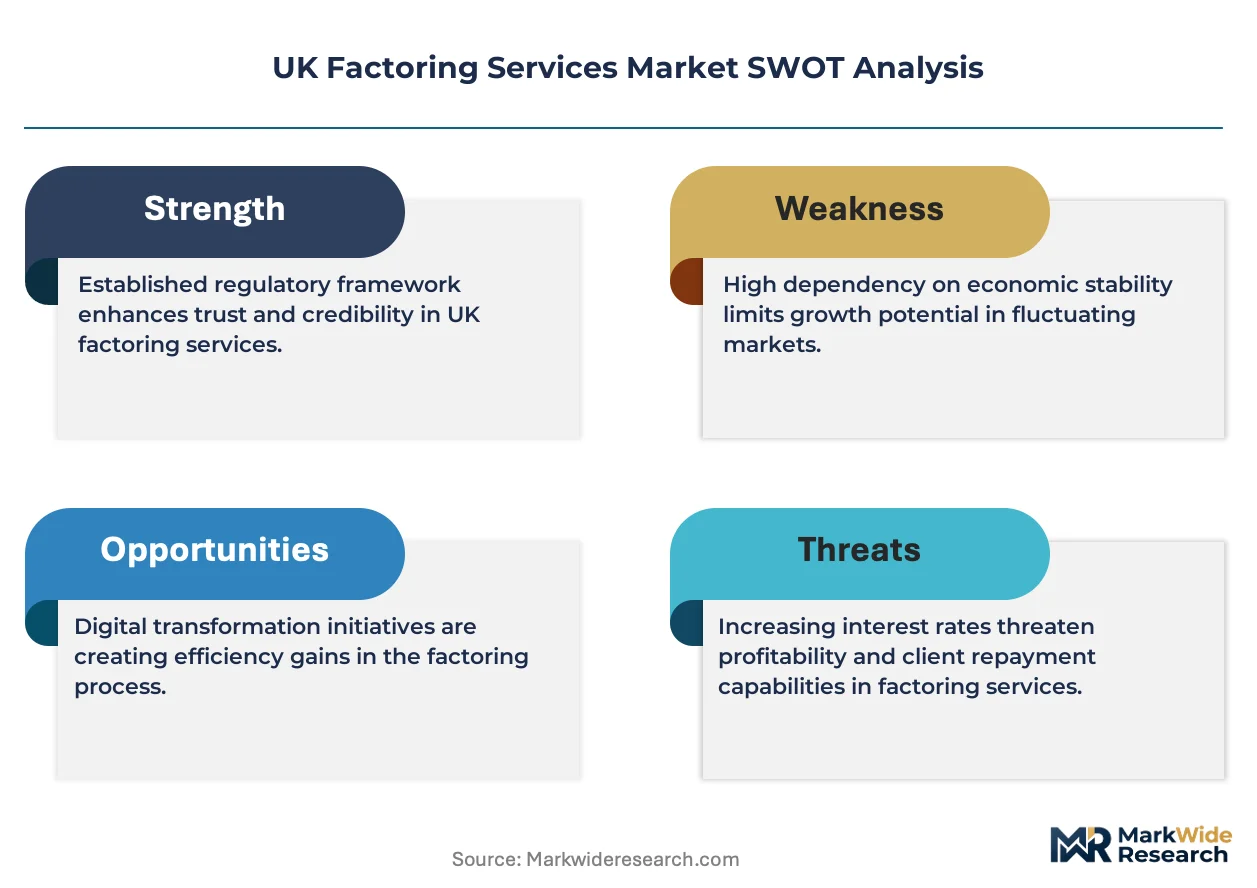
Asset-light lending models is narrowing the capital barrier for non-bank entrants to compete against established invoice finance providers. Close Brothers Invoice Finance leverages its long-standing broker relationships to sustain high client retention in traditional manufacturing verticals. Bibby Financial Services anchors its position through specialist sector teams serving construction and transport operators. Kriya competes by embedding automated credit decisions directly into accounting software workflows.
UK factoring services constitute a form of receivables finance where a business sells its unpaid invoices to a third-party provider at a discount, typically advancing 70-90% of invoice value within 24-48 hours while assuming collection responsibility. The mechanism accelerates cash conversion cycles for businesses facing extended payment terms from corporate buyers. Recourse factoring dominates transaction volumes among established SMEs with predictable debtor books, while non-recourse factoring commands premium pricing by transferring default risk to the factor. Invoice discounting grows fastest among mid-market enterprises seeking confidential arrangements that preserve direct customer relationships.
The Prudential Regulation Authority and Financial Conduct Authority jointly govern capital adequacy and conduct standards for UK invoice finance providers, with the FCA's Consumer Duty rules now extending to smaller business borrowers. The Bank of England's Term Funding Scheme shapes liquidity availability and pricing floors across the sector. Stakeholders must monitor how Basel III implementation affects bank-affiliated factors' risk-weighting calculations relative to independent platforms.
Market Dynamics
Open Banking APIs and real-time credit scoring are compressing underwriting timelines from weeks to hours, forcing traditional invoice finance providers to rebuild their technology stacks or cede mid-market share to automated platforms.
Growth Catalysts
- FCA Consumer Duty rules:The Financial Conduct Authority's expanded conduct standards for SME borrowers are legitimizing invoice finance as a regulated credit product, reducing stigma among risk-averse manufacturing finance directors.
- Construction sector payment delays:UK government mandates on public project retentions have lengthened cash conversion cycles for subcontractors, driving demand for non-recourse factoring against verified government receivables.
- London fintech clustering:Proximity to institutional funding sources in the Square Mile enables platforms to secure warehouse credit lines at competitive rates, lowering advance pricing for end-users.
Market Restraints
- Basel III risk-weighting:Bank-affiliated factors face elevated capital charges for SME receivables, constraining balance sheet capacity relative to independent platforms with alternative funding structures.
- Debtor concentration limits:Single-name exposure caps prevent factors from fully serving clients dependent on dominant corporate buyers, particularly in automotive and retail supply chains.
- Manual verification costs:Paper-based invoice authentication for construction and transport sectors requires specialist underwriters, inflating operational expense ratios versus automated SaaS models.
Strategic Opportunities
- Midlands manufacturing corridor:West Midlands and East Midlands SMEs show lower invoice finance penetration than London peers despite comparable working capital pressures, presenting geographic whitespace.
- Embedded finance integration:API partnerships with accounting software providers enable factors to surface advance offers at invoice creation, intercepting demand before borrowers seek standalone credit.
- Bank of England liquidity facilities:Term Funding Scheme extensions provide cheaper wholesale funding for platforms with robust credit models, compressing net interest margins for bank competitors.
Industry Challenges
- Credit analyst scarcity:Specialist underwriters capable of assessing construction retention risk and transport operator fleet quality command premium compensation, constraining platform scaling.
- Legacy system integration:Mid-market enterprises operating on-premises ERP systems require bespoke API development for automated invoice submission, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Factoring Services Market |
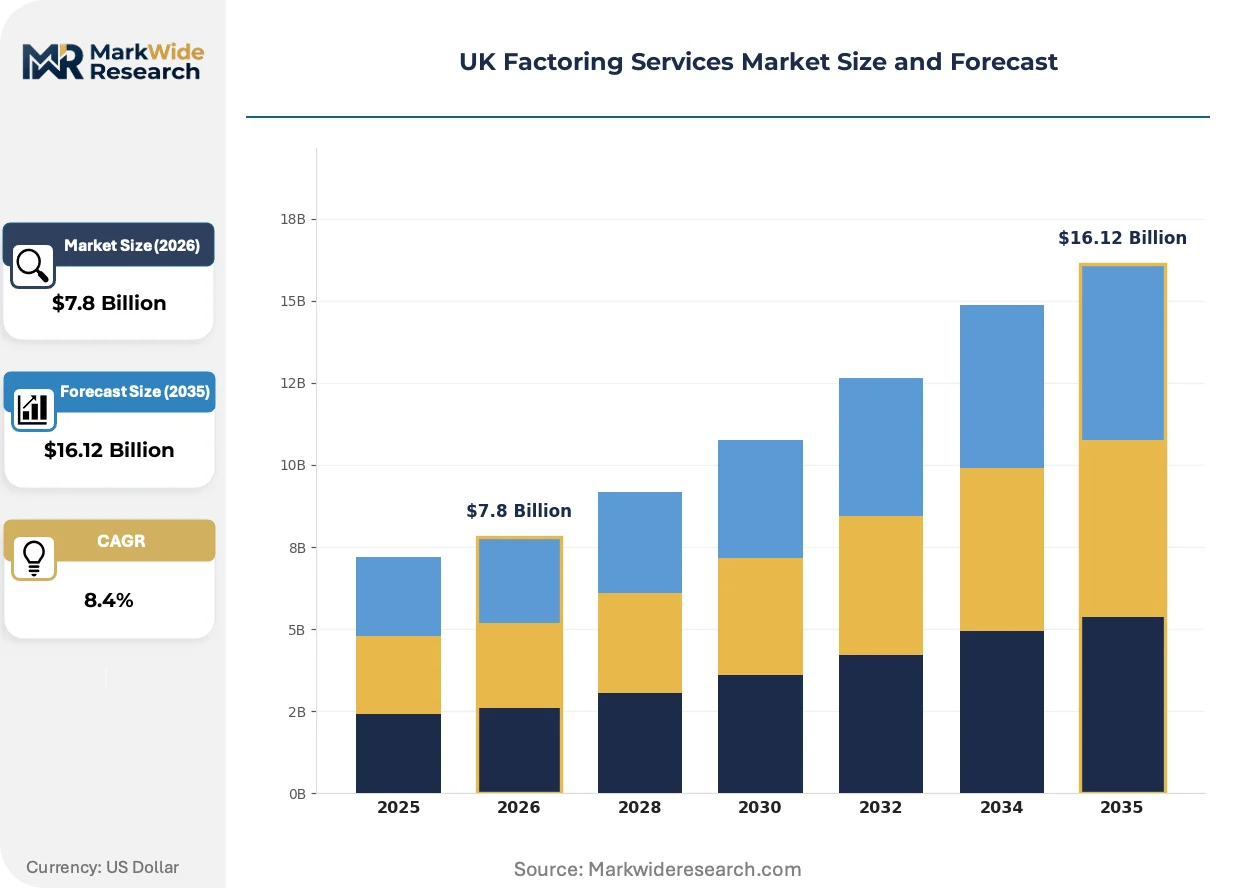
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Spot Factoring, Maturity Factoring Client Type: SMEs, Large Enterprises, Startups, Exporters, Wholesalers Industry Vertical: Manufacturing, Construction, Information Technology, Wholesale Trade, Transportation Investment Strategy: Short-Term Financing, Growth Funding, Working Capital Management, Cash Flow Optimization, Risk Mitigation |
| Companies Covered | Close Brothers Invoice Finance, eCapital Factoring, Bibby Financial Services, Metro Bank SME Finance, Hitachi Capital Invoice Finance, RBS Invoice Finance, Kriya (formerly Market Invoice), Barclays Invoice Finance, Skipton Business Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Factoring Services Market Trends and Innovations
Technology convergence between Open Banking data feeds and machine learning credit models is eliminating traditional reliance on historical financial statements, enabling real-time underwriting decisions against live transaction patterns.
Automated credit decisioning is migrating from rule-based scoring engines to machine learning models trained on Open Banking transaction histories. Mid-market manufacturing enterprises with thin credit files are adopting these platforms fastest. This migration is compressing the competitive window for factors dependent on manual underwriting, forcing incumbents to acquire or partner with technology vendors.
The Financial Conduct Authority's Consumer Duty rules now extend conduct standards to smaller business borrowers, requiring factors to demonstrate fair value and avoid foreseeable harm. Providers must redesign disclosure documents and complaint handling procedures. The construction and transport sectors, with historically complex fee structures, face the steepest compliance adjustment.
Buyer-led supply chain finance programs are displacing supplier-initiated factoring arrangements among large corporate purchasers. Procurement teams at major retailers and infrastructure contractors now mandate reverse factoring through designated platforms. This shift concentrates volume with platform providers holding approved supplier status, marginalizing independent factors lacking corporate treasury relationships.
UK Factoring Services Market Segmentation
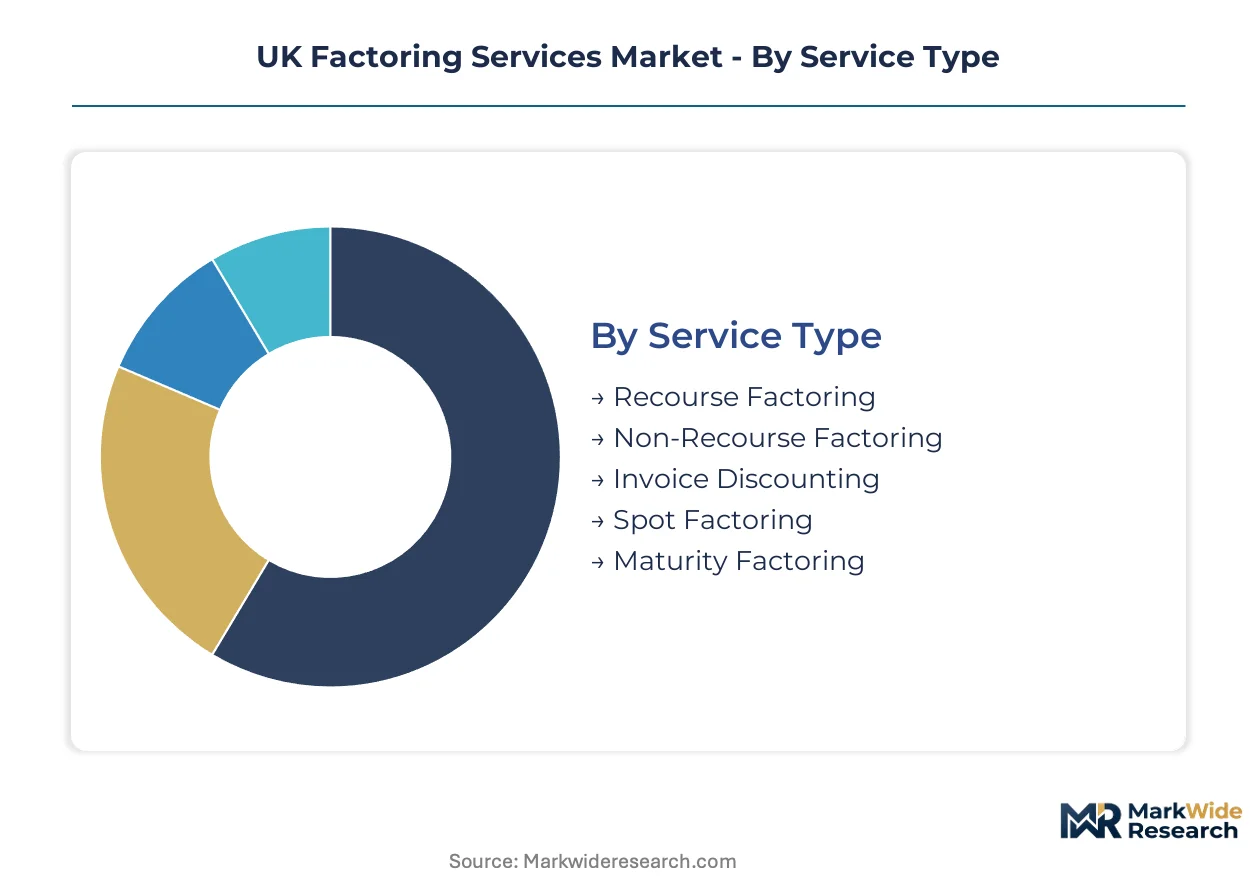
Segmentation in UK factoring services reveals how providers align risk structures with borrower cash conversion cycles and sector-specific payment patterns. Each dimension—service type, client profile, industry exposure, and strategic intent—determines advance rates, fee structures, and collection protocols.
Service Type:
Cost tier determines risk transfer mechanics and pricing premiums across the UK factoring landscape.
- Recourse Factoring:The borrower retains default risk if debtors fail to pay, enabling factors to offer lower discount rates. Manufacturing SMEs in the West Midlands favor this structure for predictable debtor books with established corporate buyers.
- Non-Recourse Factoring:The factor assumes credit risk, commanding premium pricing of 1-3 percentage points above recourse alternatives. Construction subcontractors facing public sector retentions increasingly select this option to isolate balance sheet risk from government payment delays.
- Invoice Discounting:Confidential arrangements preserve direct customer relationships, attracting mid-market enterprises seeking working capital without signaling financial stress to trade partners.
- Spot Factoring:Single-invoice transactions serve episodic liquidity needs without contractual minimums, appealing to project-based businesses with lumpy revenue streams.
- Maturity Factoring:The factor pays invoice face value on due date rather than advancing funds, functioning as credit insurance and collection service rather than financing.
Recourse structures hold installed capacity. Non-recourse arrangements are rotating up the share rankings.
Client Type:
Customer scale shapes underwriting automation potential and relationship management intensity.
- SMEs:Businesses with annual turnover below £25 million constitute the volume base, with Open Banking-enabled platforms capturing share from traditional providers through sub-24-hour approval timelines.
- Large Enterprises:Multi-million pound facility requirements demand bespoke structuring, with factors competing on covenant flexibility and cross-border capabilities for FTSE-listed supply chain participants.
- Startups:Thin credit files and limited trading history restrict access to recourse-only products, though revenue-based underwriting models are expanding eligibility for SaaS and fintech ventures.
- Exporters:Cross-border receivables require currency hedging and political risk assessment, with factors leveraging London's trade finance infrastructure to serve EU and Commonwealth trade corridors.
- Wholesalers:Seasonal inventory cycles and concentrated buyer bases necessitate flexible facility sizing, with peak advance periods aligned to pre-holiday stock build.
SMEs anchor facility volumes. Exporters are climbing the fastest as post-Brexit trade finance demand intensifies.
Industry Vertical:
Application-specific payment terms and documentation requirements segment risk assessment methodologies.
- Manufacturing:Standardized invoices and predictable production cycles enable high automation, with Midlands engineering firms driving adoption of API-integrated invoice submission.
- Construction:Retention clauses, stage payment certificates, and contractual disputes demand specialist underwriters, inflating operational costs but supporting premium pricing for verified public sector receivables.
- Information Technology:Recurring subscription revenue and milestone-based contracting create non-traditional receivable profiles, requiring factors to adapt eligibility criteria beyond conventional invoice structures.
- Wholesale Trade:High invoice frequency and established buyer relationships support scalable automated processing, with East Midlands distribution centers showing penetration gaps versus London peers.
- Transportation:Fleet asset quality and driver subcontractor arrangements complicate credit assessment, with factors specializing in haulage maintaining dedicated sector teams.
Manufacturing holds installed capacity. Information Technology is gaining share fastest as recurring revenue models reshape receivable definitions.
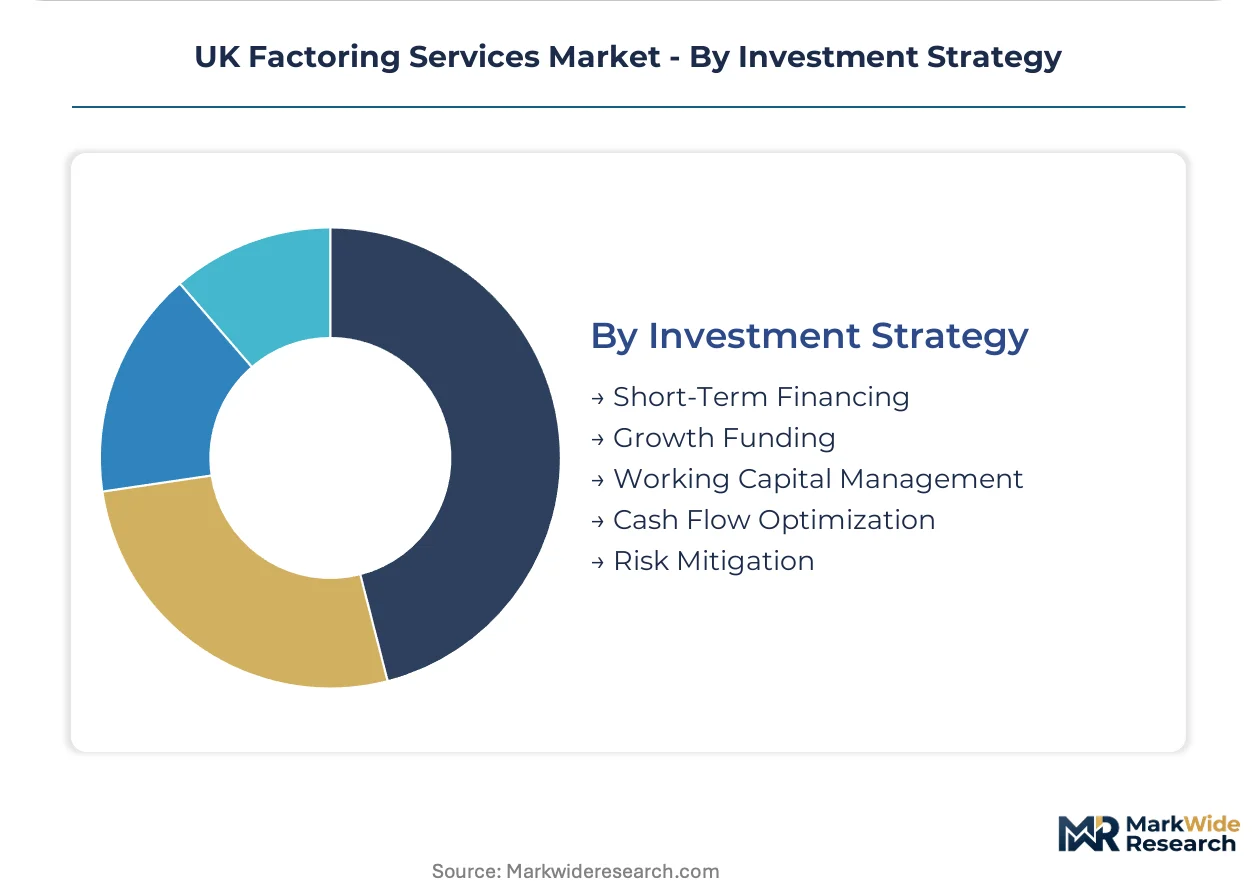
Investment Strategy:
Strategic intent determines facility structure, tenor preferences, and ancillary service bundling.
- Short-Term Financing:Bridge facilities spanning 30-90 days address seasonal tax liabilities or contract mobilization costs, with construction firms utilizing these for VAT payment timing.
- Growth Funding:Scalable facilities linked to invoice volume expansion support working capital investment without equity dilution, preferred by mid-market manufacturers pursuing contract wins.
- Working Capital Management:Systematic deployment of invoice finance as core treasury function, with finance directors integrating advance availability into cash flow forecasting.
- Cash Flow Optimization:Specific targeting of payment gap compression, with exporters leveraging factoring to neutralize extended buyer terms in international trade.
- Risk Mitigation:Non-recourse structures and credit insurance bundling protect against buyer default, particularly valued by suppliers to concentrated retail and automotive chains.
Working capital management holds installed capacity. Growth funding is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bank of England's Term Funding Scheme and FCA Consumer Duty rules are reshaping capital availability and conduct standards across UK invoice finance markets, concentrating platform development near institutional liquidity sources while extending regulatory legitimacy to previously underserved borrower segments.
London and the South East
Open Banking-enabled platforms cluster within the Square Mile to secure warehouse credit lines at competitive rates. The Prudential Regulation Authority's capital adequacy frameworks govern bank-affiliated factors operating from Canary Wharf and the City. Fintech innovators in Shoreditch and Clerkenwell embed automated credit decisions into accounting software workflows, intercepting SME demand before traditional broker relationships activate.
West Midlands
Manufacturing SMEs across Birmingham and Coventry exhibit lower invoice finance penetration than London peers despite comparable working capital pressures. Engineering firms with established corporate buyer relationships favor recourse factoring for predictable debtor books. The region's automotive supply chains face single-name exposure caps that prevent factors from fully serving clients dependent on dominant OEM buyers.
East Midlands
Distribution centers in Nottingham and Leicester show penetration gaps versus London counterparts for wholesale trade invoice processing. High invoice frequency and established buyer relationships support scalable automated processing potential. The FCA's expanded conduct standards for SME borrowers are reducing stigma among risk-averse manufacturing finance directors in Derbyshire and Leicestershire.
North England
Construction subcontractors across Manchester and Leeds increasingly select non-recourse factoring to isolate balance sheet risk from government payment delays. Public project retention mandates have lengthened cash conversion cycles for infrastructure suppliers. Specialist underwriters capable of assessing retention risk and stage payment certificates command premium compensation, constraining platform scaling in the region.
Scotland
Edinburgh's financial services heritage supports invoice finance broker networks serving Aberdeen's oilfield services sector and Glasgow's transport operators. Fleet asset quality and driver subcontractor arrangements complicate credit assessment for haulage specialists. The Scottish Government's procurement frameworks influence payment term structures for public sector suppliers seeking receivables finance.
UK Factoring Services Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct competitive tiers: bank-affiliated factors with balance sheet scale, independent specialists with sector-specific underwriting expertise, and technology-native platforms with automated origination capabilities. Strategic archetypes include relationship-driven incumbents leveraging long-standing broker networks, sector-focused providers deploying dedicated construction and transport teams, and API-integrated fintechs embedding finance into accounting workflows. Dominant competitive moves encompass technology stack modernization to compress underwriting timelines and geographic expansion into underpenetrated Midlands manufacturing corridors.
Among established independent specialists, Bibby Financial Services anchors the sector-focused archetype through dedicated teams serving construction and transport verticals. Close Brothers Invoice Finance exemplifies the relationship-driven model, sustaining client retention through broker network density in traditional manufacturing segments. Kriya occupies the technology-native position, competing via automated credit decisions embedded directly into cloud accounting software workflows.
| Leading Market Players |
|---|
| Close Brothers Invoice Finance |
| eCapital Factoring |
| Bibby Financial Services |
| Metro Bank SME Finance |
| Hitachi Capital Invoice Finance |
| RBS Invoice Finance |
| Kriya (formerly Market Invoice) |
| Barclays Invoice Finance |
| Skipton Business Finance |
| Others |
Pricing and Supply Chain Analysis
London's Square Mile fintech clustering concentrates warehouse credit line access for invoice finance platforms, translating institutional liquidity abundance into competitive advance rate pricing for end-user SMEs across the UK manufacturing corridor.
Pricing Analysis
Advance rate tiers create the primary spread between recourse and non-recourse structures, with factors pricing risk transfer at 1-3 percentage point premiums for credit protection. Fee differentiation rests on facility size and debtor concentration metrics, with mid-market enterprises commanding tighter spreads than micro-SMEs. Cost compression in automated origination is intensifying because Open Banking-enabled platforms undercut manual underwriting overhead. Micro-SMEs with thin credit files exhibit highest price sensitivity, while FTSE-listed supply chain participants prioritize covenant flexibility over rate minimization.
Supply Chain Analysis
Upstream funding feeds from UK institutional investors, European asset managers, and US private credit funds seeking yield in sterling-denominated working capital assets. Warehouse credit facilities, securitization conduits, and balance sheet deployment constitute the core funding stack. Single-source vulnerability concentrates in bank-affiliated factors facing Basel III risk-weighting constraints. Distribution runs through broker networks, direct platform onboarding, and embedded API partnerships with accounting software providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open Banking API proliferation has compressed underwriting timelines from weeks to hours, creating a regulatory-technology inflection that rewards platforms with real-time credit decisioning infrastructure.
For Market Incumbents: Insulate core manufacturing relationships by embedding automated invoice submission into legacy client ERP systems, neutralizing the threat of API-native platforms poaching mid-market accounts. Deepen sector specialization in construction retention risk and transport fleet underwriting to defend pricing power against SaaS competitors. Prioritize broker network digitization to preserve origination velocity.
For New Entrants and Emerging Players: Establish a beachhead in the West Midlands manufacturing corridor, where invoice finance penetration lags London despite comparable working capital pressures. Target engineering firms with established automotive OEM relationships currently underserved due to single-name exposure caps constraining incumbent capacity. Deploy Open Banking-integrated onboarding to compress approval timelines below 24 hours.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with proprietary machine learning credit models trained on transaction-level data rather than rule-based scoring engines. Five-to-ten year viability hinges on embedded finance integration depth and accounting software API exclusivity. Monitor FCA Consumer Duty enforcement intensity as the signal indicating whether regulatory compliance becomes a scale barrier favoring well-capitalized incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Stack Modernization | Rebuilds legacy underwriting infrastructure to match Open Banking-enabled competitor approval speeds. |
| Sector Specialist Team Expansion | Deploys dedicated construction and transport underwriters to capture premium-priced non-recourse demand. |
| Embedded Finance API Partnership | Integrates advance offers directly into Sage and Xero workflows to intercept demand pre-search. |
| Midlands Geographic Expansion | Establishes origination presence in underpenetrated West Midlands manufacturing clusters. |
| Alternative Funding Structure Development | Secures warehouse credit lines from institutional investors to circumvent Basel III bank capital constraints. |
Research Methodology
A standing panel of invoice finance relationship managers, SME finance directors, Open Banking platform engineers, and FCA supervisory staff provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against Bank of England Term Funding Scheme disclosures, FCA Consumer Duty implementation guidance, and Companies House filing data. Bottom-up facility volume analysis triangulated against top-down sectoral working capital estimates derived from ONS manufacturing and construction surveys.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying Open Banking adoption speeds and regulatory enforcement intensities. Segmentation dimensions encompassed service type, client scale tier, industry vertical exposure, and funding source structure. CAGRs were derived from trend extrapolation adjusted for technology diffusion curves and capital availability cycles. Forecast inputs incorporated real-time credit decisioning penetration rates and embedded finance API integration milestones.
Sensitivities concentrate around Bank of England liquidity facility extensions, FCA Consumer Duty enforcement calibration, and Open Banking transaction data access pricing. Forecasts reflect documented assumptions regarding technology adoption timelines and regulatory stability. Material shifts in Basel III implementation for SME receivables risk-weighting would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Student Loan Market
Loans and Leasing
Unsecured Business Loans Market