
 Alternative Lending Market | 2026-2036
Alternative Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Lending Market Analysis
The EU AI Act is hardening compliance requirements for automated credit decisions across European platforms. LendingClub leverages machine learning models to assess borrower risk beyond FICO scores. Funding Circle anchors its position in small-business term loans across the United Kingdom and United States. Prosper Marketplace competes through fixed-rate personal loans with transparent fee structures.
Alternative lending encompasses non-bank credit origination through digital platforms, utilizing alternative data streams such as cash flow patterns, social signals, and behavioral analytics to supplement or replace traditional credit bureau scoring. The primary commercial purpose is extending capital to borrowers underserved by conventional banking infrastructure, including thin-file consumers and early-stage enterprises. P2P lending sustains the largest transaction volume pool as institutional capital displaces retail participation on major platforms. Invoice financing captures expanding margin opportunity by converting accounts receivable into immediate liquidity for B2B suppliers. Crowdfunding occupies a specialized niche where community validation and pre-sales reduce default risk for creative and social ventures.
The Consumer Financial Protection Bureau in the United States, the Financial Conduct Authority in the United Kingdom, and the Securities and Exchange Commission collectively shape disclosure standards, interest rate caps, and investor protection rules that determine platform operating economics. The EU AI Act introduces specific obligations for automated lending decisions, requiring human oversight and bias auditing that will elevate compliance costs for algorithmic underwriting. Stakeholders must monitor how jurisdictional fragmentation in data privacy and credit reporting standards affects cross-border platform scalability and capital sourcing flexibility.
Market Dynamics
Open banking infrastructure and algorithmic underwriting are compressing origination timelines from weeks to hours, fundamentally restructuring how capital reaches borrowers outside traditional banking channels.
Growth Catalysts
- EU AI Act compliance frameworks:Automated credit decision platforms in Europe are deploying human-in-the-loop architectures that expand addressable borrower pools while meeting regulatory thresholds for explainable lending.
- Cash flow analytics integration:Real-time transaction data from accounting software and payment processors is absorbing thin-file small businesses previously excluded from FICO-based scoring.
- Invoice financing automation:B2B suppliers across manufacturing and logistics verticals are converting accounts receivable into immediate liquidity through API-linked platforms.
Market Restraints
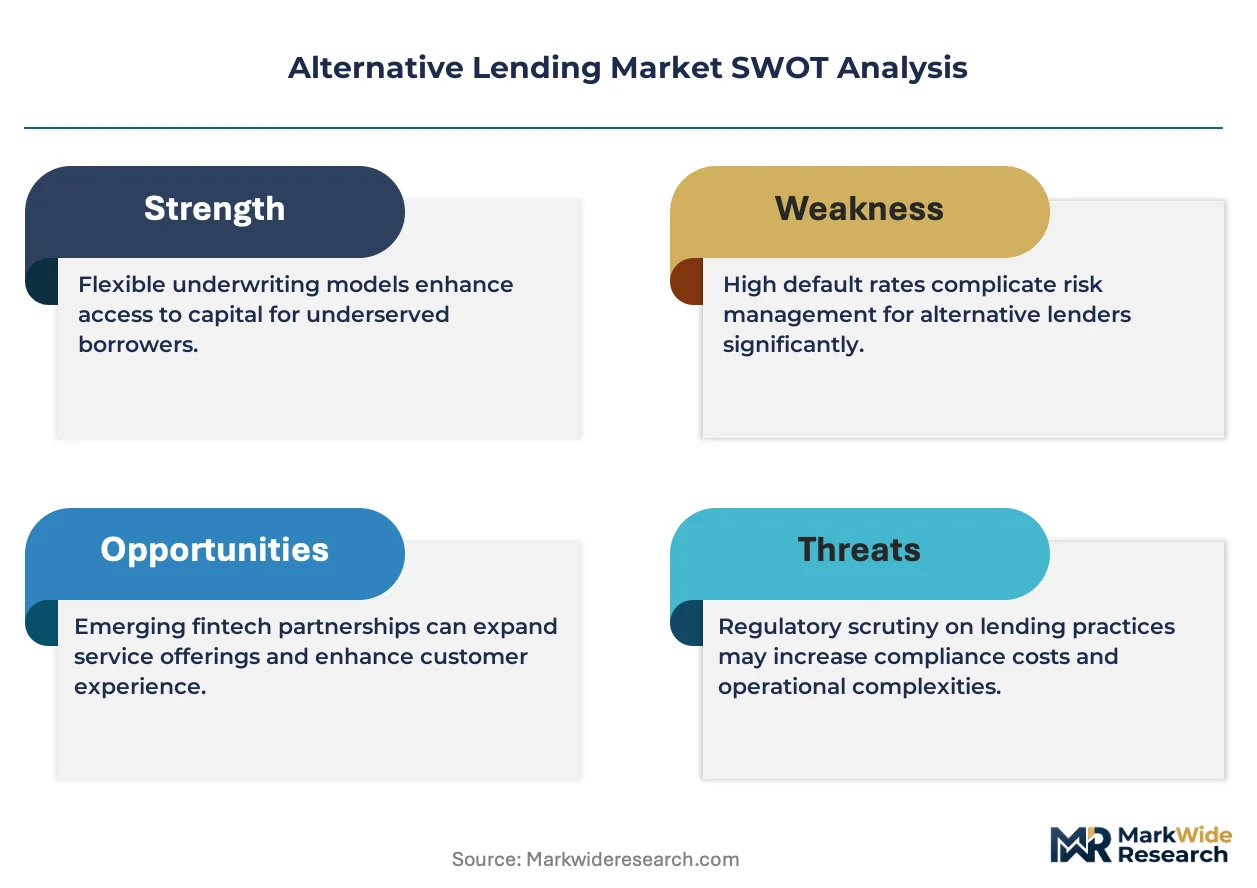
- Funding cost volatility:Institutional capital providers face basis risk between warehouse financing rates and loan portfolio yields, compressing net interest margins during rate cycle shifts.
- Data concentration risk:Three major credit bureaus control traditional scoring infrastructure, creating single-point vulnerabilities for platforms dependent on bureau-augmented models.
- Regulatory fragmentation:Jurisdictional divergence between the Consumer Financial Protection Bureau, Financial Conduct Authority, and Securities and Exchange Commission multiplies compliance architecture costs for cross-border operators.
Strategic Opportunities
- Embedded lending convergence:Point-of-sale finance partnerships with e-commerce platforms and vertical SaaS providers are absorbing transaction data streams for pre-qualified origination.
- Climate-aligned credit products:Green loan certifications tied to EU Green Deal taxonomy criteria are opening institutional capital pools from ESG-mandated investors.
- Supply chain finance expansion:Tier-2 and tier-3 supplier networks in automotive and electronics manufacturing present untapped invoice financing volumes.
Industry Challenges
- Model risk management talent scarcity:Platforms face acute shortages of quantitative analysts capable of validating machine learning credit models under SR 11-7 and EU AI Act governance standards.
- Legacy core banking integration:Partnerships with chartered banks for origination and servicing require expensive API middleware development to bridge decades-old batch processing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Lending Market |
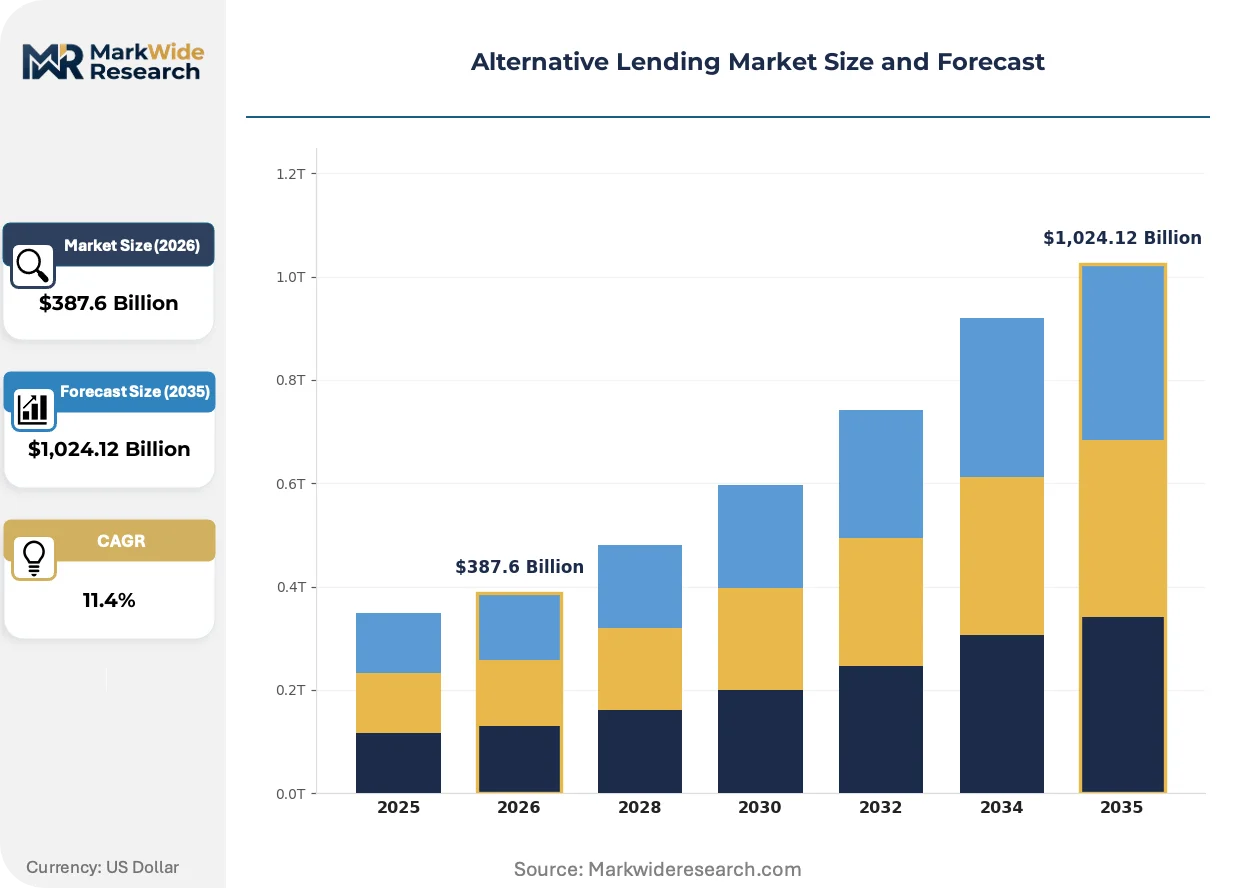
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lending Type: P2P Lending, Invoice Financing, Merchant Cash Advances, Crowdfunding Borrower Profile: Startups, Small Businesses, Freelancers, Nonprofits Loan Purpose: Working Capital, Inventory Purchase, Equipment Financing, Business Expansion Repayment Structure: Monthly Payments, Flexible Payments, Lump Sum, Revenue-Based |
| Companies Covered | LendingClub, Funding Circle, Prosper Marketplace, Upstart Network, SoFi Technologies, OnDeck Capital, GoFundMe, Kiva, CircleUp Network, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Lending Market Emerging Trajectories
Alternative lending platforms are weaponizing real-time data infrastructure to collapse origination friction, while regulators race to impose algorithmic accountability frameworks that will separate compliant operators from marginal players.
Machine learning credit scoring is absorbing behavioral signals from cash flow velocity, payment timing patterns, and digital footprint consistency to supplement traditional bureau data. Subprime and near-prime consumer segments in the United States and United Kingdom are adopting these models fastest, with platforms reporting approval rate expansion for thin-file applicants previously auto-declined. The structural consequence is absorbing underbanked populations into formal credit markets while compressing loss ratios through dynamic pricing.
The EU AI Act mandates human oversight, bias auditing, and explainability documentation for automated lending decisions across European platforms. Origination engines must now maintain audit trails linking each credit decision to interpretable risk factors rather than black-box neural network outputs. Small-business term loan providers in Germany, France, and the Netherlands are responding by hiring model risk officers and retraining underwriting teams on algorithmic governance protocols.
Borrower acquisition is fragmenting away from direct-to-consumer marketing toward embedded distribution partnerships with accounting software, payment processors, and industry-vertical marketplaces. Merchant cash advance providers are ceding ground to revenue-based financing products integrated directly into Stripe, Shopify, and QuickBooks dashboards. This channel rotation is most visible in the United States, where SaaS-embedded lending now captures disproportionate share of early-stage enterprise originations.
Alternative Lending Market Segmentation
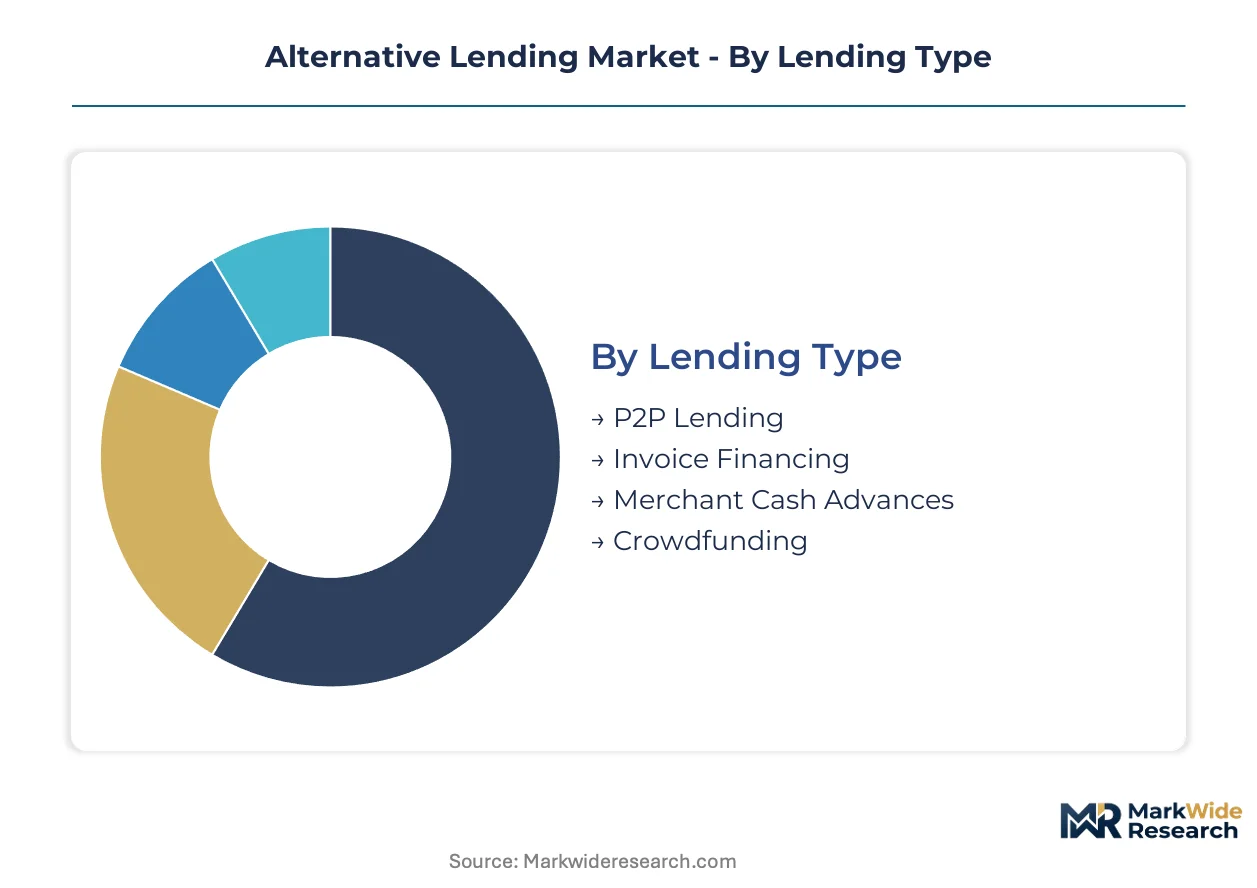
Alternative lending platforms engineer product architectures around borrower cash flow patterns and risk tolerance rather than standardized bank templates. Segmentation reveals how invoice velocity, business lifecycle stage, and revenue predictability determine which capital structures match which borrower archetypes.
Lending Type:
Platforms replace legacy term-loan products with structures that upgrade collateral efficiency and accelerate funding velocity.
- P2P Lending:Institutional capital now dominates transaction flows on platforms originally designed for retail participation. United States and United Kingdom originators concentrate here as pension funds and asset managers seek yield outside conventional fixed income.
- Invoice Financing:API-linked platforms convert accounts receivable into immediate liquidity by verifying invoice authenticity against buyer payment histories. Manufacturing and logistics suppliers in Germany and the Netherlands adopt this fastest as open banking infrastructure matures.
- Merchant Cash Advances:Future revenue streams collateralize upfront capital injections, with repayment flexing against daily card settlement volumes. Retail and hospitality operators with lumpy cash flows favor this structure.
- Crowdfunding:Community validation and pre-sales reduce default risk for creative ventures, social enterprises, and product launches. United Kingdom platforms lead regulatory clarity for equity and reward-based models.
P2P Lending sits at the top of the volume ranking, with Invoice Financing climbing the fastest.
Borrower Profile:
Customer acquisition economics vary sharply across business maturity stages, with thin-file applicants commanding premium pricing and specialized underwriting.
- Startups:Pre-revenue or early-revenue ventures access capital through revenue-based structures and equity crowdfunding. United States SaaS founders leverage Stripe and QuickBooks integrations for pre-qualified origination.
- Small Businesses:Established enterprises with 2-5 years of operating history absorb the majority of term-loan and invoice financing volumes. United Kingdom manufacturing subcontractors and German Mittelstand firms dominate this pool.
- Freelancers:Solo operators with irregular income streams rely on cash-flow-based scoring using accounting software data. France and Netherlands platforms report fastest adoption among creative professionals.
- Nonprofits:Social-purpose organizations access mission-aligned capital through specialized crowdfunding and impact-focused P2P channels. United Kingdom charity commission registration enables streamlined verification.
Small Businesses command the dominant share of origination volume, while Freelancers expand most quickly as platform onboarding friction collapses.
Loan Purpose:
Capital deployment purpose dictates risk weighting and pricing tiers, with cyclical inventory needs separating from structural expansion financing.
- Working Capital:Short-term liquidity bridges for payroll, rent, and supplier payments absorb the highest transaction frequency. United States seasonal retailers and United Kingdom construction subcontractors drive demand concentration.
- Inventory Purchase:Pre-shipment financing for import-dependent merchants leverages purchase order verification and trade credit insurance. China cross-border e-commerce sellers and German automotive parts distributors utilize this heavily.
- Equipment Financing:Asset-backed structures collateralize machinery, vehicles, and technology deployments. France and Netherlands manufacturing SMEs favor this for production line upgrades.
- Business Expansion:Growth capital for new locations, hiring, and market entry commands longer tenors and stricter covenants. United States franchise operators and United Kingdom professional services firms dominate.
Working Capital originates at the highest frequency, with Inventory Purchase gaining share fastest as supply chain finance platforms proliferate.
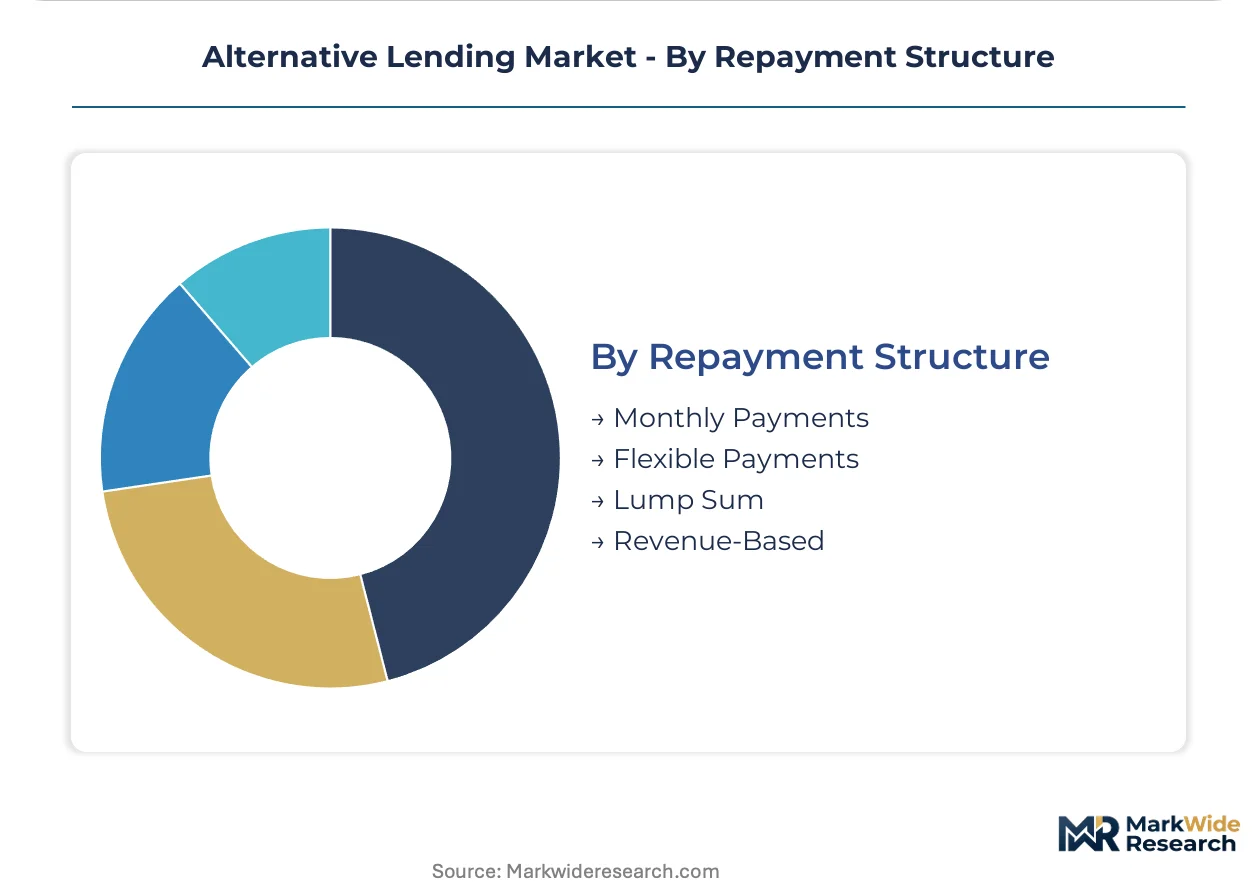
Repayment Structure:
Repayment architecture aligns borrower cash conversion cycles with platform risk management, separating fixed obligations from variable revenue-linked structures.
- Monthly Payments:Fixed amortization schedules dominate term-loan products for borrowers with predictable revenue. United States and United Kingdom small businesses with established accounting histories prefer this predictability.
- Flexible Payments:Seasonal adjustment clauses and skip-payment options accommodate tourism, agriculture, and construction cycles. France and Italy platforms embed these features for Mediterranean seasonal enterprises.
- Lump Sum:Bullet repayment at maturity matches invoice financing and short-term bridge structures. Germany and Netherlands B2B suppliers utilize this for 30-90 day receivable conversions.
- Revenue-Based:Percentage-of-revenue models scale obligations with top-line performance, capping payments during downturns. United States SaaS and e-commerce operators adopt this fastest as embedded lending spreads.
Monthly Payments retain the largest outstanding balance, with Revenue-Based structures expanding most steeply as vertical SaaS integrations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alternative lending first achieved institutional scale in the United Kingdom following the 2008 financial crisis, when regulatory reforms and bank retrenchment created permanent space for non-bank credit origination. Platform economics subsequently migrated to the United States and China, establishing the tripartite geography that now absorbs the majority of transaction flow.
United States
Stripe and QuickBooks integrations now capture pre-qualified origination for early-stage SaaS ventures and e-commerce operators. The Consumer Financial Protection Bureau enforces disclosure standards and interest rate oversight that shape platform operating economics. Fintech clusters in San Francisco and New York anchor embedded lending partnerships that collapse borrower acquisition costs through vertical SaaS distribution.
United Kingdom
Small-business term loans and invoice financing absorb the majority of platform volume as manufacturing subcontractors seek liquidity outside traditional banking channels. The Financial Conduct Authority mandates investor protection rules and transparency requirements for P2P platforms. London and Manchester host the densest concentration of revenue-based financing providers serving creative professionals and Mittelstand-linked suppliers.
China
Cross-border e-commerce sellers leverage purchase order verification and trade credit insurance for inventory pre-shipment financing. The central bank and SAMR jointly supervise non-bank credit origination and data privacy standards affecting algorithmic underwriting. Shenzhen and Hangzhou clusters specialize in supply chain finance platforms linking tier-2 automotive and electronics suppliers to immediate liquidity.
Germany
Mittelstand firms with established operating histories absorb term-loan and equipment financing volumes through open banking-enabled cash flow analytics. BaFin enforces EU AI Act compliance frameworks requiring human oversight and bias auditing for automated credit decisions. Munich and Frankfurt anchor invoice financing automation for B2B suppliers across manufacturing and logistics verticals.
Netherlands
Creative professionals and solo operators with irregular income streams adopt cash-flow-based scoring through accounting software integrations. The Dutch central bank and AFM supervise platform disclosure standards and algorithmic governance protocols. Amsterdam and Rotterdam clusters concentrate API-linked platforms converting accounts receivable into immediate liquidity for 30-90 day cycles.
Alternative Lending Market Vendor Landscape
Capital-heavy balance-sheet lenders compete with asset-light marketplace originators across divergent risk-return profiles. The vendor base fragments across three tiers: integrated full-stack platforms, specialized product architects, and embedded distribution partners. Dominant competitive moves include vertical SaaS integration for borrower acquisition and regulatory technology investments for EU AI Act compliance.
Within the integrated platform tier, LendingClub, Funding Circle, and Prosper Marketplace occupy positions that exemplify the transition from retail P2P participation toward institutional capital dominance. LendingClub represents the machine learning credit scoring archetype that assesses borrower risk beyond traditional bureau data. Funding Circle anchors small-business term loan specialization across dual-jurisdiction footprints. Prosper Marketplace exemplifies transparent fee-structure positioning within fixed-rate personal lending.
| Leading Market Players |
|---|
| LendingClub |
| Funding Circle |
| Prosper Marketplace |
| Upstart Network |
| SoFi Technologies |
| OnDeck Capital |
| GoFundMe |
| Kiva |
| CircleUp Network |
| Others |
Supply Flow & Price Mechanics
Algorithmic underwriting infrastructure is simultaneously collapsing origination cost curves and concentrating platform economics among scaled operators with proprietary data pipelines. The shift from manual credit assessment to API-linked cash flow analytics redraws cost structures while favoring providers with captive distribution through vertical SaaS partnerships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments borrowers by credit file thickness and data availability. Premium tiers command spreads for thin-file applicants lacking traditional bureau histories, while standard pricing absorbs established small businesses with verifiable accounting records. Cost compression in the economy tier is intensifying because neobank entrants are subsidizing customer acquisition through venture-backed balance sheets. Freelancers and solo operators exhibit highest price sensitivity, whereas Mittelstand-linked manufacturers with invoice financing needs demonstrate lowest elasticity due to liquidity urgency.
Supply Chain Analysis
EU AI Act certification requirements for algorithmic credit decisions are gating platform access to institutional capital pools and regulatory passporting rights. Technology infrastructure concentrates in the United States, the United Kingdom, and Germany, where open banking APIs and cloud compute capacity enable real-time underwriting engines. Funding supply draws from pension funds, asset managers, and warehouse credit facilities, with capital sourcing resting on securitization market depth. Single-source vulnerability in credit bureau data creates concentration risk for platforms dependent on legacy scoring augmentation. Distribution runs through embedded partnerships with accounting software providers, payment processors, and industry-vertical marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternative lending market functions as a regulatory compounder where EU AI Act compliance mandates are accelerating platform consolidation and elevating barriers to algorithmic underwriting. This regulatory milestone is compressing margins for non-compliant operators while expanding addressable pools for human-in-the-loop architectures.
For Market Incumbents: Acquire specialized model risk management talent pools to validate machine learning credit engines under SR 11-7 and EU AI Act governance standards. Consolidate vertical SaaS distribution partnerships to lock in borrower acquisition channels before embedded lending saturation. The threat of neobank balance-sheet subsidies demands channel control through exclusive QuickBooks, Stripe, and Shopify integrations as a defensive moat. For New Entrants and Emerging Players: API-first origination partnerships with tier-2 automotive and electronics suppliers represent the most penetrable white-space target for invoice financing automation. Revenue-based financing for pre-revenue SaaS ventures in the United States offers second-mover opportunity as incumbent platforms concentrate on established small businesses. A direct integration into vertical accounting software dashboards provides the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap platforms with EU AI Act compliance infrastructure already deployed but lacking scale to compete for institutional capital allocations. Long-term viability across the analysis window hinges on regulatory technology investments amortizing across diversified jurisdiction footprints. The signal to watch is warehouse financing spread widening, which indicates basis risk compression and potential portfolio yield stress.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture | Human-in-the-loop underwriting systems unlock institutional capital from ESG-mandated European investors. |
| Vertical SaaS Integration | Embedded lending partnerships with QuickBooks and Stripe collapse customer acquisition costs for early-stage enterprises. |
| Model Risk Management Buildout | Quantitative validation capabilities satisfy SR 11-7 standards and differentiate platforms during regulatory examinations. |
| Supply Chain Finance Expansion | Tier-2 supplier networks in German automotive manufacturing present untapped invoice financing volumes. |
| Climate-Aligned Product Certification | EU Green Deal taxonomy criteria open capital pools from impact-focused institutional lenders. |
Methodological Framework
Direct dialogue with platform risk officers, embedded lending partnership managers, institutional capital allocators, and regulatory compliance directors grounded qualitative findings in operational reality. Secondary validation drew from SEC filings for publicly traded fintech operators, Consumer Financial Protection Bureau enforcement actions, Financial Conduct Authority regulatory notices, and open banking adoption statistics published by national banking regulators. Bottom-up origination volume estimates triangulated against top-down addressable market calculations derived from small business formation data and thin-file population demographics.
Bottom-up modeling segmented transaction flows by lending type, borrower profile, loan purpose, and repayment structure across the projection horizon. Top-down analysis anchored total addressable market sizing on central bank small business lending surveys and alternative credit penetration benchmarks. CAGRs emerged from regression analysis against macroeconomic drivers including rate cycle positioning, small business formation velocity, and open banking infrastructure maturity. Forecast inputs incorporated algorithmic underwriting adoption curves and EU AI Act implementation timelines affecting compliance cost burdens.
The model assumes a particular technology adoption path for machine learning credit scoring; alternative pathways involving regulatory rejection of black-box models would alter the outlook toward explainable AI architectures with higher compliance overhead. Forecasts reflect assumptions regarding institutional capital availability and warehouse financing market depth. A model refresh is warranted upon material change in central bank rate trajectories or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Digital Lending Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
North America Used Car Financing Market
Loans and Leasing
Loan Origination Software Market