
 Montenegro Home Mortgage Finance Market | 2026-2036
Montenegro Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Montenegro Home Mortgage Finance Market Foresight
First-time buyers is reorganizing demand patterns across Montenegro's mortgage landscape, pulling volume away from investor-dominated segments that peaked during the pre-pandemic tourism-property boom. NLB Banka Montenegro leverages its Slovenian-parent balance sheet to offer longer-duration fixed-rate products that local peers struggle to match. Crnogorska Komercijalna Banka anchors the coastal corridor with branch density in Podgorica and Bar that sustains above-average conversion rates. Hipotekarna Banka specializes in structured refinancing instruments, competing aggressively for rate-sensitive refinancers from rival portfolios.
Home mortgage finance encompasses the extension of secured long-term credit collateralized by residential real property, typically structured with loan-to-value ratios between 70% and 80% for primary residences and amortization schedules spanning 15 to 30 years, with the fundamental purpose of transferring property ownership from cash-market constraints to leveraged household balance sheets. Fixed rate mortgages occupy the dominant share of origination volume as borrowers seek shelter from Euribor-linked volatility, while adjustable rate mortgages attract yield-sensitive investors in the secondary vacation-home segment. First-time buyers represent the fastest-growing client category, spurred by government guarantee schemes and developer-linked down-payment assistance programs that reduce front-equity barriers.
The Central Bank of Montenegro enforces macroprudential loan-to-value and debt-service-to-income limits that directly constrain bank underwriting flexibility and shape product design toward more conservative amortization profiles. EU accession alignment pressures are tightening capital adequacy expectations under CRD IV-inspired frameworks, while the country's national payment system regulator monitors foreign-currency exposure given the euroized economy's lack of monetary autonomy. Stakeholders must track how pending EU banking union conformance requirements will reshape local lenders' funding costs and competitive positioning.
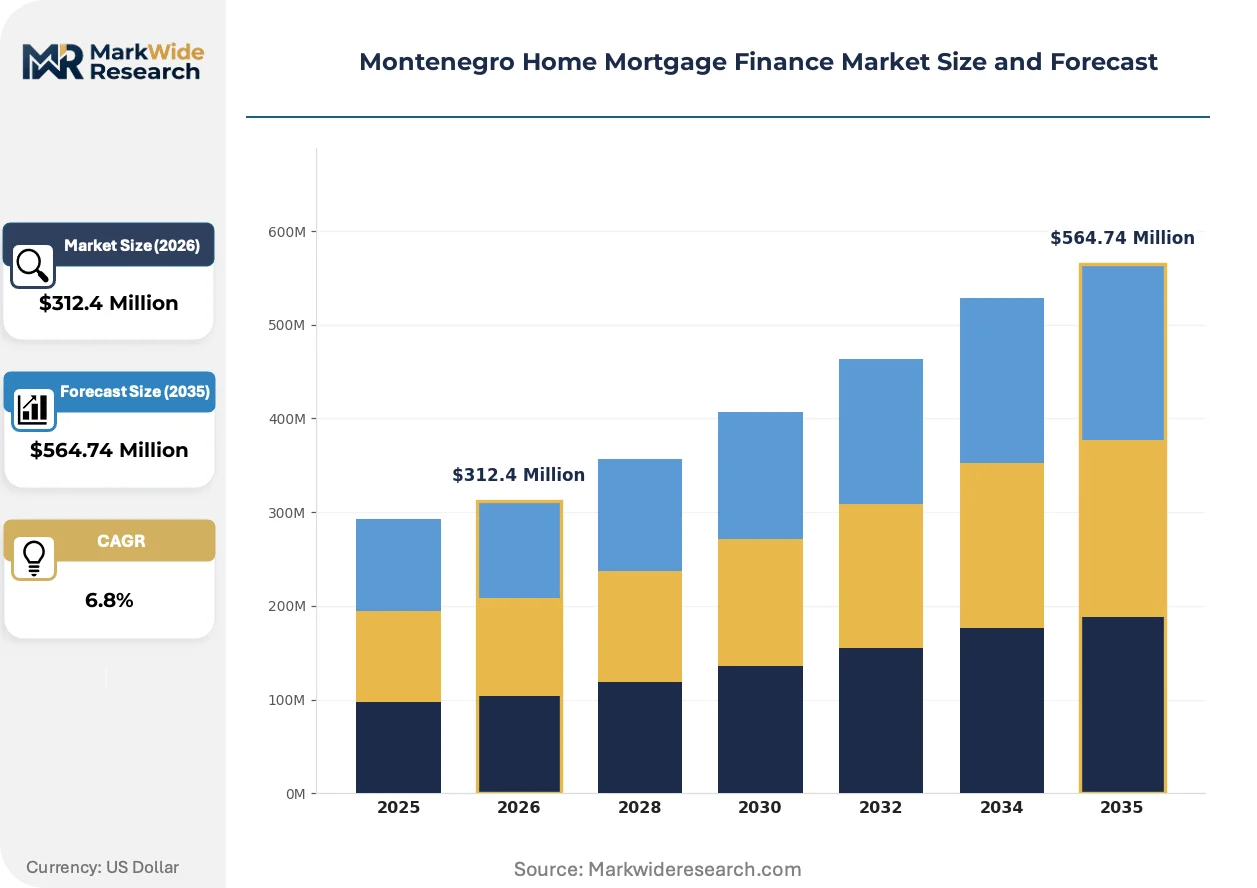
Market Dynamics
The Central Bank of Montenegro's tightening loan-to-value caps are compressing speculative origination volumes and redirecting bank credit toward first-time buyer segments with documented income stability.
Growth Catalysts
- Euribor-linked refinancing waves:Rate-sensitive households are accelerating prepayment velocities as forward rate curves signal stabilization, creating portfolio churn that specialized lenders exploit.
- Coastal tourism-property normalization:Post-boom price corrections in Budva and Kotor municipalities are restoring debt-service-to-income feasibility for local wage earners previously priced out.
- EU accession alignment capital:Parent-bank subsidiaries from Slovenia and Serbia are injecting longer-duration funding into Montenegrin mortgage books ahead of banking union conformance deadlines.
Market Restraints
- Deposit base concentration:Two systemic banks control over sixty percent of retail deposits, constraining price competition and locking smaller lenders into expensive wholesale funding.
- Construction input cost stickiness:Reinforced steel and cement price volatility imported from regional suppliers is compressing developer margins and delaying project completions that collateralize pre-sold mortgages.
- Foreign-currency earnings mismatch:Euro-denominated liabilities expose borrowers with local-dinar income streams to unhedged exchange risk despite formal euroization.
Strategic Opportunities
- Underpenetrated northern municipalities:Pljevlja and Bijelo Polje show mortgage penetration rates less than one-third of Podgorica levels, offering first-mover branch economics for agile entrants.
- Green building certification incentives:Pending EU Energy Performance of Buildings Directive alignment will create interest-rate discounts for mortgages collateralizing certified efficient stock.
- Digital origination convergence:Mobile identity verification layered with central bank credit registry APIs is miniaturizing application-to-disbursement timelines below legacy branch-based benchmarks.
Industry Challenges
- Valuation standardization gaps:Inconsistent appraisal methodologies across municipal cadastres are creating collateral-risk assessment friction that slows underwriting decisions.
- Core banking system fragmentation:Legacy IT architectures at mid-tier lenders impede real-time integration with central bank macroprudential reporting systems, forcing manual workaround processes.
- Notary bottleneck concentration:Limited numbers of licensed notaries in coastal growth corridors are elongating closing timelines and increasing borrower fall-through rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Montenegro Home Mortgage Finance Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Rate Mortgages, Adjustable Rate Mortgages, Interest-Only Mortgages, Balloon Mortgages Client Type: First-Time Buyers, Refinancers, Investors, Repeat Buyers Loan Duration: Short-Term Loans, Long-Term Loans, Mixed-Rate Loans, Standard Loans Payment Structure: Monthly Payments, Biweekly Payments, Annual Payments, Lump Sum Payments |
| Companies Covered | Crnogorska Komercijalna Banka, NLB Banka Montenegro, Erste Bank Montenegro, Adriatic Bank, Hipotekarna Banka, Lovćen Bank, Ziraat Bank Montenegro, Universal Capital Bank, First Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Montenegro Home Mortgage Finance Market Shifts & Advancements
Digital infrastructure deployment and regulatory harmonization pressures are compressing origination friction and reshaping how Montenegrin households access secured credit.
Automated valuation models using satellite imagery and municipal transaction databases are miniaturizing property assessment cycles from weeks to hours. NLB Banka Montenegro and Hipotekarna Banka have deployed these tools for refinance applications, compressing cost-to-serve metrics while expanding coverage into thinly traded northern municipalities where traditional appraisers lack density.
Central Bank of Montenegro macroprudential circulars are hardening debt-service-to-income ceilings and dynamic provisioning requirements for high-LTV buckets. These constraints are forcing product innovation toward longer amortization profiles and hybrid fixed-floating structures that optimize within regulatory boundaries. Coastal investor segments are responding by restructuring holdings through corporate vehicles exempt from retail caps.
Developer-linked down-payment assistance programs are displacing pure bank-originated front-equity requirements. Podgorica and Bar construction firms now bundle deferred-payment second liens with primary sales, capturing buyer commitment before formal mortgage placement. This channel shift concentrates volume with vertically integrated developers and erodes traditional broker intermediation economics in urban growth corridors.
Montenegro Home Mortgage Finance Market Segmentation
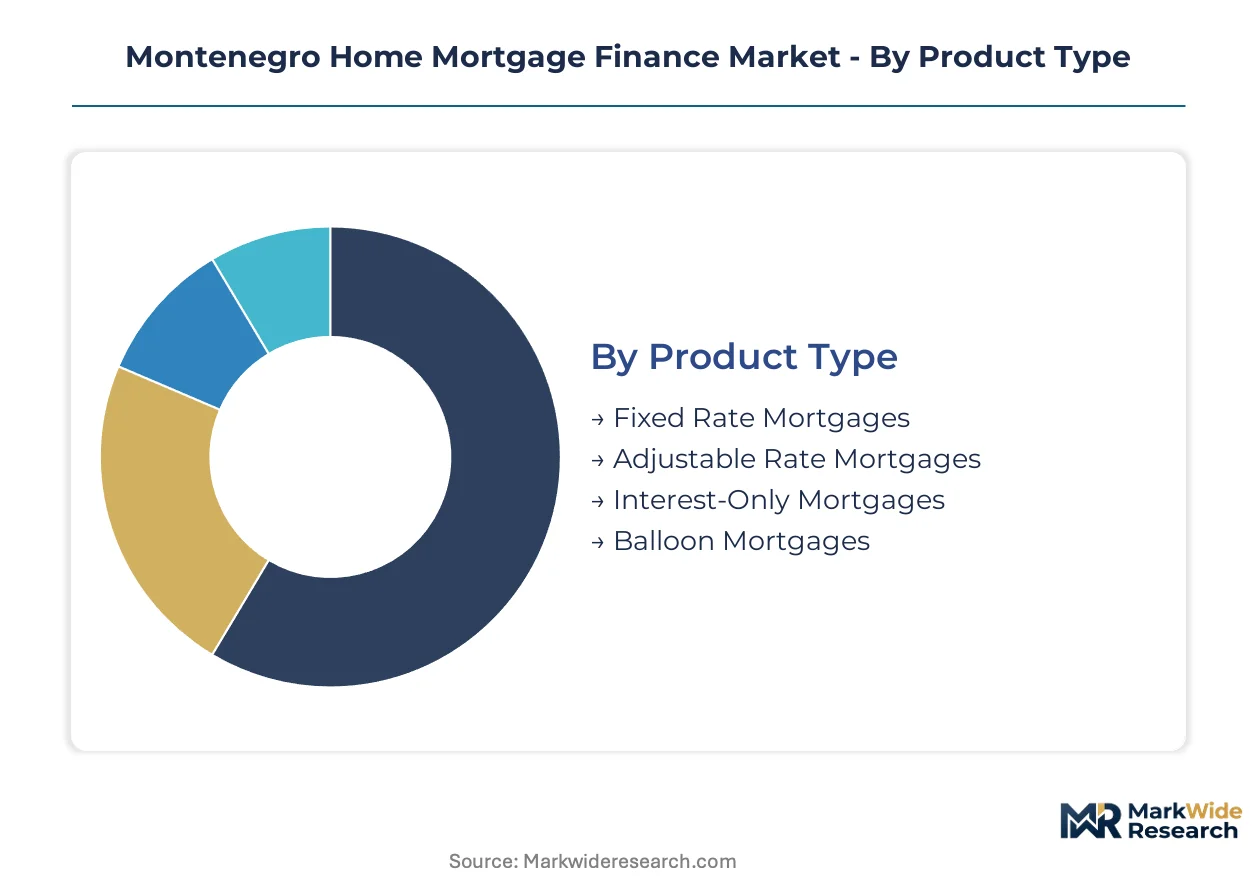
Montenegro's mortgage market fragments across product structures, borrower profiles, and payment mechanics that reflect divergent risk appetites and income patterns. Understanding these divisions reveals where regulatory tightening and digital origination are reshaping competitive positioning.
Product Type:
Domestic demand concentrates in euro-denominated fixed-rate structures that shelter households from Euribor volatility, while export-linked coastal investors retain appetite for adjustable-rate exposure.
- Fixed Rate Mortgages:These instruments lock borrowing costs for the full amortization period, typically referencing 10-year Euribor swaps plus bank margin. Podgorica wage-earners favor this predictability as the Central Bank of Montenegro tightens macroprudential ceilings. Fixed Rate Mortgages command the established base.
- Adjustable Rate Mortgages:Interest resets at predetermined intervals against 3-month or 6-month Euribor benchmarks. Budva and Kotor vacation-property investors accept this exposure to capture lower initial carrying costs, though forward curve uncertainty is compressing origination volumes. The steepest expansion runs through Interest-Only Mortgages.
- Interest-Only Mortgages:Borrowers service only interest for an initial term before principal amortization begins. Coastal developers bundle these with deferred-equity schemes to accelerate pre-sales.
- Balloon Mortgages:Structures requiring substantial terminal principal payment, favored by seasonal-income households in tourism-dependent municipalities who anticipate liquidity events.
Fixed Rate Mortgages anchor the mass-market foundation. Adjustable Rate Mortgages face pressure from regulatory risk-weighting adjustments.
Client Type:
First-time buyers are reorganizing origination flows as macroprudential caps squeeze speculative investor participation that dominated pre-pandemic coastal booms.
- First-Time Buyers:Government guarantee schemes and developer down-payment assistance are reducing front-equity barriers for Podgorica and Bar wage-earners entering ownership. First-Time Buyers command the established base.
- Refinancers:Rate-sensitive households accelerating prepayments as forward curves stabilize, creating portfolio churn that Hipotekarna Banka targets with structured refinancing instruments.
- Investors:Coastal tourism-property acquirers restructuring through corporate vehicles to circumvent retail debt-service-to-income caps imposed by the Central Bank of Montenegro.
- Repeat Buyers:Equity-rich households trading up within Podgorica's suburban expansion corridors, leveraging existing property collateral for expedited underwriting.
First-Time Buyers drive volume recovery. Investors are retreating toward corporate structuring to preserve leverage capacity.
Loan Duration:
Parent-bank subsidiaries from Slovenia are injecting longer-duration funding that local deposit-constrained lenders cannot match, extending viable amortization profiles.
- Short-Term Loans:Maturities under 10 years, typically bridging instruments for equity-heavy purchasers or pre-retirement borrowers in northern municipalities.
- Long-Term Loans:20-30 year amortization schedules that NLB Banka Montenegro extends using Slovenian-parent balance sheet capacity. Long-Term Loans command the established base.
- Mixed-Rate Loans:Hybrid structures combining initial fixed periods with subsequent adjustable terms, optimizing within regulatory boundaries while offering payment flexibility.
- Standard Loans:Conventional 15-year products that mid-tier lenders default to given deposit base constraints and manual underwriting systems.
Long-Term Loans dominate origination value. Mixed-Rate Loans are gaining share fastest as product innovation responds to macroprudential boundaries.
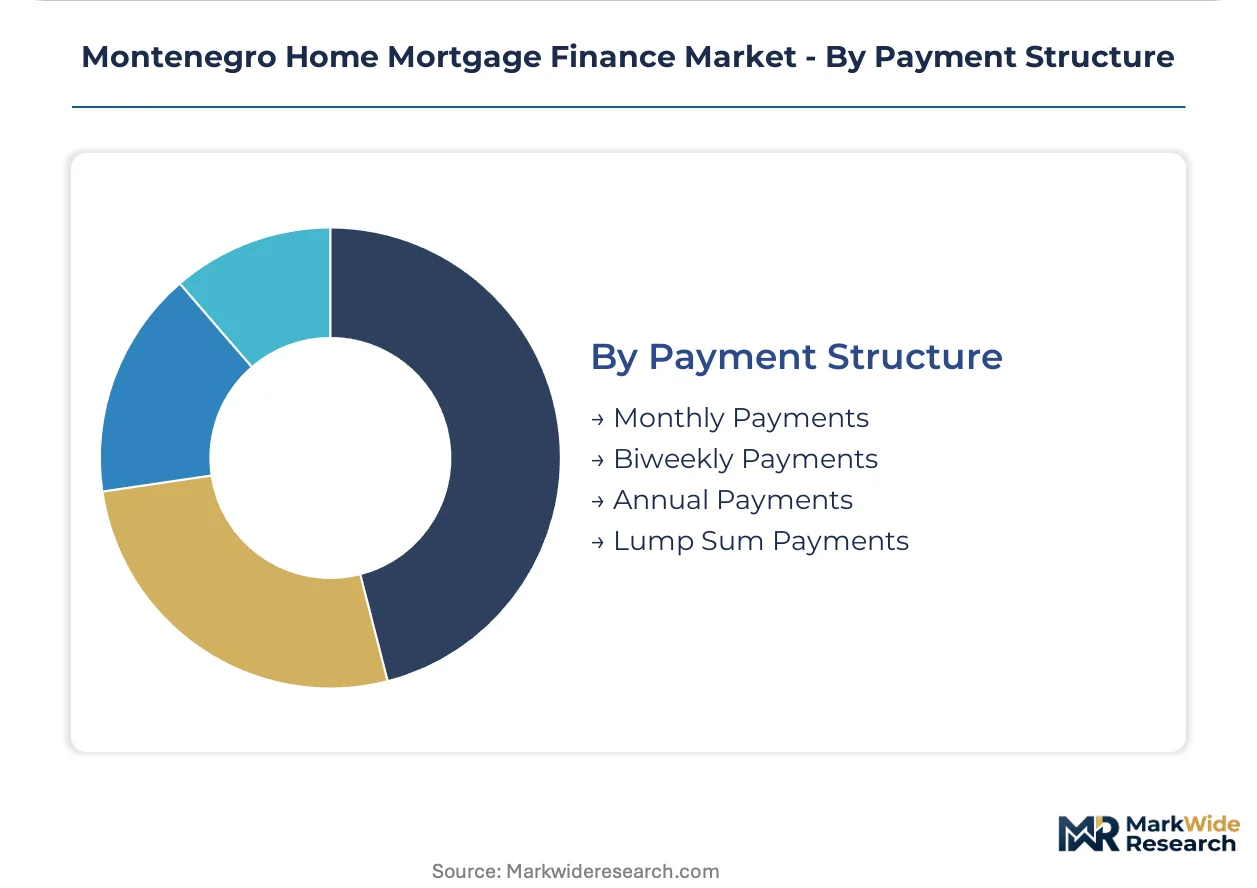
Payment Structure:
Digital infrastructure deployment is compressing payment scheduling friction, though legacy notary bottlenecks in coastal corridors still elongate closing timelines regardless of payment frequency.
- Monthly Payments:Standard salary-deduction alignment for Podgorica public-sector and formal private-sector employees, automated through employer-linked direct debit.
- Biweekly Payments:Accelerated amortization structures reducing total interest cost, adopted by households with seasonal tourism income in Budva and Tivat.
- Annual Payments:Lump-sum structures matching agricultural or hospitality business cash-flow cycles in rural northern municipalities.
- Lump Sum Payments:Terminal or periodic principal reductions favored by diaspora remittance recipients and equity-release refinancers. Monthly Payments command the established base.
Monthly Payments retain systemic dominance. Biweekly Payments are climbing fastest as digital origination enables flexible scheduling without branch overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mortgage origination concentrates in Montenegro's coastal municipalities and capital corridor, where tourism income and public-sector wages sustain debt-service capacity. Deposit base fragmentation across sub-regional banking networks shapes local pricing power.
Podgorica Capital Region
Public-sector employment and formal private-sector wages anchor origination demand in Montenegro's administrative center. The Central Bank of Montenegro's macroprudential circulars apply uniformly here, tightening debt-service-to-income ceilings for high-LTV applications. NLB Banka Montenegro maintains branch density in the capital that sustains above-average conversion rates for first-time buyer segments.
Coastal Municipalities
Budva and Kotor tourism-property markets are normalizing after pre-pandemic speculative peaks, restoring feasibility for local wage earners. The central bank's loan-to-value caps compress speculative investor participation that dominated 2017-2019 origination flows. Hipotekarna Banka targets rate-sensitive refinancers in Bar with structured instruments competing for portfolio churn.
Northern Municipalities
Pljevlja and Bijelo Polje exhibit mortgage penetration rates below one-third of Podgorica levels, constrained by thinner formal employment bases. Automated valuation models using satellite imagery now extend coverage into these thinly-traded markets where traditional appraisers lack density. Deposit concentration at Podgorica-headquartered banks limits price competition for northern borrowers.
Montenegro Home Mortgage Finance Market Competitive Landscape
Concentration sits with foreign-parent bank subsidiaries that inject longer-duration funding unavailable to deposit-constrained local lenders. Two systemic institutions control over sixty percent of retail deposits, constraining price competition and locking smaller lenders into expensive wholesale funding channels. Strategic archetypes include Slovenian-parent balance sheet deployers, specialized refinancing instrument providers, and coastal corridor branch density anchors. Dominant competitive moves center on digital origination convergence and developer-linked down-payment assistance bundling.
Among foreign-parent subsidiaries, NLB Banka Montenegro and Erste Bank Montenegro represent the balance sheet scale archetype, leveraging Slovenian and Austrian parent funding to extend fixed-rate durations that local peers cannot match. Hipotekarna Banka occupies the specialist refinancing position, competing aggressively for rate-sensitive portfolio churn. Crnogorska Komercijalna Banka anchors the coastal corridor with municipal branch density that sustains above-average conversion rates in Budva and Bar.
| Leading Market Players |
|---|
| Crnogorska Komercijalna Banka |
| NLB Banka Montenegro |
| Erste Bank Montenegro |
| Adriatic Bank |
| Hipotekarna Banka |
| Lovćen Bank |
| Ziraat Bank Montenegro |
| Universal Capital Bank |
| First Bank |
| Others |
Supply & Pricing Matrix
Parent-bank balance sheet scale at NLB Banka Montenegro and Erste Bank Montenegro compresses funding cost spreads that smaller deposit-constrained lenders cannot match, anchoring price floors for fixed-rate mortgage products while forcing mid-tier competitors toward expensive wholesale funding channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments Montenegro's mortgage market by borrower credit profile and collateral quality. Premium tiers attach to first-time buyers with government guarantee backing and low loan-to-value ratios, while economy pricing serves thin-file applicants at smaller municipal banks. Price differentiation rests on central bank macroprudential risk-weighting and parent-bank funding access. Pricing pressure stems from Euribor-linked refinancing waves compressing net interest margins. First-time buyers show highest price sensitivity, while coastal vacation-property investors accept rate premiums for flexible amortization structures.
Supply Chain Analysis
Mortgage disbursement timelines stretch from application to notarization due to limited licensed notary capacity in Budva and Kotor growth corridors, elongating closing cycles regardless of digital origination deployment. Funding supply concentrates in Slovenia, Austria, and Serbia through parent-bank subsidiaries injecting euro-denominated liabilities. Raw material dependencies include construction steel from regional Balkan suppliers and cement from Croatian producers. Single-source vulnerability sits with the two systemic banks controlling sixty percent of retail deposits. Distribution runs through branch networks in Podgorica and coastal municipalities, with digital channels accelerating pre-approval velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Montenegro's mortgage market rewards service-attach strategies as refinancing advisory and insurance bundling expand faster than pure origination revenue, creating recurring-fee layers that offset net interest margin compression.
For Market Incumbents: Shield core deposit franchises by accelerating digital origination convergence before agile entrants capture northern municipality white space. Defensive consolidation should prioritize API integration with the Central Bank of Montenegro credit registry to compress application-to-disbursement timelines. Vertical integration into developer-linked down-payment assistance preserves volume flow against broker disintermediation.
For New Entrants and Emerging Players: Lead with automated valuation model deployment in Pljevlja and Bijelo Polje where satellite imagery coverage now enables remote collateral assessment absent traditional appraiser density. The most penetrable segment is rate-sensitive refinancers churning from legacy portfolios as forward curves stabilize. Go-to-market positioning should anchor on hybrid fixed-floating product structures that optimize within macroprudential debt-service-to-income ceilings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist refinancing instrument providers with scalable digital infrastructure and low cost-to-serve metrics. Long-term viability hinges on EU accession alignment capital flows and banking union conformance deadlines. Acquisition target archetype: mid-tier lenders with legacy IT fragmentation but dense northern municipal branch networks. Signal to watch: central bank circulars on dynamic provisioning requirements that would reshape capital adequacy calculations.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Origination Platform Deployment | API integration with Central Bank of Montenegro credit registry compresses application-to-disbursement timelines below legacy benchmarks. |
| Automated Valuation Model Expansion | Satellite imagery coverage extends mortgage access into thinly-traded northern municipalities where traditional appraisers lack density. |
| Developer Down-Payment Assistance Bundling | Deferred-payment second liens capture buyer commitment before formal mortgage placement, eroding broker intermediation economics. |
| Hybrid Fixed-Floating Product Innovation | Structures optimizing within macroprudential boundaries attract rate-sensitive refinancers accelerating prepayment velocities. |
| Parent-Bank Funding Channel Diversification | Slovenian and Austrian balance sheet access enables longer-duration fixed-rate products that deposit-constrained local peers cannot match. |
Research Methodology
Operator-level perspectives from mortgage underwriting officers, central bank macroprudential supervisors, developer sales directors, and notary practitioners anchored the qualitative base. Primary interviews triangulated with secondary validation drawn from Central Bank of Montenegro circulars, EU banking union conformance documentation, municipal cadastre transaction records, and parent-bank subsidiary financial disclosures. Bottom-up origination volume estimates across product type, client segment, and regional municipality converged with top-down banking sector asset growth trajectories.
Sensitivity analysis stress-tested projections against Euribor curve volatility, construction input cost scenarios, and regulatory tightening sequences across the analysis window. Segmentation dimensions modeled encompassed product structure, borrower profile, loan duration tier, payment mechanics, and regional banking network penetration. CAGRs derived from historical origination velocity patterns adjusted for macroprudential intervention timing and EU accession capital flow assumptions. Forecast inputs included forward rate curve trajectories and northern municipality employment formalization rates.
Forecasts assume regulatory continuity in Central Bank of Montenegro macroprudential frameworks and EU banking union alignment schedules; material policy shifts or accession timeline revisions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
UK Home Equity Lending Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Microfinance Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Refinancing Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
Invoice Factoring Market