
 IoT for Finance Market | 2026-2036
IoT for Finance Market Size, Share, and Industry Trends Forecast 2026-2036
IoT for Finance Market Outlook
Platform licensing revenue is reconfiguring profit pools away from hardware-centric ATM maintenance toward software-defined branch management. Microsoft Corporation leverages its Azure IoT stack to anchor cloud-native financial infrastructure across North American institutions. IBM Corporation sustains dominance in mainframe-integrated sensor analytics for legacy banking systems. Cisco Systems specializes in edge networking hardware that controls real-time transaction verification at distributed branch locations.
IoT for Finance encompasses networked sensor systems, edge computing nodes, and API orchestration layers that collect, transmit, and analyze physical and digital event streams within financial operations. These systems typically process sub-100-millisecond latency thresholds for fraud detection and employ AES-256 encryption for data-in-motion security across payment terminals, vault sensors, and mobile banking endpoints. Fraud Detection applications occupy the largest addressable segment due to persistent card-not-present transaction vulnerabilities. Blockchain technology segments are expanding fastest among technology categories as distributed ledger protocols harden supply chain finance and cross-border settlement traceability. Retail Banking end users generate the highest implementation service volumes, though Wealth Management segments yield superior per-client consulting margins.
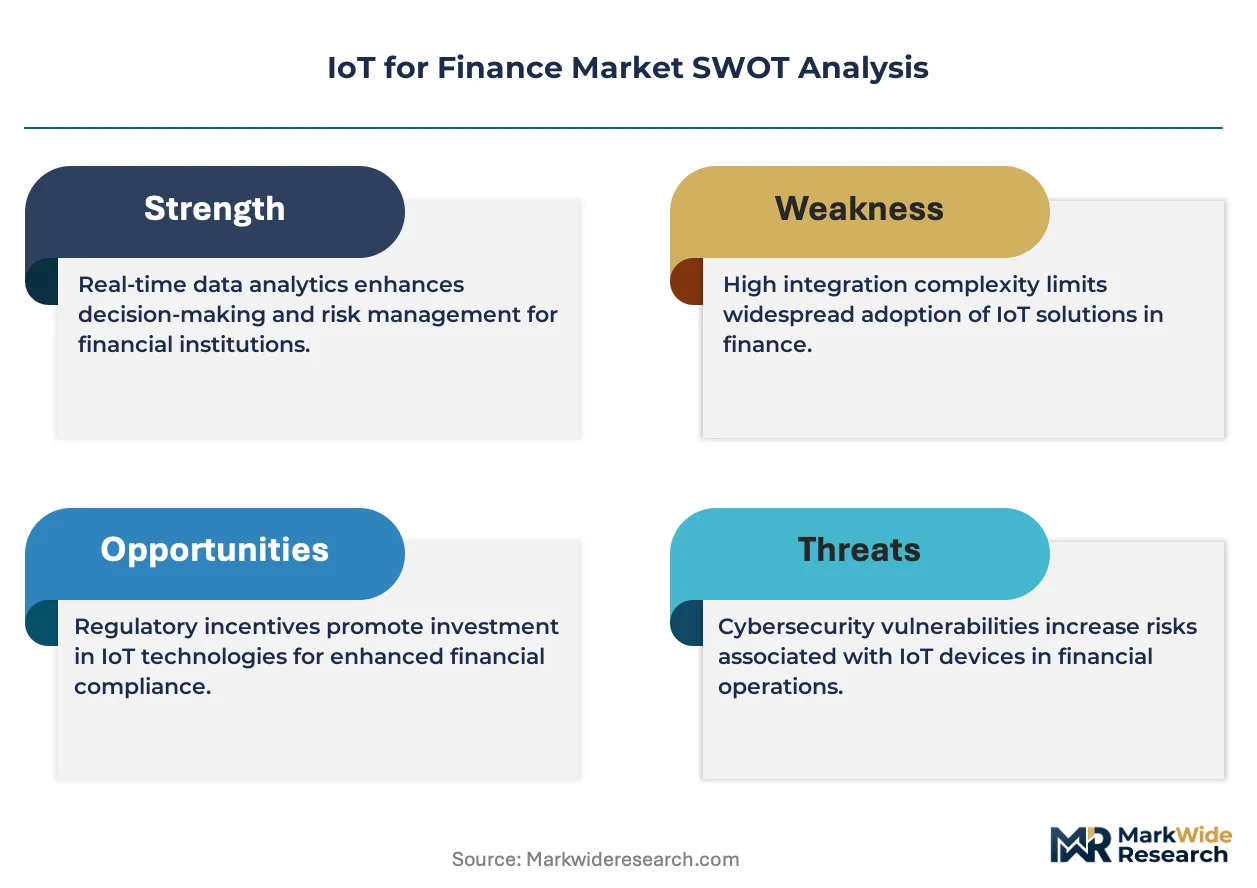
The Federal Reserve's operational risk guidelines, the EU's DORA framework for digital operational resilience, and PCI-DSS certification requirements collectively mandate encrypted endpoint telemetry and incident response automation for connected financial devices. These standards shape procurement criteria, forcing institutions to prioritize vendors with pre-certified compliance architectures rather than retrofitting legacy deployments. Stakeholders must evaluate whether their IoT vendor ecosystems can absorb forthcoming quantum-resistant cryptography mandates without forklift infrastructure replacements.
Market Dynamics
The convergence of open banking mandates and real-time payment infrastructure is compressing deployment timelines for sensor-networked financial operations. Institutions must now embed sub-100-millisecond fraud detection into distributed branch architectures while maintaining PCI-DSS encryption standards across heterogeneous endpoint fleets.
Growth Catalysts
- EU PSD2 Data-Sharing Mandates:Open banking frameworks compel retail institutions to expose account interfaces via standardized APIs, creating demand for IoT orchestration layers that bridge physical payment terminals with cloud-native transaction engines.
- Real-Time Payment Rails:The Federal Reserve's FedNow service and equivalent instant settlement systems in Brazil and India require edge-computing nodes at branch locations to pre-validate transactions before network submission.
- Vault Sensor Telemetry:Biometric access controls and environmental monitoring systems generate recurring SaaS revenue streams for hardware vendors transitioning from capital equipment sales to subscription-based operational technology management.
Market Restraints
- Semiconductor Supply Concentration:Edge computing nodes depend on specialized ASICs fabricated predominantly in Taiwan, exposing deployment schedules to geopolitical disruption risks and foundry allocation constraints.
- Quantum-Resistant Cryptography Transition:NIST post-quantum standards will force firmware overhauls across installed ATM and payment terminal bases, creating stranded asset risk for institutions with large legacy fleets.
- Mainframe Integration Friction:Core banking systems running COBOL-based transaction processing impose latency penalties on real-time IoT data streams, requiring expensive middleware layers that erode project ROI.
Strategic Opportunities
- Wealth Management Advisory Robotics:Sensor-enabled branch environments that detect client arrival and automatically surface portfolio analytics to relationship managers command premium consulting fees in Singapore and Switzerland.
- Blockchain-IoT Convergence:Distributed ledger protocols for supply chain finance require tamper-proof physical event logging, creating integrated hardware-software procurement opportunities for trade finance departments.
- India's Digital Rupee Infrastructure:The Reserve Bank of India's central bank digital currency pilot mandates offline-capable payment devices, opening design-win competitions for ruggedized IoT hardware with local manufacturing content requirements.
Industry Challenges
- Embedded Systems Security Expertise:Financial institutions face acute shortages of firmware engineers capable of implementing AES-256 hardware acceleration and secure boot chains for ARM-based payment terminals.
- Multi-Jurisdiction Certification Overlap:Devices deployed across US, EU, and UK operations must simultaneously satisfy PCI-DSS, GDPR data localization, and FCA operational resilience rules, extending compliance timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT for Finance Market |
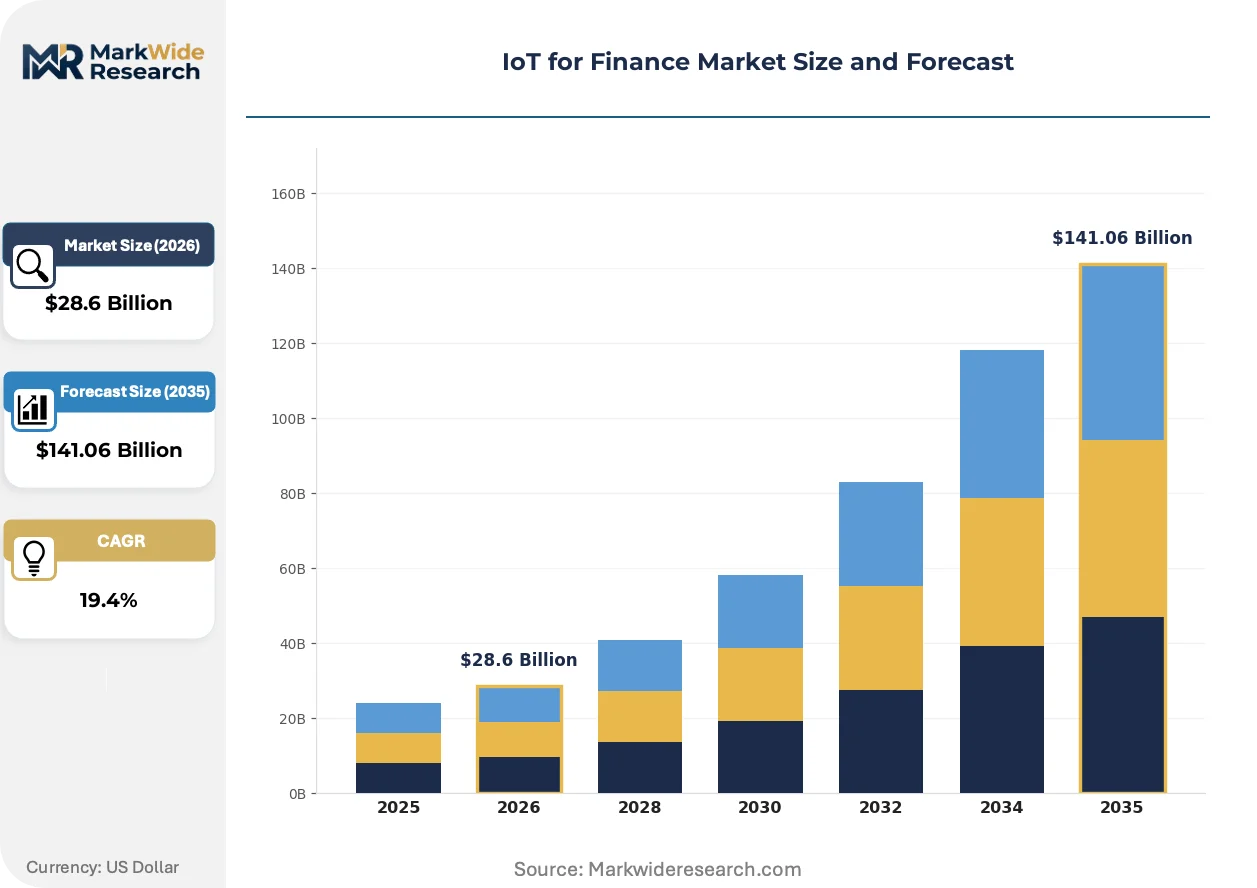
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Customer Analytics, Risk Management, Asset Tracking Technology: Cloud Computing, Artificial Intelligence, Blockchain, Big Data End User: Investment Banks, Insurance Companies, Retail Banking, Wealth Management Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Oracle Corporation, SAP SE, Accenture PLC, Capgemini SE, Amazon Web Services, HCLTech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT for Finance Market Strategic Shifts
Financial IoT architectures are pivoting from centralized cloud processing toward distributed intelligence that minimizes data gravity and regulatory exposure. This structural reconfiguration demands new hardware-software contracting models and reskilling programs for infrastructure teams.
Edge AI inference engines for fraud detection are migrating from GPU-accelerated cloud instances to ARM-based system-on-chip designs embedded directly within payment terminals. Tier-2 retail banks in Germany and the Netherlands are piloting these configurations to reduce per-transaction latency below 50 milliseconds. The technology is migrating from hyperscaler-dependent architectures toward autonomous branch-level processing that maintains transaction continuity during WAN outages.
Europe's Digital Operational Resilience Act (DORA) mandates automated incident reporting and third-party risk management for all critical ICT providers serving financial institutions. The regulation compels IoT vendors to maintain EU-based security operations centers and encrypt telemetry at the hardware layer before network transmission. Asset managers with cross-border fund distribution networks face the steepest compliance burden, driving consolidation toward vendors with pre-certified DORA architectures.
Institutional procurement of IoT infrastructure is fragmenting from enterprise-wide master service agreements toward line-of-business owned budgets with embedded cybersecurity sign-off requirements. Retail banking divisions now control sensor deployment decisions for branch automation, bypassing traditional IT procurement gatekeepers. This pattern is most pronounced in US regional banks where chief revenue officers hold P&L accountability for customer-facing technology investments.
IoT for Finance Market Segmentation
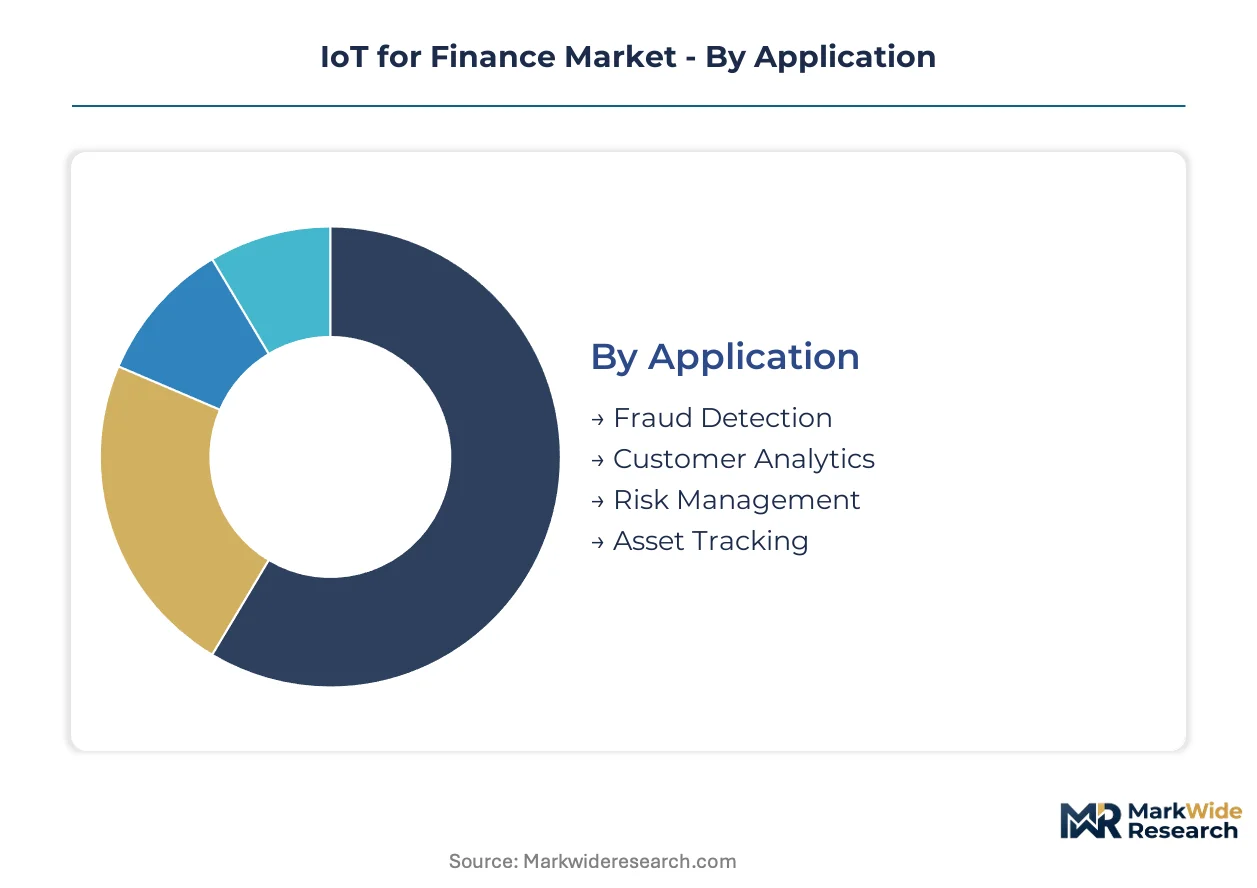
IoT for Finance deployments vary dramatically across transaction velocity, regulatory exposure, and client relationship intensity. Institutions configure sensor networks, edge nodes, and API layers differently depending on whether the priority is real-time fraud interception, predictive wealth advisory, or vault telemetry compliance.
Application:
Use-case spectrum spans millisecond-critical transaction validation through to long-horizon portfolio risk modeling, with each application imposing distinct latency and encryption requirements.
- Fraud Detection:Sub-100-millisecond inference engines embedded in payment terminals and ATM networks intercept anomalous transaction patterns before settlement. Demand concentrates in United States retail banking corridors where card-not-present vulnerabilities drive continuous sensor deployment.
- Customer Analytics:Branch-based sensor arrays detect client arrival patterns, dwell time, and service preferences to trigger personalized portfolio surfacing for relationship managers. Singapore and Switzerland wealth management centers generate premium consulting fees for these biometric-enabled environments.
- Risk Management:Environmental and access sensors monitor trading floor conditions and vault telemetry for operational continuity.
- Asset Tracking:GPS and RFID tags follow high-value physical collateral through supply chain finance arrangements.
The dominant share belongs to Fraud Detection, while Customer Analytics is closing the gap fastest.
Technology:
Technology selection hinges on data gravity constraints and cryptographic hardening requirements across distributed financial architectures.
- Cloud Computing:Hyperscaler infrastructure hosts transaction orchestration and centralized analytics for institutions with standardized branch footprints. United States regional banks leverage Azure and AWS stacks for API-based open banking compliance under FedNow integration timelines.
- Blockchain:Distributed ledger protocols harden supply chain finance and cross-border settlement traceability through tamper-proof physical event logging. Trade finance departments in Germany and Netherlands pilot integrated hardware-software procurement for immutable documentation chains.
- Artificial Intelligence:Edge AI inference migrates from GPU cloud instances to ARM-based system-on-chip designs within payment terminals.
- Big Data:Stream processing architectures aggregate telemetry from heterogeneous endpoint fleets for pattern recognition.
Cloud Computing retains the largest installed base, though Blockchain is expanding most quickly as DORA and PSD2 mandates intensify audit trail requirements.
End User:
End-user economics diverge sharply between high-volume transactional banking and high-margin advisory relationships.
- Retail Banking:Branch automation and ATM monitoring generate the highest implementation service volumes, with sensor deployments controlling real-time transaction verification at distributed locations. United States institutions in New York and Chicago drive enterprise adoption for customer-facing technology investments.
- Wealth Management:Sensor-enabled advisory environments command superior per-client consulting margins through automated portfolio analytics surfacing. Swiss and Singapore private banks lead deployment of arrival-detection systems for relationship manager optimization.
- Investment Banks:Trading floor telemetry and compliance monitoring dominate IoT priorities.
- Insurance Companies:Connected property sensors and usage-based policy telemetry reshape underwriting models.
Retail Banking captures the greatest deployment volume, while Wealth Management delivers the steepest margin expansion trajectory.
Service Type:
Service economics shift from capital equipment sales toward recurring operational technology management as hardware vendors reconfigure revenue models.
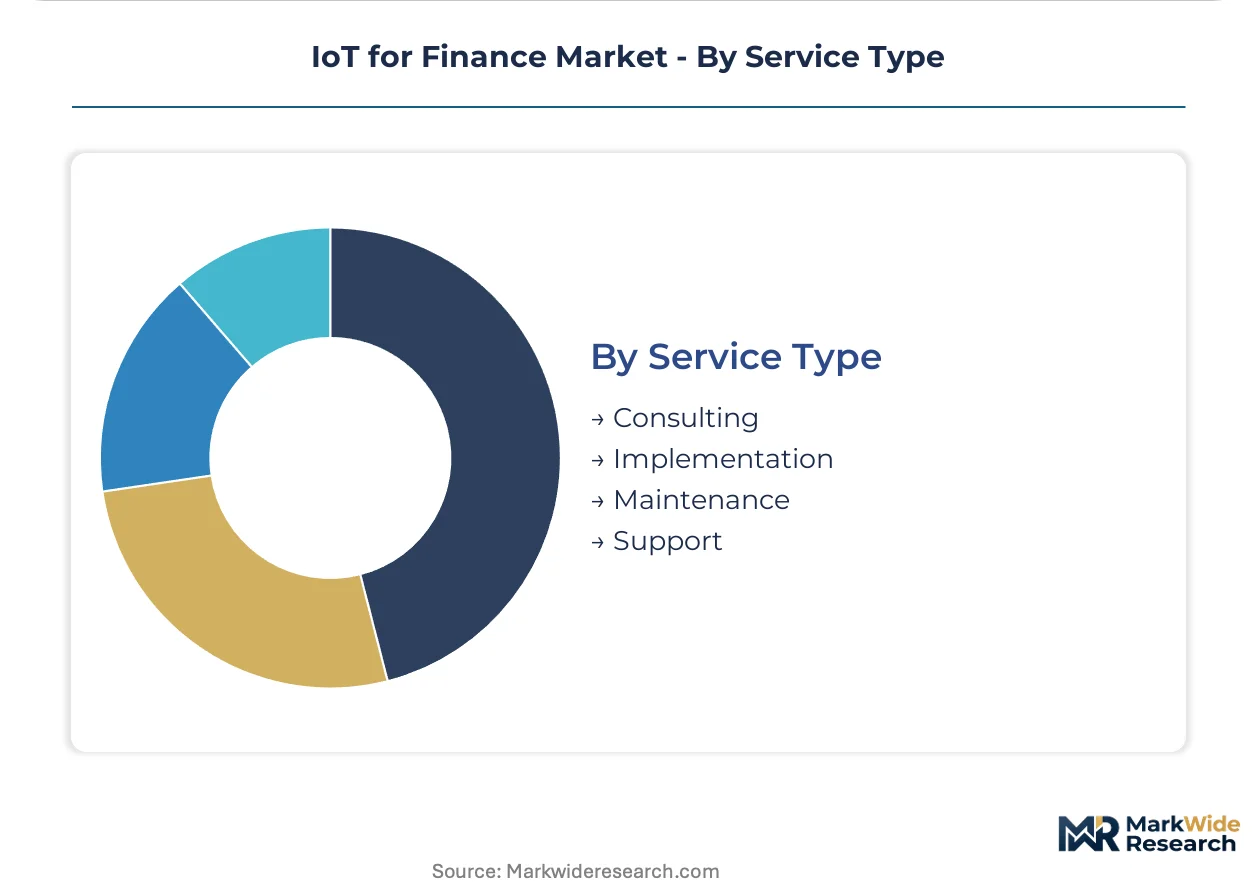
- Implementation:Integration of edge computing nodes, sensor networks, and API orchestration layers into legacy core banking systems. Tier-2 German and Dutch banks pilot ARM-based terminal configurations to compress latency below 50 milliseconds.
- Maintenance:Subscription-based vault sensor telemetry and biometric access control management generate recurring SaaS revenue streams. Hardware vendors transition from capital equipment sales to operational technology subscriptions.
- Consulting:DORA compliance architecture design and multi-jurisdiction certification navigation for cross-border fund distribution networks.
- Support:Firmware update management and quantum-resistant cryptography transition planning for legacy ATM fleets.
Implementation services anchor current revenue, while Maintenance subscriptions are gaining share fastest as vendors pivot to recurring models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers exhibit the lowest price elasticity for branch automation, while Indian institutions demand ruggedized hardware at sub-premium price points. European procurement sits between these poles, prioritizing DORA compliance over cost minimization. This demand-elasticity gradient shapes vendor go-to-market strategies across major financial centers.
United States
FedNow real-time payment infrastructure and card-not-present fraud volumes drive sensor deployment across retail banking networks. The Federal Reserve's operational risk guidelines mandate encrypted endpoint telemetry for all connected devices. New York and Chicago financial corridors anchor enterprise adoption, with regional banks in the Southeast expanding ATM monitoring fleets fastest.
Germany
Tier-2 retail banks pilot ARM-based edge AI configurations to compress transaction latency below 50 milliseconds. The EU's Digital Operational Resilience Act (DORA) compels automated incident reporting and EU-based security operations centers. Frankfurt's concentration of trade finance departments accelerates blockchain-IoT integration for supply chain documentation.
United Kingdom
Open banking API mandates from the Financial Conduct Authority create demand for IoT orchestration layers bridging physical terminals with cloud engines. The FCA's operational resilience rules extend compliance timelines for multi-jurisdiction deployments. London's wealth management clusters drive biometric-enabled branch environments for relationship manager optimization.
India
The Reserve Bank of India's central bank digital currency pilot mandates offline-capable payment devices with local manufacturing content. RBI regulations on digital payment security shape procurement criteria for ruggedized hardware. Mumbai and Bangalore financial technology corridors host design competitions for next-generation IoT payment terminals.
Singapore
Private banking segments generate premium consulting fees for sensor-enabled advisory environments that surface portfolio analytics automatically. The Monetary Authority of Singapore's technology risk management guidelines enforce hardware-layer encryption standards. Singapore's wealth management hub commands the steepest per-client margins for biometric branch automation deployments.
IoT for Finance Market Competitive Environment
Capability concentration sits with specialized edge-networking and mainframe-integration vendors; scale advantage sits with hyperscaler cloud platforms anchoring financial infrastructure. The vendor base stratifies into three tiers: legacy system integrators with decades-long banking relationships, cloud-native platforms capturing open banking workloads, and edge hardware specialists controlling real-time transaction verification. Dominant competitive moves include strategic partnerships between cloud providers and regional system integrators, plus portfolio diversification into quantum-resistant cryptography consulting.
Within the legacy-integration tier, IBM Corporation and Oracle Corporation occupy positions anchored to COBOL-based core banking systems and mainframe-integrated sensor analytics. Microsoft Corporation exemplifies the cloud-native archetype, leveraging Azure infrastructure across North American institutions for API-based compliance. Cisco Systems, Inc. represents the edge-specialist vector, with networking hardware controlling distributed branch locations. These three archetypes collectively capture procurement flows across fraud detection, branch automation, and vault telemetry segments.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Oracle Corporation |
| SAP SE |
| Accenture PLC |
| Capgemini SE |
| Amazon Web Services |
| HCLTech Ltd. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwanese ASIC fabrication determines both pricing tier spreads and supply chain shape for financial IoT deployments. Institutions face stranded asset risk when quantum-resistant cryptography mandates force firmware overhauls across legacy ATM fleets, compressing margins on maintenance subscriptions while elevating premiums for DORA-certified edge hardware.
Pricing Analysis
After-sales service revenue from biometric access control management and vault sensor telemetry drives lifetime value for hardware vendors transitioning from capital equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates DORA-certified EU-based security operations from PCI-DSS baseline configurations and uncertified legacy maintenance tiers. Cost compression in standard-tier edge nodes is intensifying because semiconductor foundry allocation constraints extend delivery timelines for ARM-based payment terminal ASICs. Tier-2 retail banks in Germany and the Netherlands exhibit highest price sensitivity due to compressed project ROI from mainframe integration friction, while Singapore wealth management segments accept premium consulting fees for arrival-detection branch environments.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan-based foundries fabricating specialized ASICs for edge computing nodes, alongside Malaysia and Vietnam facilities assembling ruggedized payment terminals for India's Digital Rupee infrastructure. Raw material dependencies draw from rare earth elements for magnetic sensors, cryptographic secure elements from South Korean fabs, and industrial-grade ARM cores licensed through UK-based IP holders. Single-source vulnerability concentrates in Taiwanese semiconductor fabrication, exposing deployment schedules to geopolitical disruption risks. Distribution runs through regional system integrators with decades-long banking relationships, bypassing direct vendor procurement for legacy mainframe-integrated sensor analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT for Finance market tracks a cyclical recovery as FedNow real-time payment infrastructure deployment accelerates sensor-networked branch automation across United States retail banking networks.
For Market Incumbents:Insulate recurring revenue streams by deepening operational technology management subscriptions for vault sensor telemetry ahead of NIST post-quantum standards forcing firmware overhauls. Acquire edge AI inference specialists with ARM-based system-on-chip designs to preempt GPU cloud dependency displacement in sub-50-millisecond fraud detection configurations.
For New Entrants and Emerging Players:Pursue white-space opportunities in India's central bank digital currency pilot for offline-capable ruggedized hardware with local manufacturing content requirements. Target wealth management advisory robotics in Singapore and Switzerland where sensor-enabled branch environments command premium per-client consulting margins unavailable to established retail banking vendors.
For Investors and Strategic Acquirers:DORA implementation deadlines reshape the acquisition landscape toward vendors with pre-certified EU-based security operations centers and hardware-layer encryption architectures. Long-term viability centers on quantum-resistant cryptography consulting capabilities and mainframe integration middleware expertise. Monitor NIST post-quantum standard finalization as the signal to watch for stranded asset risk inflection across legacy ATM fleet valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Consulting | NIST post-quantum standards force firmware overhauls across legacy ATM and payment terminal installed bases. |
| EU Security Operations Center Establishment | DORA mandates automated incident reporting and hardware-layer encryption for critical ICT providers serving financial institutions. |
| ARM-Based Edge AI System-on-Chip Development | Tier-2 German and Dutch banks pilot sub-50-millisecond inference engines migrating from GPU cloud dependency. |
| India Local Manufacturing Content Partnership | RBI Digital Rupee pilot mandates ruggedized offline-capable payment devices with domestic assembly requirements. |
| Biometric Branch Environment Integration | Swiss and Singapore private banks deploy arrival-detection systems commanding premium relationship manager optimization fees. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief information security officers at United States regional banks, EU compliance architects navigating DORA implementation, edge hardware procurement leads at Indian fintech corridors, and wealth management technology heads in Singapore private banking. Secondary validation drew from Federal Reserve operational risk guideline filings, EU Digital Operational Resilience Act regulatory texts, RBI central bank digital currency pilot documentation, and SEC disclosures from cloud infrastructure providers. Bottom-up triangulation across sensor deployment volumes and top-down reconciliation against platform licensing revenue flows anchored market sizing.
Calibration against historical ATM monitoring fleet expansions and open banking API gateway deployment rates informed trajectory modeling across the analysis window. Segmentation dimensions encompassed application type, technology stack, end-user economics, and service revenue model, with particular attention to latency threshold differentiation between fraud detection and customer analytics use cases. CAGRs were derived from installed base replacement cycles and regulatory mandate enforcement timelines, incorporating FedNow integration schedules and PSD2 compliance deadlines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in central bank digital currency adoption velocity or semiconductor foundry capacity allocation would shift the trajectory. Forecasts reflect assumptions regarding NIST post-quantum cryptography standard implementation pace and EU-based security operations center certification timelines. Quarterly review of regulatory enforcement patterns and edge AI inference engine migration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Hand Account Software Market
FinTech
Autonomous Finance Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Europe Financial Analytics Market
FinTech
Digital Banking Platform Market
FinTech
IT Financial Management Tools Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Australia Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Fintech Lending Market
FinTech
Financial Fraud Detection Software Market
FinTech
Lendtech Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Europe Fintech Market
FinTech
Singapore AI in Fintech Market
FinTech
Germany Fintech Market