
 Europe Used Car Financing Market | 2026-2036
Europe Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Used Car Financing Market Foresight
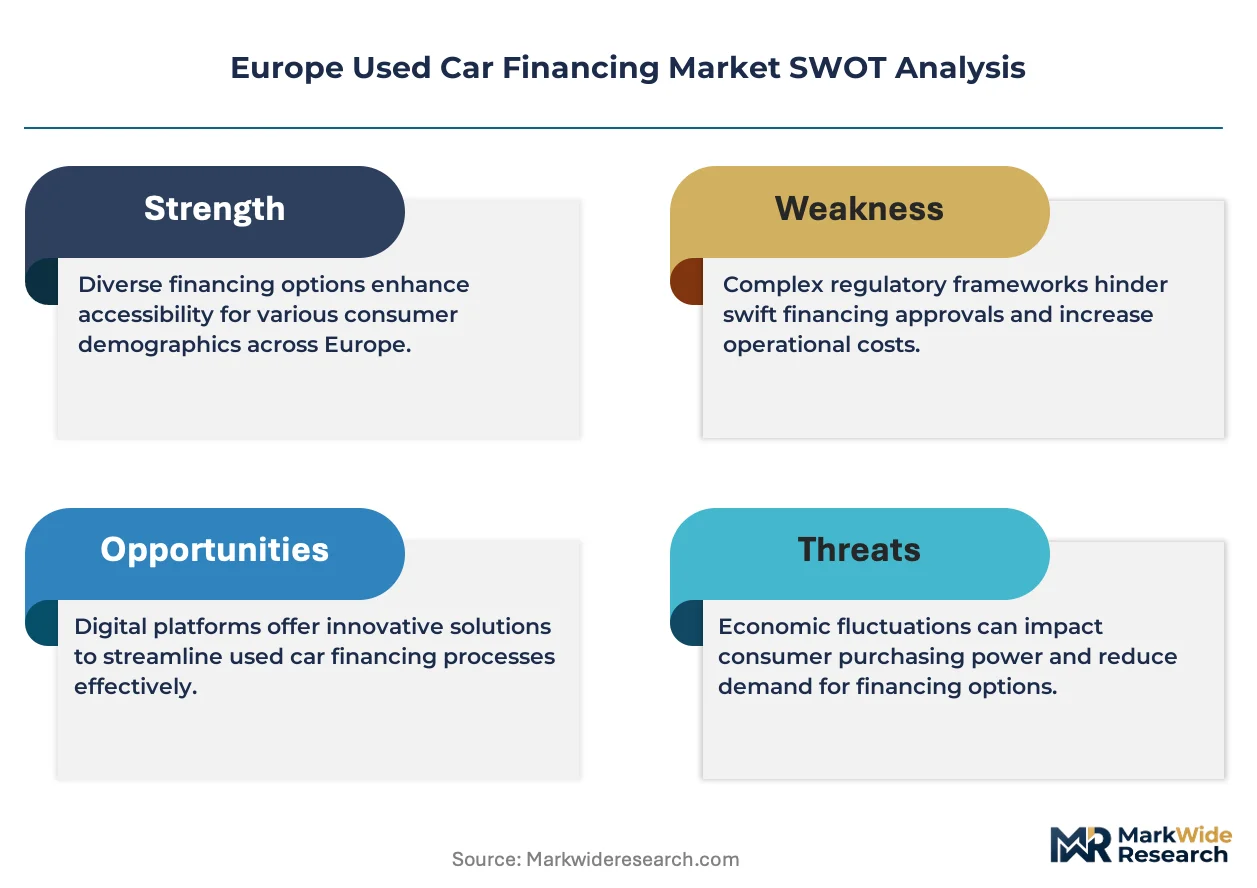
The EU AI Act is restructuring compliance obligations for automated credit-scoring systems deployed by European auto lenders. Volkswagen Financial Services leverages captive finance integration to sustain below-market rate positioning across its dealer network. Santander Consumer Finance competes through pan-European scale, while Lloyds Banking Group anchors its used car lending in direct-to-consumer digital origination.
Used car financing encompasses secured and unsecured credit instruments collateralized by pre-owned vehicles, typically featuring loan-to-value ratios calibrated against depreciation curves and residual value forecasts. Its primary commercial purpose channels liquidity to buyers of vehicles outside original manufacturer warranty coverage, where price depreciation has already absorbed steepest value loss. Dealer financing occupies the dominant origination channel, capturing buyers at point-of-sale with immediate approval workflows and manufacturer-affiliated rate subsidies. Bank loans lead among individual buyers seeking independent rate comparison, while peer-to-peer lending represents the fastest-growing structural segment as platform intermediation reduces origination overhead.
ECB interest rate policy, EBA consumer credit guidelines, and national conduct regulators such as Germany's BaFin collectively shape lending margins, affordability stress-testing, and cross-border passporting rights. The EU Green Deal's vehicle emissions benchmarks further redirect lender collateral preferences toward newer used inventories with verifiable CO2 profiles. Stakeholders must monitor how digital identity frameworks and open banking APIs reshape customer acquisition economics and fraud exposure across fragmented national markets.
Market Dynamics
The EU AI Act is forcing European auto lenders to restructure automated credit-scoring workflows, redirecting technology investment toward explainable algorithmic systems and documented human oversight protocols.
Growth Catalysts
- EU Green Deal vehicle emissions benchmarks:Lenders now collateral-preference newer used inventories with verifiable CO2 profiles, accelerating capital flows toward lower-emission vehicle pools.
- Fleet operator expansion:Logistics and ride-hailing platforms across Germany, France, and the Netherlands represent the fastest-expanding buyer segment, driving structured fleet financing products.
- Open banking API penetration:Real-time income verification and account aggregation are compressing origination timelines from days to minutes across direct-to-consumer channels.
Market Restraints
- ECB interest rate volatility:Sustained monetary tightening has widened lender spreads and compressed loan affordability for subprime borrower segments.
- Residual value forecasting uncertainty:Accelerated electrification timelines and battery degradation curves undermine collateral valuation models for 3-5 year used vehicle loans.
- Cross-border passporting friction:Divergent national interpretations of EBA consumer credit guidelines create compliance overhead for pan-European lenders.
Strategic Opportunities
- Digital identity framework deployment:The EU Digital Identity Wallet initiative enables seamless KYC verification, reducing fraud exposure and customer acquisition costs.
- Peer-to-peer platform intermediation:Marketplace lending models are capturing origination share by eliminating dealer markup and traditional bank overhead.
- Poland and Romania penetration:Underdeveloped used car financing depth in Eastern European markets offers first-mover positioning for scalable digital lenders.
Industry Challenges
- Algorithmic audit capability gaps:Lenders lack sufficient data science talent to implement EU AI Act-mandated bias testing and documentation for automated scoring systems.
- Legacy core system integration:Decades-old loan servicing platforms require expensive middleware development to connect with open banking APIs and real-time payment rails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Used Car Financing Market |
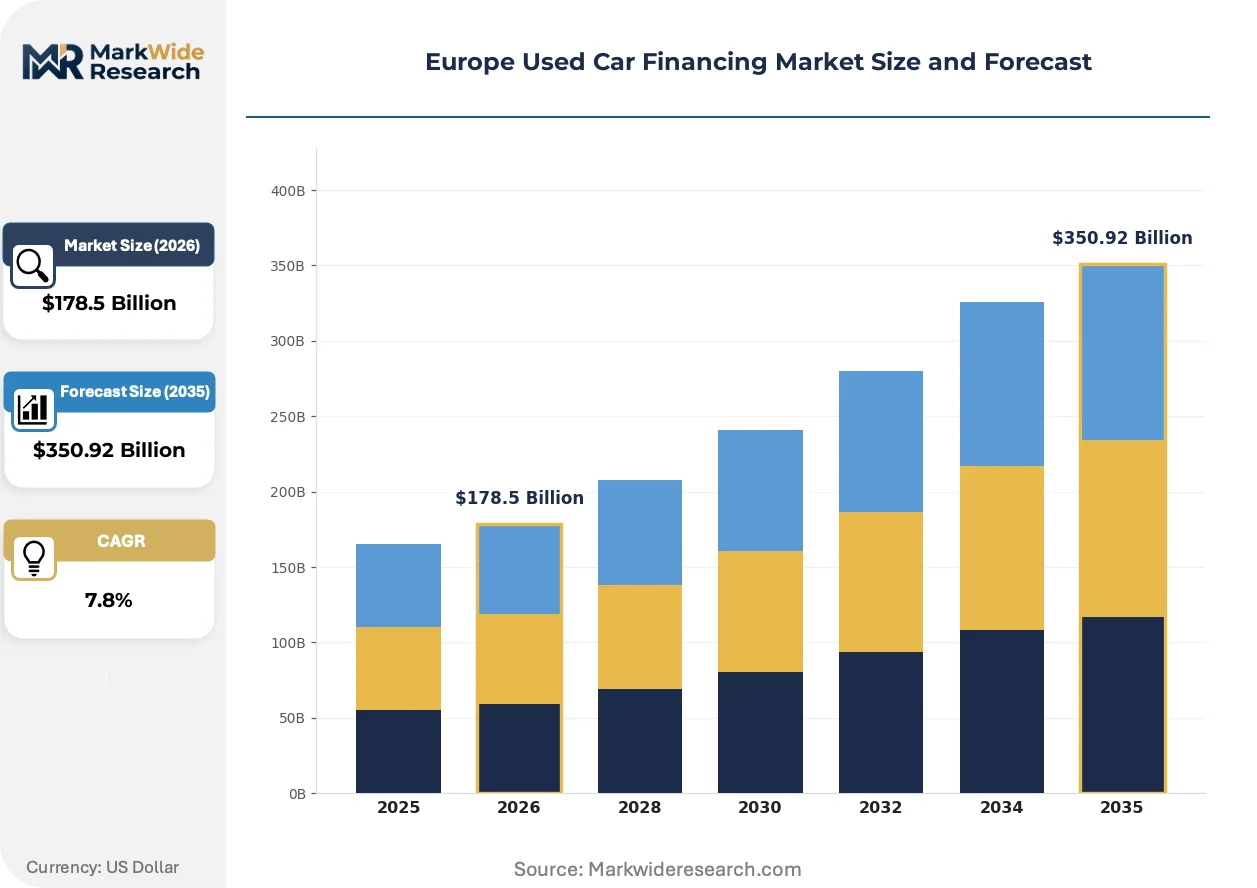
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $350.92 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Bank Loans, Credit Unions, Dealer Financing, Peer-to-Peer Lending Customer Type: Individual Buyers, Fleet Operators, Dealerships, Exporters Loan Term: Short-Term, Medium-Term, Long-Term, Flexible-Term Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate |
| Companies Covered | HSBC Holdings, Ford Motor Credit Company, Volkswagen Financial Services, Lloyds Banking Group, Allianz, BMW Financial Services, Santander Consumer Finance, Axa Bank Belgium, Deutsche Bank, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Used Car Financing Market Shifts & Advancements
Automated underwriting systems are displacing manual credit assessment across European auto finance, while regulatory pressure and shifting buyer preferences are compressing traditional dealer-centric distribution models.
Machine learning-powered risk scoring is automating income verification, employment validation, and payment behavior analysis for used vehicle loan applications. Fleet operators and digital-native lenders in Germany and the Netherlands are adopting these systems fastest, with implementation cycles under six months. This compression of origination workflows is reducing unit economics for traditional dealer-arranged financing and shifting volume toward direct channels.
The EU AI Act's risk-based classification framework mandates human oversight for high-risk automated credit decisions, requiring lenders to maintain explainable algorithmic documentation and audit trails. Volkswagen Financial Services and Santander Consumer Finance are restructuring their scoring architectures to embed mandatory human review checkpoints. This regulatory retrofit is most burdensome for mid-tier lenders with limited compliance infrastructure.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among urban consumers aged 25-40. Fleet operators and mobility platforms are displacing individual buyers as the primary demand source for nearly-new used vehicles, with direct bulk procurement replacing dealer auction channels. This shift is most pronounced in Paris, Berlin, and Amsterdam, where parking constraints and emission zone restrictions favor flexible access over asset ownership.
Europe Used Car Financing Market Segmentation
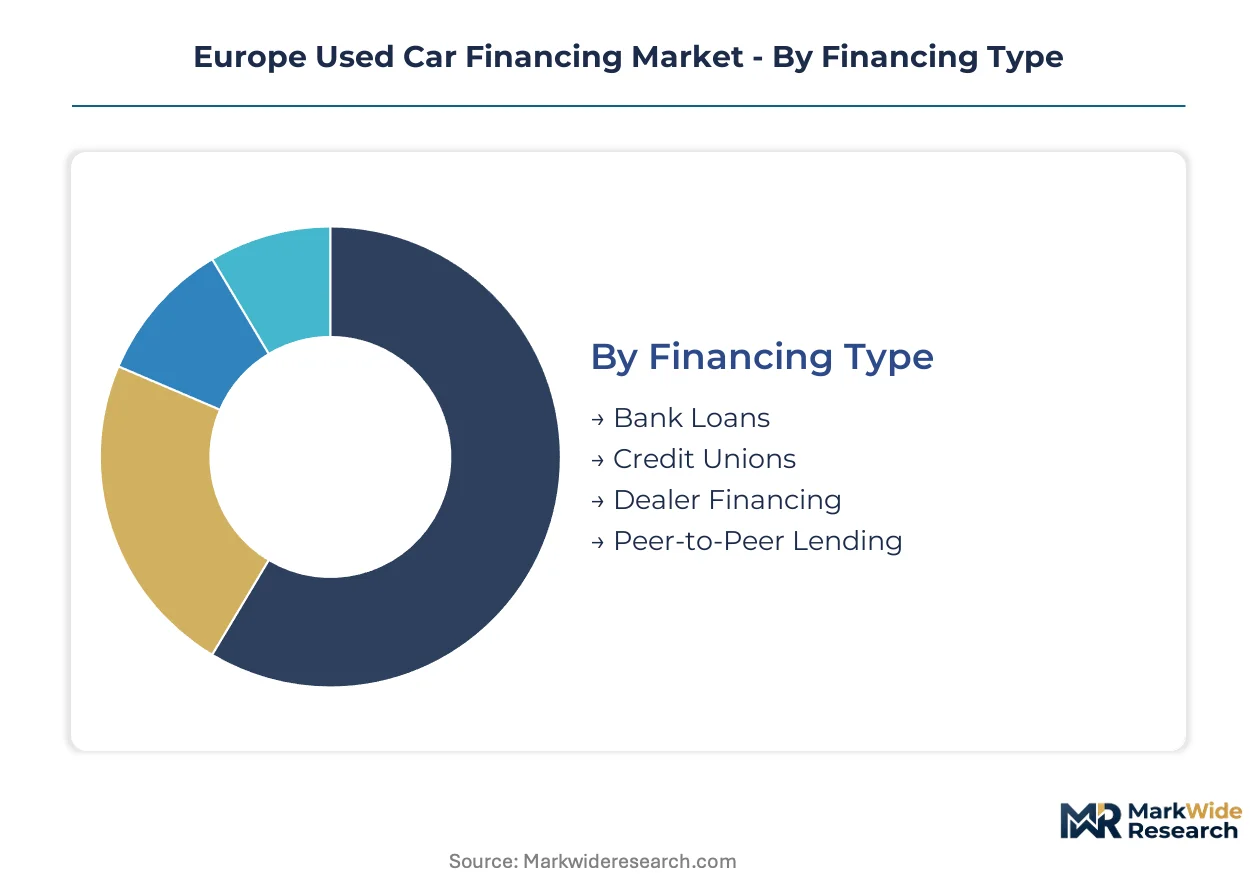
Financing structures in Europe's used car market diverge sharply across origination channels and borrower profiles, with regulatory treatment varying by lender type and loan structure. Understanding these divisions reveals where capital costs concentrate and where digital disruption is rewriting traditional distribution economics.
Financing Type:
ECB capital requirements and national conduct rules from Germany's BaFin to France's ACPR impose tiered compliance burdens that reshape competitive positioning across origination models.
- Bank Loans:Traditional installment credit issued by regulated deposit-taking institutions, typically featuring standardized affordability assessments under EBA consumer credit guidelines. Demand concentrates among German and Dutch individual buyers seeking rate transparency through comparison platforms, constrained by ECB interest rate volatility compressing net interest margins.
- Dealer Financing:Point-of-sale credit arranged through manufacturer-affiliated captives or independent dealer networks, leveraging immediate approval workflows and subsidized promotional rates. Volume leadership rests with Volkswagen Financial Services and similar captive structures integrating vehicle remarketing with loan origination.
- Credit Unions:Member-owned cooperative lenders operating under national mutual banking frameworks, predominantly serving localized borrower pools in France and Italy with relationship-based underwriting.
- Peer-to-Peer Lending:Marketplace platforms matching retail investors directly with borrowers, eliminating intermediary overhead and capturing origination share fastest among digitally-native segments in the Netherlands and UK.
Leading the category by volume: Dealer Financing. Growing fastest: Peer-to-Peer Lending.
Customer Type:
Risk-weighting frameworks and collateral management requirements diverge substantially between retail and commercial borrower segments, driving specialized product architectures.
- Fleet Operators:Logistics and ride-hailing platforms procuring vehicle pools through structured fleet financing with bulk residual value guarantees. German and French logistics firms anchor demand concentration, with electrification mandates under EU Green Deal redirecting procurement toward newer used inventories with verifiable CO2 profiles.
- Individual Buyers:Retail borrowers financing single-vehicle purchases, segmented by credit tier with subprime affordability stress-tested against ECB rate trajectories. Digital origination channels in Germany and UK are displacing branch-based acquisition.
- Dealerships:Independent and franchise dealers securing floorplan financing for inventory acquisition, collateralized by vehicle pools and subject to rapid depreciation risk.
- Exporters:Cross-border traders financing vehicle acquisition for resale in Eastern European and North African markets, navigating divergent national registration and emissions compliance requirements.
Volume concentration: Fleet Operators in Germany and France. Steepest expansion trajectory: Fleet Operators integrating electrified vehicle pools.
Loan Term:
Duration structures reflect depreciation curve alignment and residual value forecasting horizons, with electrification uncertainty compressing preferred terms.
- Medium-Term:36-60 month structures dominating standard used vehicle financing, balancing affordable monthly payments against collateral value retention.
- Short-Term:12-24 month products for near-new vehicles with minimal depreciation exposure, favored by German fleet operators rotating inventory rapidly.
- Long-Term:72-84 month structures extending affordability for higher-priced used electric vehicles, constrained by battery degradation curve uncertainty undermining residual forecasts.
- Flexible-Term:Subscription-linked or mileage-adjusted repayment structures emerging in Dutch and French urban markets, fragmenting traditional ownership patterns.
Dominant structure: Medium-Term. Gaining share fastest: Flexible-Term products tied to mobility subscriptions.
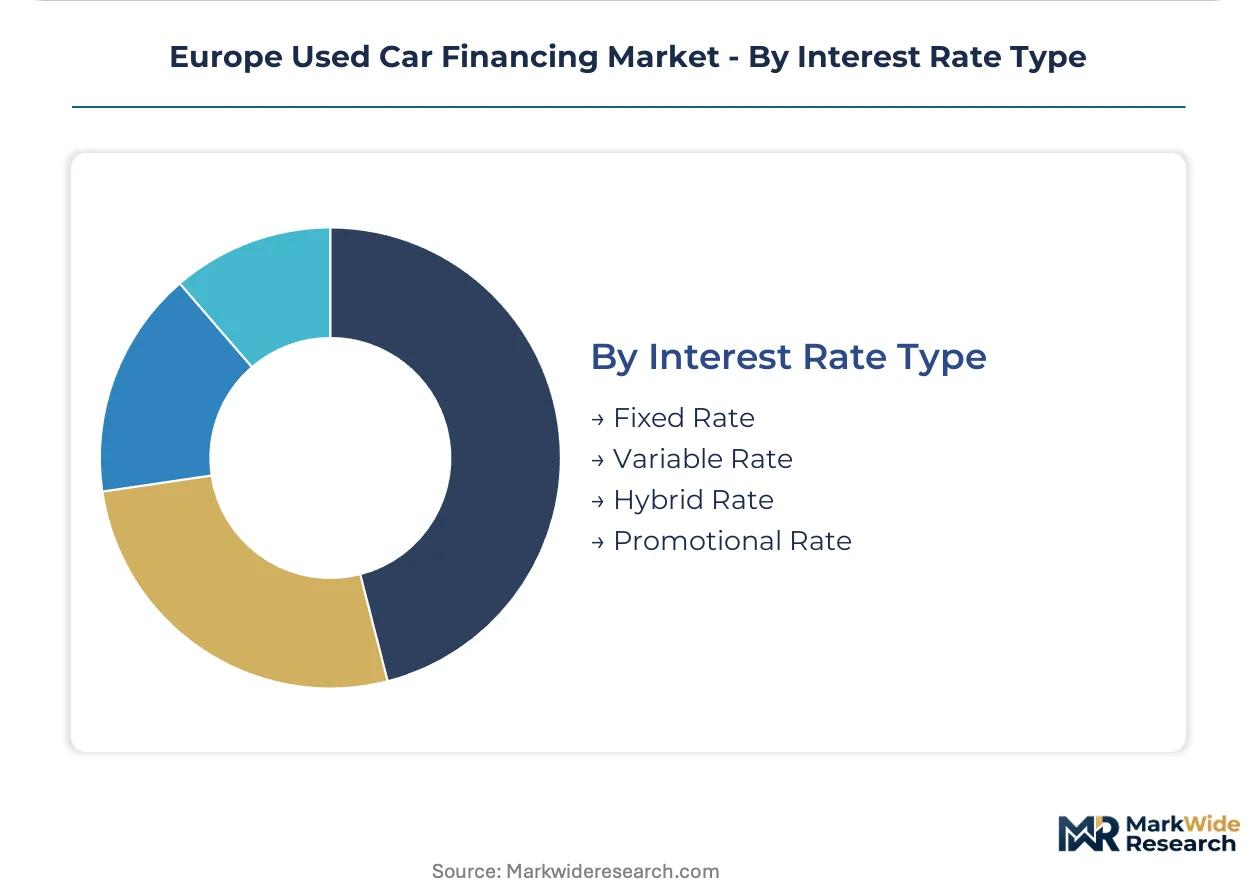
Interest Rate Type:
Monetary policy transmission and hedging capability determine rate structure preferences across borrower risk tiers and lender balance sheet profiles.
- Fixed Rate:Predetermined repayment schedules insulating borrowers from ECB policy volatility, commanding premium pricing in tightening cycles.
- Variable Rate:Euribor-linked structures transferring rate risk to borrowers, concentrated among prime credit segments with absorption capacity.
- Hybrid Rate:Fixed-initial periods converting to variable structures, balancing payment predictability with lender hedging efficiency.
- Promotional Rate:Manufacturer-subsidized teaser rates supporting captive finance volume objectives, prevalent in Volkswagen Financial Services dealer network positioning.
Market standard: Fixed Rate. Expanding most quickly: Hybrid Rate structures as lenders manage duration mismatch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most intensely in Germany, where certified pre-owned vehicle pools and dense banking infrastructure sustain financing depth across the region. France and the Netherlands follow with accelerating fleet operator procurement, while Eastern European markets remain underpenetrated relative to vehicle ownership rates.
Germany
Fleet operators and logistics platforms anchor demand growth, with ride-hailing services expanding structured financing for electrified vehicle pools. BaFin consumer credit guidelines enforce stringent affordability stress-testing across all origination channels. The Stuttgart-Munich corridor hosts Europe's densest concentration of captive finance operations integrating vehicle remarketing with loan underwriting.
France
Subscription-based vehicle access models are fragmenting traditional ownership patterns among Parisian consumers aged 25-40. ACPR conduct rules shape lender disclosure requirements and cross-selling limitations across digital and branch channels. The Île-de-France region concentrates fleet operator procurement platforms redirecting capital toward lower-emission used inventories under EU Green Deal benchmarks.
Netherlands
Open banking API penetration enables real-time income verification compressing origination timelines to minutes. The Dutch central bank's prudential framework governs affordability assessments and interest rate risk management for variable-rate products. Amsterdam anchors the fastest-growing peer-to-peer lending segment as platform intermediation eliminates traditional dealer markup.
United Kingdom
Lloyds Banking Group's direct-to-consumer digital origination anchors competitive positioning among individual buyers seeking rate transparency. FCA consumer credit rules mandate clear disclosure of total cost of credit and cooling-off periods across all channels. London concentrates fintech lenders deploying machine-learning risk scoring to displace traditional dealer-arranged financing.
Poland
Underdeveloped used car financing depth relative to vehicle ownership growth creates first-mover positioning for scalable digital lenders. National conduct regulators apply EBA consumer credit guidelines with jurisdiction-specific interpretations creating compliance navigation requirements. The Warsaw-Łódź corridor concentrates emerging fleet operator demand from logistics firms expanding electrified delivery vehicle pools.
Europe Used Car Financing Market Competitive Landscape
German captives anchor one tier; British and Spanish banking groups hold pan-European scale positions through diversified origination channels. The market structure concentrates around manufacturer-affiliated finance arms with integrated vehicle remarketing capabilities and independent banking groups with digital direct-to-consumer platforms. Three archetypes dominate: captive finance integrating vehicle supply with loan origination, universal banks leveraging deposit funding cost advantages, and marketplace platforms eliminating intermediary overhead. Competitive dynamics center on M&A targeting digital origination capabilities and strategic partnerships embedding open banking APIs into underwriting workflows.
Within the captive finance tier, Volkswagen Financial Services exemplifies manufacturer-integrated origination with below-market rate positioning across dealer networks. Santander Consumer Finance represents pan-European scale deployment through diversified national market penetration. Lloyds Banking Group anchors direct-to-consumer digital origination among British-based banking groups competing on rate transparency and compressed approval timelines.
| Leading Market Players |
|---|
| HSBC Holdings |
| Ford Motor Credit Company |
| Volkswagen Financial Services |
| Lloyds Banking Group |
| Allianz |
| BMW Financial Services |
| Santander Consumer Finance |
| Axa Bank Belgium |
| Deutsche Bank |
| Others |
Supply & Pricing Matrix
Algorithmic underwriting talent clustering in Amsterdam and London widens pricing spreads between premium digital-native lenders and legacy dealer-channel incumbents, with labor-cost differentials compressing margins for mid-tier banks unable to automate income verification workflows.
Pricing Analysis
Volume leadership concentrates with dealer-arranged captive financing while margin capture favors direct-to-consumer digital channels. Three-tier pricing structure across premium algorithmic scoring, standard branch-based assessment, and economy subprime dealer markup dominates origination. Pricing pressure stems from ECB rate volatility compressing net interest margins across variable-rate portfolios. Fleet operators exhibit lowest price sensitivity due to bulk residual guarantees, while subprime individual buyers face steepest affordability stress.
Supply Chain Analysis
Reverse-logistics flows for off-lease vehicle refurbishment and battery health recertification anchor collateral value preservation across German, French, and Dutch remarketing hubs. Vehicle sourcing draws from captive manufacturer lease returns, fleet operator rotation schedules, and dealer auction networks. Single-source vulnerability concentrates in German captive finance arms controlling certified pre-owned vehicle pools. Distribution runs through manufacturer-affiliated dealer networks for individual buyers and direct bulk procurement platforms for fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in European used car financing is becoming a vertical-integration race, with lenders pursuing downstream control over vehicle remarketing and residual value guarantees to lock in origination economics.
For Market Incumbents: Anchor market position through backward integration into certified pre-owned vehicle remarketing infrastructure, defending against fintech lenders deploying real-time open banking APIs. Prioritize compliance infrastructure investment to satisfy EU AI Act audit requirements for automated scoring systems. Capacity addition in Poland and Romania offers geographic diversification from saturated Western European markets.
For New Entrants and Emerging Players: Eastern European fleet operators represent the most penetrable buyer archetype, with underdeveloped financing depth relative to logistics sector expansion. Deploy subscription-linked flexible-term products targeting Dutch and French urban mobility platforms. Go-to-market execution should embed open banking APIs for income verification to compress origination timelines below incumbent benchmarks.
For Investors and Strategic Acquirers: The window for entry favors digital-native lenders with algorithmic underwriting capabilities and scalable Eastern European footprints. Long-term viability hinges on regulatory technology infrastructure capable of EU AI Act compliance and cross-border passporting navigation. Monitor ECB rate trajectory stabilization as inflection signal for leveraged buyout timing in subprime lending portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | Real-time income verification compresses origination timelines from days to minutes across direct channels. |
| Captive Remarketing Infrastructure | Volkswagen Financial Services leverages integrated vehicle pools to sustain below-market rate positioning. |
| EU AI Act Compliance Architecture | Explainable algorithmic documentation mandates reshape technology investment for automated scoring systems. |
| Eastern European Market Entry | Poland and Romania offer first-mover positioning for scalable digital lenders in underpenetrated markets. |
| Flexible-Term Product Development | Subscription-linked repayment structures capture urban mobility platform demand in Amsterdam and Paris. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with auto finance risk officers, dealership operations managers, open banking platform engineers, and fleet procurement directors. EBA consumer credit guidelines, BaFin conduct circulars, and ECB monetary policy statements provided regulatory boundary conditions. Vehicle registration databases and captive finance origination disclosures enabled volume triangulation against bottom-up channel estimates.
Data-stream reconciliation across dealer network origination systems, direct-to-consumer platform metrics, and peer-to-peer marketplace volumes established baseline market sizing. Segmentation dimensions modeled encompass financing type, customer archetype, loan duration structure, and interest rate mechanism across the projection horizon. CAGRs derived from regression analysis against macroeconomic drivers including ECB policy rates, vehicle electrification adoption curves, and fleet operator procurement intensity. Battery degradation forecasting and residual value modeling informed long-term collateral risk assessments.
Revisions become necessary when ECB rate trajectories diverge from baseline assumptions or EU AI Act enforcement timelines accelerate compliance cost burdens. Forecasts reflect assumptions regarding open banking API penetration rates and fleet operator electrification procurement schedules. Practitioners should monitor regulatory technology vendor pricing and algorithmic audit talent availability for early signals of competitive cost structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Student Loan Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
Japan Car Loan Market