
 China Car Loan Market | 2026-2036
China Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
China Car Loan Market Insights
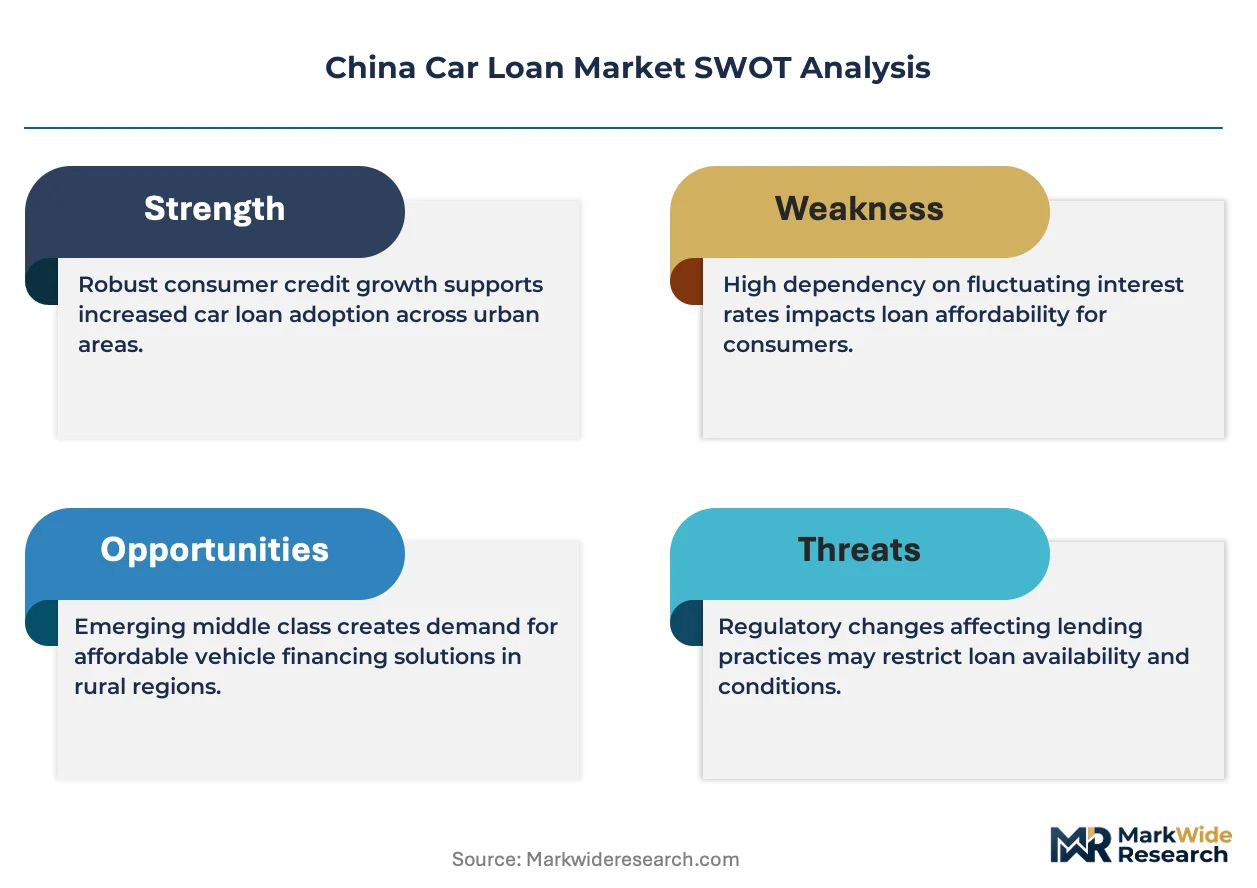
Asset-light leasing models and captive finance restructuring is narrowing the competitive field for traditional banks. Industrial and Commercial Bank of China leverages its branch density across tier-two cities to sustain origination leadership. China Merchants Bank differentiates through digital-first auto loan platforms that reduce approval cycles. Ping An Bank anchors its position via integrated insurance-financing bundles tied to vehicle telematics data.
A car loan constitutes a secured consumer credit instrument collateralized by the financed vehicle, with terms typically spanning twelve to sixty months and interest rates indexed to the People's Bank of China loan prime rate or proprietary risk-based pricing models; its commercial purpose channels household and enterprise liquidity into automotive purchases while generating recurring interest income for lenders. New car loans dominate origination volumes given manufacturer incentive programs and dealer commission structures, while used car loans represent the fastest-expanding segment as certified pre-owned channels mature and residual value transparency improves. Lease financing occupies a specialized niche among corporate clients seeking off-balance-sheet fleet management, with margin pools concentrated in end-of-term residual risk underwriting.
The China Banking and Insurance Regulatory Commission imposes capital adequacy and consumer protection standards that constrain non-bank auto finance company expansion, while the People's Bank of China steers systemic credit conditions through reserve requirement ratios and the loan prime rate mechanism. The National Financial Regulatory Administration's tightening of internet lending rules limits fintech platforms from originating auto loans without banking partnerships. Stakeholders must monitor how dual carbon targets and new energy vehicle subsidy phase-outs reshape collateral valuations and borrower credit profiles across China's provincial markets.
Market Dynamics
The People's Bank of China's loan prime rate reforms and digital credit scoring mandates are compressing approval cycles and flattening lender hierarchies. Traditional branch-based underwriting is giving way to algorithmic risk assessment, forcing incumbents to rebuild core systems or cede origination share to digital-native competitors.
Growth Catalysts
- New Energy Vehicle Subsidies:Dual carbon targets and provincial EV incentive programs are channeling household liquidity into electrified vehicle purchases, expanding the addressable collateral pool for secured auto lending.
- Fleet Digitization:Logistics and ride-hailing platforms are scaling financed vehicle acquisitions as asset-light operating models displace direct ownership among enterprise borrowers.
- Residual Value Transparency:Certified pre-owned certification standards and telematics-driven depreciation models are unlocking used car loan origination previously constrained by collateral uncertainty.
Market Restraints
- Capital Adequacy Requirements:The National Financial Regulatory Administration's prudential standards constrain non-bank auto finance companies from scaling balance sheets independently of banking partnerships.
- Input Cost Volatility:Lithium carbonate and battery-grade nickel price swings are compressing new energy vehicle manufacturer margins, pressuring downstream financing incentives and residual value guarantees.
- Regional Credit Fragmentation:Provincial-level social credit data silos limit cross-jurisdictional underwriting consistency, fragmenting risk pricing across China's interior markets.
Strategic Opportunities
- Telematics-Insurance Convergence:Vehicle usage data streams are enabling usage-based insurance bundles that reduce loss ratios and deepen customer lifetime value for integrated finance providers.
- Tier-Three City Penetration:Underbanked prefecture-level cities in central and western provinces present origination white space for lenders with alternative credit scoring capabilities.
- Green Bond Financing:The People's Bank of China's carbon reduction support facility offers subsidized funding costs for new energy vehicle loan portfolios, compressing net interest margins for qualifying originators.
Industry Challenges
- Legacy Core System Migration:State-owned banks face multi-year timelines to replace COBOL-based loan origination platforms with cloud-native architectures capable of real-time credit decisions.
- Data Privacy Compliance:The Personal Information Protection Law imposes consent-layer complexity on telematics data collection, requiring redesigned customer onboarding workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Car Loan Market |
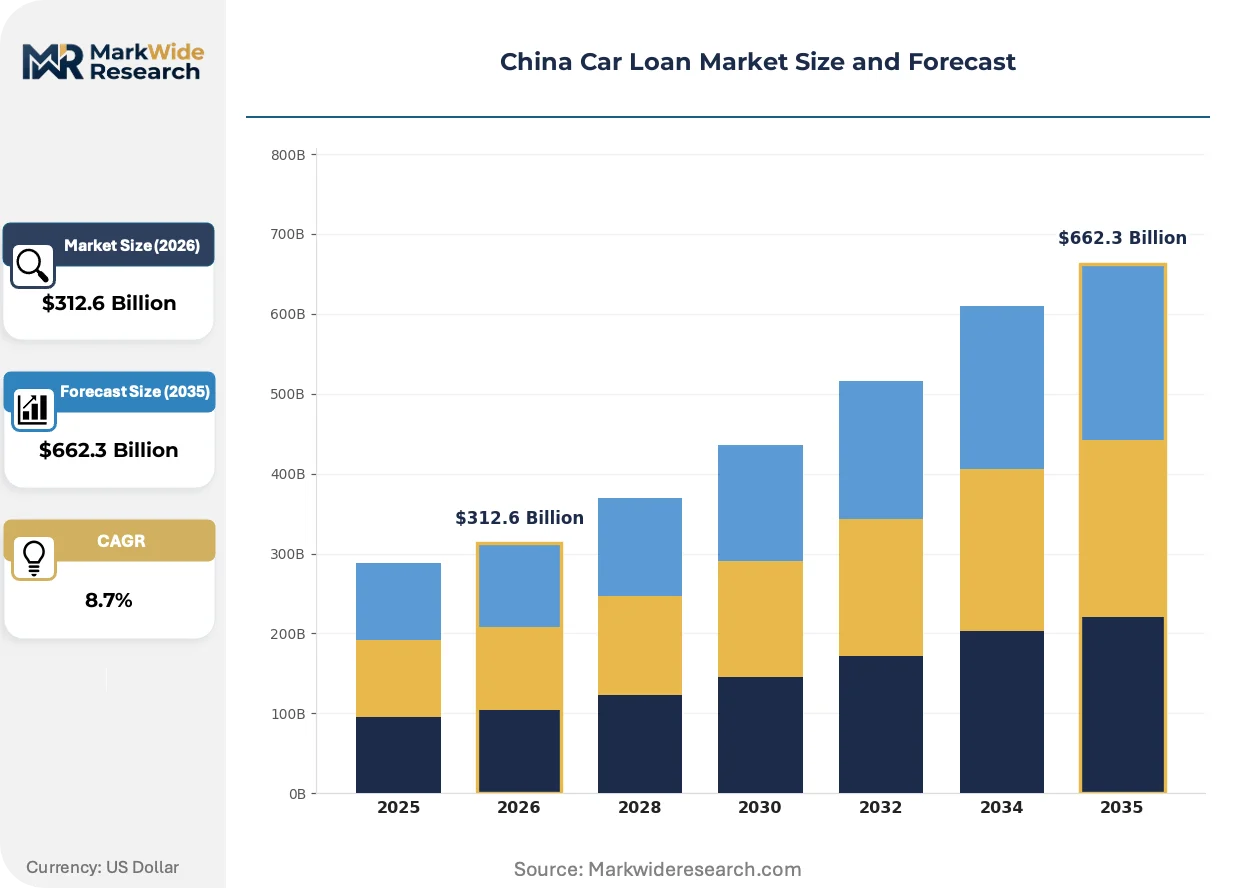
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Individual Borrowers, Fleet Buyers, Corporate Clients, Dealerships Loan Type: New Car Loans, Used Car Loans, Refinancing Loans, Lease Financing Term Duration: Short-Term, Medium-Term, Long-Term, Flexible Terms Interest Rate Type: Fixed Rate, Variable Rate, Tiered Rate, Promotional Rates |
| Companies Covered | Industrial and Commercial Bank of China, China Construction Bank, Bank of China, Agricultural Bank of China, China Merchants Bank, China Minsheng Banking Corp., Ltd., Ping An Bank, Bank of Communications, China Everbright Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Car Loan Market Trends and Innovations
Digital infrastructure and regulatory technology are converging to restructure how auto credit is originated, priced, and serviced. Lenders are rebuilding operating models around data assets rather than branch networks.
Blockchain-enabled smart contracts for vehicle title verification and lien registration are hybridizing traditional secured lending documentation with distributed ledger immutability. Captive finance arms of domestic manufacturers are piloting these systems for fleet transactions. The structural consequence is compressing title clearance timelines from weeks to hours, reducing fraud exposure and collateral recovery friction.
The National Financial Regulatory Administration's tightening of internet lending rules is mandating banking partnership structures for fintech platforms. This regulatory friction is consolidating origination volume toward licensed depositories with compliant balance sheet capacity. Non-bank platforms are responding by deepening API integrations with joint-stock banks rather than pursuing standalone licenses.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among younger urban cohorts. Dealer networks are responding by unbundling sales from financing, creating direct-to-consumer digital channels that bypass showroom intermediation. This shift is most visible in the Yangtze River Delta, where Shanghai-based platforms are capturing lease origination previously dominated by manufacturer captives.
China Car Loan Market Segmentation
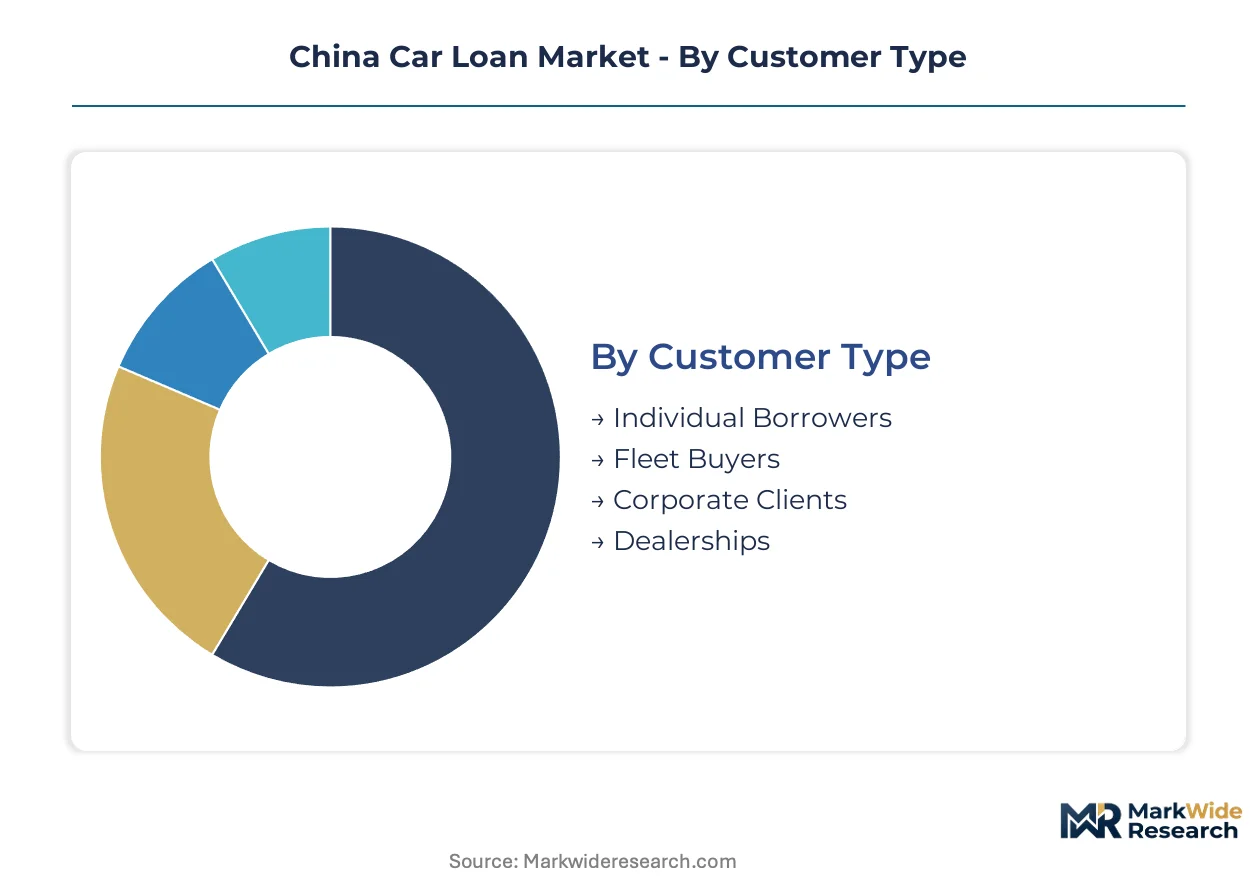
Segmentation in China's auto finance market reflects divergent underwriting economics across borrower profiles and collateral vintages. Lenders optimize capital allocation by matching term structures and rate mechanisms to specific risk-return profiles within each slice.
Customer Type:
Cost tier differentiation separates mass retail origination from specialized commercial underwriting workflows.
- Individual Borrowers:Household applicants present standardized credit bureau profiles and employment verification requirements. Demand concentrates in the Yangtze River Delta, where Shanghai's wage premiums support higher loan-to-value ratios and compressed approval cycles.
- Fleet Buyers:Logistics and ride-hailing operators seek bulk financing arrangements with telematics-linked servicing structures. These borrowers anchor volume in tier-two manufacturing hubs where vehicle utilization rates justify amortization schedules.
- Corporate Clients:Enterprise borrowers leverage balance sheet strength to negotiate off-balance-sheet lease structures.
- Dealerships:Dealer floorplan financing channels inventory liquidity through captive finance arms and joint-stock bank partnerships.
Individual borrowers command the established base. The steepest expansion runs through fleet buyers.
Loan Type:
Application focus distinguishes manufacturer-subsidized new vehicle flows from residual-value-dependent used car channels.
- New Car Loans:Manufacturer incentive programs and dealer commission structures dominate origination economics. The People's Bank of China's loan prime rate mechanism provides the pricing anchor for these standardized products.
- Used Car Loans:Certified pre-owned certification standards and telematics-driven depreciation models are unlocking collateral certainty previously constrained by valuation opacity. Demand is expanding most quickly in provincial capitals where residual value transparency is improving.
- Refinancing Loans:Rate arbitrage opportunities emerge when loan prime rate adjustments create spread advantages for balance sheet restructuring.
- Lease Financing:Corporate clients utilize off-balance-sheet structures for fleet management with end-of-term residual risk underwriting.
New car loans command the established base. The steepest expansion runs through used car loans.
Term Duration:
Volume concentration varies by amortization schedule alignment with vehicle replacement cycles and borrower cash flow patterns.
- Short-Term:Twelve-to-twenty-four month structures serve corporate fleet turnover cycles and high-turnover ride-hailing assets.
- Medium-Term:Thirty-six-month products balance monthly serviceability with total interest burden for mass retail borrowers.
- Long-Term:Sixty-month amortization maximizes affordability for new energy vehicle purchases where battery depreciation curves require extended collateral coverage.
- Flexible Terms:Seasonal payment structures accommodate agricultural and construction equipment financing with irregular revenue patterns.
Medium-term structures command the established base. The steepest expansion runs through long-term products.
Interest Rate Type:
Margin architecture differentiates between policy-linked benchmark products and risk-priced proprietary offerings.
- Fixed Rate:Locked spreads provide certainty for household budgeting and dominate retail origination. The People's Bank of China's loan prime rate reforms have compressed these spreads while flattening lender hierarchies.
- Variable Rate:Prime-linked adjustments transfer policy rate risk to borrowers while protecting lender net interest margins during tightening cycles.
- Tiered Rate:Risk-based pricing stratifies borrowers across credit score bands with social credit system integration enabling granular segmentation.
- Promotional Rates:Manufacturer-subsidized zero-percent offers absorb front-end margin compression to accelerate inventory velocity.
Fixed rate products command the established base. The steepest expansion runs through tiered rate structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in logistics and ride-hailing services concentrate origination demand in manufacturing-intensive provinces, while individual borrowers cluster in coastal wage-premium cities. The Yangtze River Delta anchors national auto finance volumes through Shanghai's dealer network density and Jiangsu's manufacturing supply chains.
Yangtze River Delta
Shanghai and Suzhou manufacturing hubs generate concentrated demand from enterprise fleet operators and high-income retail borrowers. The People's Bank of China's loan prime rate reforms compress approval cycles for digital-first platforms headquartered in the region. Nanjing and Hangzhou fintech clusters are piloting telematics-integrated underwriting systems for new energy vehicle portfolios.
Pearl River Delta
Shenzhen and Guangzhou drive origination through technology sector wage premiums and electric vehicle manufacturer proximity. Guangdong provincial EV subsidy programs channel household liquidity into battery-electric purchases requiring extended-term financing. Dongguan's logistics corridor anchors commercial fleet acquisition volumes for cross-border e-commerce delivery operators.
Beijing-Tianjin-Hebei
State-owned enterprise employees and government contractors form a stable retail borrower base with standardized credit profiles. Beijing municipal vehicle quota restrictions shift demand toward used car channels where certified pre-owned standards are tightening. Tianjin's port logistics infrastructure supports import vehicle floorplan financing for northern dealership networks.
Sichuan-Chongqing
Western interior markets present underbanked origination opportunities for lenders with alternative credit scoring capabilities. Chongqing's automotive manufacturing cluster generates captive finance demand for SAIC and Changan vehicle distribution. Chengdu's consumption-driven economy supports expanding new car loan penetration among first-time vehicle purchasers.
Shandong Peninsula
Qingdao and Yantai port cities concentrate commercial vehicle financing for maritime logistics and agricultural equipment operators. Shandong provincial rural credit cooperatives maintain strong penetration in county-level auto loan markets. Jinan's administrative concentration supports regulatory technology development for social credit system integration in underwriting workflows.
China Car Loan Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where state-owned banks dominate origination volumes through branch density advantages. Joint-stock banks differentiate via digital platform investments that compress approval timelines. Three strategic archetypes define competitive positioning: universal banks leveraging deposit-funded balance sheets, digital-native specialists with algorithmic underwriting capabilities, and captive finance arms of domestic manufacturers. Consolidation pressure manifests through API partnership formations between fintech platforms and licensed depositories, alongside core system modernization investments by legacy institutions.
Among state-owned banking incumbents, Industrial and Commercial Bank of China exemplifies branch-network-driven origination leadership across tier-two city markets. China Merchants Bank occupies a position within the digital-first specialist tier, representing integrated platform strategies that reduce customer acquisition costs. Ping An Bank anchors the insurance-finance convergence archetype, exemplifying bundled product structures that deepen customer lifetime value through telematics data integration.
| Leading Market Players |
|---|
| Industrial and Commercial Bank of China |
| China Construction Bank |
| Bank of China |
| Agricultural Bank of China |
| China Merchants Bank |
| China Minsheng Banking Corp., Ltd. |
| Ping An Bank |
| Bank of Communications |
| China Everbright Bank |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in tier-three city branch networks is compressing net interest margins while accelerating digital platform migration among price-competitive lenders. The People's Bank of China's loan prime rate mechanism transmits policy signals directly into borrower pricing, flattening traditional geographic rate arbitrage.
Pricing Analysis
Cost-plus contracts indexed to the loan prime rate dominate retail auto finance, with spreads tightening as algorithmic underwriting displaces manual credit assessment. Three-tier pricing structure across premium, standard, and economy risk bands stratifies borrowers through social credit system integration. Pricing pressure stems from green bond financing subsidies for new energy vehicle portfolios, which compress margins for qualifying originators. Fleet buyers exhibit lowest price sensitivity due to telematics-linked total cost of ownership models, while first-time individual borrowers in western provinces show highest rate elasticity.
Supply Chain Analysis
Tariff exposure between China and lithium-exporting jurisdictions in South America and Australia dominates raw material cost volatility for electric vehicle collateral valuation. Battery-grade nickel and lithium carbonate supply concentrates in Indonesia, Chile, and the Democratic Republic of Congo, with processing capacity anchored in China and South Korea. Single-source vulnerability in semiconductor chip supply for vehicle telematics systems creates residual value uncertainty. Distribution runs through captive finance arms of domestic manufacturers, joint-stock bank partnerships, and emerging fintech API integrations with licensed depositories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China car loan market functions as a defensive-moat industry where regulatory entrenchment through banking licenses creates durable barriers against unlicensed fintech disruption.
For Market Incumbents: Build data network effects by integrating telematics streams from partnered fleet operators into proprietary risk scoring engines. Deepen vertical integration through captive insurance underwriting tied to vehicle usage data, countering margin compression from green bond financing subsidies. State-owned banks must accelerate core system modernization to defend against digital-native competitors with real-time approval capabilities. For New Entrants and Emerging Players: Tier-three prefecture-level cities in Sichuan and Shaanxi provinces represent the most penetrable entry point, where social credit data silos fragment incumbent underwriting consistency. Alternative credit scoring using utility payment histories and e-commerce transaction patterns unlocks white-space segments. Partner with regional joint-stock banks through API integrations to bypass standalone licensing requirements under National Financial Regulatory Administration rules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital-first auto finance platforms as cloud-native architectures reduce fixed cost structures versus legacy branch networks. Acquisition targets should emphasize algorithmic underwriting capabilities and telematics data partnerships over traditional deposit-funded balance sheets. Monitor loan prime rate spread compression as the inflection signal for portfolio repricing cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Insurance Bundle Launch | Ping An Bank's integrated data streams reduce loss ratios through usage-based pricing models. |
| Green Bond Portfolio Expansion | People's Bank of China carbon reduction facility offers subsidized funding for new energy vehicle loans. |
| Tier-Three City Digital Penetration | Alternative credit scoring unlocks underbanked prefecture-level markets in central and western provinces. |
| Core System Cloud Migration | Industrial and Commercial Bank of China's multi-year timeline reflects legacy COBOL replacement urgency. |
| Captive Finance Restructuring | Manufacturer-owned lenders consolidate origination share as asset-light leasing models displace direct ownership. |
Research Methodology
A spread of perspectives from auto finance product managers, regulatory compliance officers at joint-stock banks, fleet operations directors at logistics platforms, and telematics data scientists converged on the working assumptions. Primary interviews combined with secondary validation from People's Bank of China policy circulars, National Financial Regulatory Administration disclosure filings, and vehicle registration databases. Bottom-up origination volume modeling triangulated against top-down credit stock estimates across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation across customer type, loan type, term duration, and interest rate mechanism modeled throughout the projection horizon. CAGRs derived from cohort-level vintage analysis of repayment performance and collateral depreciation curves. New energy vehicle subsidy phase-out schedules and dual carbon target implementation timelines served as key forecast inputs.
Stress conditions across loan prime rate adjustment bands, lithium carbonate price volatility ranges, and provincial social credit data integration speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology adoption curves. Material shifts in People's Bank of China reserve requirement ratios or internet lending partnership rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
France Auto Loan Market