
 Student Loan Market | 2026-2036
Student Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Student Loan Market Analysis
Refinancing activity is reshaping margin-pool migration between origination and portfolio retention in the student loan sector. SoFi leverages technology-driven underwriting to capture creditworthy graduates seeking lower rates. Nelnet sustains servicing dominance through its federal contract infrastructure. Sallie Mae anchors private loan origination with direct-to-student marketing channels.
A student loan constitutes a term debt instrument issued to finance post-secondary education expenses, typically carrying repayment obligations that commence after a grace period following graduation or separation from enrollment. Federal loans originate through government-guaranteed programs with standardized interest rates and borrower protections, while private loans rely on credit-based pricing from bank and non-bank lenders. Federal loan programs command the largest outstanding balance pool, though refinancing loans represent the fastest-growing segment as borrowers seek rate reduction in rising-rate environments. Income-driven repayment plans now capture expanding enrollment share as borrowers prioritize payment flexibility over amortization speed.
The US Department of Education governs federal loan origination, servicing standards, and income-driven repayment frameworks that determine servicer compensation structures and borrower eligibility criteria. The Consumer Financial Protection Bureau enforces disclosure requirements and pursues enforcement against deceptive lending practices in private student lending. State attorneys general in New York, California, and Massachusetts have augmented federal oversight with borrower-protection statutes that constrain collection practices and refinancing solicitations. Stakeholders must monitor regulatory shifts in forgiveness eligibility thresholds and servicing fee structures that could redistribute profitability across origination, servicing, and refinancing activities.
Market Dynamics
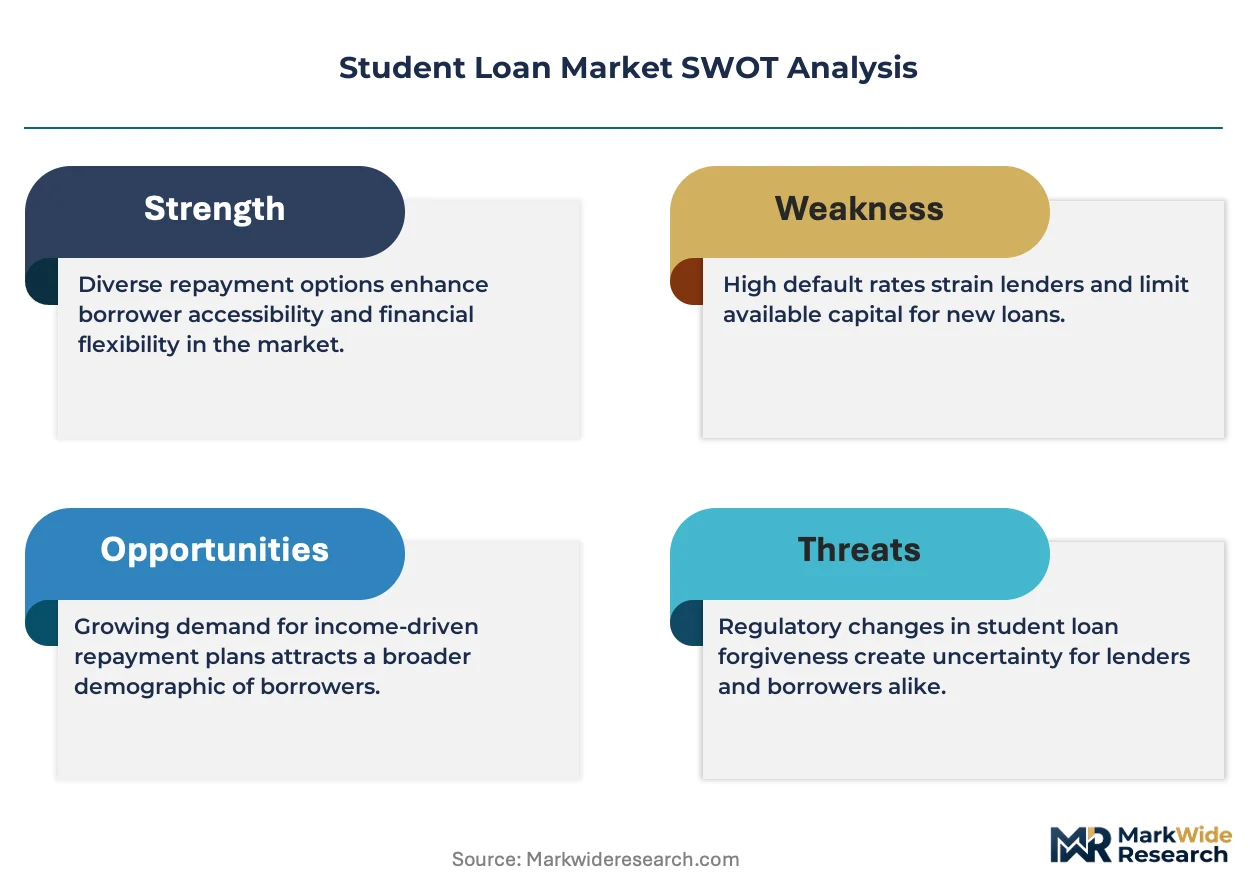
Income-driven repayment frameworks from the US Department of Education are restructuring borrower obligations and compressing servicer revenue models across the federal loan portfolio.
Growth Catalysts
- Graduate Enrollment Expansion:Post-baccalaureate programs at research universities are driving borrowing volume as professional degree costs escalate. Master's and doctoral candidates represent concentrated origination growth.
- SAVE Plan Enrollment:The US Department of Education's newest income-driven repayment option reduces monthly obligations and accelerates forgiveness timelines. Borrower uptake is expanding the addressable pool of refinancable federal debt.
- Credit-Based Underwriting Automation:Alternative data integration from fintech platforms is streamlining private loan approvals. Employment verification APIs and cash-flow analytics are compressing decision timelines.
Market Restraints
- Servicing Fee Compression:Federal contracts from the Department of Education impose fixed per-borrower compensation that fails to scale with portfolio complexity. Revenue per account is declining as forbearance and income-driven plan administration intensifies.
- Interest Rate Volatility:Private loan pricing benchmarks tied to SOFR and Prime expose lenders to margin compression during tightening cycles. Hedging costs erode net interest margins on fixed-rate refinancing products.
- Regulatory Forgiveness Uncertainty:Executive branch policy shifts on Public Service Loan Forgiveness eligibility create balance sheet unpredictability. Servicers face retroactive payment recounting and borrower dispute volume spikes.
Strategic Opportunities
- Employer-Sponsored Repayment:Corporate benefits platforms are integrating student loan contribution tools as retention mechanisms. HR technology vendors represent an underpenetrated distribution channel for refinancing referrals.
- International Student Lending:Non-US domiciled applicants at American universities face limited credit access without domestic co-signers. Specialized underwriting for high-earning graduate programs offers origination white space.
- State-Based Refinancing Authorities:Municipal bond-financed programs in states like Rhode Island and Minnesota offer below-market rate products. Partnership structures with state treasuries provide funding cost advantages.
Industry Challenges
- Borrower Servicing Transitions:Federal contract reassignments between servicers trigger payment processing disruptions and customer service backlogs. Data migration between legacy mainframe systems requires multimillion-dollar integration investments.
- Compliance Documentation Burden:Income recertification for income-driven plans demands annual tax transcript verification. Servicer call center staffing must scale cyclically with enrollment deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Student Loan Market |
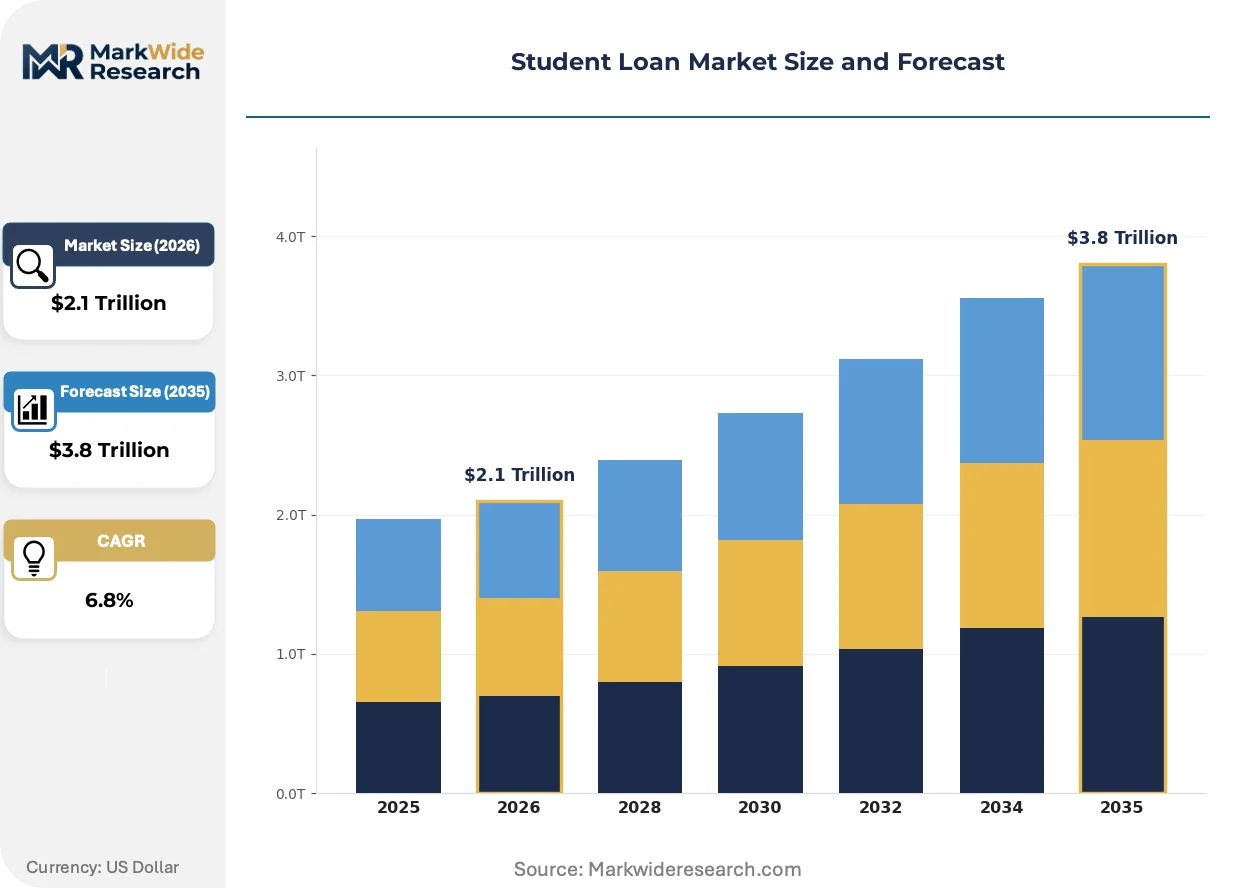
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.8 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Federal Loans, Private Loans, Consolidation Loans, Refinancing Loans Borrower Type: Undergraduates, Graduates, Parents, Professionals Interest Rate Type: Fixed Rate, Variable Rate, Subsidized, Unsubsidized Repayment Plan: Standard Plan, Income-Driven Plan, Graduated Plan, Extended Plan |
| Companies Covered | Ascent, Nelnet, SoFi, MPower Financing, ELFI, Sallie Mae, Earnest, Citizens Bank, College Ave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Student Loan Market Emerging Trajectories
Digital infrastructure is compressing origination costs and enabling real-time borrower decisioning across both federal and private loan channels.
Artificial intelligence-powered underwriting engines are virtualizing traditional credit assessment workflows. Fintech platforms deploy machine learning models that incorporate employment history and educational attainment alongside FICO scores. Graduate degree holders in high-earning fields receive instant rate quotes without manual document submission. This capability is virtualizing the role of loan officers and collapsing the origination timeline from weeks to minutes.
The US Department of Education's Fresh Start initiative for defaulted borrowers is reshaping collection and rehabilitation protocols. Eligible accounts regain access to income-driven repayment and forgiveness tracks upon enrollment. Servicers must reconfigure default outreach operations and retrain collection staff on compliance requirements. The policy shift is forcing portfolio reclassification and reserve adjustments across federal contractors.
Borrowers are consolidating multiple federal loans through direct-to-consumer refinancing platforms rather than servicer-retained consolidation. Digital comparison tools display real-time rate savings across competing lenders. Medical and legal professionals with stable income trajectories represent the most active segment. This behavior is most pronounced in high-cost metropolitan areas where loan balances exceed regional income medians.
Student Loan Market Segmentation
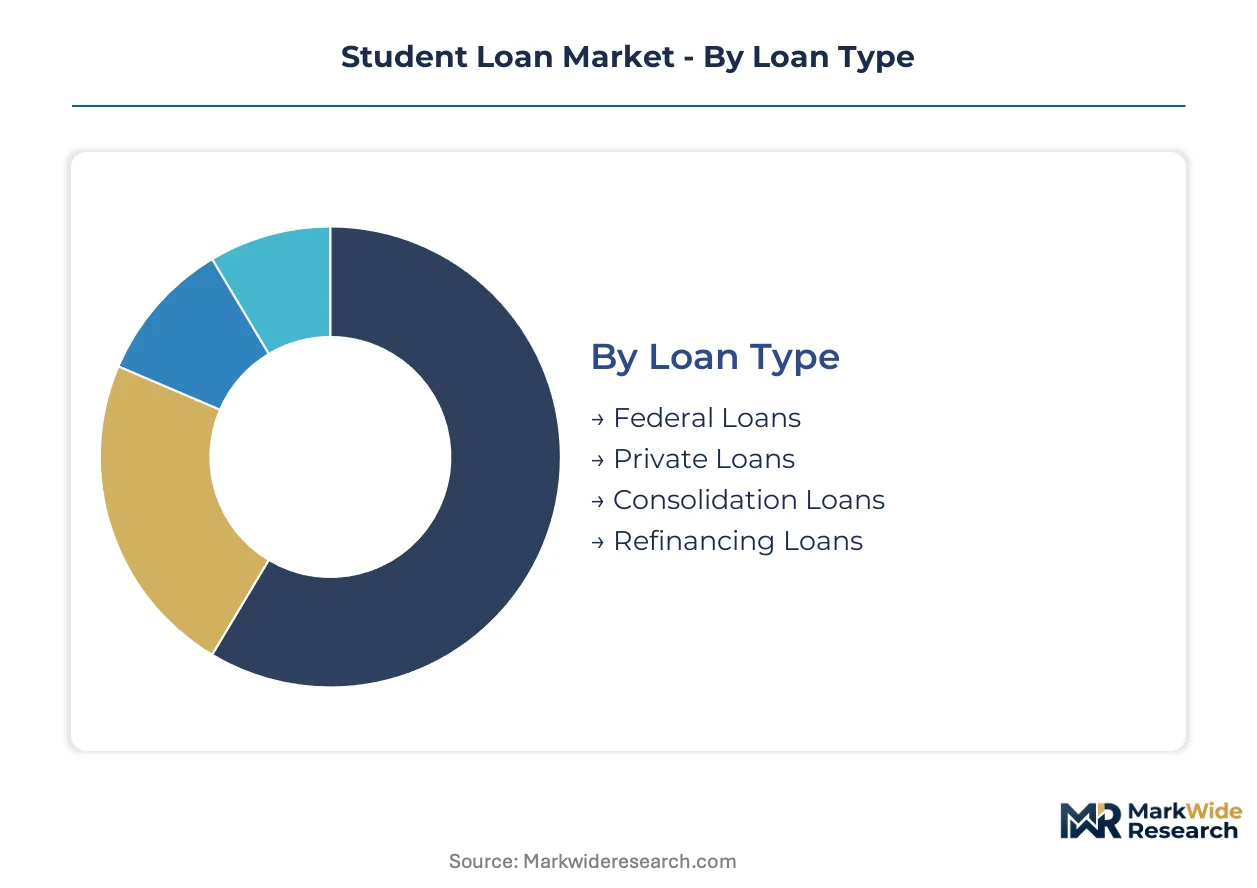
Segmentation in the student loan market determines servicer resource allocation, pricing model selection, and regulatory compliance burden. Borrower characteristics and loan structures dictate repayment behavior patterns and refinancing propensity across portfolio pools.
Loan Type:
After-sales service intensity varies dramatically across loan origination channels, with federal contracts demanding perpetual borrower support while private loans require credit monitoring infrastructure.
- Federal Loans:Government-guaranteed instruments carry standardized interest rates and income-driven repayment eligibility. The US Department of Education originates these through the Direct Loan Program, with servicing contracts awarded to specialized vendors. Borrower protections including deferment, forbearance, and forgiveness tracks create ongoing administrative complexity throughout the loan lifecycle.
- Private Loans:Credit-based instruments from bank and non-bank lenders feature variable pricing tied to borrower FICO scores and co-signer status. Sallie Mae and Discover Education Loans dominate origination through direct-to-student marketing channels. Demand concentrates among borrowers exhausting federal aid limits at high-tuition institutions.
- Consolidation Loans:Federal Direct Consolidation combines multiple federal obligations into a single instrument with weighted average rates.
- Refinancing Loans:Private market products replacing existing obligations with new credit-based terms.
By volume, Federal Loans lead. By growth pace, Refinancing Loans are expanding most quickly.
Borrower Type:
Cost tier segmentation aligns underwriting sophistication with lifetime value expectations across educational attainment levels.
- Graduates:Master's and doctoral candidates at research universities generate the highest per-borrower origination volumes as professional degree costs escalate. Medical and legal students at institutions like Harvard and Stanford represent concentrated demand for jumbo private loans exceeding federal limits. SoFi targets this segment with employment-verification APIs and cash-flow analytics.
- Professionals:Post-graduate degree holders in stable high-earning fields exhibit the strongest refinancing conversion rates. Physicians and attorneys in metropolitan markets leverage digital comparison platforms to capture rate savings unavailable through federal consolidation.
- Undergraduates:First-time borrowers at four-year and community colleges form the largest absolute population.
- Parents:PLUS loan borrowers financing dependent education face distinct credit evaluation standards.
Undergraduates dominate absolute borrower counts. Professionals deliver the steepest expansion trajectory for refinancing originators.
Interest Rate Type:
Margin structure separates subsidized federal products from market-priced alternatives, with hedging costs eroding profitability on fixed-rate commitments.
- Fixed Rate:Instruments locking rates at origination protect borrowers against SOFR and Prime benchmark volatility. Private lenders face margin compression during tightening cycles as funding costs rise against static receivable yields. Borrowers in rising-rate environments prioritize payment predictability over potential variable savings.
- Variable Rate:Products repricing quarterly or monthly expose borrowers to payment fluctuation in exchange for initial rate discounts. SoFi and other fintech platforms market these to creditworthy graduates expecting rapid principal reduction. Demand concentrates among borrowers with income trajectories supporting accelerated amortization.
- Subsidized:Federal need-based products with government-paid interest during enrollment and grace periods.
- Unsubsidized:Federal non-need instruments accruing interest from disbursement.
Fixed Rate products command the largest outstanding balance. Variable Rate offerings are gaining share fastest among refinancing platforms.
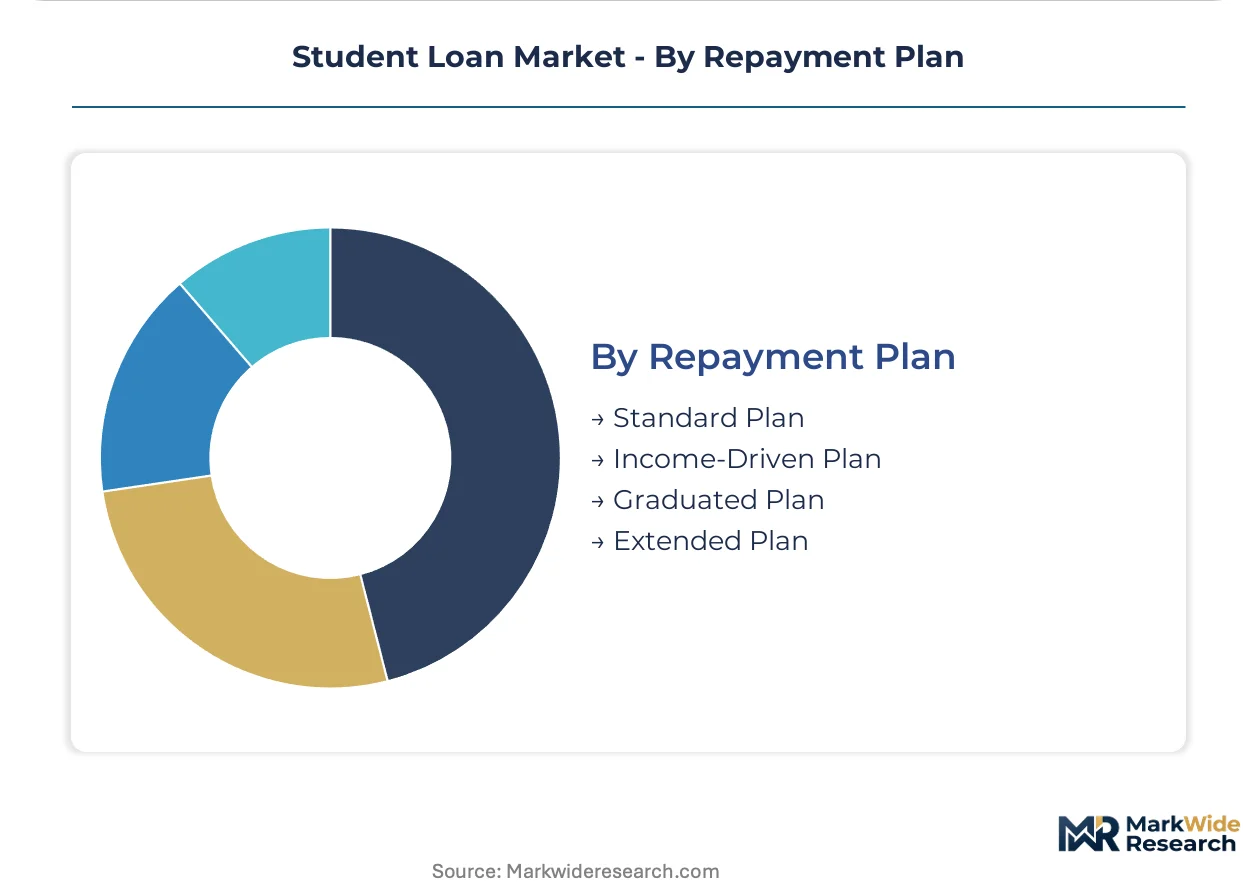
Repayment Plan:
Administrative complexity escalates with income verification requirements, driving servicer staffing models and technology investments.
- Income-Driven Plan:Frameworks including SAVE, PAYE, and REPAYE tie monthly obligations to discretionary income percentages. The US Department of Education's newest SAVE option reduces payments and accelerates forgiveness timelines. Nelnet and other federal contractors must scale call center operations cyclically with annual recertification deadlines.
- Standard Plan:Level amortization over ten years minimizes total interest cost for borrowers with stable employment. This structure dominates private loan servicing where forgiveness tracks do not apply. Servicer revenue per account runs highest here due to minimal forbearance and administrative intervention.
- Graduated Plan:Payment schedules starting low and increasing biennially.
- Extended Plan:Term stretching up to twenty-five years for high-balance federal borrowers.
Standard Plan retains the largest enrolled population. Income-Driven Plan enrollment is climbing the fastest as borrowers prioritize payment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal loan origination infrastructure and refinancing platform development cluster heavily in the United States, where regulatory frameworks and capital market depth create unmatched scale. Other national markets operate smaller programs with distinct funding mechanisms and borrower protections.
United States
Graduate enrollment at research universities and professional schools drives the highest per-borrower origination volumes globally. The US Department of Education administers the Direct Loan Program and sets servicing standards through federal contracts. Nelnet maintains servicing operations in Lincoln, Nebraska, processing income-driven repayment recertifications for millions of accounts.
United Kingdom
Income-contingent repayment plans administered by the Student Loans Company capture nearly all domestic higher education borrowing. The UK government's repayment threshold adjustments and interest rate caps determine servicer revenue stability. London-based fintech platforms have begun exploring cross-border refinancing products for UK graduates working in US markets.
Germany
State-backed KfW student loan programs coexist with private bank offerings, though overall indebtedness remains lower than Anglo-Saxon markets. Federal Education and Research Ministry regulations govern interest subsidy eligibility and income verification requirements. Bavarian technical universities and Baden-Württemberg engineering institutes generate concentrated demand for living-expense financing.
Australia
The Higher Education Loan Programme provides income-contingent funding indexed to inflation rather than market rates. Australian Taxation Office collection mechanisms integrate repayment with income tax withholding. Sydney and Melbourne professional services clusters produce graduates with refinancing demand as they enter high-salary employment tracks.
Canada
Provincial-federal partnership structures split loan administration between national and regional authorities. Canada Student Loans Program integration with provincial systems creates servicing complexity across Ontario, British Columbia, and Quebec. Toronto's financial sector hosts private refinancing entrants targeting medical and legal graduates from Canadian universities.
Student Loan Market Vendor Landscape
Technology-enabled refinancers and legacy federal contractors split the market between rapid digital acquisition and servicing infrastructure retention. The competitive map shows moderate concentration at the origination layer with fragmentation across servicing operations. Two strategic archetypes dominate: fintech platforms deploying automated underwriting engines, and incumbent servicers holding federal contract relationships. Competitive moves center on API-based employment verification partnerships and state refinancing authority alliances.
Within the federal servicing tier, Nelnet exemplifies contract-dependent revenue models built on Department of Education relationships. Among technology-driven refinancers, SoFi and Earnest occupy positions defined by cash-flow analytics and instant rate-quoting infrastructure. Sallie Mae anchors the private origination segment through direct-to-student marketing channels at high-tuition institutions.
| Leading Market Players |
|---|
| Ascent |
| Nelnet |
| SoFi |
| MPower Financing |
| ELFI |
| Sallie Mae |
| Earnest |
| Citizens Bank |
| College Ave |
| Others |
Supply Flow & Price Mechanics
Nebraska's servicing infrastructure cluster anchors federal loan administration capacity, concentrating operational expertise that shapes downstream pricing power for portfolio retention and refinancing origination. The state's concentration of Department of Education contract holders creates regional labor market tightness in specialized collections and income-driven plan administration, directly feeding into per-account cost structures that lenders must recover through spread pricing.
Pricing Analysis
Extended servicing contracts drive lifetime value more than origination fees in federal loan portfolios. Three-tier pricing structure across premium refinancing rates for creditworthy professionals, standard consolidation products, and economy-tier income-driven plans captures borrower segmentation. Cost compression in variable-rate refinancing is intensifying because SOFR benchmark volatility erodes hedged margin assumptions. Undergraduates exhausting federal aid limits exhibit highest price sensitivity, while medical and legal graduates with verified employment trajectories accept premium fixed-rate premiums for payment certainty.
Supply Chain Analysis
Tariff exposure between capital markets and funding structures dominates supply chain risk for private student lenders dependent on securitization flows. Funding draws from institutional ABS investors, warehouse credit facilities, and municipal bond programs in Rhode Island and Minnesota. Single-source vulnerability concentrates in credit bureau data providers and employment verification API vendors. Distribution runs through direct-to-consumer digital platforms, university financial aid offices, and employer-sponsored benefits channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Income-driven repayment plan expansion represents an early-cycle penetration story. SAVE plan enrollment acceleration creates a structural tailwind for refinancing addressable market growth as borrowers regain current-status eligibility.
For Market Incumbents: Pre-empt fintech platform encroachment by embedding employment-verification APIs directly into federal servicing workflows. Lock in multi-year university channel exclusives before digital-native competitors capture graduate school origination. Nelnet's contract infrastructure advantage erodes if SoFi scales direct-to-student marketing at top-50 research institutions. For New Entrants and Emerging Players: Build out international student lending infrastructure targeting Indian and Chinese graduate applicants at STEM-focused universities lacking domestic co-signer networks. Employer-sponsored repayment benefits represent the most penetrable white space, with HR technology partnerships offering embedded distribution. White-label servicing for state refinancing authorities provides funding cost advantages without balance sheet construction. For Investors and Strategic Acquirers: Carve-out targets emerge from bank holding companies divesting non-core education finance subsidiaries amid regulatory capital pressure. Long-term viability hinges on servicing contract renewal timing and refinancing platform technology depreciation cycles. Watch Department of Education contract reassignments as inflection signals for federal servicer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Employment Verification Partnership | SoFi's instant rate-quoting infrastructure compresses decision timelines from weeks to minutes for creditworthy graduates. |
| State Refinancing Authority Alliance | Municipal bond-financed programs in Minnesota deliver below-market funding costs through treasury partnership structures. |
| Employer Benefits Platform Integration | Corporate retention mechanisms channel refinancing referrals through underpenetrated HR technology vendor networks. |
| Income-Driven Plan Servicing Scale-Up | Nelnet's cyclical call center staffing aligns with annual SAVE recertification deadlines from the Department of Education. |
| International Student Underwriting Development | MPower Financing's specialized models capture high-earning graduate program demand without domestic co-signer requirements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Department of Education servicing contract disclosures, Consumer Financial Protection Bureau complaint databases, and Federal Reserve consumer credit reports. Interviews with federal loan servicer operations executives, private lender underwriting heads, university financial aid directors, and fintech platform product managers grounded operational assumptions. Secondary validation drew from SEC 10-K filings of publicly traded education lenders, National Student Loan Data System enrollment statistics, and credit bureau aggregated origination flow data. Bottom-up account-level projections triangulated against top-down market size estimates from macroeconomic education expenditure trends.
Forecast inputs include graduate enrollment trajectories at research universities, SAVE plan uptake velocity, refinancing conversion rates by borrower credit tier, and federal servicing contract renewal schedules. Segmentation dimensions modeled span loan type, borrower educational attainment level, interest rate structure, and repayment plan enrollment status. CAGRs derived from historical origination volume patterns projected through enrollment elasticity assumptions and policy implementation timelines. Interest rate environment scenarios and forgiveness eligibility threshold adjustments fed sensitivity analysis across the projection horizon.
Practitioners should monitor Department of Education regulatory bulletins and servicing fee structure revisions for early signals of contract profitability redistribution. Forecasts reflect assumptions about income-driven plan enrollment permanence and refinancing market share stability that executive branch policy shifts could materially revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
UK Car Loan Market
Loans and Leasing
China Home Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Australia Automotive Financing Market