
 USA Home Loan Market | 2026-2036
USA Home Loan Market Size, Share, and Industry Trends Forecast 2026-2036
USA Home Loan Market Insights
Regional bank lending capacity across the Southeast and Southwest is recalibrating after two years of balance-sheet contraction, redirecting mortgage liquidity toward correspondent channels. Rocket Mortgage leverages its digital origination platform to sustain application volumes with minimal branch infrastructure. JPMorgan Chase Bank anchors prime jumbo distribution through its private banking network. U.S. Bank competes in the construction-to-permanent segment where builder relationships differentiate regional capture.
A home loan constitutes a secured debt instrument collateralized by residential real property, typically structured with amortization schedules spanning fifteen to thirty years and governed by lien priority recorded through county-level title systems. Fixed-rate products dominate the loan-type segment due to borrower preference for payment certainty, while FHA-backed originations lead among first-time homebuyer channels where down-payment flexibility expands qualification pools. The purpose segment tilts toward purchase activity in supply-constrained metros, though refinance volumes fluctuate with rate volatility and home-equity accumulation cycles.
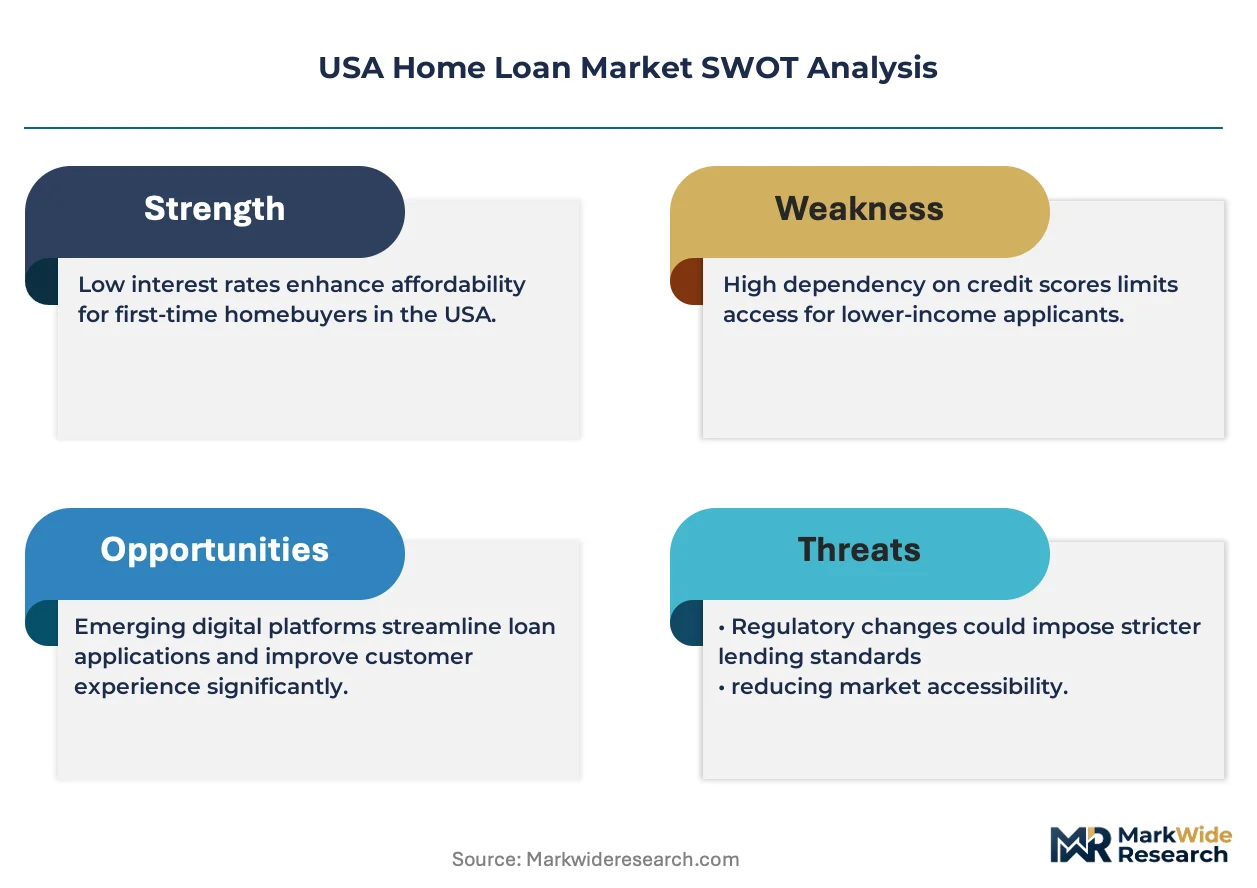
The Consumer Financial Protection Bureau enforces Truth-in-Lending disclosure protocols, while FHA, VA, and USDA programs set underwriting standards that shape product availability across borrower segments. Fannie Mae and Freddie Mac conforming limits determine pricing stratification between agency-eligible and jumbo execution. Stakeholders must monitor GSE conservatorship policy, Basel III bank capital treatment of mortgage servicing rights, and state-level foreclosure moratorium precedents that alter loss-severity assumptions.
Market Dynamics
Rate volatility and GSE policy recalibration are compressing origination margins while forcing lenders toward correspondent channels and digital fulfillment platforms. The Federal Reserve's balance-sheet runoff and Basel III capital treatment of mortgage servicing rights are restructuring bank participation economics.
Growth Catalysts
- FHA Insurance Expansion:Down-payment flexibility under Federal Housing Administration programs widens first-time homebuyer qualification pools. Sun Belt population inflows sustain purchase application volumes in supply-constrained metros.
- Digital Origination Platforms:Automated underwriting engines reduce cycle times from application to closing. Correspondent lenders leverage API integrations to scale without branch infrastructure.
- Construction-to-Permanent Financing:Builder relationships unlock lot acquisition and vertical construction funding. Regional banks redeploy capital into development-phase exposure.
Market Restraints
- Interest Rate Volatility:Treasury yield swings compress gain-on-sale margins and hedge effectiveness. Pipeline fallout rises when rate locks expire before closing.
- Regional Bank Contraction:Balance-sheet capacity in Southeast and Southwest correspondent channels remains below 2022 peaks. Depository institutions face Basel III mortgage servicing rights capital charges.
- Title Insurance Concentration:Underwriter capacity constraints in high-volume states delay closing timelines. County-level recording backlogs extend lien perfection schedules.
Strategic Opportunities
- Underserved Rural Markets:USDA guaranteed loan programs carry below-market rates and zero down-payment requirements. Community banks dominate these geographies with limited fintech penetration.
- Home Equity Access Products:HELOC and closed-end second lien demand rises with tappable equity accumulation. Credit union channels capture this segment through membership relationships.
- Climate-Resilient Underwriting:Catastrophe modeling integration into loan-level pricing differentiates Florida and Gulf Coast exposure. Private flood insurance alternatives expand beyond National Flood Insurance Program zones.
Industry Challenges
- Loan Officer Talent Compression:Commission-based compensation structures struggle to retain producers through rate-cycle troughs. Refinance-dependent originators face income volatility.
- Legacy System Integration:Point-of-sale platform upgrades require core banking system overhauls. Middleware costs escalate when LOS vendors lack open API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Home Loan Market |
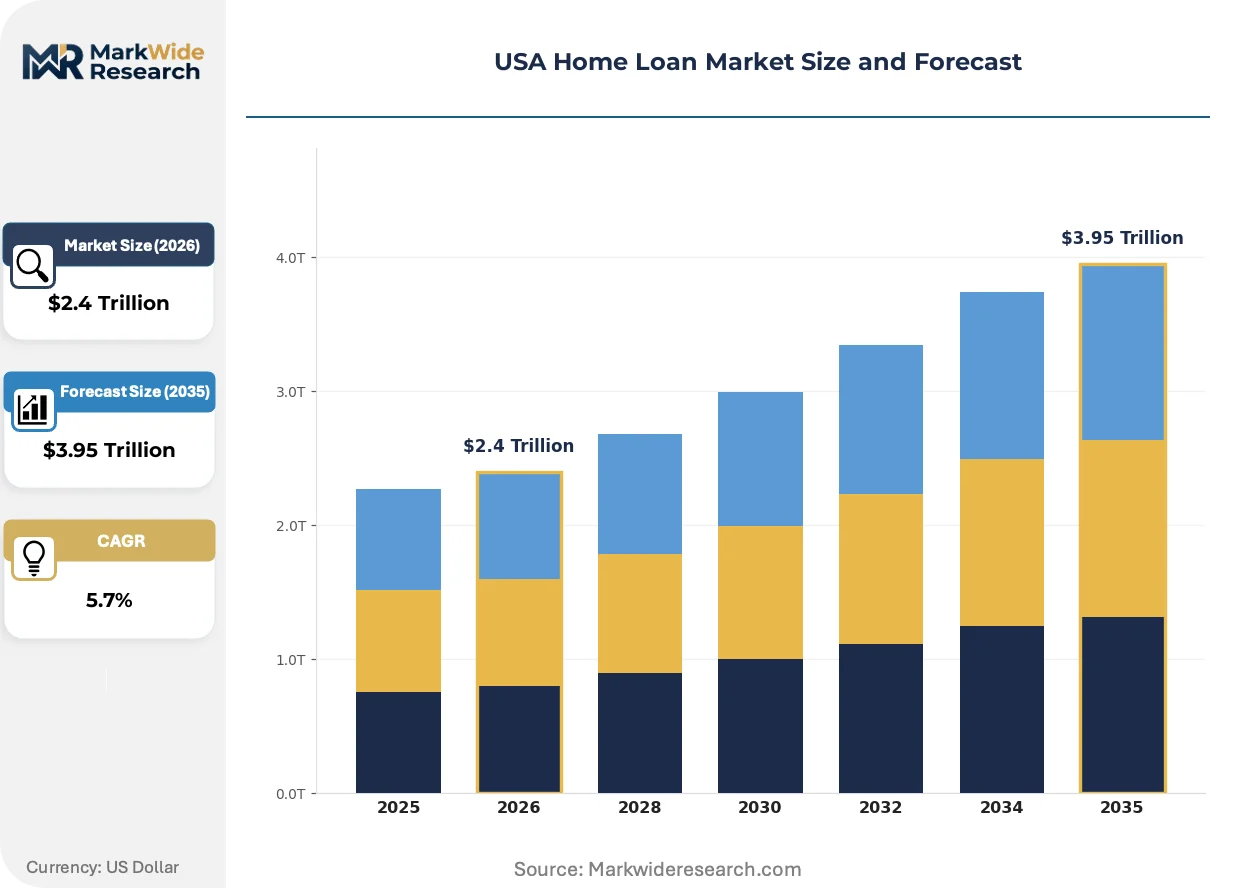
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $3.95 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed Rate, Adjustable Rate, FHA, VA Borrower Type: First-time Homebuyers, Investors, Veterans, Refinancers Loan Size: Small, Medium, Large, Jumbo Purpose: Purchase, Refinance, Home Improvement, Debt Consolidation |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, CrossCountry Mortgage, JPMorgan Chase Bank, U.S. Bank, Guaranteed Rate, DHI Mortgage Company, Fairway Independent Mortgage, LoanDepot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Home Loan Market Trends and Innovations
Automated valuation models and alternative credit scoring are compressing traditional appraisal and FICO-dependent underwriting timelines. Lenders restructure fulfillment workflows around these capabilities.
Automated valuation models leverage satellite imagery and property records to generate collateral estimates without physical inspection. Federal Housing Administration and GSEs expanded AVM acceptance for refinances and low-LTV purchases. This capability is decentralizing appraisal capacity from licensed appraiser pools toward algorithmic vendors.
The Consumer Financial Protection Bureau's updated Qualified Mortgage rule removes the 43% debt-to-income ratio cap for GSE-eligible loans. Lenders gain flexibility on non-traditional income documentation for gig-economy borrowers. First-time homebuyer segments in high-cost metros benefit most from expanded DTI capacity.
Digital closing platforms enable remote online notarization and e-note execution without physical presence. Title agents and settlement attorneys face disintermediation as counties adopt electronic recording. Texas and Florida lead state-level RON adoption, compressing closing timelines from weeks to days.
USA Home Loan Market Segmentation
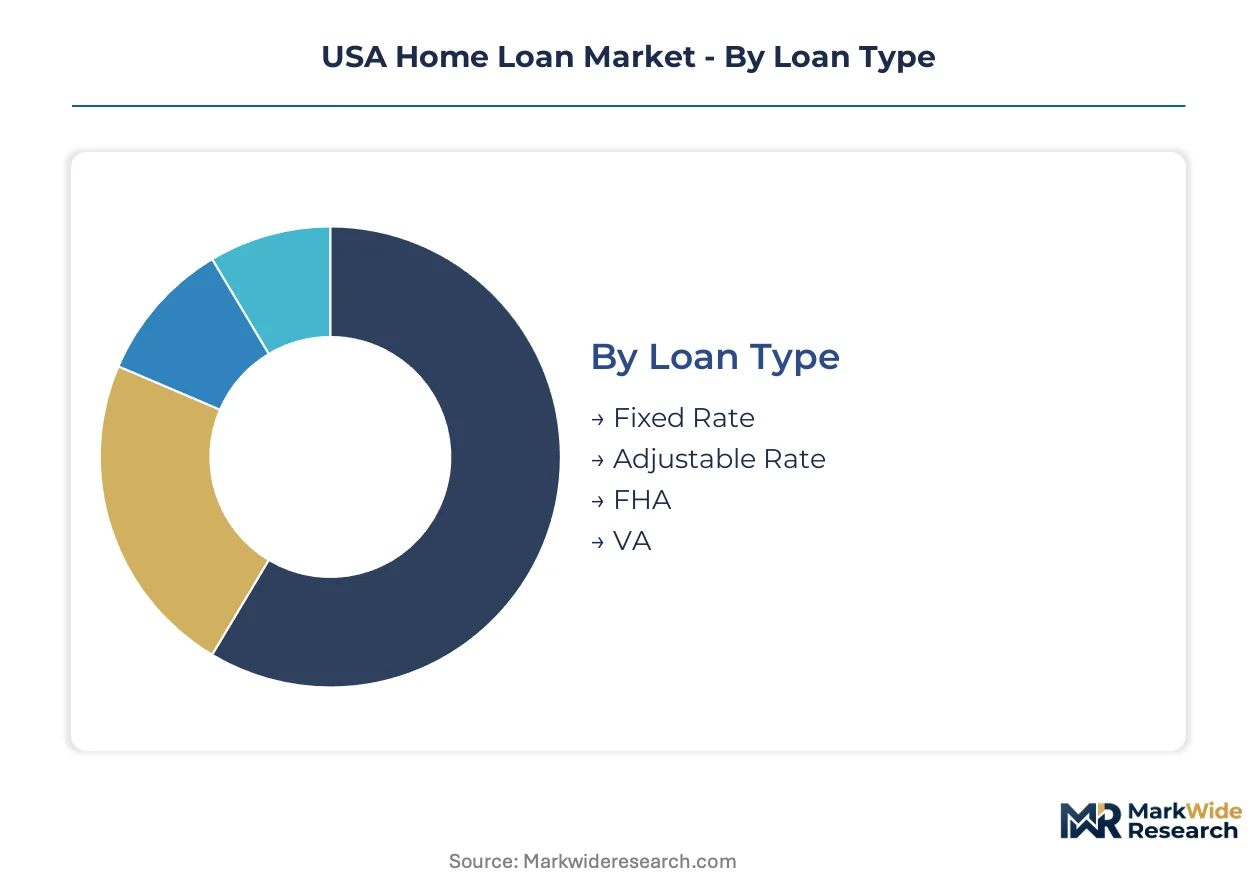
Loan segmentation determines capital allocation, pricing stratification, and servicing economics across the origination pipeline. Product categorization shapes GSE eligibility, investor appetite, and correspondent channel placement. Understanding these divisions reveals where margin compression concentrates and where technology investments yield execution advantages.
Loan Type:
Supply concentration in fixed-rate production reflects borrower preference for payment certainty and investor demand for prepayment-stable cash flows. Regional bank balance sheets and correspondent aggregators compete for this paper based on duration-matched funding costs.
- Fixed Rate:Thirty-year amortization schedules with locked coupon rates dominate agency-eligible production. Sun Belt purchase markets in Florida and Texas absorb the highest volumes where migration-driven demand sustains application pipelines. Borrowers trade off higher initial rates against elimination of reset risk.
- Adjustable Rate:Hybrid structures with fixed introductory periods before index-linked resets appeal to short-tenure borrowers and investors optimizing carry costs. Concentration in high-cost coastal metros where loan sizes amplify rate sensitivity. Margin compression here exceeds fixed-rate channels due to hedging complexity.
- FHA:Government insurance enables down payments as low as 3.5 percent, expanding first-time buyer qualification pools. Federal Housing Administration underwriting standards shape product availability across credit spectrum segments.
- VA:Zero-down financing for eligible veterans and active-duty service members carries no mortgage insurance requirement. Department of Veterans Affairs guaranty reduces lender credit risk exposure.
Today's leader: Fixed Rate. Tomorrow's challenger: FHA.
Borrower Type:
Cost tier differentiation separates rate-sensitive first-time buyers from equity-heavy investors and streamlined refinancers. Commission structures and marketing spend allocate toward segments with highest conversion velocity and lowest fallout risk.
- First-time Homebuyers:Down-payment constraints and thin credit files require manual underwriting capacity and education-intensive origination workflows. Sun Belt metros with strong employment inflows sustain the deepest applicant pools. FHA and state bond programs dominate this channel.
- Refinancers:Rate-and-term and cash-out executions spike during Treasury yield troughs, then collapse when rates rise. Digital platforms capture this segment through automated valuation and streamlined documentation. Retention economics favor servicers with existing customer relationships.
- Investors:Non-owner-occupied properties command higher rates and larger reserve requirements. Portfolio lenders and private funds dominate this segment outside agency-eligible limits.
- Veterans:VA eligibility unlocks favorable terms with limited competition from conventional products. Specialized military-focused originators maintain advantage through base proximity and cultural fluency.
First-time Homebuyers command origination investment. Refinancers drive volume volatility.
Loan Size:
Volume distribution across size tiers tracks median home prices and conforming limit geography. Jumbo production concentrates where GSE caps exclude high-value collateral from agency execution.
- Jumbo:Loan amounts exceeding conforming limits require portfolio retention or private securitization. Private banking networks and depository balance sheets dominate distribution. California and Northeast urban cores generate the highest concentrations.
- Large:Near-conforming sizes approaching agency caps capture rate-sensitive borrowers in high-cost metros. Correspondent channels compete aggressively for this paper given GSE execution certainty.
- Medium:National median price alignment produces the deepest liquidity and tightest spreads. Aggregator competition compresses gain-on-sale margins.
- Small:Rural and rust-belt geographies with limited appreciation trajectories. USDA and state housing finance agency programs sustain origination flow where private capital retreats.
Jumbo commands premium pricing. Medium delivers volume scale.
Purpose:
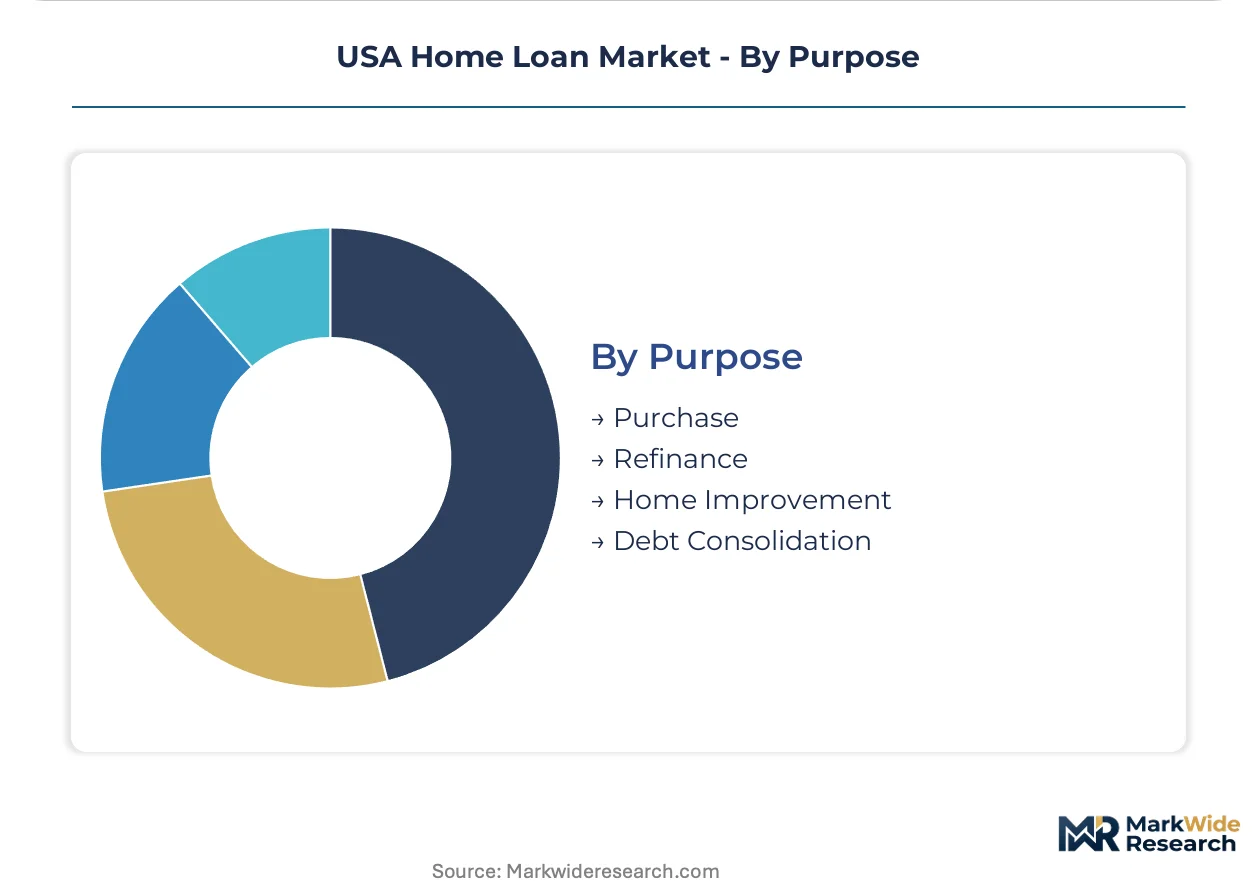
Application intent shapes timeline pressure, documentation requirements, and competitive intensity. Purchase transactions face hard closing deadlines while refinancers optimize rate timing.
- Purchase:Contract-driven deadlines require rapid underwriting turnaround and title clearance coordination. Builder-affiliated lenders and digital platforms compete on speed. Sun Belt population inflows sustain the strongest pipelines.
- Home Improvement:Second lien and cash-out first mortgage structures tap accumulated equity for renovation financing. Credit union membership relationships and contractor referral networks drive origination flow.
- Refinance:Rate-dependent demand cycles create severe volume volatility and talent retention challenges. Automated valuation models and streamlined processes reduce per-loan fulfillment cost.
- Debt Consolidation:Cash-out structures replacing higher-cost obligations require enhanced ability-to-repay documentation. Non-bank lenders with flexible underwriting capture this segment.
Purchase anchors sustainable origination capacity. Home Improvement gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Canada diverge in mortgage market structure, with American lenders navigating GSE conservatorship debates while Canadian institutions operate under stricter federal banking concentration limits. Both markets face parallel pressures from rate volatility and housing affordability constraints.
Southeast
Florida and Georgia absorb sustained population inflows from high-tax Northern states, driving purchase mortgage demand in Tampa, Orlando, and Atlanta metros. Federal Housing Administration programs expand first-time buyer access in these supply-constrained markets. Miami-Dade and Broward counties concentrate jumbo origination activity as luxury coastal properties transact above conforming limits.
Southwest
Texas and Arizona lead Sun Belt migration patterns, with Dallas-Fort Worth and Phoenix posting the nation's highest purchase application volumes. Department of Veterans Affairs guarantees support military personnel concentrations near San Antonio and El Paso installations. Austin's technology sector expansion fuels non-qualified mortgage demand among equity-compensated borrowers.
West Coast
California's median home prices exceed GSE conforming limits in most coastal counties, forcing portfolio retention or private securitization for prime jumbo production. San Francisco Bay Area lenders face Basel III mortgage servicing rights capital charges that compress bank participation economics. Los Angeles County maintains the nation's largest FHA origination pipeline among first-time buyers.
Northeast
New York and Massachusetts operate under state-level foreclosure moratorium precedents that alter loss-severity assumptions for servicers. Boston's biotech and financial services employment base sustains high-income purchase demand despite elevated property taxes. Upstate New York and rural New England depend on USDA guaranteed loan programs where private capital retreats from stagnant appreciation markets.
Midwest
Illinois and Ohio retain manufacturing-dependent employment bases with slower home price appreciation trajectories than coastal markets. Chicago's diverse economy supports conventional conforming production at national median price points. Detroit's post-bankruptcy housing recovery attracts non-bank lenders with flexible underwriting for credit-impaired borrowers.
USA Home Loan Market Competitive Landscape
Detroit-based originators anchor the wholesale tier; California and Texas specialists hold correspondent channel positions. The vendor base separates into three strata: deposit-rich universal banks, technology-enabled non-bank platforms, and builder-captive mortgage subsidiaries. Strategic archetypes include rate-agnostic servicers, digital-first acquisition engines, and construction-phase financiers. Competitive intensity concentrates on correspondent network expansion and automated underwriting speed.
Among scale-driven originators, United Wholesale Mortgage and Rocket Mortgage occupy positions at opposite ends of the wholesale-retail spectrum. CrossCountry Mortgage exemplifies the distributed retail model with loan officer networks spanning multiple states. JPMorgan Chase Bank anchors prime jumbo distribution through private banking relationships rather than mass-market channels. U.S. Bank and Guaranteed Rate represent hybrid structures balancing depository funding with correspondent aggregation capacity.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| CrossCountry Mortgage |
| JPMorgan Chase Bank |
| U.S. Bank |
| Guaranteed Rate |
| DHI Mortgage Company |
| Fairway Independent Mortgage |
| LoanDepot |
| Others |
Pricing and Supply Chain Analysis
Climate-resilient underwriting mandates from Fannie Mae and Freddie Mac now gate access to premium-tier correspondent channels, forcing originators to invest in catastrophe modeling infrastructure before qualifying for GSE-eligible execution pricing. These environmental standards simultaneously constrain warehouse lender participation and stratify gain-on-sale margins between compliant and non-compliant loan sellers.
Pricing Analysis
Capacity additions in Texas and Florida are reshaping price floors for correspondent aggregation as regional banks redeploy balance-sheet capacity into Sun Belt mortgage banking. Loan-level pricing stratifies across agency-eligible, jumbo, and non-qualified mortgage tiers based on GSE execution certainty and servicing-retention economics. Pricing pressure stems from Basel III mortgage servicing rights capital charges compressing bank participation economics. First-time homebuyer segments exhibit highest price sensitivity, while jumbo borrowers in coastal metros demonstrate lowest rate elasticity.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Atlanta anchor hub-and-spoke fulfillment patterns for title insurance and appraisal management services. Origination infrastructure concentrates in the United States, with technology vendors in California and Texas and document recording systems anchored in county-level jurisdictions nationwide. Raw material dependencies include credit data from Experian, TransUnion and Equifax, plus title plant records from First American and Fidelity National. Single-source vulnerability in automated underwriting platforms creates systemic risk. Distribution runs through correspondent lender networks, retail branch footprints, and digital direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA Home Loan Market functions as a geographic-arbitrage play where Sun Belt population inflows sustain origination velocity despite Northeast and West Coast regulatory compression and higher cost structures.
For Market Incumbents: Cement correspondent relationships in Florida and Texas through exclusive rate-lock commitments and dedicated warehouse lines. Deepen vertical integration into title insurance and appraisal management to offset third-party margin leakage. The fintech-enabled non-bank entrant archetype threatens traditional retail branch economics, making digital fulfillment platform investment the priority defensive lever. For New Entrants and Emerging Players: Digital correspondent channels offer the lowest customer-acquisition-cost pathway into mortgage banking. Target USDA guaranteed loan programs in rural Midwest and Mountain West markets where depository concentration remains thin and fintech penetration lags. Builder-captive mortgage subsidiaries in supply-constrained Sun Belt metros provide the most penetrable origination flow anchor. For Investors and Strategic Acquirers: Roll-up economics work for regional correspondent aggregators because GSE execution certainty and servicing-retained cash flows generate predictable revenue streams across rate cycles. Long-term viability centers on technology-enabled cost structures rather than commission-dependent loan officer networks. The signal to watch is Federal Reserve balance-sheet policy direction as Treasury yield trajectory determines refinance volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Correspondent Network Expansion | United Wholesale Mortgage demonstrates how wholesale aggregation scales without retail branch infrastructure investment. |
| Digital Closing Platform Integration | Remote online notarization adoption in Texas and Florida compresses closing timelines from weeks to days. |
| Construction-to-Permanent Financing Buildout | DHI Mortgage Company leverages builder relationships to capture lot acquisition and vertical construction funding. |
| Climate Risk Modeling Investment | Private flood insurance alternatives expand beyond National Flood Insurance Program zones in Florida and Gulf Coast. |
| Servicing Rights Portfolio Acquisition | Basel III capital treatment creates distressed selling from regional banks seeking balance-sheet capacity relief. |
Research Methodology
Direct dialogue with mortgage banking executives, correspondent lending officers, GSE policy specialists, title insurance underwriters, and warehouse lending directors grounded the qualitative assessment. Secondary validation drew from Home Mortgage Disclosure Act filings, Federal Housing Administration endorsement data, GSE loan-level disclosures, and Mortgage Bankers Association origination surveys. Bottom-up origination volume modeling and top-down housing stock penetration analysis were triangulated against macroeconomic scenario inputs.
Bottom-up segmentation analysis tracked loan type, borrower category, loan size tier, and purpose across the projection horizon. Top-down demand modeling incorporated household formation rates, mortgage rate sensitivity coefficients, and regional migration pattern data. CAGRs were derived from regression analysis of historical origination volumes against explanatory variables including Treasury yield spreads, home price appreciation, and regulatory policy shifts. Industry-specific forecast inputs included GSE conforming limit adjustments and FHA mortgage insurance premium trajectories.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based title recording and decentralized finance lending protocols would alter the outlook. Forecasts reflect stated assumptions regarding Federal Reserve monetary policy, GSE conservatorship resolution, and Basel III implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Embedded Lending Market
Loans and Leasing
Automotive Finance Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Montenegro Home Mortgage Finance Market