
 Flock Binder Market | 2026-2036
Flock Binder Market Size, Share, and Industry Trends Forecast 2026-2036
Flock Binder Market Analytics
Waterborne acrylic dispersion technology is reconfiguring flock binder formulation priorities as manufacturers phase out solvent-based systems to meet volatile organic compound limits. Kemiteks leverages its Turkish production base to supply acrylic binders across European textile hubs. Dow anchors its position through integrated polymer science capabilities that extend from raw ethylene to specialized flock adhesives. Arkema differentiates via high-performance polyurethane chemistry targeting automotive OEM specifications.
Flock binders are thermoplastic or thermosetting adhesive systems, typically 40-60% solids content, designed to anchor flock fibers onto substrates through electrostatic or mechanical flocking processes. The primary industrial purpose is creating velvet-like surface textures with enhanced abrasion resistance for automotive dashboards, upholstery, and decorative panels. Acrylic formulations lead volume consumption due to cost-performance balance in textile applications, while polyurethane commands premium positioning in automotive interiors where heat aging requirements exceed 120°C. Epoxy binders occupy a specialized niche in industrial coatings requiring chemical resistance, and vinyl systems sustain demand in furniture lamination where plasticizer compatibility remains critical.
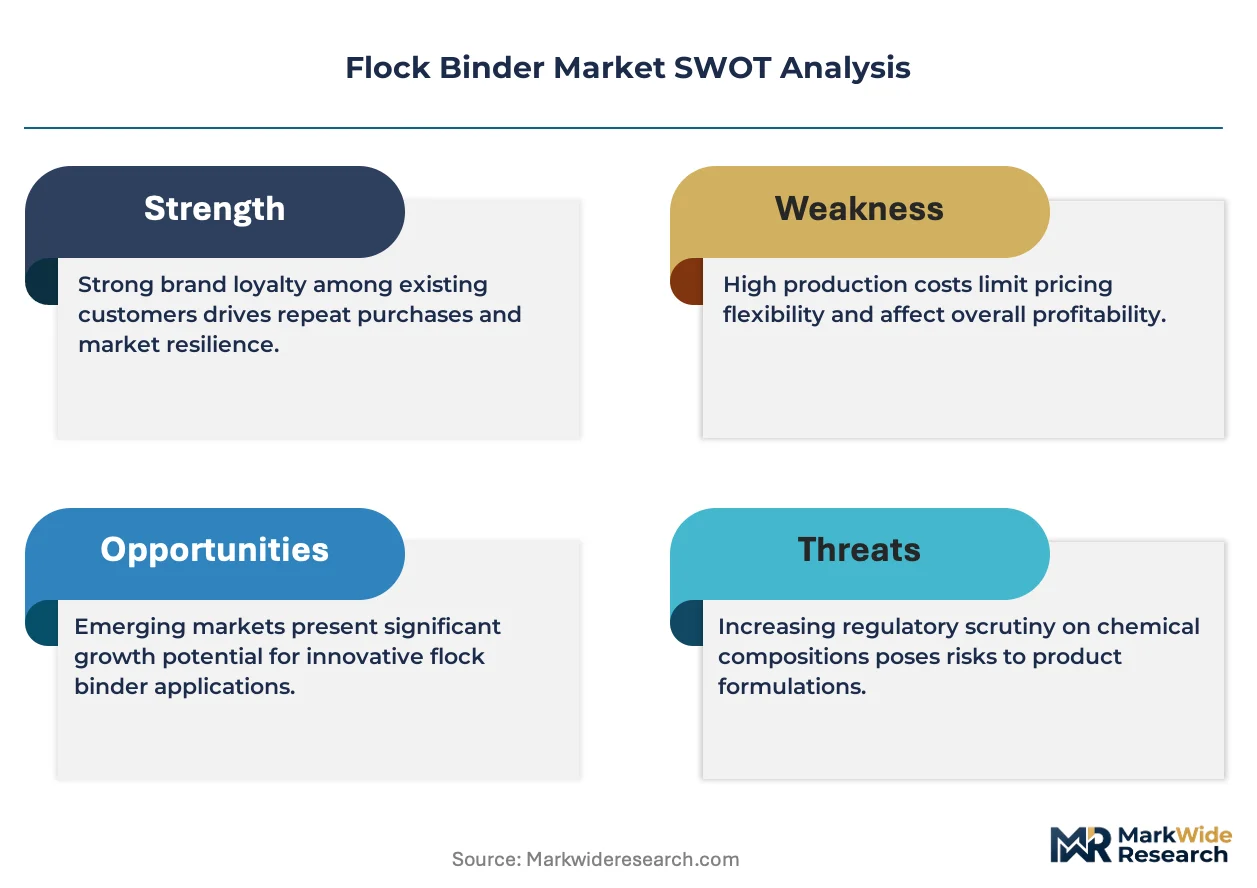
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based binder production in the United States, while REACH registration requirements in Europe enforce full chemical substance disclosure across supply chains. China's MEE oversees wastewater discharge standards affecting binder manufacturing in the Yangtze River Delta cluster. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustment mechanisms threaten to fragment compliance costs across export markets.
Market Dynamics
Waterborne acrylic dispersion technology is reconfiguring formulation priorities across the flock binder industry as manufacturers phase out solvent-based systems to meet tightening volatile organic compound limits in automotive and textile applications.
Growth Catalysts
- Automotive Interior Specifications:OEM heat aging requirements exceeding 120°C are pulling polyurethane chemistry into premium dashboard and upholstery applications.
- REACH Chemical Disclosure Mandates:Full substance registration across European supply chains is accelerating transparency investments that favor established binder suppliers with compliance infrastructure.
- Yangtze River Delta Manufacturing Cluster:Concentrated furniture and textile production in eastern China sustains volume consumption of vinyl and acrylic systems for decorative panel lamination.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and polyurethane raw material costs fluctuate with ethylene and propylene pricing, compressing margin stability for mid-tier formulators.
- Specialized Equipment Concentration:Electrostatic flocking line manufacturers cluster in Germany and northern Italy, creating supply bottleneck risk for capacity expansion in emerging markets.
- Epoxy Substitution Ceiling:Industrial coatings requiring chemical resistance face technical limitations where epoxy binders cannot match polyurethane flexibility in thermally stressed applications.
Strategic Opportunities
- India Furniture Manufacturing Expansion:Domestic upholstery production growth under the PLI scheme creates unserved demand for cost-optimized acrylic flock systems.
- Carbon Border Adjustment Mechanism Preparation:EU importers are qualifying low-carbon footprint binder sources ahead of 2026 phased implementation, rewarding early supply chain reconfiguration.
- Bio-Based Polyol Convergence:Renewable feedstock polyurethane chemistry is intersecting with automotive OEM sustainability scorecards to open premium positioning for certified formulations.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Industrial adhesive R&D talent pools concentrate at Dow, Arkema, and legacy European specialists, constraining independent innovation capacity.
- Multi-Jurisdiction Certification Timelines:EPA NESHAP pre-manufacture notification parallel with REACH registration extends product launch cycles by 18-24 months for new chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flock Binder Market |
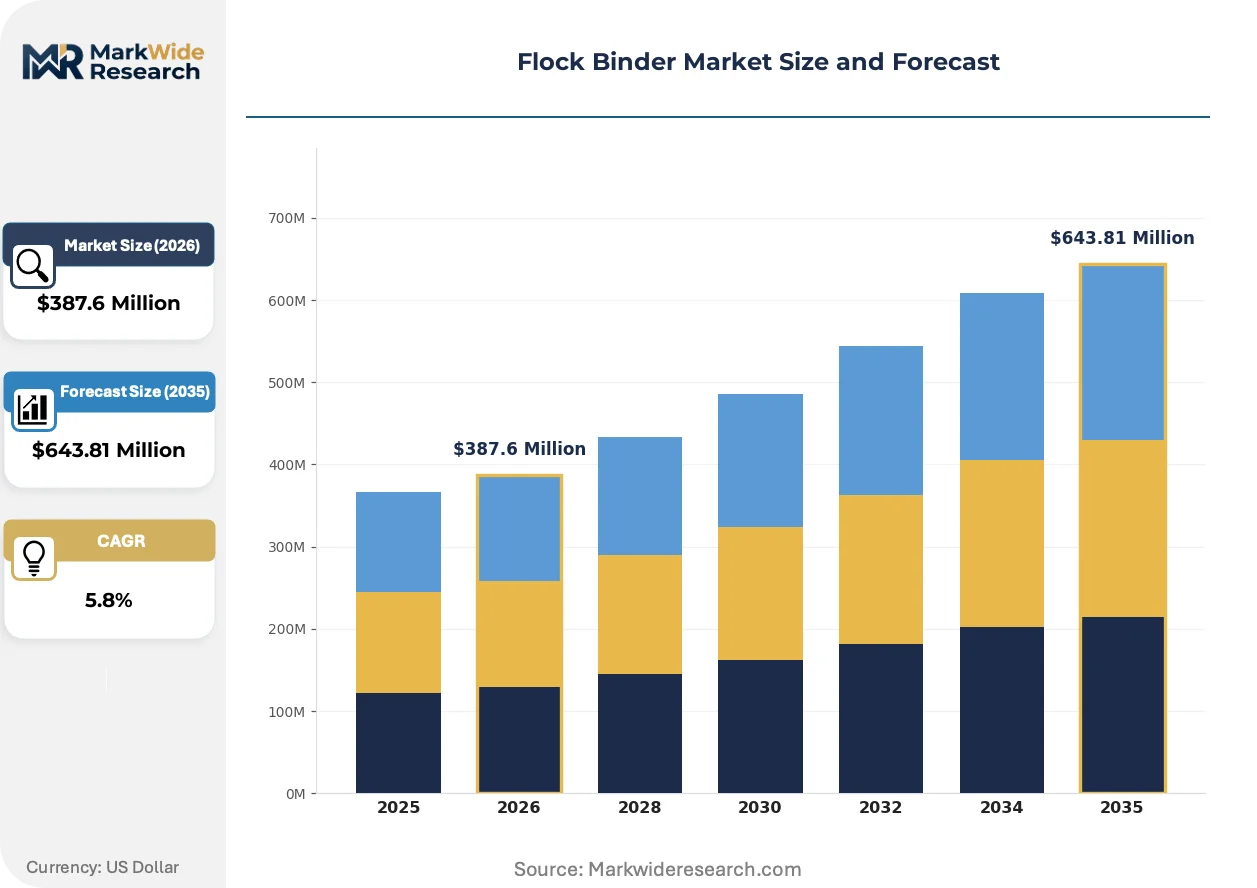
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Vinyl Application: Textiles, Automotive, Furniture, Industrial End User: Manufacturers, Retailers, Distributors, Exporters Distribution Channel: Online, Direct Sales, Wholesalers, Others |
| Companies Covered | Kemiteks, Sidh Organics Private Limited, Darshan Tex-Chem, Indofil Industries Limited, Primus Chemical Co., Ltd, ALV Kimya, ADPL Polychem, Arkema, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flock Binder Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement sophistication are advancing in parallel across the flock binder value chain, compressing competitive differentiation cycles for adhesive suppliers.
Waterborne acrylic dispersion systems are migrating from textile decorative applications into automotive interior specifications as Tier 1 suppliers seek single-platform compliance with EPA volatile organic compound ceilings. Ford and Stellantis procurement teams are qualifying these systems for dashboard skin lamination at accelerated validation timelines. The technology is migrating from cost-driven textile markets into performance-driven automotive segments, collapsing the historical segmentation between industrial and transportation adhesive grades.
REACH authorization requirements for Substances of Very High Concern are forcing reformulation of legacy plasticizer systems in vinyl flock binders used across European furniture manufacturing. ECHA's 2024 update to the Candidate List added several phthalate alternatives, triggering supply chain audits among German upholstery producers. Vinyl system suppliers serving IKEA and European retail chains are accelerating non-phthalate plasticizer transitions ahead of sunset date uncertainties.
Automotive OEMs are consolidating approved supplier lists for interior materials, compressing the viable vendor base for flock binder procurement from fragmented regional chemical distributors toward direct relationships with integrated polymer producers. Tier 2 laminators in the United States are losing specification authority as Ford, General Motors, and Tesla centralize material qualification at the corporate engineering level. This concentration is most visible in Michigan and southern German automotive supplier corridors where engineering approval gates have tightened since 2023.
Flock Binder Market Segmentation
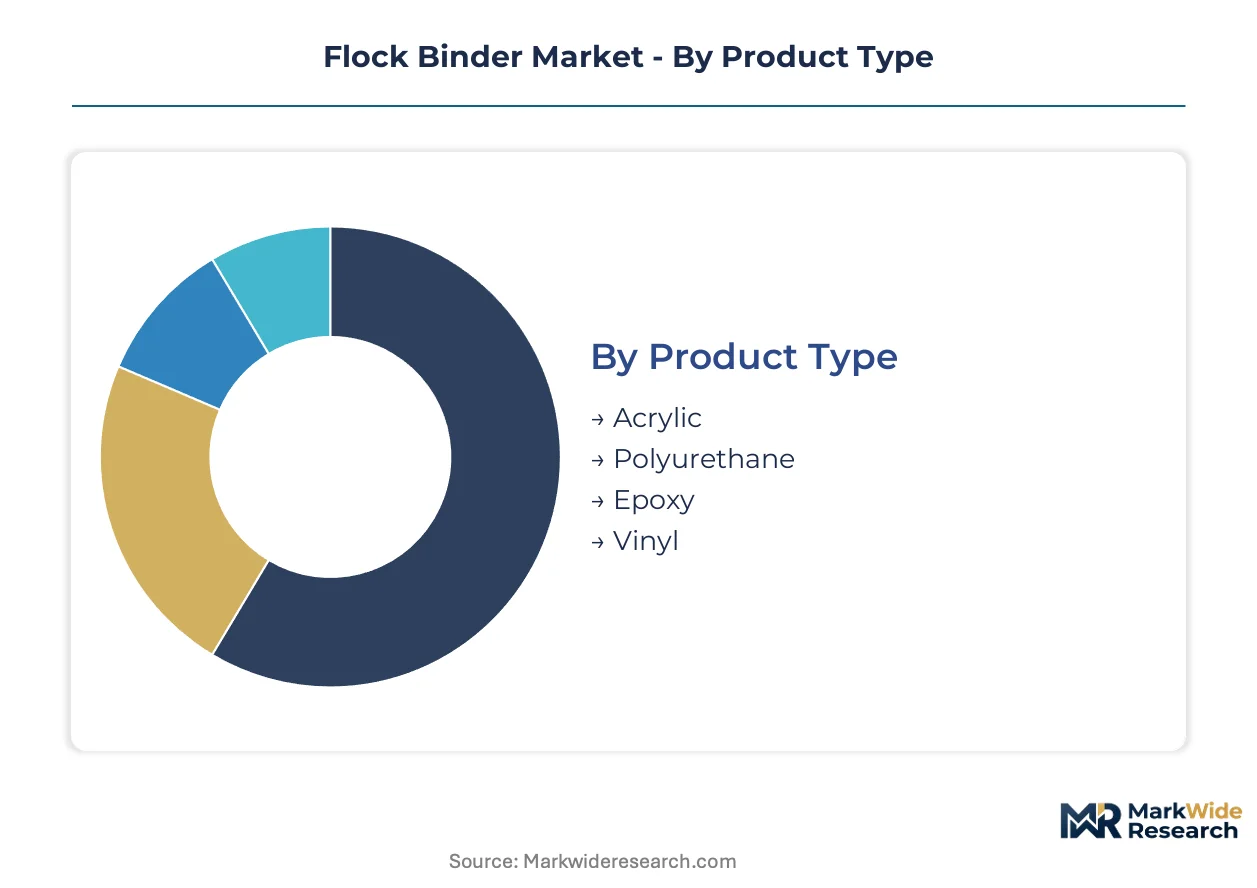
Flock binder procurement patterns diverge sharply across product chemistries and end-use specifications, requiring suppliers to maintain distinct technical service capabilities for each segment. Understanding these structural divisions reveals where formulation investments and regulatory compliance resources generate the strongest returns.
Product Type:
After-sales service intensity varies dramatically across binder chemistries, with polyurethane systems demanding dedicated technical support for automotive qualification while acrylic volumes flow through standardized distribution.
- Acrylic:Waterborne dispersions dominate textile and furniture applications through cost-performance balance at 40-60% solids content. Demand concentrates in China's Yangtze River Delta furniture clusters where manufacturers prioritize rapid line speeds over thermal resistance.
- Polyurethane:Two-component systems command premium positioning in automotive interiors where OEM heat aging specifications exceed 120°C on dashboard and upholstery substrates. German and US automotive supplier corridors drive specification authority for these high-performance grades.
- Epoxy:Specialized industrial coatings requiring chemical resistance anchor this niche, with limited penetration beyond heavy-duty protective applications.
- Vinyl:Plasticizer-compatible systems sustain furniture lamination demand, though REACH authorization pressures on phthalate alternatives are forcing accelerated reformulation cycles.
Acrylic holds the largest share; momentum sits with polyurethane as automotive OEMs consolidate approved supplier lists.
Application:
Cost tier stratification separates commodity textile coatings from premium automotive specifications, with margin structures reflecting divergent technical barriers and qualification timelines.
- Textiles:Decorative flocking on apparel and home furnishings drives volume consumption of waterborne acrylic systems. Turkish and Italian textile hubs maintain dense supplier networks for these cost-sensitive applications.
- Automotive:Dashboard skins, door panels, and seating surfaces require polyurethane binders meeting OEM durability protocols. Ford, Stellantis, and Tesla procurement teams have centralized material qualification since 2023, compressing the viable vendor base.
- Furniture:Upholstery and decorative panel lamination splits between vinyl systems for plasticizer compatibility and acrylics for cost optimization. India's PLI scheme is expanding domestic production capacity in this segment.
- Industrial:Protective coatings and specialized substrates occupy a narrow niche where epoxy chemistry provides chemical resistance unmatched by flexible alternatives.
Automotive commands the steepest expansion trajectory as interior material specifications tighten across German and US supplier corridors.
End User:
Customer type determines procurement sophistication, with integrated manufacturers driving specification authority while distributors handle fragmented regional demand.
- Manufacturers:Tier 1 automotive laminators and large furniture producers negotiate direct contracts with Dow, Arkema, and integrated polymer suppliers, bypassing traditional chemical distribution.
- Retailers:European furniture chains including IKEA audit supply chains for REACH compliance, accelerating non-phthalate plasticizer transitions among vinyl binder suppliers.
- Distributors:Regional chemical distributors retain relevance in textile markets and emerging economies where order fragmentation prevents direct supplier relationships.
- Exporters:Cross-border traders face escalating carbon border adjustment mechanism preparation requirements, favoring suppliers with documented low-carbon footprint credentials.
Manufacturers hold the largest share; momentum sits with exporters as EU importers reconfigure supply chains ahead of phased mechanism implementation.
Distribution Channel:
Supply concentration patterns favor direct relationships for high-volume automotive accounts while online platforms capture specification research and small-order fulfillment.
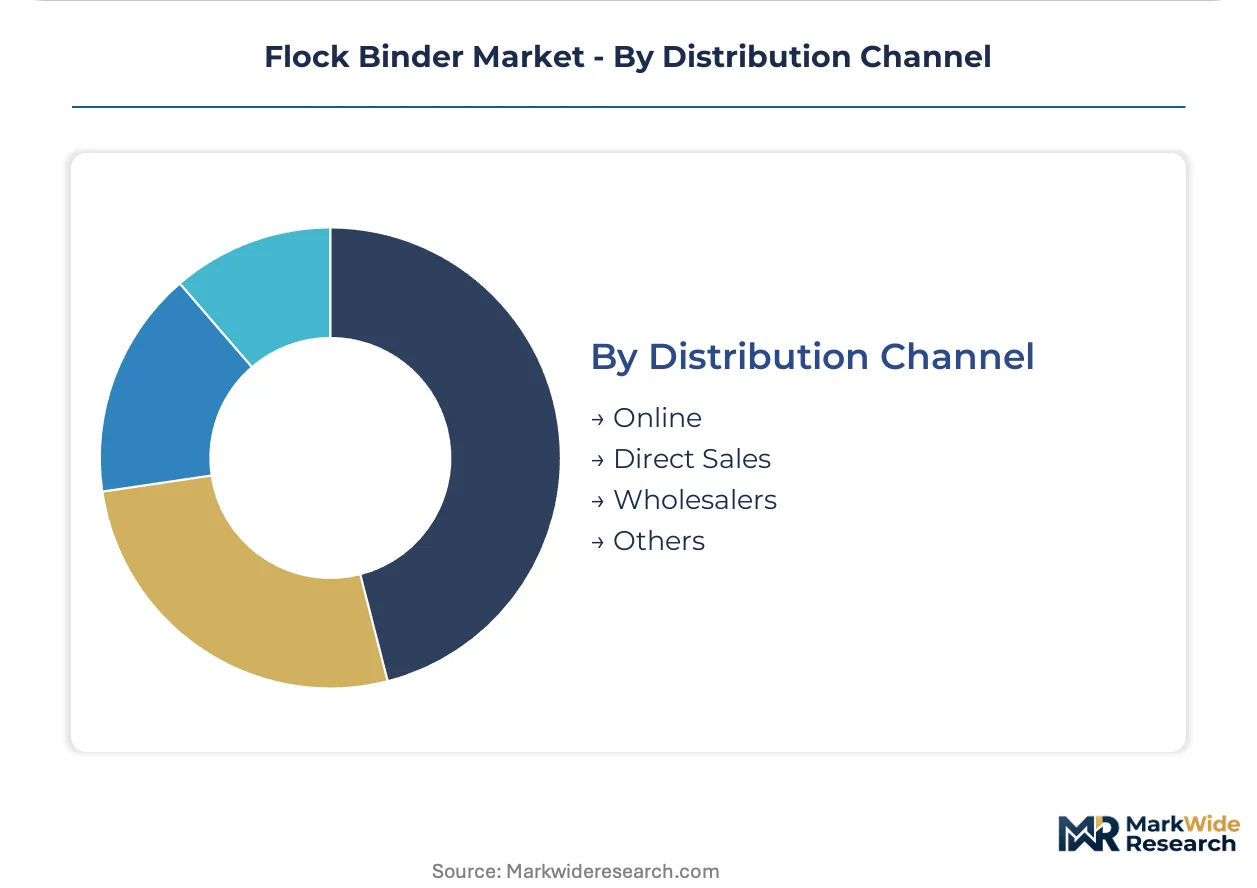
- Online:Digital procurement platforms serve research and sample ordering functions, particularly for independent textile converters evaluating new formulations.
- Direct Sales:Integrated polymer producers maintain dedicated account teams for automotive OEM and Tier 1 laminator relationships, with engineering approval gates tightening in Michigan and southern Germany.
- Wholesalers:Regional chemical distributors sustain furniture and textile market coverage where order fragmentation and technical service requirements are modest.
- Others:Agent-based representation persists in emerging markets where local regulatory navigation and relationship infrastructure remain critical.
Direct sales holds the largest share; momentum sits with online channels as specification research migrates to digital platforms ahead of procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and furniture manufacturers concentrate procurement authority in Germany, China, and the United States, where dense supplier corridors and regulatory enforcement create divergent compliance burdens for adhesive formulators.
Germany
Automotive dashboard and upholstery specifications from BMW and Mercedes-Benz pull polyurethane binders through Tier 1 laminators in Baden-Württemberg. ECHA's REACH authorization requirements for Substances of Very High Concern force reformulation of legacy vinyl systems. The Stuttgart supplier corridor maintains engineering approval gates that compress the viable vendor base for flock binder procurement.
China
Furniture manufacturing clusters in the Yangtze River Delta sustain volume consumption of waterborne acrylic and vinyl systems for decorative panel lamination. MEE wastewater discharge standards constrain binder production capacity in Jiangsu and Zhejiang provinces. Suzhou and Hangzhou maintain dense networks of textile converters sourcing cost-optimized flock adhesives for export markets.
United States
Ford, General Motors, and Tesla procurement teams centralize material qualification for interior applications, consolidating approved supplier lists. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based binder production capacity. Michigan and Ohio automotive supplier corridors drive specification authority for heat-resistant polyurethane grades.
India
Domestic upholstery production expansion under the PLI scheme creates unserved demand for cost-optimized acrylic flock systems. BIS certification requirements for imported chemical formulations extend qualification timelines for foreign suppliers. Gujarat and Maharashtra furniture manufacturing clusters are scaling flocking line capacity to serve retail chain procurement.
Turkey
Textile hub demand for decorative flocking applications anchors acrylic binder consumption across Istanbul and Bursa manufacturing zones. The country's national chemical regulator enforces substance registration parallel to REACH alignment efforts for EU export access. Kemiteks leverages its domestic production base to supply European textile converters with waterborne dispersion systems.
Flock Binder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated polymer producers anchor premium automotive specifications through direct OEM relationships, while regional formulators capture fragmented textile and furniture demand. Three archetypes dominate: petrochemical-integrated multinationals with captive raw material supply, mid-scale regional specialists with formulation flexibility, and commodity distributors serving price-sensitive decorative applications. Competitive moves concentrate on backward integration into acrylic monomer production and geographic expansion into India's PLI-supported furniture clusters.
Among integrated polymer producers, Dow and Arkema occupy positions exemplifying petrochemical-backward competitive architecture. Kemiteks anchors the regional specialist archetype from its Turkish production base. Sidh Organics Private Limited and Darshan Tex-Chem represent mid-scale formulators serving South Asian textile markets. ALV Kimya and ADPL Polychem sit within the specialty chemical distributor tier. Indofil Industries Limited exemplifies diversified chemical manufacturers with adhesive portfolio extensions. Primus Chemical Co., Ltd. occupies a position among East Asian formulators supplying furniture lamination markets.
| Leading Market Players |
|---|
| Kemiteks |
| Sidh Organics Private Limited |
| Darshan Tex-Chem |
| Indofil Industries Limited |
| Primus Chemical Co., Ltd |
| ALV Kimya |
| ADPL Polychem |
| Arkema |
| Dow |
| Others |
Value Network & Pricing Analysis
Ethylene and propylene feedstock concentration in Gulf Coast petrochemical complexes anchors margin capture at the monomer production tier, while downstream flock binder formulators absorb volatility through contract indexation clauses.
Pricing Analysis
Cost-plus contracts indexed to ICIS propylene and ethylene benchmarks dominate procurement between integrated polymer producers and automotive Tier 1 laminators. Three-tier pricing structure across automotive OEM-specified, industrial grade, and textile economy levels separates qualification-intensive polyurethane systems from commodity acrylic dispersions. Pricing pressure stems from MEE wastewater compliance investments in China's Yangtze River Delta, compressing margins for vinyl and acrylic formulators serving furniture export markets. Textile converters in Turkey and Italy exhibit highest price sensitivity, while German automotive supplier corridors accept premium positioning for heat-aging certified grades.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements between German automotive OEMs and their approved binder vendors, straining working capital for mid-tier formulators. Raw material sourcing draws from Saudi ethylene crackers, US Gulf Coast propylene derivatives, and South Korean polyol production. Acrylic monomer and isocyanate dependencies create single-source vulnerability when force majeure events disrupt Asian petrochemical complexes. Distribution runs through direct account teams for automotive specifications and regional chemical wholesalers for fragmented textile demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic polyurethane hot-melt adhesives present a credible substitution threat to conventional flock binders in automotive interior lamination, forcing incumbents to defend specification authority through performance differentiation.
For Market Incumbents: Insulate automotive qualification pipelines by deepening captive acrylic monomer production and accelerating REACH-registered bio-based polyol certification ahead of carbon border adjustment mechanism implementation. Secure direct engineering relationships with Ford, Stellantis, and Tesla procurement teams to lock out reformulated adhesive substitutes before validation cycles complete.
For New Entrants and Emerging Players: Build out technical service capabilities targeting India's PLI-supported furniture clusters in Gujarat and Maharashtra, where domestic flocking line expansion outpaces qualified local binder supply. Qualify cost-optimized waterborne acrylic systems through BIS certification pathways to capture unserved demand from regional upholstery producers supplying retail chains.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators in Turkey and Southeast Asia lacking REACH compliance infrastructure but holding established textile customer relationships. Five-to-ten-year viability hinges on successful reformulation investments and geographic expansion execution. Monitor ECHA Candidate List updates for phthalate alternative restrictions as inflection signals requiring portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer | Dow and Arkema secure margin capture from ethylene feedstock through captive monomer supply. |
| REACH-Compliant Bio-Based Polyol Certification | Automotive OEM sustainability scorecards reward certified polyurethane formulations with preferred supplier status. |
| India PLI Cluster Technical Service Expansion | Kemiteks and regional specialists establish local formulation support to capture furniture manufacturing growth. |
| Carbon Border Adjustment Mechanism Supply Reconfiguration | EU importers qualify low-carbon footprint sources ahead of phased implementation. |
| Non-Phthalate Plasticizer Reformulation | Vinyl binder suppliers serving IKEA accelerate transitions ahead of ECHA sunset date uncertainties. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive R&D directors, automotive Tier 1 procurement managers, textile plant engineers, and regional chemical distributors and refined through secondary validation against customs trade data, ECHA registration databases, SEC chemical company filings, and ACC industry reports. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Germany, China, and the United States.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation across acrylic, polyurethane, epoxy, and vinyl chemistries; automotive, textile, furniture, and industrial applications; and manufacturer, retailer, distributor, and exporter end-user types. CAGRs derived from elasticity-adjusted growth coefficients incorporating automotive production forecasts and furniture manufacturing expansion indices.
Practitioners should monitor feedstock price volatility, REACH authorization timeline shifts, and automotive OEM qualification centralization for early signals requiring forecast reassessment. Macroeconomic contraction in European automotive production, regulatory acceleration of phthalate restrictions, or breakthrough thermoplastic adhesive adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
India Construction Chemicals Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market